
 Dental Chair Market | 2026-2036
Dental Chair Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Chair Market Analysis
The capital-intensity divergence between integrated manufacturers and assembly-dependent competitors is reorganizing competitive tiers in the dental chair industry. A-dec leverages captive production of hydraulic lift mechanisms to sustain margin control across North American dental clinics. Planmeca anchors its position through in-house development of programmable chair positioning software. J. Morita competes by dominating electromechanical actuator supply chains serving Asian markets.
A dental chair constitutes an electromechanically actuated patient support platform, typically integrating a base frame, hydraulic or electric elevation system, articulating backrest, and detachable spittoon basin, designed to position patients for oral examination and surgical procedures. Electric variants now incorporate brushless DC motors achieving positional accuracy within 0.5 millimeters and load capacities exceeding 200 kilograms. The product type dimension shows electric chairs capturing premium procurement while portable units address rural outreach programs. End-user segmentation reveals dental clinics as the dominant installation base, with hospitals representing the fastest-growing channel due to expanded oral surgery departments.
The FDA's medical device quality system regulation mandates design controls for programmable chair electronics, while ISO 13485 certification requirements shape supplier qualification protocols for European market access. Japan's PMDA enforces electromagnetic compatibility standards that filter out non-compliant actuator imports. Stakeholders must monitor evolving cybersecurity requirements for networked chair control systems as dental practices integrate practice management software.
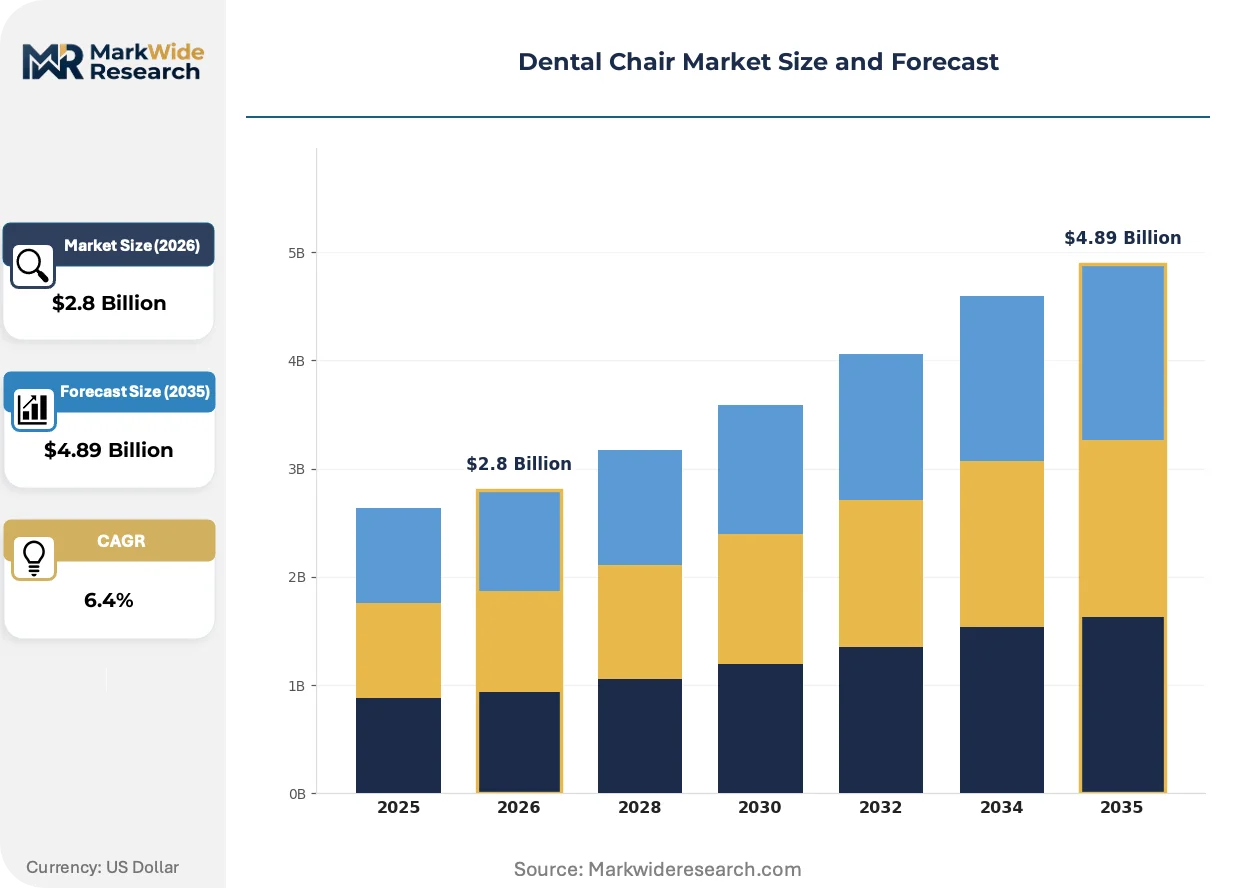
Market Dynamics
Electromechanical actuator precision is compressing replacement cycles for hydraulic dental chairs while forcing suppliers to recertify under tightened electromagnetic compatibility standards.
Growth Catalysts
- Brushless DC motor adoption:Positional accuracy within 0.5 millimeters enables complex oral surgical procedures previously requiring specialized equipment. Dental clinics in Germany and Japan are prioritizing these specifications.
- FDA quality system regulation:Design control mandates for programmable chair electronics are filtering out non-compliant manufacturers and consolidating procurement toward certified suppliers.
- Rural outreach programs:Portable chair demand from mobile dental units in underserved regions creates secondary market volume independent of clinic infrastructure investment.
Market Restraints
- Electromechanical actuator supply concentration:Asian component suppliers dominate precision actuator manufacturing, creating vulnerability for assembly-dependent chair producers in North America and Europe.
- ISO 13485 certification timeline:European market access requires 12-18 month supplier qualification protocols that delay new entrant commercialization.
- Practice management software integration costs:Networked chair control systems require cybersecurity compliance expenditure that inflates total cost of ownership for independent dental practices.
Strategic Opportunities
- Hospital oral surgery expansion:Fastest-growing installation channel as surgical departments upgrade patient positioning platforms for multidisciplinary procedures.
- LED-integrated instrument tray convergence:Combining illumination systems with chair-mounted delivery units commands premium pricing and reduces operatory footprint.
- PMDA electromagnetic compatibility pathways:Japan's streamlined certification for compliant actuators creates first-mover advantage for suppliers meeting JIS standards ahead of competitors.
Industry Challenges
- Field service technician scarcity:Hydraulic-to-electric transition requires retraining maintenance networks on brushless motor diagnostics and software calibration protocols.
- Legacy chair retrofit complexity:Existing clinic infrastructure limits upgrade paths when base frames lack compatibility with modern elevation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Chair Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Hydraulic, Portable, Manual End User: Dental Clinics, Hospitals, Dental Schools, Home Care Material: Leather, Fabric, Plastic, Metal Feature: Adjustable Headrest, Lumbar Support, Built-in LED Light, Instrument Tray |
| Companies Covered | Takara Belmont, Midmark, A-dec, Anthos, J. Morita, Dentsply Sirona, KaVo, Stern Weber, Planmeca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Chair Market Emerging Trajectories
Digital positioning protocols are redefining chair functionality expectations while regulatory pressure on networked medical devices accelerates cybersecurity integration requirements.
Brushless DC motor arrays with closed-loop feedback are displacing hydraulic lift mechanisms in premium procurement segments. Dental clinics with expanded surgical service lines are specifying electric variants for load capacities exceeding 200 kilograms. This displacement is compressing the addressable market for fluid power specialists while elevating electromechanical component suppliers to tier-one vendor status.
Japan's PMDA electromagnetic compatibility standards are filtering non-compliant actuator imports from regional supply chains. Manufacturers serving Asian markets must redesign control shielding and grounding architectures to maintain market access. European suppliers with pre-certified IEC 60601-1-2 compliance are capturing redirected procurement from exporters facing PMDA rejection.
Service contract unbundling is separating preventive maintenance from capital equipment procurement in North American dental group practices. Multi-location operators are centralizing technical service agreements with independent field engineering networks rather than manufacturer-authorized technicians. This channel shift is most visible in United States metropolitan clusters where dental service organizations control 15-plus chair installations.
Dental Chair Market Segmentation
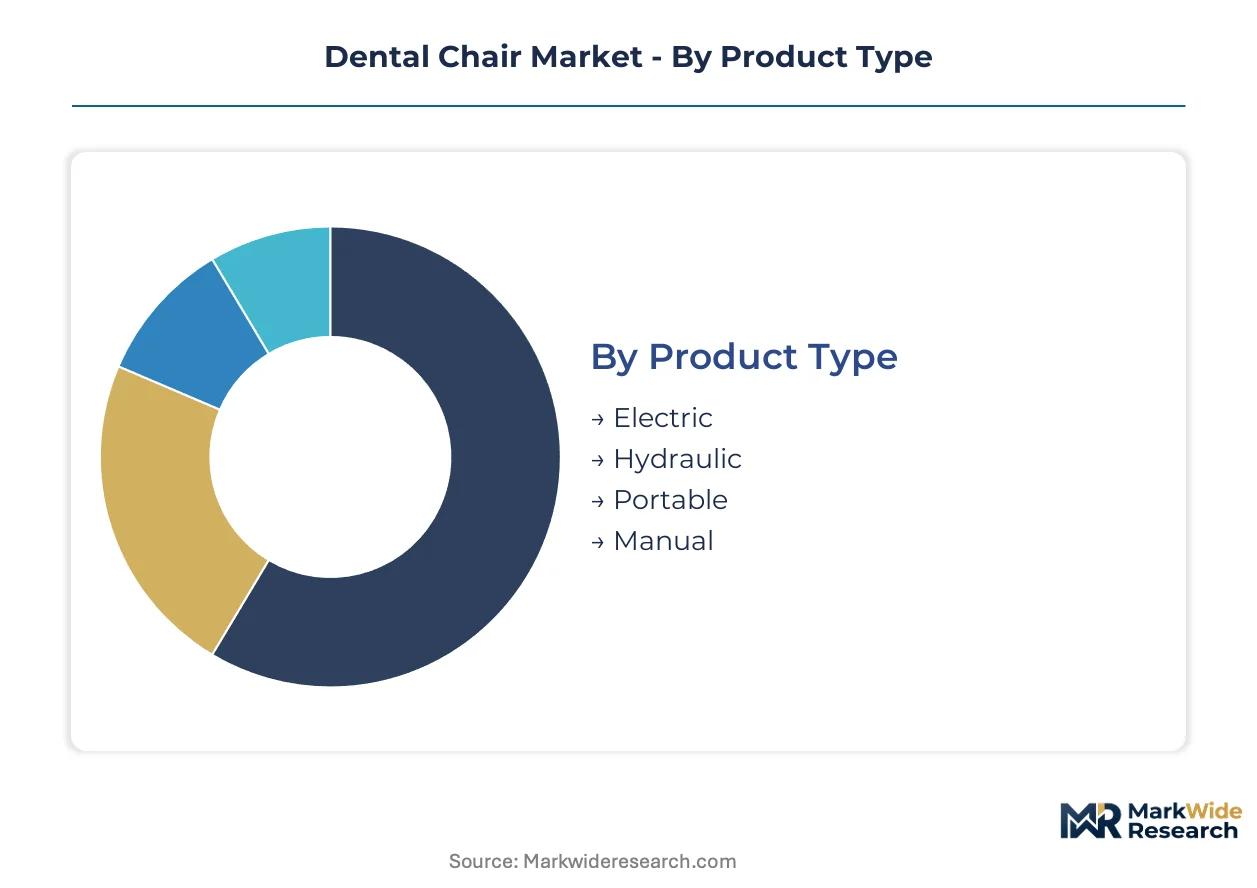
Dental chair procurement patterns diverge sharply between capital-intensive clinic infrastructure and mobile outreach deployments. Electric variants with integrated positioning software command premium budgets while portable units address access gaps in underserved geographies.
Product Type:
Electric chairs face intensifying substitution pressure from hydraulic alternatives in budget-constrained markets, though precision motor arrays are displacing fluid power in surgical-grade installations.
- Electric:Brushless DC motor arrays with closed-loop feedback achieve positional accuracy within 0.5 millimeters and load capacities exceeding 200 kilograms. German and Japanese dental clinics prioritize these specifications for expanded oral surgery service lines.
- Hydraulic:Fluid power elevation systems retain cost advantages in emerging markets and legacy clinic retrofits where electrical infrastructure upgrades prove prohibitive. Replacement cycles are compressing as electromechanical precision standards tighten.
- Portable:Lightweight collapsible frames serve mobile dental units in rural outreach programs across India and Brazil.
- Manual:Mechanical crank mechanisms persist in veterinary dentistry and extreme low-budget humanitarian deployments.
Electric chairs anchor the volume base in premium procurement while portable units gain share at the steepest rate among non-clinic channels.
End User:
Cost tier stratification separates institutional buyers with centralized technical service from independent operators managing total cost of ownership directly.
- Dental Clinics:Independent and group practices constitute the dominant installation base, with multi-location operators in United States metropolitan clusters unbundling service contracts from capital procurement. FDA design control mandates for programmable electronics filter supplier qualification toward certified manufacturers.
- Hospitals:Oral surgery departments drive fastest-expanding demand as multidisciplinary procedures require patient positioning platforms with surgical-grade load tolerance. Integration with hospital information systems demands cybersecurity compliance expenditure.
- Dental Schools:Training institutions specify durable entry-level configurations with standardized control interfaces for curriculum consistency.
- Home Care:Compact electric variants serve mobility-impaired patients requiring domiciliary oral health services in aging populations.
Dental clinics retain the largest installed base while hospitals demonstrate the steepest expansion trajectory among end-user channels.
Material:
Supply concentration in Asian textile and polymer manufacturing shapes regional cost structures for upholstery and structural components.
- Leather:Premium natural and synthetic hides dominate high-end clinic aesthetics in Germany and Japan, with antimicrobial treatment specifications tightening under ISO 13485 supplier protocols.
- Fabric:Breathable woven textiles address infection control requirements in high-throughput hospital settings where rapid turnover demands moisture-resistant surfaces.
- Plastic:Molded polymer shells reduce unit weight for portable chair configurations.
- Metal:Stainless steel and aluminum alloys provide structural frames across all product tiers, with electropolished finishes mandated for surgical environments.
Leather upholstery commands premium positioning while fabric alternatives expand most quickly in institutional procurement.
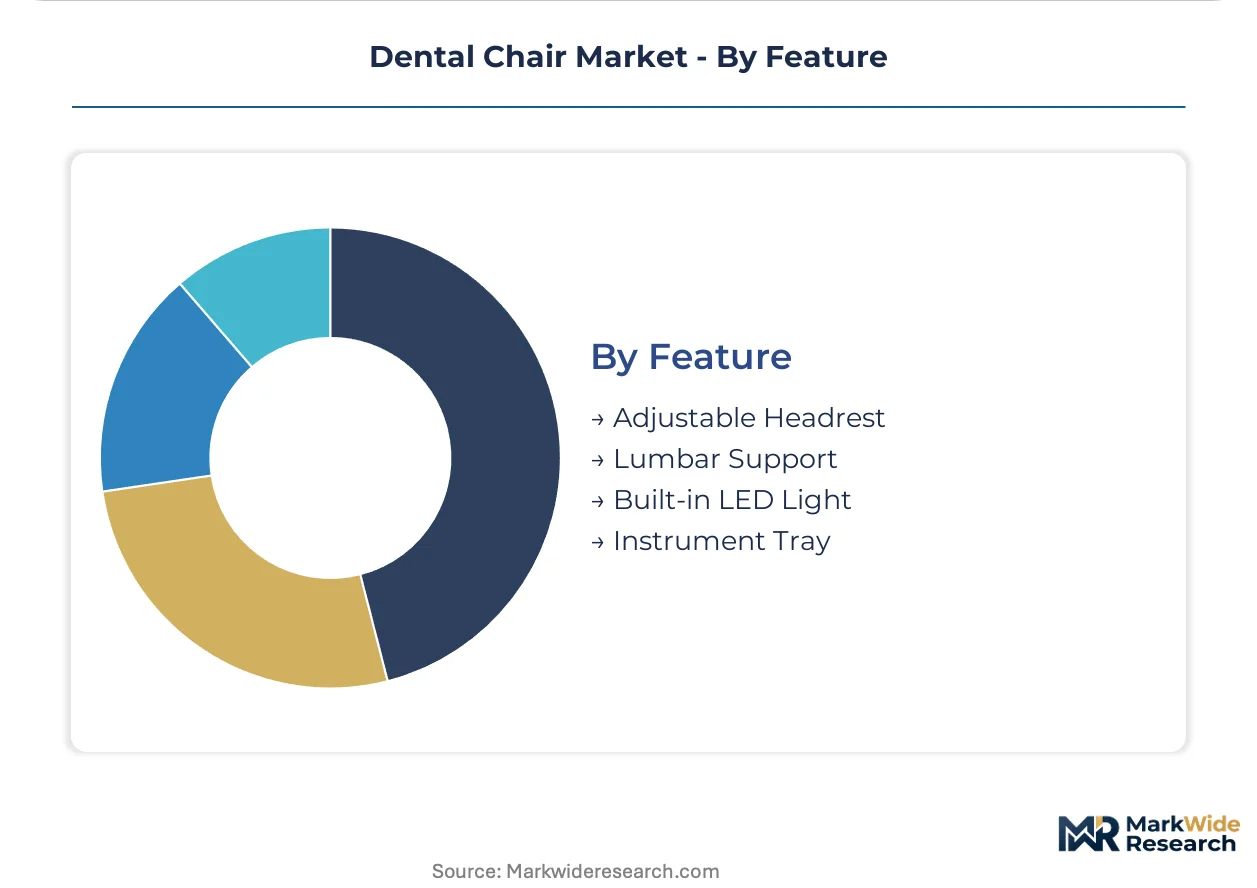
Feature:
Technology convergence is collapsing discrete component categories into integrated delivery systems that reduce operatory footprint.
- Adjustable Headrest:Articulating cervical support mechanisms with magnetic quick-release enable rapid patient repositioning during complex procedures. Precision actuator control allows programmable memory positions for recurring treatment protocols.
- Built-in LED Light:Integrated illumination systems with color temperature adjustment are merging with chair-mounted delivery units, commanding price premiums while eliminating ceiling-mounted dental lights. Japanese PMDA electromagnetic compatibility standards filter non-compliant imports.
- Lumbar Support:Contoured backrest padding reduces practitioner strain during extended procedures.
- Instrument Tray:Detachable and swing-arm configurations organize handpiece delivery for workflow efficiency.
Adjustable headrests anchor standard configuration requirements while built-in LED lighting gains share fastest through convergence with delivery system integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German dental clinics command premium pricing for electromechanical precision systems while Indian procurement gravitates toward cost-optimized hydraulic configurations, creating a structural pricing-power asymmetry between Western European and South Asian markets.
United States
Dental service organizations in metropolitan clusters drive consolidated procurement of fully electric chairs with integrated LED systems. FDA quality system regulations for programmable medical devices filter supplier qualification toward certified manufacturers. Greater Boston and Pacific Northwest dental groups anchor multi-location standardization programs.
Germany
Precision manufacturing heritage shapes demand for brushless DC motor arrays achieving sub-millimeter positional accuracy. ISO 13485 certification requirements enforce rigorous supplier protocols for European market access. Bavarian dental equipment distributors concentrate technical service capabilities for high-throughput clinic networks.
Japan
Aging dental infrastructure replacement cycles accelerate procurement of electromechanical systems with surgical-grade load tolerance. PMDA electromagnetic compatibility standards filter non-compliant actuator imports from regional supply chains. Tokyo-Osaka corridor clinics prioritize integrated positioning software for complex oral surgery protocols.
China
Domestic manufacturing scale supports cost-competitive hydraulic chair production for budget-constrained clinic expansion. NMPA medical device registration pathways streamline approval for locally assembled electromechanical components. Yangtze River Delta industrial clusters concentrate precision actuator fabrication capacity.
Brazil
Mobile dental unit programs in underserved regions generate portable chair demand independent of fixed clinic infrastructure investment. ANVISA medical device regulations govern import qualification for electromechanical patient positioning platforms. São Paulo state dental cooperatives coordinate bulk procurement for rural outreach deployment.
Dental Chair Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with precision electromechanical specialists commanding premium positioning while hydraulic assembly operations capture volume in emerging markets. The vendor base organizes around three strategic archetypes: integrated manufacturers with captive actuator production, software-centric positioning system developers, and regional assembly operations dependent on imported components. Competitive dynamics center on M&A activity consolidating field service networks and vertical integration into precision motor supply chains.
Among integrated manufacturers, A-dec, J. Morita, and Planmeca occupy positions representing distinct competitive vectors. A-dec exemplifies the North American integrated production archetype with captive hydraulic and electromechanical lift mechanism fabrication. J. Morita anchors the Asian precision component supply chain dominance visible in actuator manufacturing concentration. Planmeca represents the Nordic software-hardware convergence model with in-house programmable positioning system development. These three entities collectively illustrate how geographic industrial specialization shapes competitive positioning without any single archetype commanding universal advantage across procurement segments.
| Leading Market Players |
|---|
| Takara Belmont |
| Midmark |
| A-dec |
| Anthos |
| J. Morita |
| Dentsply Sirona |
| KaVo |
| Stern Weber |
| Planmeca |
| Others |
Supply Flow & Price Mechanics
FDA quality system regulation gates both supplier qualification and price differentiation simultaneously, filtering non-compliant manufacturers from premium procurement channels while compressing margins for assembly-dependent competitors lacking captive actuator production.
Pricing Analysis
Configured-to-order pricing for electric chairs with programmable positioning software commands substantial premiums over standard hydraulic configurations. Three-tier pricing structure across premium, standard, and economy levels separates surgical-grade electromechanical systems from clinic-grade electric units and budget hydraulic alternatives. Cost compression in the hydraulic tier is intensifying because Asian component suppliers dominate precision actuator manufacturing. Independent dental practices in emerging markets exhibit the highest price sensitivity, while hospital oral surgery departments demonstrate the lowest sensitivity due to capital budget insulation.
Supply Chain Analysis
Strategic stockpiling of brushless DC motors and electromechanical actuators characterizes procurement behavior among integrated manufacturers, while assembly-dependent competitors favor just-in-time arrangements vulnerable to supply disruption. Precision actuator manufacturing concentrates in Japan, Germany, and China, with Yangtze River Delta industrial clusters anchoring volume production. Supply chains draw from rare earth magnet suppliers, precision-machined aluminum alloys, and medical-grade polymer feedstocks. Single-source vulnerability in brushless motor controller chipsets creates structural risk for North American and European chair assemblers. Distribution runs through specialized dental equipment distributors with technical service capabilities, particularly in Bavaria and the Tokyo-Osaka corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dental chair procurement sits in early-cycle expansion as hospital oral surgery departments accelerate platform upgrades for multidisciplinary procedures, creating tailwinds for surgical-grade electromechanical systems.
For Market Incumbents: Secure captive supply of brushless DC motor arrays and programmable control electronics to defend against Asian component supplier forward integration. Invest in ISO 13485 certification maintenance and FDA design control documentation to sustain hospital procurement channel access. Prioritize backward integration into precision actuator fabrication or binding long-term supply agreements with Japanese electromechanical specialists. For New Entrants and Emerging Players: Anchor in portable chair configurations for rural outreach programs across Brazil and India, where mobile dental unit demand operates independent of fixed clinic infrastructure investment. Target veterinary dentistry and humanitarian deployment channels where manual and entry-level electric specifications face limited incumbent competition. Pursue ANVISA and CDSCO registration pathways to unlock government-coordinated bulk procurement for rural health initiatives. For Investors and Strategic Acquirers: FDA cybersecurity guidance for networked medical devices reshapes the acquisition landscape by elevating software-capable platform developers over hardware-centric assemblers. The five-to-ten year viability window favors targets with in-house programmable positioning system development and hospital information system integration capabilities. Monitor PMDA electromagnetic compliance certification rates among Asian actuator suppliers as an inflection indicator for supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Brushless DC Motor Supply Agreement | Captive actuator access insulates margin control against Asian supplier concentration. |
| FDA Design Control Documentation Investment | Programmable chair electronics certification unlocks hospital oral surgery procurement. |
| ISO 13485 Supplier Qualification Pathway | European market access requires twelve-to-eighteen month compliance protocols. |
| Hospital Information System Integration | Cybersecurity-compliant networked control systems capture fastest-growing installation channel. |
| Field Service Network Acquisition | Technical service capabilities consolidate procurement influence among dental service organizations. |
Methodological Framework
Cross-validation between primary interviews with dental equipment procurement managers and secondary validation through FDA 510(k) filings anchors the qualitative findings. Conversations with hospital purchasing committees, biomedical engineers, GPO contracts managers, and dental clinic operations directors informed demand-side segmentation. Bottom-up and top-down triangulation combined customs trade data, hospital procurement databases, and manufacturer shipment disclosures with clinician procedure volume estimates.
Sensitivity analysis across the projection horizon tested demand elasticity for electric versus hydraulic configurations under varying regulatory compliance cost assumptions. The analytical framework models product type, end-user channel, material specification, and feature integration dimensions throughout the forecast period. CAGRs derive from installed base replacement cycle analysis and penetration rate modeling for surgical-grade positioning systems. Brushless motor cost curves and PMDA electromagnetic compliance timelines serve as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under stable regulatory enforcement and supply chain continuity assumptions; material deviation would warrant model refresh. Forecasts reflect documented assumptions regarding hospital oral surgery expansion rates and electromechanical actuator supply availability. Revision becomes warranted when cybersecurity compliance expenditure thresholds or Asian component supplier forward integration crosses materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Intraoral Dental Sensors Market
Dental Devices
Endodontics and Orthodontics Market
Dental Devices
Spain Dental Devices Market
Dental Devices
Global Dental Hygiene Devices Market
Dental Devices
Dental Restoration Market
Dental Devices
Dental Hand Tools Market
Dental Devices
Global Veterinary Dentistry Instruments and Equipment Market
Dental Devices
Dental Calipers Market
Dental Devices
Dental Diamond Burs Market
Dental Devices
RFID-Enabled Dental Printing Market
Dental Devices
Global Orthodontic Product Market
Dental Devices
Global Endodontics Market
Dental Devices
United Kingdom Dental Devices Market
Dental Devices
Global Dental Endodontics Market
Dental Devices
Global Dentures Market
Dental Devices
Europe Dental Implants Market