
 North America Nurse Call Systems Market | 2026-2036
North America Nurse Call Systems Market Size, Share, and Industry Trends Forecast 2026-2036
North America Nurse Call Systems Market Analytics
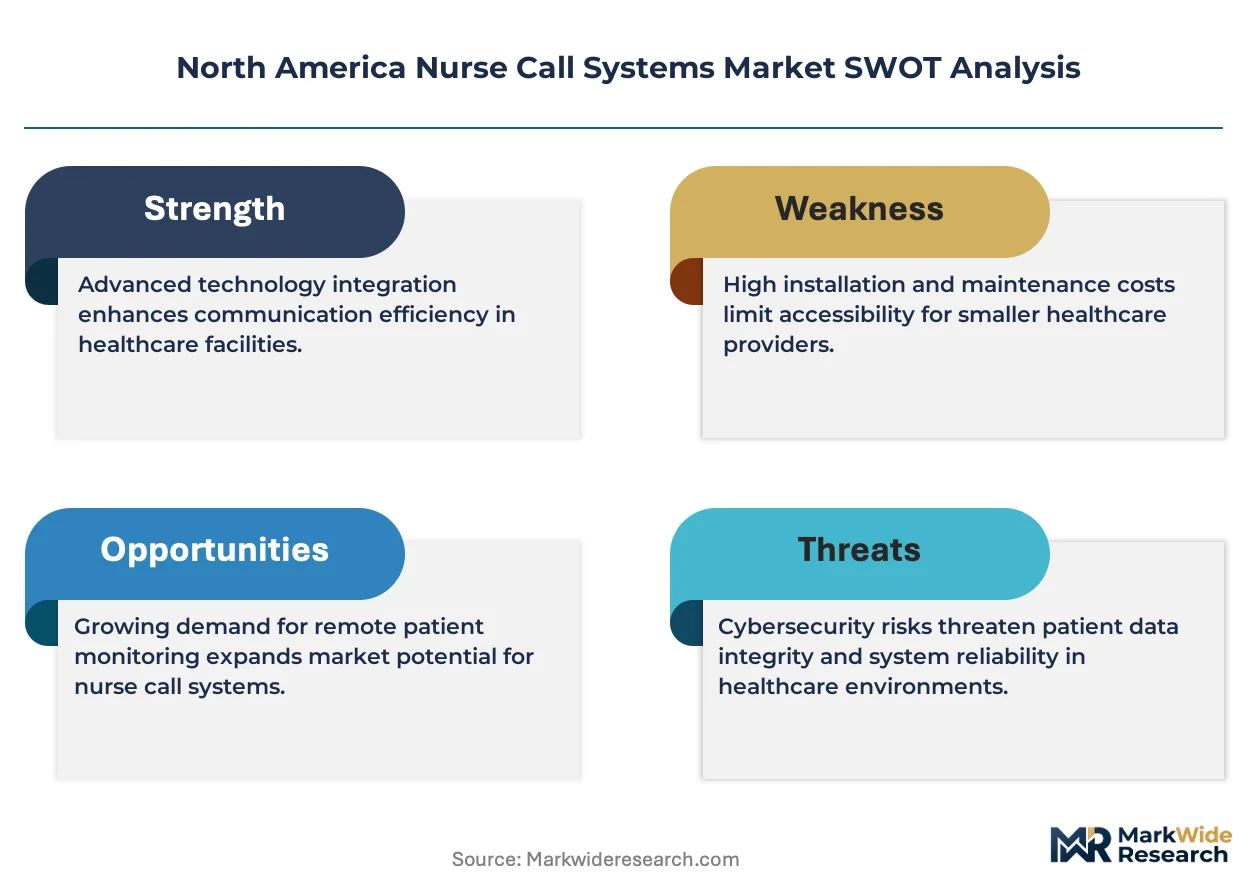
Recurring software subscriptions for platform upgrades and remote monitoring is rebalancing vendor revenue models away from one-time hardware sales. Hill-Rom Holdings Inc. leverages its installed base across major health systems to sustain service attach rates. Ascom Holding AG differentiates through mobile-centric architectures that integrate voice, alarm, and messaging workflows. Jeron Electronic Systems, Inc. specializes in hardwired reliability for skilled nursing operators that prioritize uptime over wireless flexibility.
A nurse call system comprises bedside signaling terminals, corridor dome lights, central nurse console stations, and communication cabling or radio infrastructure that alerts clinical staff to patient assistance requests. These systems integrate with real-time location services and electronic health records to reduce response latency and document care delivery. Wireless systems command attention for greenfield hospital construction, while retrofitting dominates upgrade cycles in aging nursing homes where conduit replacement proves cost-prohibitive. Software solutions capture expanding margin pools as facilities prioritize analytics dashboards and predictive alerting over hardware replacement alone.
The Joint Commission accreditation standards, CMS Conditions of Participation for hospitals, and OSHA workplace safety guidelines collectively mandate reliable patient-staff communication and staff duress alerting capabilities. FDA oversight of connected medical devices adds compliance layers for systems that integrate with patient monitors or infusion pumps. Stakeholders must weigh interoperability commitments against vendor lock-in risks as health systems consolidate purchasing authority across multi-state networks.
Market Dynamics
The transition from hardwired copper infrastructure to IP-based wireless platforms is compressing replacement cycles across acute care hospitals and skilled nursing facilities. CMS reimbursement penalties for patient safety events now directly tie capital budgets to communication system modernization timelines.
Growth Catalysts
- CMS Hospital-Acquired Conditions Reduction Program:Financial penalties for preventable patient harm events force facilities to upgrade response-time tracking capabilities. The program mandates documented staff alert workflows.
- Real-time location services convergence:Nurse call platforms now embed RTLS for asset tracking and staff duress alerting. Acute care hospitals prioritize this integration for emergency department throughput.
- Canadian provincial modernization:Ontario and British Columbia accelerated capital programs for long-term care infrastructure. Federal funding pools target communication system replacements in aging facilities.
Market Restraints
- Copper conduit replacement costs:Retrofitting 1970s-era nursing homes requires complete electrical infrastructure overhaul. Labor costs in urban Canadian markets exceed equipment expenses by three-to-one.
- Semiconductor supply concentration:RF chipsets for wireless call pendants depend on concentrated Asian foundry capacity. Lead times for proprietary frequency modules extend to 26 weeks.
- Interoperability certification delays:FDA 510(k) clearance for devices integrating with patient monitors adds 14-18 months to product launch timelines. Small vendors lack regulatory affairs bandwidth.
Strategic Opportunities
- Behavioral health vertical expansion:Psychiatric hospitals and addiction treatment centers represent underserved demand. These facilities require specialized staff duress and elopement alerting.
- Software-as-a-service migration:Cloud-hosted analytics platforms enable predictive staffing models. Subscription revenue stabilizes vendor cash flows against hardware replacement volatility.
- Mexican hospital privatization:Grupo Angeles and Hospital Star Médica chains expand bed capacity in Monterrey and Guadalajara. Greenfield construction favors wireless-native architectures.
Industry Challenges
- Biomedical engineering talent scarcity:Facilities struggle to hire technicians capable of troubleshooting IP-based networks. Legacy electro-mechanical repair skills dominate the existing workforce.
- Legacy system data migration:Decades of patient call logs and response metrics sit in proprietary formats. Health systems face audit trail gaps during platform transitions.
- Multi-vendor integration complexity:Best-of-breed RTLS, EHR, and security systems require custom middleware. Interoperability testing consumes 40% of implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Nurse Call Systems Market |
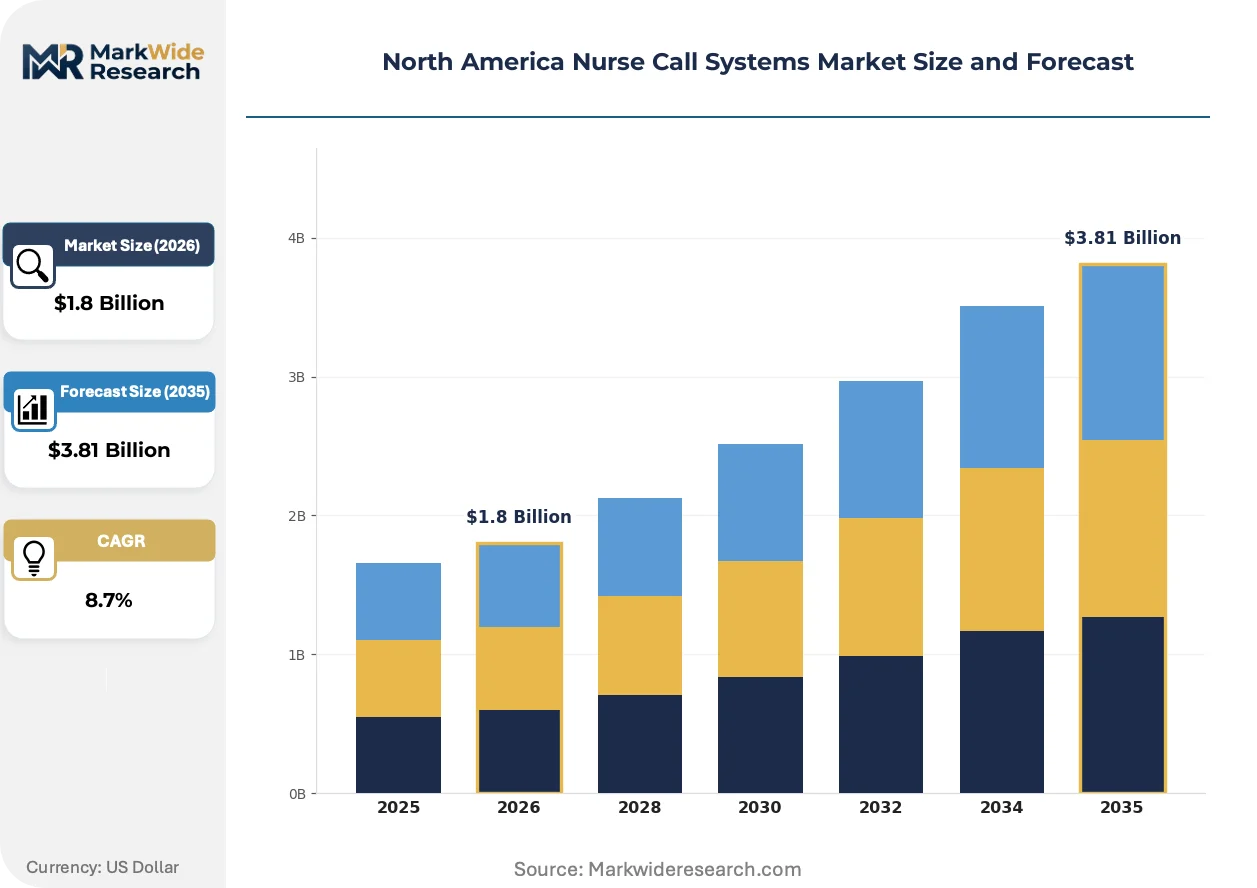
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Systems, Wired Systems, Integrated Systems, Software Solutions End User: Hospitals, Nursing Homes, Assisted Living Facilities, Rehabilitation Centers Technology: Audio-Visual, Mobile Apps, Locator Systems, Messaging Services Installation: New Installations, Upgrades, Retrofitting, Maintenance Services |
| Companies Covered | Rauland-Borg Corporation, Hill-Rom Holdings Inc., Honeywell International, Inc., Ascom Holding AG, Stanley Healthcare, Jeron Electronic Systems, Inc., Cornell Communications, TekTone Sound and Signal Mfg., Inc., Critical Alert Systems LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Nurse Call Systems Market Evolving Landscape
Voice-over-IP and smartphone-based alerting are displacing dedicated hardware endpoints. Vendors now compete on workflow software depth rather than device durability alone.
Bluetooth Low Energy beacon technology is integrating with nurse call infrastructure to enable room-level patient location without separate RTLS hardware. Large health systems in Texas and California deploy this architecture to reduce pendant loss rates. The convergence is integrating asset tracking and staff safety into unified platform investments.
OSHA workplace violence prevention guidelines now mandate staff duress alerting in emergency departments and psychiatric units. The standard requires wearable panic buttons with location transmission to security dispatch. Behavioral health facilities in the Northeast are retrofitting hardwired systems first due to wireless signal interference concerns in shielded environments.
Hospital procurement departments now unbundle installation and multi-year service contracts from initial hardware purchases. Group purchasing organizations negotiate platform-wide pricing across health system networks. This pattern concentrates vendor selection authority in Chicago, Nashville, and San Francisco headquarters rather than individual facility managers.
North America Nurse Call Systems Market Segmentation
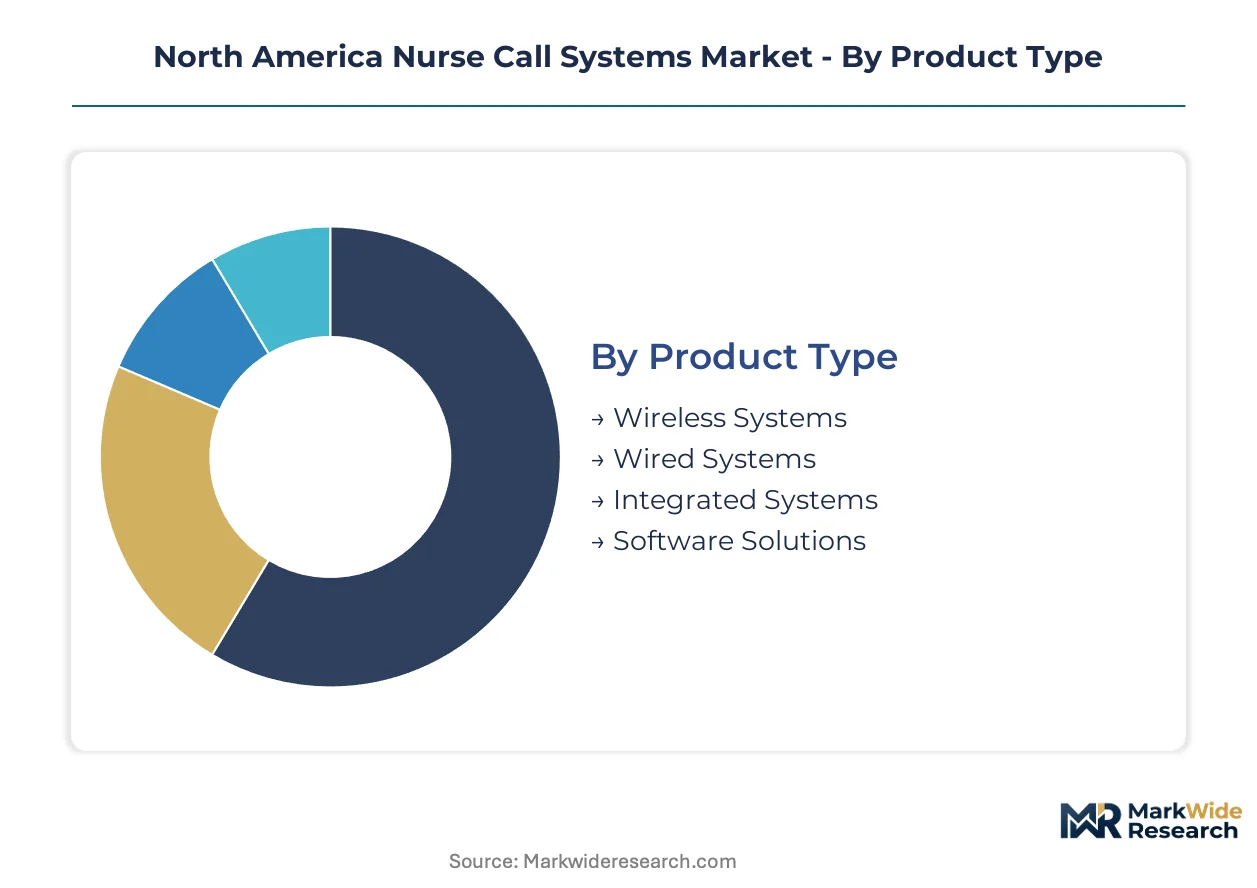
Product architecture and installation method determine regulatory exposure and margin structure across the North America nurse call systems market. Segmentation reveals which configurations face FDA 510(k) pathways versus simpler electrical certifications, directly impacting vendor go-to-market timelines and pricing power.
Product Type:
FDA oversight intensity varies by connectivity level—wireless pendant transmitters with patient monitor integration trigger 510(k) clearance, while standalone wired stations face lighter electrical safety review.
- Wireless Systems:RF-based pendant and dome light architectures eliminate conduit requirements. Greenfield hospital construction in Texas and California favors these platforms for their rapid deployment and RTLS integration capabilities.
- Wired Systems:Copper-cabled infrastructure with centralized switching delivers hardwired reliability for skilled nursing operators prioritizing uptime over flexibility. Canadian provincial modernization programs target these replacements in aging long-term care facilities.
- Integrated Systems:Platforms combining nurse call, RTLS, and EHR connectivity through unified middleware.
- Software Solutions:Cloud-hosted analytics and predictive alerting modules sold on subscription.
Leading the category by volume: Wired Systems. Growing fastest: Software Solutions.
End User:
Facility type dictates workflow complexity and staff duress requirements—acute care hospitals need emergency department throughput optimization while nursing homes prioritize fall response documentation.
- Hospitals:Multi-department deployments spanning medical-surgical floors, ICUs, and emergency departments. CMS Conditions of Participation mandate reliable patient-staff communication with documented response-time tracking.
- Nursing Homes:Long-term care operators face CMS reimbursement penalties for preventable patient harm events. Retrofitting 1970s-era facilities dominates upgrade cycles where conduit replacement proves cost-prohibitive.
- Assisted Living Facilities:Residential care settings requiring lighter-duty alerting with family notification features.
- Rehabilitation Centers:Post-acute facilities needing therapy room coverage and mobility-assisted patient signaling.
Revenue concentrates in: Hospitals. Expanding most quickly: Nursing Homes.
Technology:
Interface modality determines hardware replacement velocity—smartphone-based alerting compresses endpoint lifecycles versus traditional dome light infrastructure.
- Audio-Visual:Corridor dome lights and bedside speaker stations remain standard in legacy facilities. These electro-mechanical endpoints face biomedical engineering talent scarcity for troubleshooting.
- Mobile Apps:Smartphone-based nurse alerting with secure messaging and voice-over-IP integration. Large health systems in the Northeast deploy these architectures to reduce dedicated hardware dependency.
- Locator Systems:Bluetooth Low Energy beacon technology enabling room-level patient location without separate RTLS hardware.
- Messaging Services:Text-based escalation workflows with automatic supervisor notification.
Highest installed base: Audio-Visual. Steepest expansion trajectory: Mobile Apps.
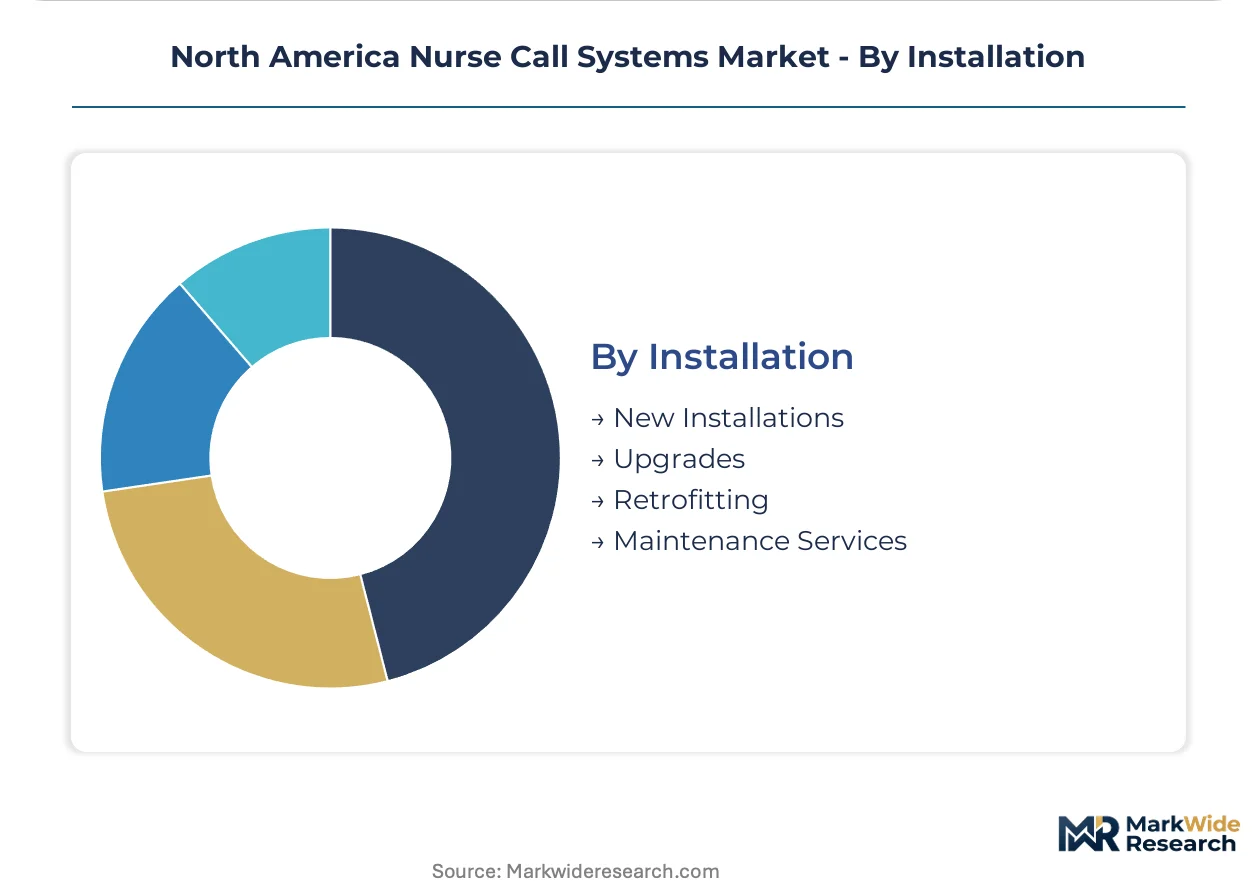
Installation:
Project type shapes vendor cash flow patterns—new installations generate upfront hardware revenue while maintenance services stabilize recurring income.
- New Installations:Greenfield construction in Mexican hospital privatization and US suburban health system expansion. These projects favor wireless-native architectures with IP-based infrastructure.
- Upgrades:Platform replacements retaining existing conduit where possible. Group purchasing organizations negotiate multi-facility rollouts across consolidated health system networks.
- Retrofitting:Infrastructure overhaul in aging facilities requiring complete electrical replacement. Labor costs in urban Canadian markets exceed equipment expenses by substantial margins.
- Maintenance Services:Multi-year service contracts unbundled from initial hardware purchases by hospital procurement departments.
Shortest sales cycles: Maintenance Services. Gaining share fastest: Upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Midwestern US manufacturing corridors while consumption spreads across hospital networks in Sun Belt expansion zones and Canadian provincial health systems. Mexico's private hospital construction creates import demand for wireless-native platforms. The regional imbalance between domestic manufacturing capacity and cross-border installation requirements shapes vendor logistics strategies.
United States
Texas and Florida health systems drive greenfield hospital construction with integrated RTLS-nurse call platforms. CMS Hospital-Acquired Conditions Reduction Program penalties force modernization timelines across medical-surgical floors. Nashville headquarters of major hospital operators concentrate procurement decision-making for multi-state network rollouts.
Canada
Ontario and British Columbia provincial governments accelerated long-term care infrastructure spending following federal funding commitments. Health Canada oversight of connected medical devices adds certification layers for wireless pendant systems. Toronto and Vancouver hospital clusters prioritize retrofitting 1970s-era wired infrastructure in aging nursing homes.
Mexico
Grupo Angeles and Hospital Star Médica chains expand bed capacity in Monterrey and Guadalajara metropolitan zones. Mexican hospital privatization favors wireless-native architectures that reduce installation labor requirements. Northern border states import US-manufactured systems through cross-border distribution channels serving private healthcare investors.
North America Nurse Call Systems Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across hardware manufacturing and software platform development. The vendor base spans diversified medical technology conglomerates, specialized nurse call manufacturers, and emerging software-centric entrants. Three archetypes dominate: integrated health technology platforms, dedicated communication infrastructure specialists, and cloud-native workflow software providers. Consolidation pressure drives strategic partnerships between hardware manufacturers and EHR vendors, while geographic expansion targets Mexican private hospital construction.
Among diversified health technology platforms, Hill-Rom Holdings Inc. and Honeywell International, Inc. occupy positions that leverage broad medical device portfolios. Dedicated communication infrastructure specialists include Rauland-Borg Corporation and Jeron Electronic Systems, Inc., representing manufacturers with focused product architectures. Ascom Holding AG exemplifies the mobile-centric workflow software archetype, sitting within the convergence of voice, alarm, and messaging integration.
| Leading Market Players |
|---|
| Rauland-Borg Corporation |
| Hill-Rom Holdings Inc. |
| Honeywell International, Inc. |
| Ascom Holding AG |
| Stanley Healthcare |
| Jeron Electronic Systems, Inc. |
| Cornell Communications |
| TekTone Sound and Signal Mfg., Inc. |
| Critical Alert Systems LLC |
| Others |
Value Network & Pricing Analysis
IP-based wireless platform migration simultaneously compresses hardware replacement cycles and concentrates component sourcing around RF chipset suppliers. This technology shift forces vendors to rebalance revenue models toward recurring software subscriptions while managing semiconductor procurement exposure.
Pricing Analysis
Margin tightening in hardware tiers reflects CMS reimbursement penalties accelerating facility upgrade timelines. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared integrated systems from standalone wired installations. Pricing pressure stems from group purchasing organization consolidation across multi-state health networks. Nursing homes exhibit highest price sensitivity due to capital constraints, while acute care hospitals prioritize RTLS integration over unit cost.
Supply Chain Analysis
Freight cost volatility from Asian foundry centers to Midwestern US assembly corridors shapes inventory positioning strategies. RF chipsets and Bluetooth Low Energy modules draw from concentrated Taiwanese and South Korean semiconductor capacity. Copper cabling and electro-mechanical components source from domestic US and Mexican maquiladora operations. Single-source vulnerability in proprietary frequency modules creates procurement risk. Distribution runs through hospital procurement departments and group purchasing organization networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America nurse call systems consolidation accelerates as FDA 510(k) clearance timelines and interoperability certification costs force smaller vendors toward strategic exits.
For Market Incumbents: Cement installed base retention through multi-year SaaS contract structures that increase switching costs. Deepen backward integration into RF module design to reduce Asian foundry dependency. Prioritize Health Canada certification investment to capture Ontario and British Columbia provincial modernization programs before regional specialists consolidate share. For New Entrants and Emerging Players: Behavioral health facilities represent an underserved buyer archetype with specialized staff duress requirements and limited incumbent penetration. Target psychiatric hospital chains in the Northeast corridor with hardwired reliability solutions addressing wireless signal interference in shielded environments. Pursue channel partnerships with EHR vendors rather than direct hospital sales cycles. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified health technology platforms seeking nurse call communication capabilities. Five-to-ten year viability favors vendors with cloud-native workflow architectures over legacy hardware manufacturers. Watch for FDA guidance document publication on connected medical device interoperability as inflection indicator for regulatory compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| CMS Compliance Certification Investment | FDA 510(k) clearance for patient monitor integration opens reimbursement-qualifying hospital contracts. |
| Cloud Analytics Platform Launch | Predictive staffing dashboards convert hardware vendors into recurring revenue SaaS providers. |
| Bluetooth Low Energy Beacon Integration | Room-level location services reduce separate RTLS hardware procurement for Texas health systems. |
| Canadian Provincial Partnership | Ontario and British Columbia federal funding pools accelerate long-term care infrastructure replacement cycles. |
| Biomedical Engineering Training Program | IP network troubleshooting capability addresses acute talent scarcity in aging facility retrofit projects. |
Research Methodology
Hospital procurement databases, CMS Medicare reimbursement filings, and FDA 510(k) clearance records formed the secondary backbone for market sizing and competitive mapping. Primary interviews with biomedical engineering directors, GPO contracts managers, long-term care facility administrators, and nurse call system integration specialists validated demand patterns and pricing dynamics. Bottom-up facility counts and top-down health system capital expenditure analysis enabled triangulation across independent estimation approaches.
Historical trendline analysis across product architecture transitions informed projection modeling throughout the forecast period. Segmentation dimensions span connectivity modality, facility type, technology interface, and installation method. CAGRs derive from facility construction pipeline analysis, CMS penalty schedule implementation timelines, and provincial funding commitment trajectories. Semiconductor lead time volatility and biomedical engineering labor market tightness serve as sensitivity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA interoperability guidance evolution and Canadian federal funding continuity. Outputs reflect documented assumptions around reimbursement rule stability and wireless technology adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Equipment
Physiotherapy Equipment Market
Healthcare Equipment
North America Healthcare Machine Vision System Market
Healthcare Equipment
Patient Infotainment Terminals Market
Healthcare Equipment
US Medical Cold Storage Market
Healthcare Equipment
Medical Cold Storage Market
Healthcare Equipment
Emergency Hospital Beds Market
Healthcare Equipment
Skin Cooling Systems Market
Healthcare Equipment
Cold Plunge Tub Market
Healthcare Equipment
Global Hospital Asset Management Market
Healthcare Equipment
Patient Recliner Market
Healthcare Equipment
Healthcare Cold Chain Monitoring Market
Healthcare Equipment
Clinical Mobility Market
Healthcare Equipment
India Healthcare Machine Vision System Market
Healthcare Equipment
Ophthalmic Examination Chairs Market
Healthcare Equipment
Middle East and Africa Ultrasound Probe Disinfection Market
Healthcare Equipment
Healthcare Personal Protection Equipment Market