
 Global Veterinary Dentistry Instruments and Equipment Market | 2026-2036
Global Veterinary Dentistry Instruments and Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Veterinary Dentistry Instruments and Equipment Market Foresight
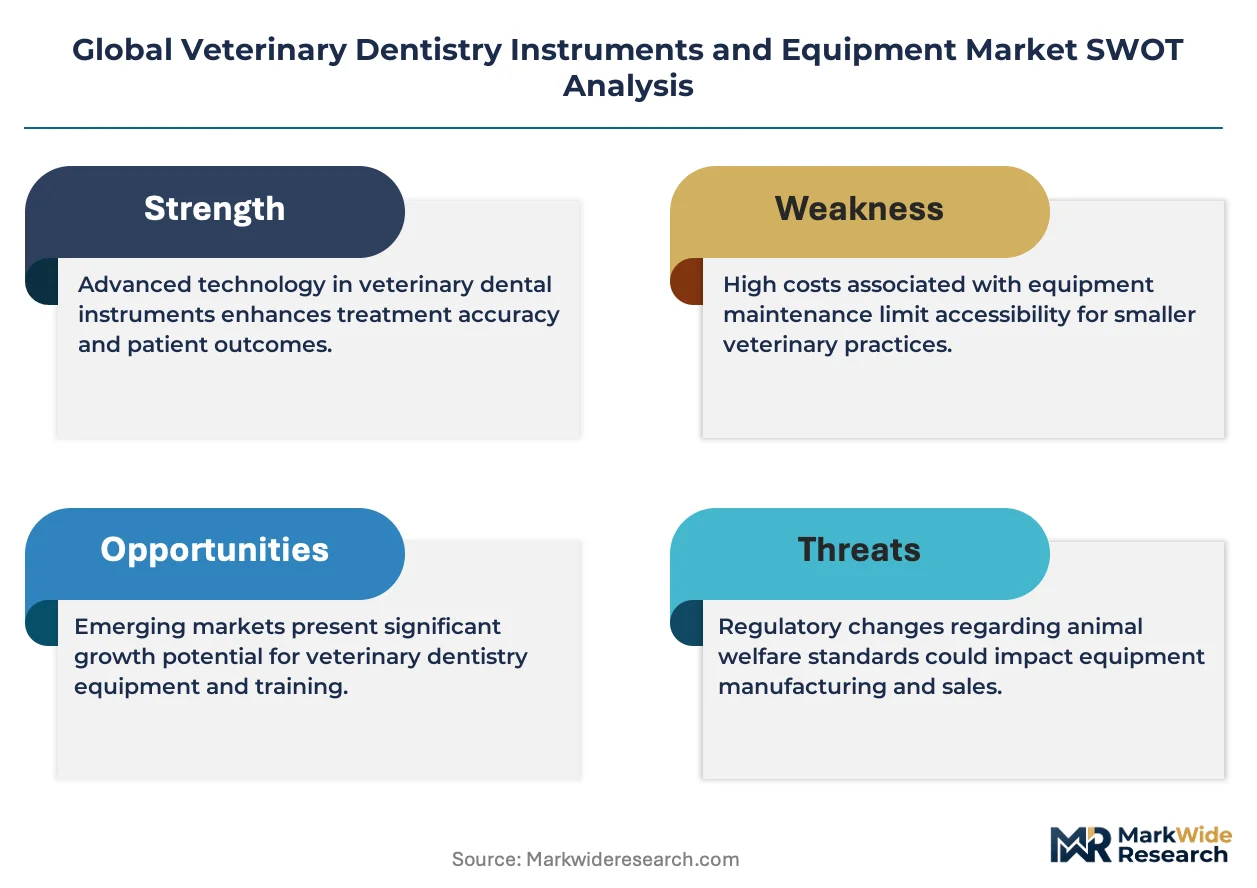
Veterinary equipment distribution through specialty dental dealers is tilting toward direct manufacturer partnerships with large clinic chains. Henry Schein, Inc. leverages its North American logistics footprint to control last-mile delivery of high-value imaging systems. Midmark Corporation anchors its position through dedicated veterinary furniture and procedure room integration. iM3Vet Pty Ltd. specializes in species-specific dental units that dominate the Australian and UK companion animal markets.
Veterinary dentistry instruments and equipment encompass electromechanical devices, precision hand instruments, and powered systems designed for oral examination, calculus removal, tooth extraction, and periodontal intervention in non-human species, typically manufactured from surgical-grade stainless steel or titanium with autoclave-compatible finishes and operating at frequencies between 18,000 and 45,000 RPM for rotary applications. Dental scalars and ultrasonic cleaners lead product type revenue due to replacement cycle intensity and cross-species applicability, while laser technology commands premium positioning in periodontal therapy where soft-tissue precision reduces anesthetic risk. End-user demand pools concentrate in veterinary clinics and animal hospitals where procedure volume justifies capital investment in multimodal dental suites.
FDA Center for Veterinary Medicine device regulations, EU MDR veterinary applicability frameworks, and Australia's APVMA equipment import standards collectively shape product registration pathways and post-market surveillance obligations for manufacturers. ISO 13485 quality management certification has become a de facto market access requirement across OECD veterinary device procurement channels. Stakeholders must monitor evolving national veterinary dental curriculum standards that determine which technologies graduating practitioners are trained to operate and prescribe.
Market Dynamics
Veterinary practice consolidation is compressing procurement autonomy, as large clinic chains centralize purchasing decisions and demand integrated equipment suites that smaller manufacturers cannot assemble.
Growth Catalysts
- EU MDR veterinary applicability frameworks:Harmonized device classification across member states accelerates cross-border certification, reducing duplicate testing costs for manufacturers targeting multiple European markets.
- Companion animal insurance expansion:Broadened coverage for dental procedures in the United States and Germany converts out-of-pocket veterinary spending into reimbursable claims, unlocking procedure volume.
- Titanium alloy instrumentation:Superior autoclave durability and corrosion resistance extend instrument lifespan in high-throughput hospital settings, justifying premium positioning.
Market Restraints
- Surgical-grade stainless steel price volatility:Nickel and chromium input cost swings compress margin buffers for instrument manufacturers locked into annual distributor contracts.
- Supply concentration in German precision machining:Dependency on Baden-Württemberg component suppliers creates vulnerability to regional energy cost shocks and logistics disruptions.
- FDA Center for Veterinary Medicine premarket notification pathways:Extended 510(k) review timelines for novel electromechanical devices delay revenue recognition by 8-14 months.
Strategic Opportunities
- Underpenetrated Brazilian market:São Paulo and Rio de Janeiro veterinary clinic density remains below OECD benchmarks, creating first-mover advantage for ISO 13485-certified entrants.
- Laser-ultrasonic convergence:Combined soft-tissue and calculus removal modalities reduce anesthetic duration, appealing to high-volume feline dental practices.
- Australia's APVMA streamlined import registration:Mutual recognition agreements with EU notified bodies accelerate market entry for European manufacturers.
Industry Challenges
- Veterinary dental anesthesia certification gaps:Graduating practitioners in France and Italy receive minimal hands-on training with powered rotary systems, limiting immediate equipment utilization.
- Capital intensity of multimodal imaging suites:Digital radiography and cone-beam CT integration requires six-figure investments that strain independent clinic balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Veterinary Dentistry Instruments and Equipment Market |
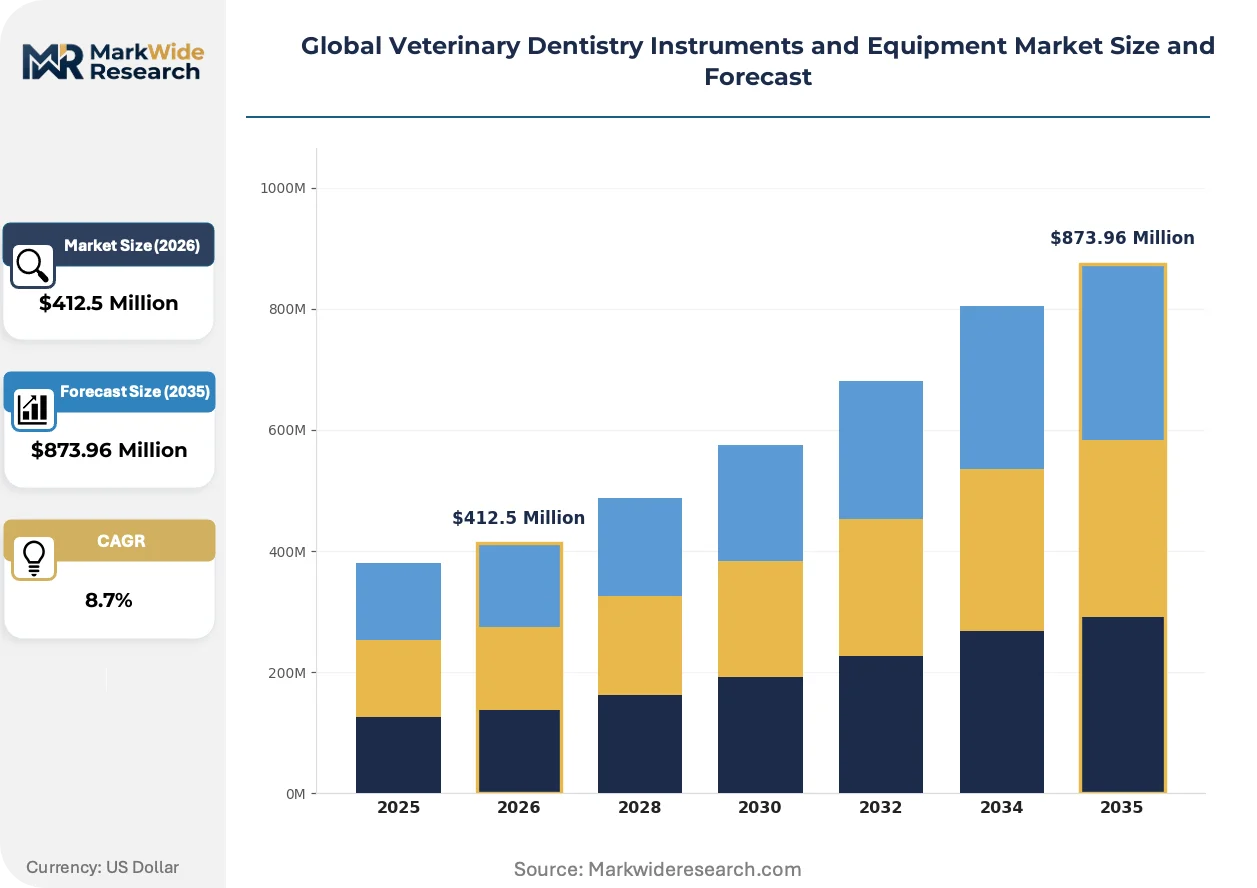
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dental Scalers, Polishing Equipment, Ultrasonic Cleaners, Handpieces, Dental Curettes Technology: Ultrasonic, Laser, Manual, Electric, Battery Operated Application: Teeth Cleaning, Periodontal Therapy, Tooth Extraction, Endodontic Treatment, Orthodontic Procedures End User: Veterinary Clinics, Animal Hospitals, Research Laboratories, Mobile Vet Services, Zoos |
| Companies Covered | Henry Schein, Inc., Midmark Corporation, iM3Vet Pty Ltd., Dentalaire International, Patterson Companies, Inc., Integra LifeSciences Holdings Corporation, Planmeca Oy, Acteon Group Ltd., Dispomed Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Veterinary Dentistry Instruments and Equipment Market Shifts & Advancements
Digital workflow integration is erasing boundaries between diagnostic imaging, treatment planning, and procedure documentation, forcing equipment vendors to deliver interoperable platforms rather than standalone devices.
Portable battery-operated dental units are collapsing the distinction between clinic-based and field veterinary dentistry. Mobile large-animal practitioners in Australia and the western United States now perform extractions and periodontal therapy on-site. Equipment rental networks and shared-ownership models are emerging to serve this decentralized demand pattern.
Japan's PMDA has tightened electrical safety standards for veterinary electrosurgical devices, requiring IEC 60601-1 third edition compliance for all new market registrations. Domestic manufacturers are redesigning grounding systems and leakage current protection. Export-oriented suppliers in South Korea and Taiwan are accelerating certification to maintain access.
Large clinic chains now specify outcome-based equipment performance guarantees in procurement tenders, replacing traditional capital purchase with per-procedure leasing structures. Henry Schein and specialty veterinary distributors are restructuring sales compensation to align with recurring revenue recognition. This shift is most advanced in the United States and United Kingdom.
Global Veterinary Dentistry Instruments and Equipment Market Segmentation
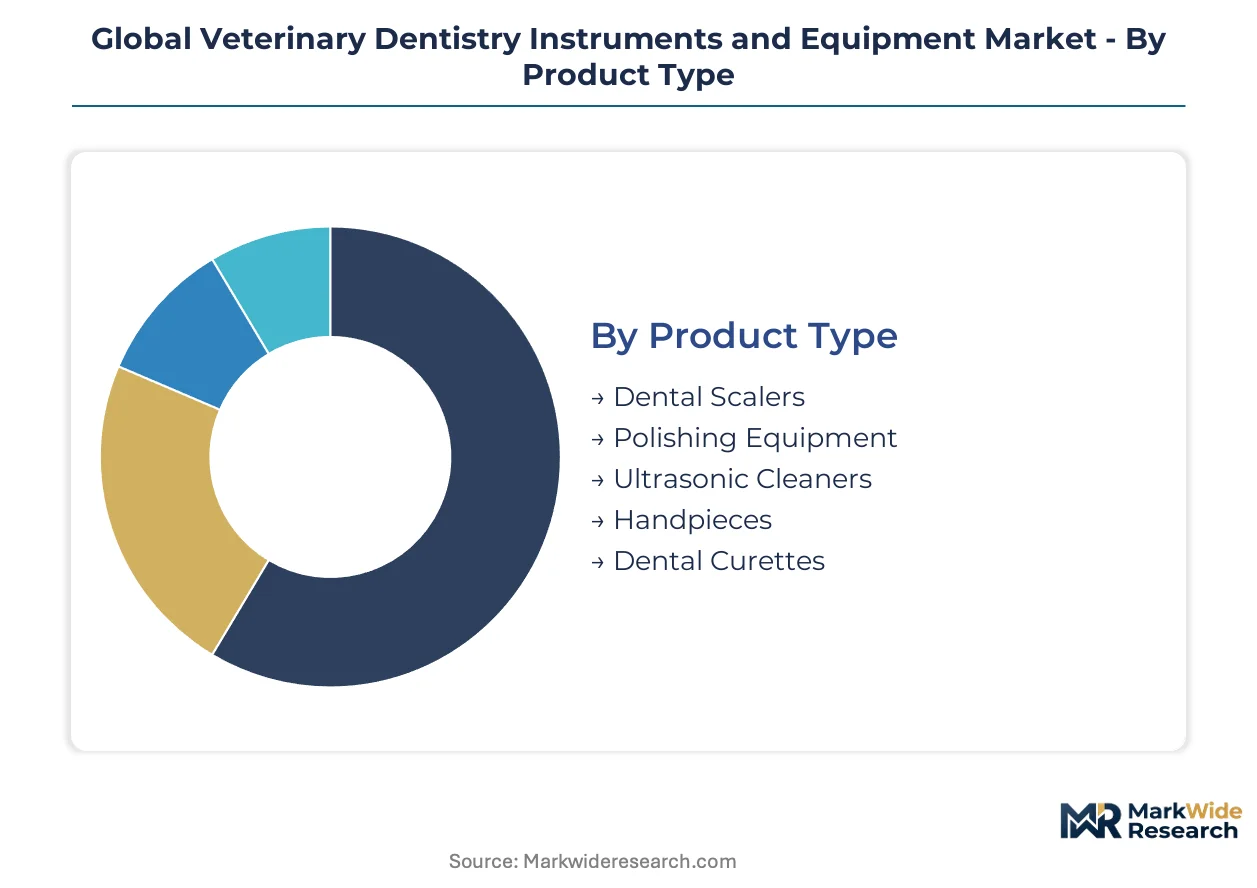
Veterinary dentistry equipment segments diverge sharply in replacement cadence. Consumables and hand instruments turn over in months, while capital equipment locks purchasing cycles into multi-year horizons. Understanding these rhythm differences shapes inventory strategy and service revenue models for distributors.
Product Type:
Replacement cycle intensity separates high-velocity consumables from durable capital goods, with direct implications for recurring revenue streams versus one-time equipment sales.
- Dental Scalers:Precision instruments manufactured from surgical-grade stainless steel or titanium alloys, designed for calculus removal across canine, feline, and equine dentition. United States companion animal clinics drive replacement demand through sterilization protocols that degrade cutting edges after 12-18 months of high-volume use. Frequent replacement creates predictable aftermarket revenue for specialty distributors.
- Polishing Equipment:Rotary prophylaxis systems operating at controlled RPM ranges with disposable prophy angle attachments. German and Australian veterinary hospital chains specify integrated polishing modules within multimodal dental suites, bundling equipment procurement with consumable supply contracts. Capital-intensive positioning limits penetration in independent practices.
- Ultrasonic Cleaners:Piezoelectric or magnetostrictive scaling systems generating cavitation for subgingival debridement.
- Handpieces:High-speed rotary instruments for sectioning and extraction procedures.
- Dental Curettes:Manual periodontal instruments for root planing and subgingival curettage.
Dental Scalers anchor the volume base while Ultrasonic Cleaners gain share at the steepest rate.
Technology:
Power source and energy modality determine equipment portability, procedural precision, and total cost of ownership across deployment settings.
- Ultrasonic:Cavitation-based calculus removal with adjustable water irrigation, dominating high-throughput hospital environments where procedure speed governs anesthetic duration. United States academic veterinary hospitals train residents on ultrasonic platforms, embedding technology preference into future purchasing authority.
- Laser:Soft-tissue ablation and periodontal pocket sterilization using diode or CO2 wavelengths. Premium positioning in feline-exclusive practices across Japan and the United Kingdom, where reduced hemorrhage and postoperative pain justify per-procedure cost premiums. Japan's PMDA electrical safety standards constrain supplier eligibility.
- Manual:Hand-activated instrumentation without powered assistance.
- Electric:Mains-powered rotary and scaling systems for fixed installation.
- Battery Operated:Cordless units enabling field dentistry in mobile and large-animal applications.
Manual technology retains the widest installed base though Laser platforms command the highest margin expansion trajectory.
Application:
Procedure complexity and reimbursement status shape equipment specification, with preventive services scaling faster than intervention-heavy specialties.
- Teeth Cleaning:Prophylactic scaling and polishing constituting the procedural volume foundation. Expansion of pet insurance dental coverage in Germany and the United States converts previously declined preventive care into billable services, driving scaler and polisher procurement.
- Periodontal Therapy:Subgingival intervention for stage 2-4 periodontal disease, increasingly combining ultrasonic debridement with adjunctive laser treatment. Australian companion animal practices report rising case complexity as pet longevity extends.
- Tooth Extraction:Surgical removal requiring radiographic planning and specialized elevation instruments.
- Endodontic Treatment:Root canal therapy and vital pulp therapy for strategic tooth preservation.
- Orthodontic Procedures:Malocclusion correction primarily in brachycephalic breeds and show animals.
Teeth Cleaning generates the highest procedure count while Periodontal Therapy shows the strongest technology upgrade intensity.
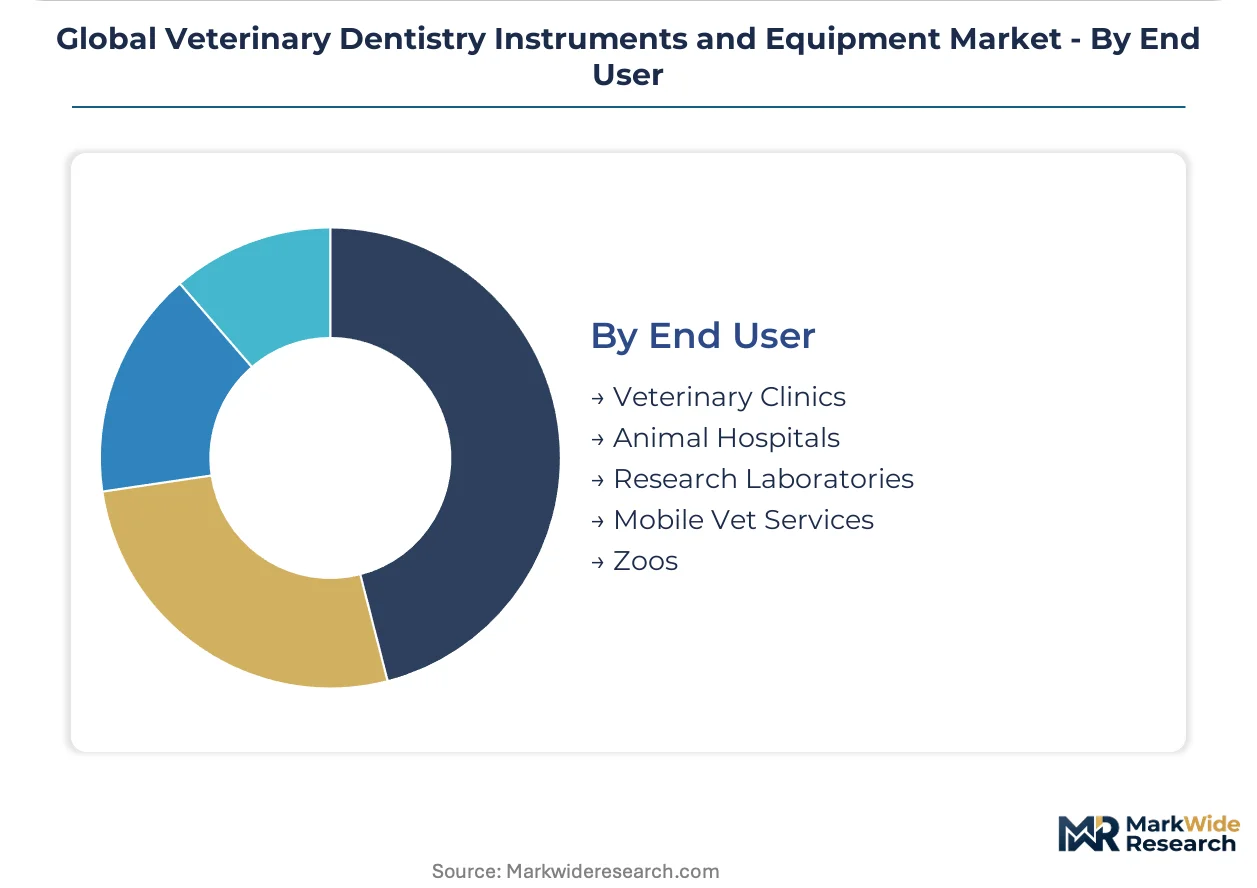
End User:
Facility scale and case mix determine capital absorption capacity, with consolidated chains extracting procurement advantages unavailable to independent operators.
- Veterinary Clinics:Primary care settings performing routine dental prophylaxis and minor extractions. United States practice consolidation concentrates purchasing decisions within corporate procurement offices, favoring integrated equipment suites from established distributors over standalone device vendors.
- Animal Hospitals:Referral and emergency centers with specialist dental services and multimodal imaging capability. Germany's university veterinary hospitals set equipment standards that cascade through continuing education networks, influencing private hospital procurement specifications.
- Research Laboratories:Institutional settings with specialized protocol requirements.
- Mobile Vet Services:Field practitioners serving equine and agricultural species across dispersed geographies.
- Zoos:Exotic species dentistry requiring customized instrumentation for non-standard dentition.
Veterinary Clinics constitute the deepest demand pool while Animal Hospitals drive specification complexity upward fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles anchors trans-Pacific distribution for high-value veterinary imaging systems entering North America. German precision machining clusters in Baden-Württemberg supply rotary handpiece components to assemblers worldwide. Sydney's specialized veterinary distributor networks bridge Asia-Pacific demand with European manufacturing.
United States
Companion animal insurance expansion in California and Texas converts dental procedures into reimbursable claims. FDA Center for Veterinary Medicine 510(k) pathways govern electromechanical device registration. Henry Schein's Melville distribution hub consolidates last-mile logistics for multimodal dental suites across the Northeast corridor.
Germany
University veterinary hospitals in Leipzig and Munich set equipment standards that cascade through continuing education networks. EU MDR veterinary applicability frameworks harmonize device classification across member states. Baden-Württemberg's precision machining suppliers concentrate rotary component manufacturing near Stuttgart industrial clusters.
Australia
Mobile large-animal practitioners in Queensland and Western Australia drive portable battery-operated unit demand. APVMA streamlined import registration accelerates European manufacturer market entry through mutual recognition agreements. Sydney and Melbourne veterinary distributor networks specialize in species-specific dental units for companion animal practices.
Japan
Feline-exclusive practices in Tokyo and Osaka premium-position laser periodontal therapy to reduce anesthetic risk. PMDA tightened electrical safety standards require IEC 60601-1 third edition compliance for electrosurgical device registration. Kanto region equipment distributors serve high-density metropolitan veterinary clinic networks.
Brazil
São Paulo veterinary clinic density remains below OECD benchmarks despite rising companion animal ownership. ANVISA medical device regulations establish registration pathways for imported instrumentation. Rio de Janeiro specialty practices create first-mover opportunity for ISO 13485-certified equipment entrants.
Global Veterinary Dentistry Instruments and Equipment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying precision-machined rotary elements and disposable attachments. The vendor base splits between consolidated distribution conglomerates with North American logistics footprints and mid-scale specialists focused on species-specific configurations. Three archetypes dominate: integrated equipment suite assemblers, precision hand instrument forges, and mobile/portable system innovators. Competitive moves concentrate on direct manufacturer partnerships with consolidating clinic chains and outcome-based performance guarantees replacing capital purchase structures.
Within the distribution-integrated tier, Henry Schein, Inc. and Patterson Companies, Inc. occupy positions anchoring North American supply chain control through dedicated veterinary logistics networks. Midmark Corporation exemplifies the equipment integration archetype through procedure room configuration specialization. iM3Vet Pty Ltd. represents the geography-anchored specialist model with concentrated presence in Australian and UK companion animal markets.
| Leading Market Players |
|---|
| Henry Schein, Inc. |
| Midmark Corporation |
| iM3Vet Pty Ltd. |
| Dentalaire International |
| Patterson Companies, Inc. |
| Integra LifeSciences Holdings Corporation |
| Planmeca Oy |
| Acteon Group Ltd. |
| Dispomed Ltd. |
| Others |
Supply & Pricing Matrix
Baden-Württemberg's precision machining clusters near Stuttgart govern rotary handpiece component availability, translating regional energy cost volatility into downstream margin pressure for equipment assemblers locked into annual distributor contracts. German supplier concentration hands pricing leverage to component forges while veterinary clinic chains exploit volume scale to compress capital equipment acquisition costs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by ISO 13485 certification status and after-sales service bundling. Premium tiers capture university veterinary hospitals and consolidated clinic chains seeking outcome-based performance guarantees, while independent practices gravitate toward economy tiers with stripped-down warranty coverage. Pricing pressure stems from nickel and chromium input cost swings in surgical-grade stainless steel, squeezing instrument manufacturers with fixed distributor pricing commitments. Corporate procurement offices at large clinic chains exhibit lowest price sensitivity due to insurance reimbursement pass-through, whereas mobile large-animal practitioners demonstrate highest elasticity.
Supply Chain Analysis
Extended payment terms from 90 to 120 days now dominate supplier-finance arrangements between Baden-Württemberg precision machinists and North American equipment assemblers. Manufacturing concentration in Germany, South Korea, and Taiwan feeds rotary component supply, with titanium alloy bar stock and piezoelectric transducers anchoring raw material dependencies. Single-source vulnerability concentrates in Stuttgart-area CNC machining capacity exposed to regional energy cost shocks. Distribution runs through Henry Schein's Melville hub and Patterson's veterinary logistics networks, consolidating last-mile delivery for multimodal dental suites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pet insurance coverage expansion across the United States and Germany signals early-cycle penetration acceleration, converting out-of-pocket veterinary spending into reimbursable dental claims that unlock procedure volume and equipment procurement.
For Market Incumbents: Insulate margin position through captive supply agreements with Baden-Württemberg precision machinists, locking in component access against energy cost volatility. Accelerate ISO 13485 certification investment to maintain procurement eligibility as EU MDR veterinary applicability frameworks tighten quality benchmarks. Direct manufacturer partnerships with consolidating clinic chains represent the priority defensive lever against specialty distributor disintermediation. For New Entrants and Emerging Players: Build out portable battery-operated dental units targeting Queensland and Western Australia's mobile large-animal practitioners, where field dentistry demand outpaces incumbent product development. São Paulo's underpenetrated veterinary clinic density offers white-space entry for ISO 13485-certified equipment suites. Species-specific configurations for Australian companion animal markets provide differentiated go-to-market positioning against integrated equipment suite vendors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision hand instrument forges with established Baden-Württemberg supplier relationships and recurring consumable revenue streams. Long-term viability hinges on laser-ultrasonic convergence platforms reducing anesthetic duration in high-volume feline practices. Watch FDA Center for Veterinary Medicine 510(k) review timeline compression as inflection signal for novel electromechanical device revenue recognition acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Secures procurement eligibility across EU MDR and APVMA regulatory frameworks. |
| Direct Manufacturer Partnership | Bypasses specialty dental dealers to capture consolidated clinic chain volume. |
| Laser-Ultrasonic Platform Development | Reduces anesthetic risk in feline-exclusive practices commanding premium positioning. |
| Portable Battery-Operated Unit Launch | Addresses Queensland mobile large-animal field dentistry demand gap. |
| Outcome-Based Performance Guarantee | Replaces capital purchase with per-procedure leasing structures for hospital chains. |
Research Methodology
Operator-level perspectives from veterinary practice owners, hospital procurement managers, biomedical equipment technicians, and distributor sales directors anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, APVMA import registration records, and veterinary dental curriculum standards. Customs data on titanium alloy and surgical-grade stainless steel trade flows supplemented demand-side triangulation. Bottom-up equipment unit economics and top-down macroeconomic drivers were cross-referenced for consistency.
Scenario-bracketing around pet insurance penetration rates and veterinary practice consolidation velocity framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product type replacement cycles, technology power modalities, application procedure complexity, and end-user facility scale. CAGRs derived from procedure volume elasticities to insurance coverage expansion and equipment replacement cadence assumptions. Veterinary dental anesthesia certification gaps and multimodal imaging suite capital intensity served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by Henry Schein or Patterson would shift component supplier bargaining dynamics. Macroeconomic deviation in nickel and chromium commodity markets, regulatory acceleration in FDA premarket notification pathways, or technological breakthrough in laser-ultrasonic convergence platforms would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
North America Dental Lasers Market
Dental Devices
Dental Veneers Market
Dental Devices
Dental Amalgamators Market
Dental Devices
Dental Implants Market
Dental Devices
Dental Healing Caps Market
Dental Devices
Latin America Dental Devices Market
Dental Devices
Toothbrush Sterilizer Market
Dental Devices
Dental Caries and Endodontic Market
Dental Devices
Acrylic Teeth Market
Dental Devices
3D Printing Dental Device Market
Dental Devices
Malocclusion Market
Dental Devices
Global Dental Crowns and Bridges Market
Dental Devices
Global Dental Obturators Market
Dental Devices
Italy Dental Devices Market
Dental Devices
Dental Floss Market
Dental Devices
Turkey CAD/CAM Dental Devices Market