
 Dental Hand Tools Market | 2026-2036
Dental Hand Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Hand Tools Market Analysis
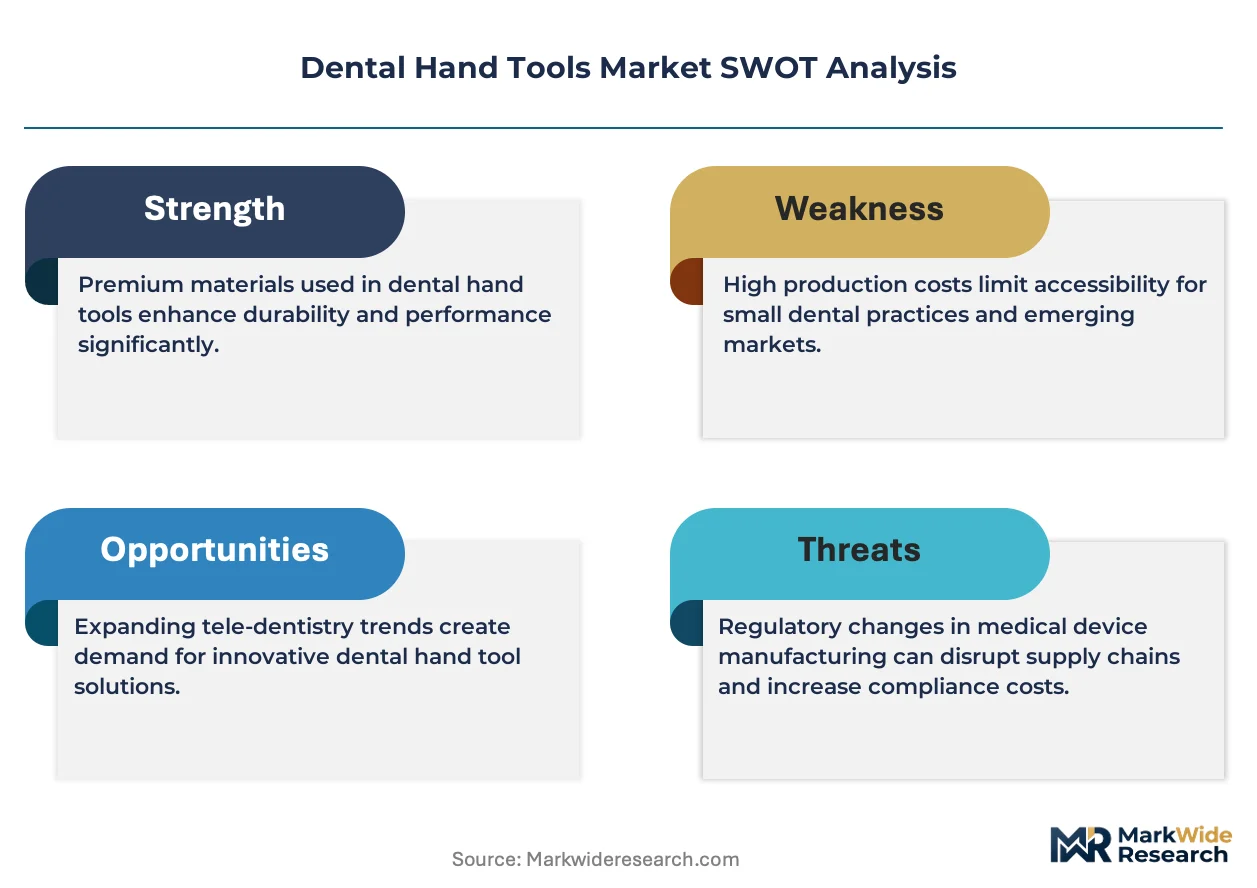
Stainless steel is decoupling from premium instrument economics as tungsten carbide tips and ceramic-coated alternatives gain traction in high-wear applications. Dentsply Sirona leverages vertical integration across milling and finishing operations to protect margin pools on precision burs. KaVo Group anchors its position through captive production of turbine handpiece interfaces. Hu-Friedy competes on R&D intensity in ergonomic handle geometries for extended clinical use.
Dental hand tools are manually operated or low-speed rotary instruments fabricated from medical-grade alloys and polymers, typically heat-treated to Rockwell C 48-52 hardness for edge retention and corrosion resistance; they serve restorative, periodontal, and surgical procedures requiring tactile feedback beyond motorized systems. Scalers and diagnostic mirrors occupy mature revenue streams with replacement-cycle predictability, while tungsten carbide inserts in excavators and finishing burs capture expanding margin pools as adhesive dentistry proliferates. Dental clinics constitute the dominant procurement channel, though dental schools represent a concentrated volume segment driven by bulk training kit standardization.
FDA 510(k) clearance pathways and ISO 13485 quality system mandates govern US market access, while the EU Medical Device Regulation's Class I reclassification for reusable instruments tightens clinical evidence requirements for European suppliers. The EPA's reprocessing effluent standards and emerging state-level dental amalgam separator rules indirectly shape instrument selection and retirement protocols. Stakeholders must monitor how MDR transition timelines and FDA digital health pre-certification pilots converge on instrument traceability requirements.
Market Dynamics
ISO 13485 quality mandates and FDA reprocessing guidance are compressing supplier margins while elevating certified stainless steel and single-use instrument procurement across dental clinics. This regulatory tightening favors manufacturers with captive heat-treatment and finishing capabilities.
Growth Catalysts
- EU Medical Device Regulation Class I reclassification:Reusable instruments face tightened clinical evidence requirements, accelerating demand for pre-certified suppliers with established quality systems in Germany and France.
- Tungsten carbide tip proliferation:Adhesive dentistry expansion drives excavator and finishing bur replacement cycles, with ceramic-coated alternatives capturing high-wear restorative applications.
- North American clinic consolidation:Dental service organizations standardize procurement across multi-site networks, favoring vendors with volume-scale logistics and kit-configuration flexibility.
Market Restraints
- Nickel and cobalt alloy volatility:Medical-grade stainless steel input costs fluctuate with commodity markets, squeezing margin pools on mid-tier diagnostic mirrors and scalers.
- German-Japanese manufacturing concentration:Precision milling and turbine handpiece interface production clusters in Stuttgart and Osaka regions, creating geographic supply risk.
- Rockwell C 48-52 hardness ceiling:Conventional heat-treatment protocols limit edge retention in periodontal curettes, constraining functional lifespan against patient throughput demands.
Strategic Opportunities
- Indian dental school bulk procurement:Training kit standardization at institutions in Mumbai and Delhi creates concentrated volume contracts with multi-year replacement schedules.
- EPA effluent compliance services:Reprocessing audit and instrument retirement protocol consulting opens recurring revenue streams adjacent to hardware sales.
- Ergonomic handle geometry R&D:Extended clinical use requirements in surgical suites drive demand for polymer-composite grips with vibration-dampening properties.
Industry Challenges
- 510(k) clearance timeline compression:FDA digital health pre-certification pilots create parallel track complexity for instrument traceability system submissions.
- Multi-site inventory synchronization:Dental service organizations demand real-time lot tracking across distributed clinic networks, straining legacy ERP integrations.
- Amalgam separator rule fragmentation:Emerging state-level dental effluent standards in California and New York force instrument selection protocol variations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Hand Tools Market |
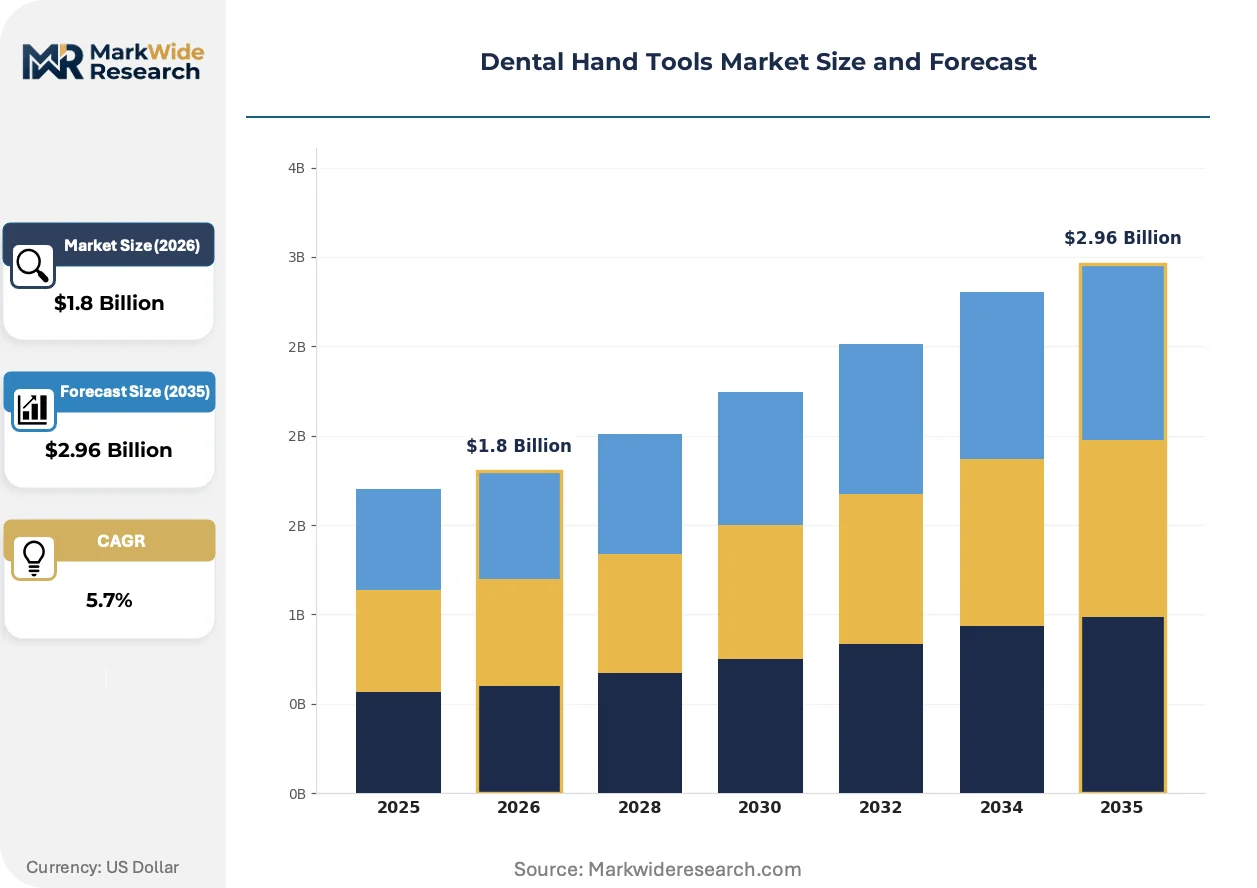
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scalers, Excavators, Forceps, Mirrors Material: Stainless Steel, Plastic, Tungsten Carbide, Aluminum End User: Dental Clinics, Hospitals, Dental Schools, Research Labs Application: Teeth Cleaning, Restorative Procedures, Extractions, Diagnostic Procedures |
| Companies Covered | Dentsply Sirona, Hu-Friedy, KaVo Group, Integra LifeSciences, 3M Company, Kerr Corporation, Planmeca, Henry Schein, Brasseler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Hand Tools Market Emerging Trajectories
Material science advances and regulatory digitization are restructuring how dental hand tools are specified, procured, and retired across clinical environments. These shifts favor suppliers with integrated quality-data infrastructure.
Ceramic-coated burs and tungsten carbide inserts are absorbing margin migration from conventional stainless steel in high-precision restorative applications. Dental clinics in the United States and Germany are adopting these materials at accelerated replacement frequencies. This material shift is absorbing volume from economy-grade instrument tiers while compressing price elasticity in premium segments.
The EU Medical Device Regulation's Class I reclassification for reusable instruments tightens post-market surveillance and clinical evidence requirements. European suppliers face expanded technical documentation burdens and notified body engagement costs. German and Swiss manufacturers are responding by consolidating SKU portfolios and accelerating single-use instrument line development.
Consolidated buying by dental service organizations is unbundling after-sales service from hardware contracts. Multi-site procurement teams in Texas and Florida now negotiate instrument kits, reprocessing protocols, and retirement logistics as separate spend categories. This unbundling is most visible in periodontal scaler and diagnostic mirror categories where replacement predictability enables just-in-time inventory models.
Dental Hand Tools Market Segmentation
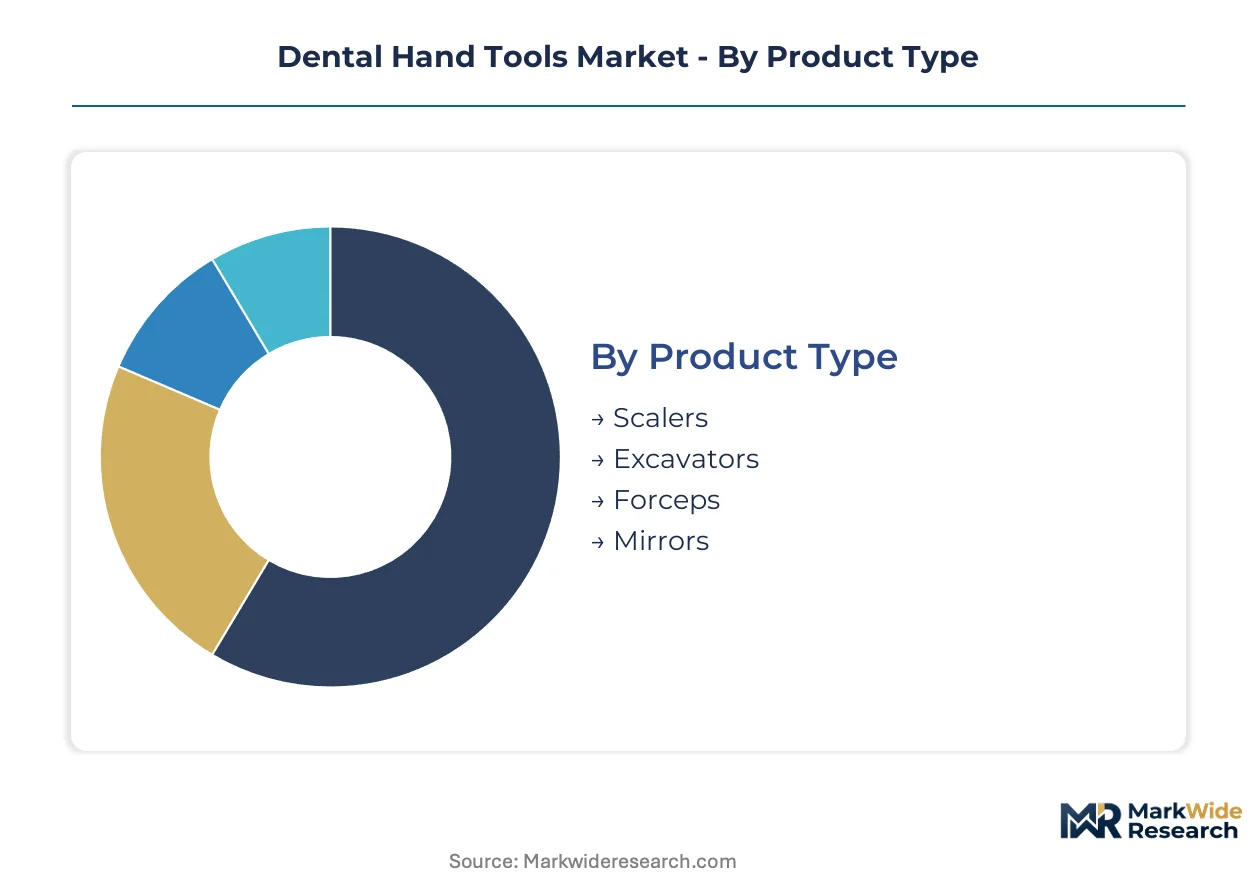
Material specifications and sterilization protocols create divergent procurement patterns across dental hand tool categories. Segment boundaries reflect how clinical use intensity, regulatory exposure, and replacement cycles concentrate purchasing power.
Product Type:
Tool geometry and functional durability separate premium procurement from commodity replacement cycles.
- Scalers:Periodontal curettes and sickle scalers fabricated from medical-grade stainless steel with Rockwell C 48-52 hardness ratings dominate high-frequency replacement schedules. Dental clinics in Germany and the United States absorb volume through standardized kit configurations driven by ISO 13485-certified suppliers.
- Excavators:Spoon and hatchet designs with tungsten carbide inserts command margin premiums as adhesive dentistry expands cavity preparation precision. Japanese manufacturers concentrate production of precision-milled working ends for restorative suites in Stuttgart and Osaka.
- Forceps:Extraction instruments with ergonomic handle geometries serve oral surgery suites requiring tactile feedback beyond motorized systems.
- Mirrors:Diagnostic mouth mirrors with rhodium-coated surfaces occupy predictable replacement cycles in dental school training kits.
Scalers lead on scale; excavators lead on momentum.
Material:
Cost tier stratification follows heat-treatment capability and corrosion resistance specifications.
- Stainless Steel:Medical-grade alloys with chromium-nickel composition remain the baseline for reusable instruments subject to FDA reprocessing guidance and EPA effluent standards. Procurement concentrates in North American dental service organizations standardizing across multi-site networks.
- Tungsten Carbide:Cemented carbide tips bonded to stainless steel shanks absorb margin migration in high-wear restorative applications where edge retention exceeds Rockwell hardness ceilings of conventional heat treatment.
- Plastic:Polymer-composite handles with vibration-dampening properties address ergonomic requirements in extended surgical procedures.
- Aluminum:Lightweight alloys serve single-use instrument lines developing under EU Medical Device Regulation Class I reclassification pressures.
Stainless steel anchors procurement volume; tungsten carbide captures expanding margin pools.
End User:
Customer type determines kit standardization depth and replacement predictability.
- Dental Clinics:Private practices and dental service organizations drive instrument procurement through consolidated buying agreements. Texas and Florida multi-site networks unbundle after-sales service from hardware contracts.
- Dental Schools:Training institutions in Mumbai and Delhi generate concentrated bulk contracts with multi-year replacement schedules for standardized student kits.
- Hospitals:Oral surgery departments within integrated health systems procure specialized forceps and elevators through centralized sterile processing departments.
- Research Labs:Academic and commercial research facilities absorb precision instruments for material science and clinical validation studies.
Dental clinics concentrate purchasing power; dental schools offer contract predictability.
Application:
Procedure volume and reimbursement exposure shape instrument specification priorities.
- Restorative Procedures:Cavity preparation and finishing demand tungsten carbide burs and ceramic-coated alternatives with precision tolerances for adhesive dentistry workflows. German manufacturers supply premium segments while Chinese producers serve economy tiers.
- Teeth Cleaning:Prophylaxis and periodontal maintenance generate recurring scaler and curette demand with replacement cycles tied to patient throughput.
- Extractions:Oral surgery applications prioritize forceps durability and ergonomic handle design for operator fatigue reduction.
- Diagnostic Procedures:Mirror and probe specifications standardize across training and clinical environments with limited differentiation.
Teeth cleaning drives replacement frequency; restorative procedures concentrate premium specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart and Osaka concentrate precision milling capacity for turbine handpiece interfaces and tungsten carbide inserts. Dental clinics across Germany, the United States, and Japan drive procurement standardization under tightening ISO 13485 and FDA reprocessing mandates. Regulatory divergence between the EU Medical Device Regulation and US FDA pathways is fragmenting supplier compliance strategies.
United States
Dental service organizations in Texas and Florida consolidate procurement across multi-site networks, unbundling after-sales service from hardware contracts. FDA 510(k) clearance pathways and updated reprocessing guidance elevate demand for certified stainless steel instruments with traceability systems. California and New York state-level dental amalgam separator rules force instrument selection protocol variations.
Germany
Stuttgart-based manufacturers anchor European production of precision-milled working ends for restorative suites. EU Medical Device Regulation Class I reclassification tightens post-market surveillance and clinical evidence requirements for reusable instruments. Baden-Württemberg industrial clusters respond by consolidating SKU portfolios and accelerating single-use instrument line development.
Japan
Osaka-region production clusters concentrate turbine handpiece interface manufacturing for premium consumption. PMDA quality system requirements align with ISO 13485 mandates, reinforcing captive heat-treatment capabilities. Tokyo dental clinics absorb ceramic-coated bur volumes as adhesive dentistry expands precision tolerance demands.
India
Dental schools in Mumbai and Delhi generate concentrated bulk contracts for standardized training kits with multi-year replacement schedules. CDSCO medical device regulations tighten quality system documentation for imported instruments. Maharashtra-based distributors serve as procurement intermediaries for clinic networks standardizing across North and West India.
China
NMPA medical device registration requirements elevate barrier-to-entry for foreign instrument suppliers while domestic producers scale economy-tier output. Yangtze River Delta manufacturing clusters supply stainless steel diagnostic mirrors and scalers to Southeast Asian export markets. Shanghai dental clinics absorb growing volumes of tungsten carbide inserts as adhesive dentistry workflows proliferate.
Dental Hand Tools Market Vendor Landscape
Global majors compete with regional champions across quality certification and captive manufacturing capabilities. The supplier base stratifies into three tiers: integrated multinationals with in-house heat-treatment and finishing operations; mid-scale specialists competing on ergonomic R&D and economy-tier fabricators serving price-sensitive procurement in emerging markets. Dominant competitive moves include backward integration into precision milling and strategic partnerships with dental service organizations for multi-site logistics.
Among Germany-based fabricators, KaVo Group anchors the turbine handpiece interface segment. Dentsply Sirona occupies a position exemplifying vertical integration across milling and finishing operations. Hu-Friedy represents the ergonomic specialization archetype, competing on R&D intensity in handle geometries for extended clinical use.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Hu-Friedy |
| KaVo Group |
| Integra LifeSciences |
| 3M Company |
| Kerr Corporation |
| Planmeca |
| Henry Schein |
| Brasseler |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists in Baden-Württemberg and Osaka anchor pricing discipline through captive heat-treatment assets, insulating premium tiers from commodity stainless steel volatility while compressing margin pools on economy-grade diagnostic mirrors.
Pricing Analysis
Input-cost pass-through from nickel and cobalt alloy markets intensifies pricing pressure on mid-tier scalers and curettes. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified German instruments from Chinese economy output. Price differentiation rests on certification grade and after-sales service bundling. Dental service organizations exhibit lowest price sensitivity due to consolidated volume contracts, while independent Mumbai clinics drive hardest bargain on training kit procurement.
Supply Chain Analysis
Single-source vulnerability sits with Stuttgart-region precision milling capacity for tungsten carbide inserts. Manufacturing clusters in Germany, Japan, and the United States dominate turbine handpiece interface production. Raw material dependencies center on medical-grade stainless steel alloys, cemented carbide powders, and rhodium coating substrates. Supply chain risk runs through regulatory restriction as EU MDR Class I reclassification forces SKU consolidation. Distribution runs through dental service organization procurement hubs in Texas and Florida, with Henry Schein and regional distributors serving fragmented clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Dental Hand Tools Market functions as a stable compounder, with infection control protocol tightening across North American and European clinics driving predictable replacement cycles regardless of macroeconomic cycles.
For Market Incumbents: Anchor market position through backward integration into precision milling operations and ISO 13485 certification depth. Dentsply Sirona and KaVo Group exemplify this through captive finishing capabilities that protect margin pools against nickel alloy volatility. Prioritize ergonomic R&D in polymer-composite handle geometries to defend against mid-tier specialists eroding surgical suite share. For New Entrants and Emerging Players: E-commerce direct procurement channels offer lowest-friction entry into Indian dental school bulk contracts. White-space concentrates in Mumbai and Delhi training kit standardization, where CDSCO documentation burdens deter established Western suppliers. Target single-use instrument lines under EU MDR reclassification pressure, leveraging aluminum alloy sourcing from Yangtze River Delta clusters. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale ergonomic specialists without captive heat-treatment assets. Long-term viability favors targets with established notified body relationships and dental service organization logistics contracts. Monitor FDA digital health pre-certification pilot expansion as signal for instrument traceability system inflection.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Unlocks EU MDR compliance and German clinic procurement eligibility. |
| Captive Heat-Treatment Capacity Addition | Insulates margin pools from nickel alloy spot price volatility. |
| Dental Service Organization Partnership | Secures multi-site Texas and Florida network standardization contracts. |
| Single-Use Instrument Line Development | Captures EU MDR Class I reclassification-driven demand migration. |
| Ergonomic Handle Geometry R&D Program | Addresses operator fatigue in extended oral surgery procedures. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged dental clinic procurement managers, GPO contracts administrators, biomedical engineers at sterilization departments, and regulatory affairs leads at Stuttgart and Osaka manufacturers. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and customs trade data for medical-grade alloy imports. Bottom-up instrument shipment analysis triangulated against top-down dental clinic spending estimates.
Segment-weighting approach distributed value across material tiers, end-user concentration, and application intensity. The analytical framework modeled product type, material specification, customer category, and procedure application dimensions across the projection horizon. CAGRs derived from replacement cycle frequency analysis and adhesive dentistry workflow expansion rates. Forecast inputs incorporated ISO 13485 certification penetration curves and dental service organization consolidation velocity.
The model assumes a particular technology adoption path; alternative pathways for ceramic-coated bur displacement of tungsten carbide would alter the outlook. Forecasts reflect assumptions about regulatory timeline adherence and alloy price stabilization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Inlays and Onlays Market
Dental Devices
Dental Suction Systems Market
Dental Devices
North America Aligner Sheet Market
Dental Devices
Dental Rapid Prototyping Systems Market
Dental Devices
Dental Carpule Market
Dental Devices
Dental Splints Market
Dental Devices
Saudi Arabia Dental Devices Market
Dental Devices
North America Dental Lasers Market
Dental Devices
North America Dental Lab Market
Dental Devices
Dental Suction Mirror Market
Dental Devices
Global Veterinary Dentistry Instruments and Equipment Market
Dental Devices
Plaque Disclosing Aids Market
Dental Devices
Spain Dental Devices Market
Dental Devices
Australia Dental Devices Market
Dental Devices
Dental CAD/CAM Market
Dental Devices
Dental Crown Removal Market