
 Asia-Pacific Dental Aligners Market | 2026-2036
Asia-Pacific Dental Aligners Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Dental Aligners Market Outlook
Direct-to-clinic distribution is narrowing as Asian manufacturers build proprietary digital platforms. Angelalign Technology leverages its domestic cloud-based treatment planning network to control patient acquisition costs across mainland China. Align Technology sustains premium positioning through intensive R&D spending on AI-driven tooth-movement algorithms. Institut Straumann competes by anchoring its aligner portfolio to its existing implantologist relationships across Southeast Asia.
Dental aligners are removable, transparent thermoplastic appliances engineered from multi-layer polyethylene terephthalate glycol (PETG) or polyurethane materials, fabricated via stereolithography or fused deposition modeling to exert calibrated orthodontic force on specific tooth surfaces. Their primary commercial purpose is to correct malocclusion and spacing irregularities without fixed brackets or wires. Clear aligners dominate value generation due to superior patient acceptance and higher per-case pricing, while 3D printing technology captures the fastest expansion as chairside production reduces laboratory turnaround from weeks to hours. Digital scanning displaces traditional polyvinyl siloxane impressions across orthodontist and general dentist channels, compressing initial appointment duration and improving fit accuracy.
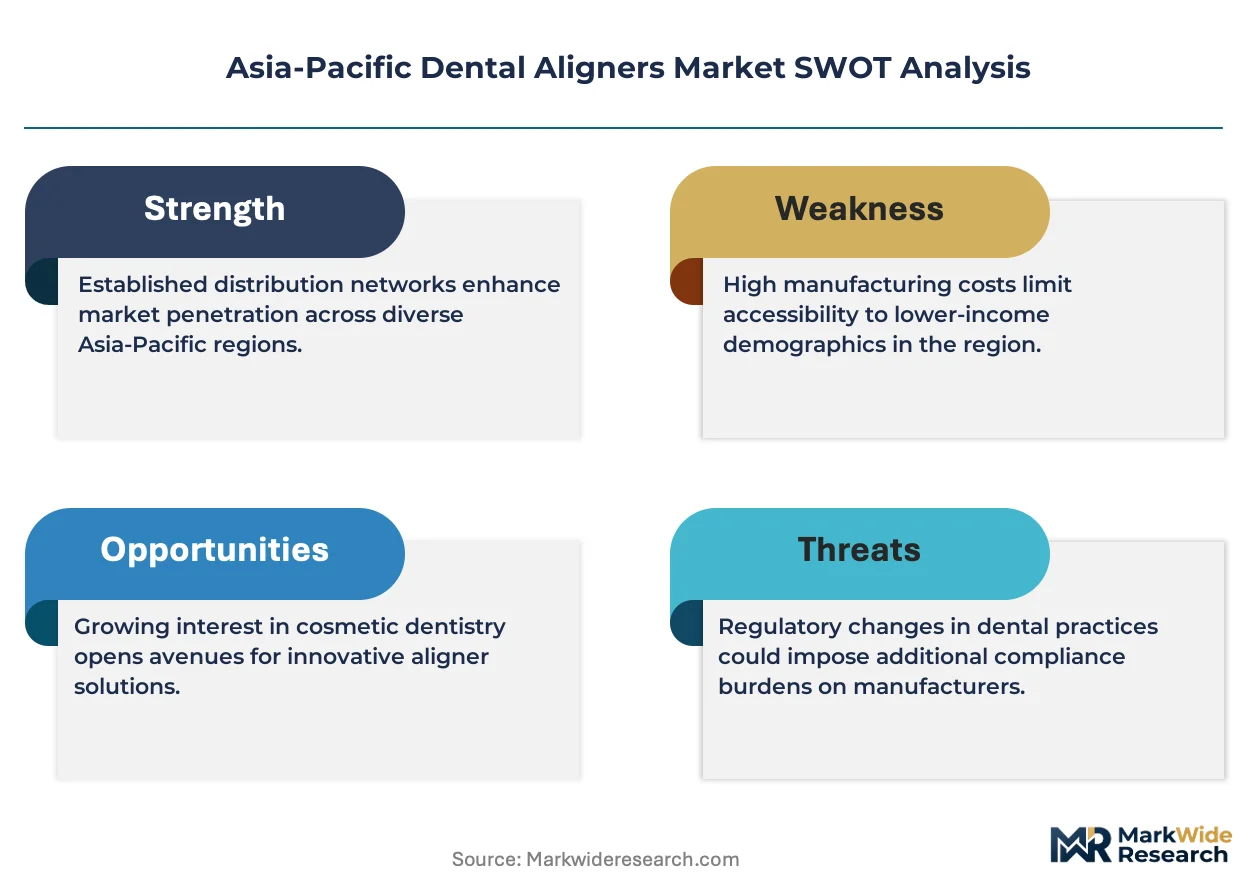
China's NMPA regulates dental aligners as Class II medical devices, requiring biocompatibility testing and clinical validation for domestic market entry. Japan's PMDA enforces equivalent standards through its QMS ordinance, while Australia's TGA mandates inclusion in the Australian Register of Therapeutic Goods before commercial distribution. India's CDSCO has aligned with ISO 13485 for polymer-based orthodontic device manufacturing. Stakeholders must monitor how each national regulator treats AI-generated treatment plans versus clinician-directed protocols, as this classification divergence will determine platform licensing costs and liability structures.
Market Dynamics
Cloud-based treatment planning platforms are consolidating patient acquisition control across Asia-Pacific, compressing distributor margins while forcing orthodontists to choose between proprietary ecosystems and open-architecture workflows. This infrastructure shift is redrawing competitive boundaries faster than manufacturing scale advantages can accumulate.
Growth Catalysts
- Teenage aesthetic demand:Adolescents and young adults in China's tier-one cities now initiate orthodontic consultations at rates triple those of prior generations, creating a self-reinforcing social norm around transparent correction.
- CDSCO quality alignment:India's tightened polymer-based medical device norms are accelerating ISO 13485 certification among domestic manufacturers, filtering out subscale competitors and legitimizing premium pricing for compliant products.
- Chairside 3D printing:Stereolithography systems deployed directly in orthodontic practices are collapsing laboratory turnaround from weeks to hours, converting general dentists into aligner prescribers without specialist referral.
Market Restraints
- PETG supply concentration:Multi-layer thermoplastic raw material production clusters in East Asian chemical hubs, exposing aligner manufacturers to input cost volatility when regional petrochemical capacity tightens.
- NMPA clinical validation:China's Class II medical device pathway requires biocompatibility testing and documented tooth-movement efficacy, extending domestic market entry timelines for novel appliance designs.
- Fixed appliance substitution:Lingual brackets and ceramic brackets retain cost advantages for complex malocclusion cases, limiting clear aligner penetration in severe correction segments.
Strategic Opportunities
- Southeast Asia penetration:Vietnam, Indonesia, and the Philippines maintain orthodontist-to-population ratios below one-tenth of Japan's level, offering first-mover positioning for digital platform entrants.
- AI-generated planning:Automated tooth-movement algorithms are hybridizing with clinician oversight protocols, creating regulatory arbitrage opportunities where jurisdictions classify AI-assisted versus clinician-directed plans differently.
- Straumann's implantologist channel:Existing relationships between implant specialists and premium oral appliance providers across Thailand and Malaysia create ready-made distribution for aligner portfolio extensions.
Industry Challenges
- Digital workflow integration:Orthodontic practices must retrain staff on intraoral scanning and cloud-based case submission, creating implementation friction that slows platform adoption despite clinical benefits.
- Cross-border data governance:Treatment plans stored on Chinese cloud infrastructure face transfer restrictions under multiple national privacy frameworks, complicating multi-country practice networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Dental Aligners Market |
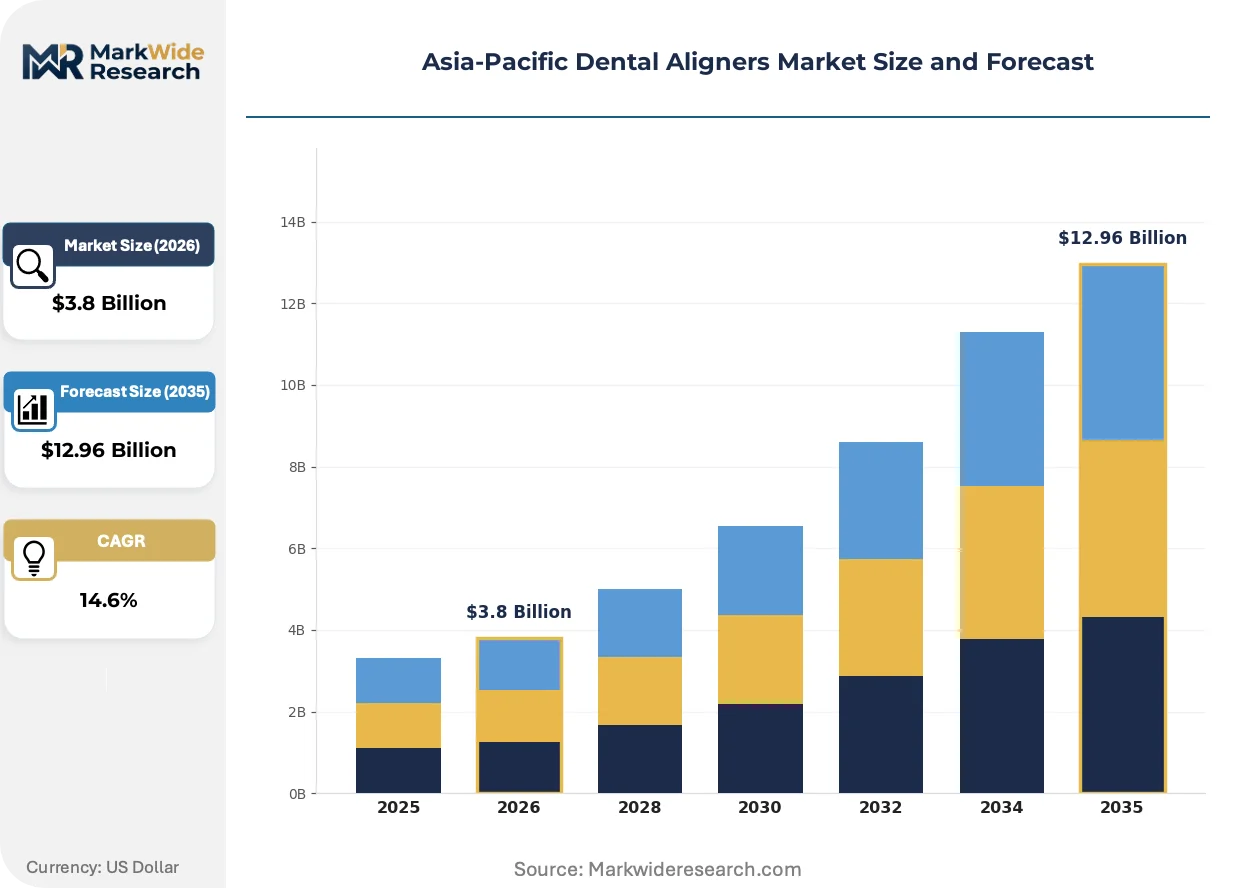
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clear Aligners, Traditional Braces, Lingual Aligners, Retainers End User: Orthodontists, General Dentists, Specialty Clinics, Home Users Technology: 3D Printing, CAD/CAM, Digital Scanning, Photogrammetry Distribution Channel: Online Sales, Direct Sales, Dental Clinics, Retail Pharmacies |
| Companies Covered | Align Technology, Dentsply Sirona, Ormco, Angelalign Technology, 3Shape, Institut Straumann, Envista Holdings, Henry Schein, Ivoclar Vivadent, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Dental Aligners Market Strategic Shifts
Digital scanning infrastructure is compressing initial appointment duration while simultaneously generating proprietary patient datasets that lock practices into specific aligner ecosystems. This dual function is accelerating competitive consolidation around platform owners rather than manufacturing scale leaders.
Multi-layer PETG-PU composite materials are hybridizing with embedded force-calibration layers to deliver staged orthodontic pressure across treatment sequences. High-volume orthodontic groups in Shanghai and Shenzhen are adopting these next-generation thermoplastics at twice the rate of independent practices. The technology is hybridizing manufacturing economics by enabling single-facility production of both standard and complex case aligners without retooling.
Japan's PMDA QMS ordinance now enforces equivalent standards to China's NMPA for polymer-based orthodontic devices, creating regulatory convergence across Northeast Asia. Manufacturers seeking multi-country approval can leverage shared biocompatibility documentation, reducing duplicate testing costs. Smaller domestic Japanese manufacturers are responding by partnering with Chinese digital platform providers rather than building independent cloud infrastructure.
General dentists are displacing specialist orthodontists as the primary aligner prescription channel across Australia's metropolitan corridors. Digital scanning and AI-assisted treatment planning are replacing the diagnostic expertise gap that previously required specialist referral. This channel shift is most visible in Sydney and Melbourne, where dental service organizations now capture majority aligner volume through standardized protocols deployed across general practice networks.
Asia-Pacific Dental Aligners Market Segmentation
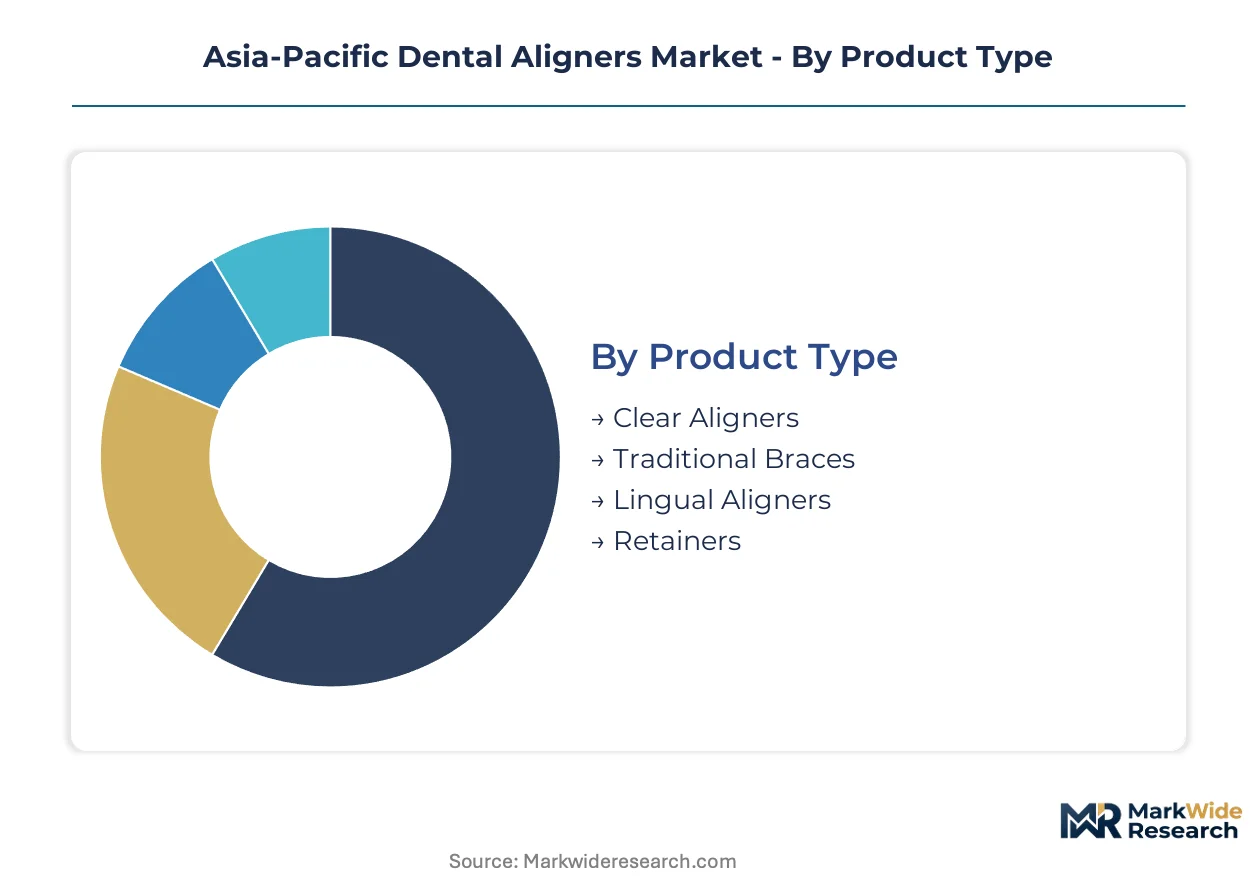
Segmentation in dental aligners determines everything from manufacturing setup to margin structure. Product type dictates material science requirements, while technology choice locks practices into specific ecosystem dependencies. Channel configuration directly shapes patient acquisition economics across Asia-Pacific's heterogeneous regulatory environments.
Product Type:
After-sales service intensity varies dramatically across appliance categories, with removable systems demanding ongoing patient support and fixed alternatives requiring fewer touchpoints post-installation.
- Clear Aligners:Multi-layer polyethylene terephthalate glycol or polyurethane thermoplastics deliver calibrated orthodontic force through staged appliance sequences. Shanghai and Shenzhen's high-volume orthodontic groups adopt next-generation PETG-PU composites at twice independent practice rates, driven by chairside 3D printing integration that collapses laboratory turnaround from weeks to hours.
- Traditional Braces:Stainless steel or ceramic brackets bonded to tooth surfaces with archwire mechanics remain cost-advantaged for complex malocclusion corrections. China's tier-one cities see declining share among teenage aesthetic demand cohorts, though lingual and ceramic variants retain penetration in severe correction segments where clear aligner biomechanics underperform.
- Lingual Aligners:Fixed appliances mounted on tooth interior surfaces address aesthetic concerns without removability compliance risks.
- Retainers:Post-tention appliances prevent orthodontic relapse with lower per-case pricing and minimal active tooth movement.
By volume, clear aligners lead. By growth pace, retainers are gaining share fastest as treatment completion volumes accumulate across Asia-Pacific's expanding installed base.
End User:
Margin profiles diverge sharply across prescriber categories, with specialist orthodontists commanding premium pricing and general dentists competing on accessibility and convenience.
- Orthodontists:Specialist-trained practitioners with advanced biomechanical expertise manage complex malocclusion cases through proprietary digital workflows. Australia's metropolitan corridors show general dentists displacing this channel for standard aligner prescriptions, though severe cases retain specialist concentration.
- General Dentists:Primary care dental providers increasingly prescribe aligners through standardized AI-assisted treatment protocols. Sydney and Melbourne dental service organizations now capture majority volume through intraoral scanning and cloud-based case submission systems that compress initial appointment duration.
- Specialty Clinics:Focused orthodontic facilities with captive laboratory infrastructure.
- Home Users:Direct-to-consumer aligner recipients bypassing professional supervision channels.
General dentists contribute highest patient volume throughput. Orthodontists maintain steepest expansion trajectory as AI-assisted planning extends their case complexity range.
Technology:
Capital deployment requirements separate scalable platform investments from point-solution equipment, with cloud infrastructure locking in recurring revenue streams for technology owners.
- 3D Printing:Stereolithography and fused deposition modeling systems fabricate aligners directly from digital treatment plans. Chairside deployment in orthodontic practices converts general dentists into aligner prescribers without specialist referral, collapsing laboratory turnaround from weeks to hours.
- CAD/CAM:Computer-aided design and manufacturing software generates appliance geometries from intraoral scan data. Angelalign Technology's domestic cloud-based treatment planning network controls patient acquisition costs across mainland China through integrated CAD/CAM workflows.
- Digital Scanning:Intraoral scanners displace polyvinyl siloxane impressions across orthodontist and general dentist channels.
- Photogrammetry:Optical measurement systems capture tooth position data for treatment planning.
Digital scanning dominates installed base. 3D printing is climbing the fastest as chairside production economics improve.
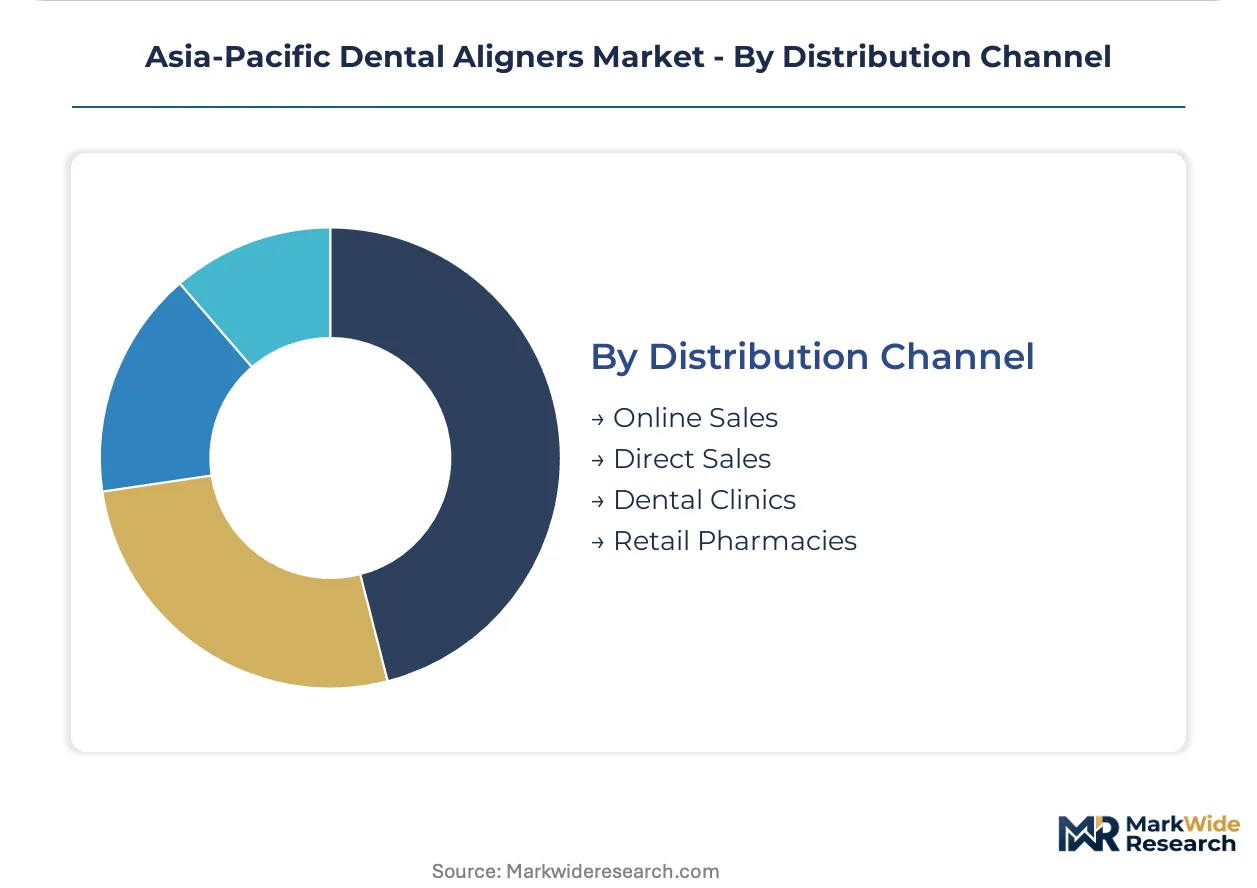
Distribution Channel:
Customer acquisition cost structures vary by channel, with digital platforms compressing distributor margins while forcing ecosystem lock-in decisions on practices.
- Online Sales:Direct-to-consumer digital platforms bypass clinical intermediaries for initial patient screening and appliance delivery. Cross-border data governance complications arise when treatment plans stored on Chinese cloud infrastructure face transfer restrictions under multiple national privacy frameworks.
- Direct Sales:Manufacturer-to-practice relationships with dedicated salesforce coverage. Align Technology sustains premium positioning through intensive R&D spending on AI-driven tooth-movement algorithms deployed through direct clinical engagement.
- Dental Clinics:Traditional point-of-care distribution through orthodontic and general dental practices.
- Retail Pharmacies:Over-the-counter retail channels with limited clinical integration.
Dental clinics retain highest transaction volume. Online sales show steepest expansion trajectory as Asian manufacturers build proprietary digital platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in China's tier-one cities at levels triple those achievable in India's emerging metro corridors, reflecting infrastructure maturity gaps that reshape manufacturer investment sequencing across the region.
China
Teenage aesthetic demand in Shanghai and Shenzhen now initiates orthodontic consultations at rates triple prior generations, creating self-reinforcing social norms around transparent correction. The NMPA regulates dental aligners as Class II medical devices, requiring biocompatibility testing and clinical validation for domestic market entry. High-volume orthodontic groups in Beijing and Guangzhou adopt next-generation PETG-PU composites at twice independent practice rates, driven by chairside 3D printing integration.
Japan
Specialist orthodontists retain case complexity authority even as digital scanning penetrates general dental channels across Tokyo and Osaka metropolitan corridors. The PMDA enforces equivalent standards to China's NMPA through its QMS ordinance for polymer-based orthodontic devices, creating regulatory convergence that reduces duplicate testing costs. Smaller domestic manufacturers in Nagoya and Fukuoka respond by partnering with Chinese digital platform providers rather than building independent cloud infrastructure.
India
CDSCO tightened medical device quality norms for polymer-based dental appliances, accelerating ISO 13485 certification among domestic manufacturers and filtering out subscale competitors. Mumbai and Delhi-NCR dental service organizations capture growing aligner volume through standardized protocols deployed across general practice networks. The regulatory alignment legitimizes premium pricing for compliant products while exposing residual players to compliance-driven consolidation.
Australia
General dentists displace specialist orthodontists as the primary aligner prescription channel across Sydney and Melbourne metropolitan corridors, where dental service organizations now capture majority volume. The TGA mandates inclusion in the Australian Register of Therapeutic Goods before commercial distribution, creating a controlled pathway for platform entrants. Digital scanning and AI-assisted treatment planning replace the diagnostic expertise gap that previously required specialist referral.
Southeast Asia
Vietnam, Indonesia, and the Philippines maintain orthodontist-to-population ratios below one-tenth of Japan's level, offering first-mover positioning for digital platform entrants. Thailand's implant specialist networks anchor premium oral appliance distribution through existing relationships between specialists and providers. Bangkok and Kuala Lumpur emerge as early concentration points for cloud-based treatment planning platform deployment.
Asia-Pacific Dental Aligners Market Competitive Environment
Platform owners and manufacturing-scale specialists split the market along ecosystem-control versus production-efficiency lines. Cloud-based treatment planning infrastructure is consolidating patient acquisition control, compressing distributor margins while forcing orthodontists to choose between proprietary ecosystems and open-architecture workflows. Three archetypes dominate: domestic digital platform operators with captive cloud infrastructure, multinational R&D-intensive technology licensors, and implantology-anchored diversified dental groups. Competitive moves concentrate on M&A to secure digital workflow integration and strategic partnerships to penetrate general dentist channels.
Among multinational technology developers, Align Technology and Institut Straumann occupy positions at opposite ends of the channel strategy spectrum. Angelalign Technology exemplifies the domestic platform archetype through its China-centric cloud infrastructure. These three anchors illustrate how geographic origin and legacy business model shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| Align Technology |
| Dentsply Sirona |
| Ormco |
| Angelalign Technology |
| 3Shape |
| Institut Straumann |
| Envista Holdings |
| Henry Schein |
| Ivoclar Vivadent |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in China's PETG resin production clusters is compressing raw material contract rates while simultaneously allowing tier-one aligner manufacturers to extend payment terms to downstream dental service organizations, tightening working capital cycles across the value chain.
Pricing Analysis
The customization-premium spread separates standard appliance sequences from complex malocclusion configurations requiring staged force-calibration layers. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by ISO 13485 certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because domestic Chinese manufacturers are absorbing margin erosion to capture volume share. General dentist channels exhibit highest price sensitivity due to standardized protocol deployment, while specialist orthodontist networks maintain lowest sensitivity through case complexity premiums.
Supply Chain Analysis
Extended payment terms from East Asian petrochemical suppliers now stretch to 90-120 days for volume purchasers, easing working capital pressure on aligner fabricators. Raw material production draws from China, South Korea, and Japan for multi-layer PETG-PU composites, with stereolithography resin formulations resting on German and Japanese specialty chemical inputs. Single-source vulnerability concentrates in East Asian chemical hubs when regional capacity tightens. Distribution runs through direct manufacturer-to-practice relationships with cloud-based platform intermediation displacing traditional dental distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment creates durable barriers: NMPA Class II validation timelines and ISO 13485 certification requirements lock in compliant incumbents while filtering subscale competitors.
For Market Incumbents: Entrench cloud infrastructure ownership to capture patient acquisition economics before open-architecture workflows fragment platform control. Anchor backward integration into PETG-PU composite manufacturing to defend margin position against raw material volatility. Prioritize NMPA and PMDA regulatory dossier maintenance as emerging entrants face extended clinical validation timelines.
For New Entrants and Emerging Players: Mid-market general dentist networks in Vietnam, Indonesia, and the Philippines represent the most penetrable entry point given orthodontist-to-population ratios below one-tenth of Japan's density. AI-assisted treatment planning protocols without captive cloud infrastructure offer lowest-capital go-to-market positioning. Partner with existing Chinese digital platform providers rather than building independent infrastructure.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-based treatment planning platform operators with captive CAD/CAM workflows. Long-term viability favors manufacturers with dual regulatory approval across NMPA and PMDA jurisdictions. The signal to monitor is chairside 3D printing adoption velocity in general dentist channels as an inflection indicator for manufacturing scale requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Platform Integration | Angelalign's domestic infrastructure locks in patient acquisition costs across tier-one Chinese cities. |
| Regulatory Certification Investment | ISO 13485 alignment filters subscale Indian competitors while legitimizing premium pricing. |
| Chairside 3D Printing Deployment | Stereolithography systems in orthodontic practices collapse laboratory turnaround from weeks to hours. |
| AI-Assisted Treatment Planning | Automated tooth-movement algorithms hybridize with clinician oversight to extend case complexity range. |
| Southeast Asia Market Entry | Vietnam and Indonesia's low orthodontist density offers first-mover positioning for digital platforms. |
Study Parameters
Cross-validation between primary interviews with orthodontic specialists, general dentists, and dental service organization procurement managers anchors the qualitative findings against secondary validation from NMPA device registration databases, PMDA QMS ordinance filings, and CDSCO medical device quality circulars. Bottom-up modeling of aligner case volumes by prescriber category triangulates with top-down PETG thermoplastic consumption estimates across Asia-Pacific manufacturing clusters.
Calibration against historical NMPA approval timelines and chairside 3D printing adoption curves shapes the analytical framework across the analysis window. Segmentation dimensions include product type, end-user channel, technology deployment, and distribution configuration. CAGRs derive from patient consultation initiation rates, regulatory pathway duration assumptions, and digital scanning penetration curves by metropolitan corridor.
Macroeconomic conditions sit as an overlay; deviation in Chinese consumer discretionary spending or regional petrochemical capacity utilization would shift the trajectory. Forecasts reflect documented assumptions about regulatory treatment of AI-generated versus clinician-directed protocols. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Global Dental Restorative Market
Dental Devices
India Dental Devices Market
Dental Devices
Intraoral Dental Sensors Market
Dental Devices
Guided Biofilm Therapy Market
Dental Devices
Prophy Dental Handpiece Market
Dental Devices
Dental Composite Resin Filling Market
Dental Devices
Dental Handpieces Market
Dental Devices
Global Dental Lasers Market
Dental Devices
Americas Acrylic Teeth Market
Dental Devices
Dental Implant Motors Market
Dental Devices
Netherlands Dental Devices Market
Dental Devices
Dental Caries Market
Dental Devices
Dental Erbium Lasers Market
Dental Devices
Canada Dental Devices Market
Dental Devices
Digital Facebow Market
Dental Devices
Global Dental Turbine Market