
 Sperm Processing Media Market | 2026-2036
Sperm Processing Media Market Size, Share, and Industry Trends Forecast 2026-2036
Sperm Processing Media Market Analysis
Buyer concentration among fertility clinics is recalibrating as independent reproductive medicine centers consolidate into multi-site networks across Western Europe. Cooper Surgical Fertility Solutions leverages its integrated distribution through IVF clinic partnerships to sustain volume leadership in buffered salt solutions. FUJIFILM Irvine Scientific anchors North American supply through cGMP-compliant manufacturing facilities. Vitrolife differentiates via proprietary protein-free formulations that command premium positioning in Scandinavian markets.
Sperm processing media comprises sterile, pH-balanced formulations designed to maintain motility, viability, and membrane integrity during washing, capacitation, and cryopreservation procedures, typically containing HEPES or MOPS buffers alongside energy substrates such as pyruvate and lactate. Cryoprotectants represent the fastest-expanding product type as vitrification protocols displace slow-freeze methods in high-throughput fertility laboratories. In vitro fertilization applications capture the dominant value share, while artificial insemination segments face margin compression from commoditized buffer formulations. Fertility clinics as an end-user channel concentrate procurement power through group purchasing organizations, redirecting volume toward manufacturers with validated cold-chain logistics.
The FDA enforces 21 CFR Part 1271 human cells and tissues regulations that classify sperm processing media as minimally manipulated HCT/Ps, while the EU MDR reclassifies certain assisted reproductive technology media as Class IIa devices requiring notified body certification. Japan's PMDA maintains distinct pharmaceutical-grade standards for sperm preparation media used in clinical applications, creating separate compliance pathways for exporters. Stakeholders must monitor evolving harmonization between ISO 13485 quality management requirements and national pharmacopeial monographs to anticipate registration timelines and supply qualification barriers.
Market Dynamics
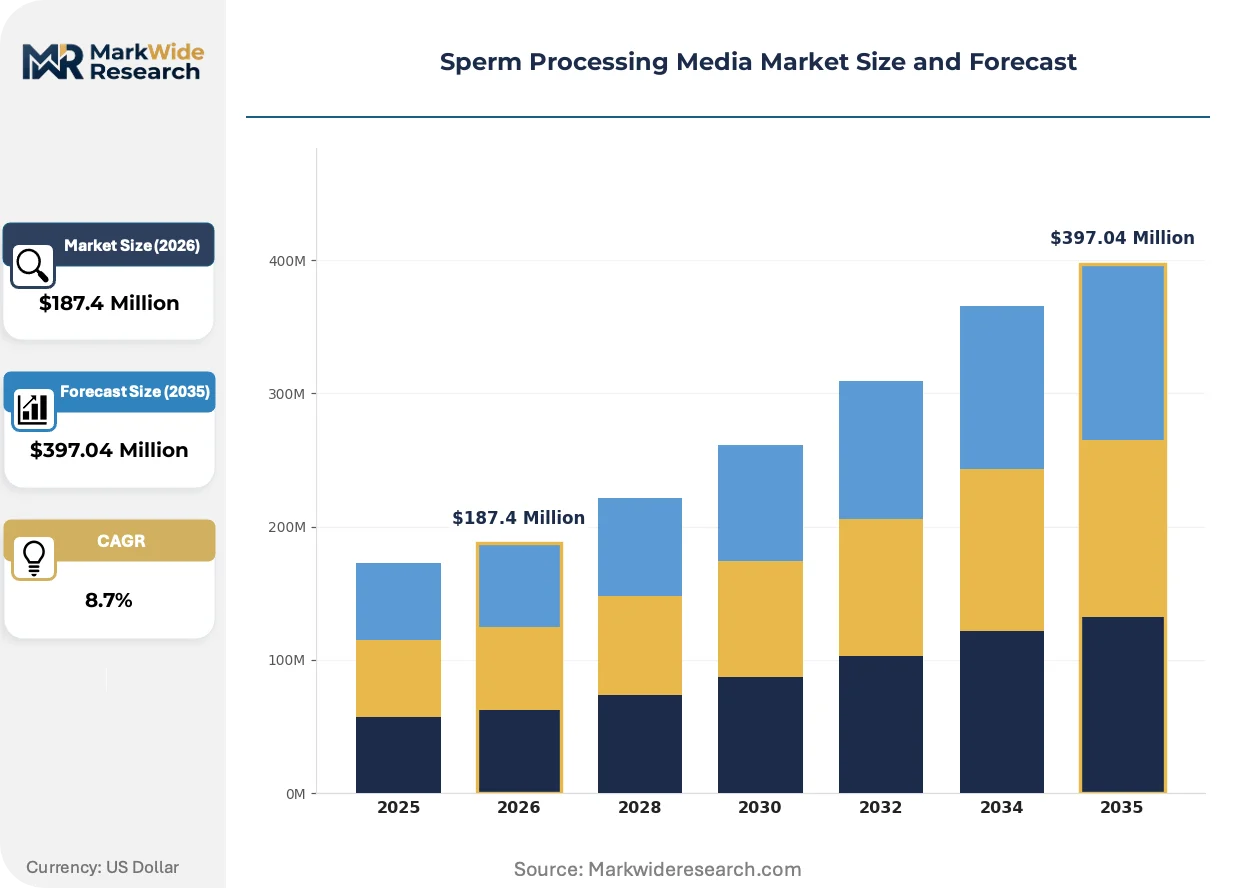
Vitrification protocols are compressing demand for slow-freeze cryoprotectants while EU MDR reclassification forces manufacturers to rebuild quality management systems around notified body certification timelines. This regulatory recalibration intersects with procurement consolidation among multi-site fertility networks.
Growth Catalysts
- EU MDR Class IIa Device Reclassification:Manufacturers investing in ISO 13485 harmonization capture procurement contracts from GPO-affiliated fertility clinics seeking validated supply chains.
- Vitrification Protocol Adoption:High-throughput laboratories in Germany and Spain are converting cryopreservation workflows, expanding addressable volume for specialized cryoprotectant formulations.
- Protein-Free Formulation Demand:Scandinavian regulatory preferences for xeno-free media create premium positioning opportunities for suppliers with serum-free manufacturing capabilities.
Market Restraints
- Human Serum Albumin Price Volatility:Bovine serum supply disruptions from South American processing constraints inflate input costs for traditional protein-supplemented media.
- Notified Body Bottleneck:EU MDR certification queues extend 18-24 months, freezing new product introductions and freezing smaller manufacturers out of clinic procurement cycles.
- Synthetic Surfactant Substitution:Recombinant albumin and polymer-based alternatives threaten conventional HSA-dependent formulation margins.
Strategic Opportunities
- Poland and Czech Republic Clinic Expansion:Cross-border reproductive tourism from Western Europe drives capital investment in Warsaw and Prague fertility centers.
- CE-IVD Self-Test Integration:At-home sperm quality screening kits create downstream consumable pull-through for preparation media in retail pharmacy channels.
- AI-Assisted Sperm Selection Convergence:Computer vision systems for motility analysis require media formulations optimized for automated imaging compatibility.
Industry Challenges
- Embryologist Training Pipeline Constraints:Specialized andrology technologist certification programs in Germany and the Netherlands face enrollment shortfalls against clinic expansion rates.
- Cold-Chain Validation Complexity:Temperature excursion documentation for protein-free formulations demands redundant sensor infrastructure and real-time monitoring investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sperm Processing Media Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Buffered Salt Solutions, Protein-Free Media, Serum-Based Media, Cryoprotectants Application: In Vitro Fertilization, Artificial Insemination, Semen Analysis, Cryopreservation End User: Fertility Clinics, Research Institutions, Hospitals, Animal Breeding Centers Packaging Type: Plastic Bottles, Ampoules, Pouches, Vials |
| Companies Covered | Cooper Surgical Fertility Solutions, FUJIFILM Irvine Scientific, Vitrolife, HI-TECH SOLUTIONS, Wondersperm, GYNEMED GmbH & Co. KG, gynotec, Cryo-Genie India Pvt. Ltd., Sperm Processor Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sperm Processing Media Market Emerging Trajectories
Formulation chemistry is pivoting toward chemically defined, xeno-free compositions as regulatory scrutiny intensifies on bovine-derived components. Manufacturing scale-up now requires simultaneous compliance with pharmaceutical-grade and medical device quality frameworks.
Time-lapse incubation media is integrating pH-stable buffer systems designed for extended embryo culture without media exchange. Scandinavian fertility networks are adopting these formulations at accelerated rates compared to Southern European clinics. This shift is integrating single-step media protocols that compress laboratory workflow complexity and reduce handling variation.
REACH substance restriction proposals are tightening scrutiny on phthalate-based plasticizers in media contact materials. Manufacturers are reformulating packaging and transfer device compositions to maintain CE marking eligibility. Protein-free media categories face the steepest compliance recertification burdens under these evolving chemical safety frameworks.
Group purchasing organizations are consolidating procurement authority across formerly independent fertility centers in Germany, France, and the United Kingdom. Regional laboratory networks are displacing standalone clinic purchasing, concentrating volume with suppliers offering validated cold-chain logistics and multi-site inventory management. Spain's fertility tourism corridors exhibit the most advanced GPO penetration, with Barcelona and Madrid hubs standardizing on single-source media contracts.
Sperm Processing Media Market Segmentation
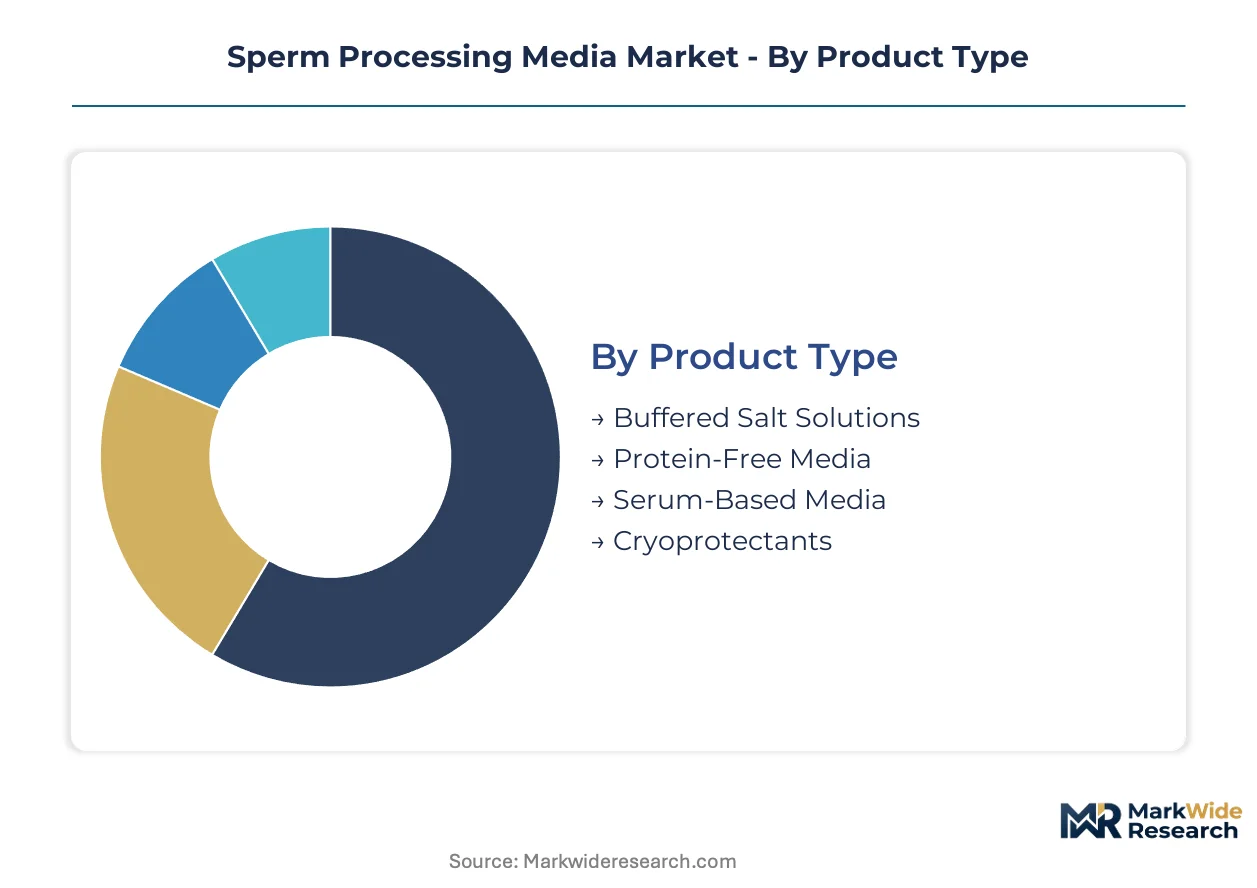
Sperm processing media formulations diverge sharply across clinical workflows, with protein composition and cryopreservation compatibility driving specification requirements. Procurement patterns in fertility networks favor suppliers capable of spanning multiple segment boundaries with harmonized quality systems.
Product Type:
Standardization dominates buffered salt solutions while cryoprotectant formulations demand extensive customization for vitrification protocols.
- Buffered Salt Solutions:HEPES or MOPS-buffered formulations maintain pH stability during sperm washing and capacitation procedures. German university hospital laboratories specify these for high-throughput andrology workflows, though margin compression intensifies from commoditized supply.
- Cryoprotectants:Glycerol-based and non-permeable additive formulations protect cellular membranes during rapid cooling protocols. Spanish fertility tourism hubs in Barcelona and Madrid are converting vitrification workflows fastest, displacing slow-freeze methods and expanding volume for specialized suppliers.
- Protein-Free Media:Chemically defined, xeno-free compositions eliminate bovine serum albumin for regulatory-sensitive applications.
- Serum-Based Media:Human serum albumin-supplemented formulations retain installed base in legacy clinic protocols.
Most installed capacity flows through buffered salt solutions. Expansion is steepest in cryoprotectants.
Application:
Volume concentrates in fertilization procedures while analysis applications command specification premiums for imaging compatibility.
- In Vitro Fertilization:Media formulations support sperm capacitation, selection, and coincubation with oocytes in controlled incubator environments. Multi-site fertility networks in the United Kingdom consolidate procurement for these high-complexity applications, prioritizing suppliers with validated cold-chain documentation.
- Cryopreservation:Sperm banking and fertility preservation protocols require osmotically balanced media with optimized cryoprotectant penetration kinetics. Scandinavian regulatory preferences for xeno-free compositions create premium positioning opportunities distinct from Southern European cost-optimized purchasing.
- Artificial Insemination:Simplified buffer requirements enable multi-source supply with reduced qualification burdens.
- Semen Analysis:Diagnostic-grade media must maintain motility parameters during extended imaging for computer-assisted sperm analysis systems.
Procurement scale peaks with in vitro fertilization. Specification complexity is climbing fastest in cryopreservation.
End User:
Procurement authority is shifting from standalone clinics toward consolidated purchasing entities with multi-site inventory management requirements.
- Fertility Clinics:Specialized reproductive medicine centers perform the majority of sperm processing procedures with direct media consumption. Group purchasing organizations across Germany, France, and the United Kingdom now centralize contracts, redirecting volume toward manufacturers with redundant distribution nodes.
- Research Institutions:Academic andrology laboratories drive formulation innovation through investigator-initiated protocol development.
- Hospitals:General medical centers with fertility units represent secondary volume with standardized purchasing procedures.
- Animal Breeding Centers:Veterinary applications require species-specific osmolarity adjustments and extended shelf-life packaging.
Revenue concentration sits with fertility clinics. Research institutions are gaining procurement influence through protocol standardization initiatives.
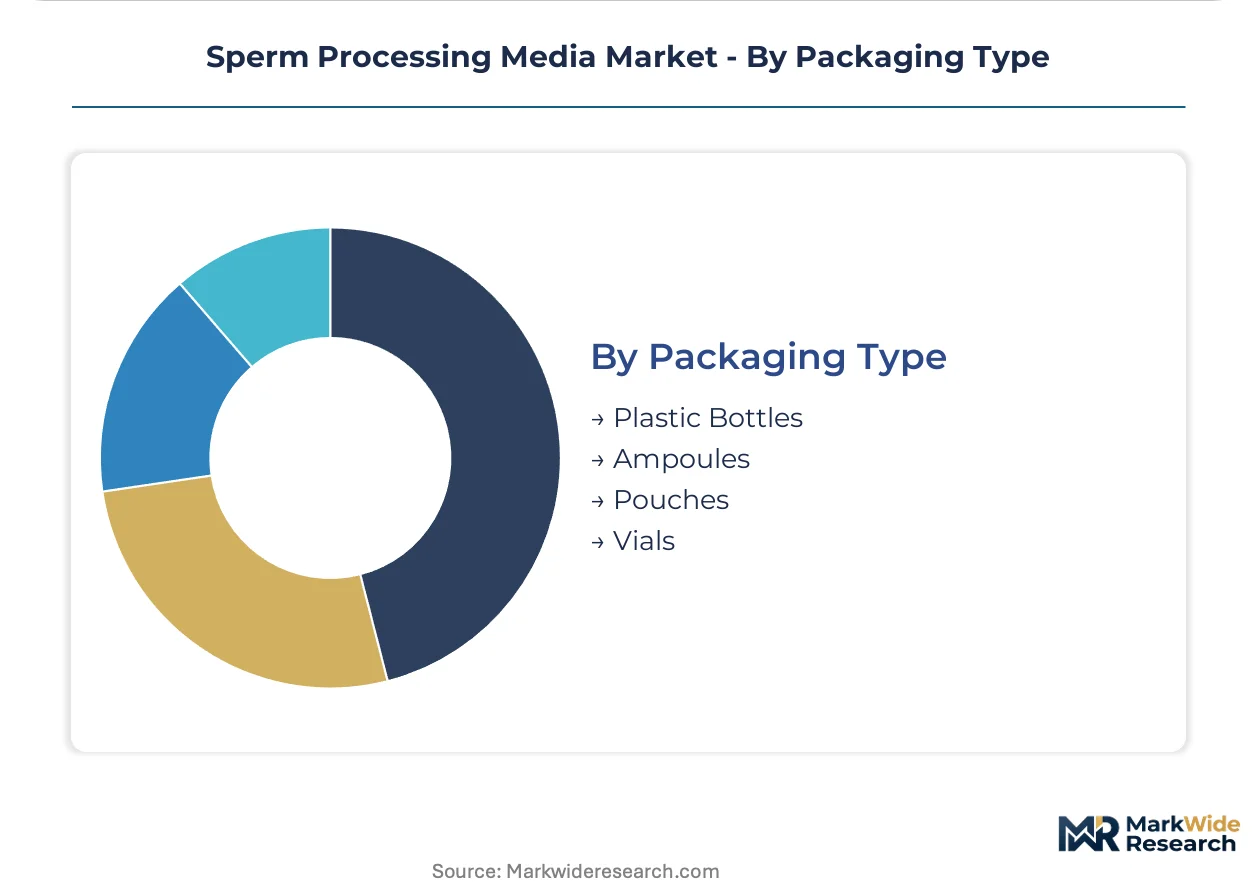
Packaging Type:
Material selection intersects with REACH substance restrictions and cold-chain validation requirements for protein-free formulations.
- Plastic Bottles:High-density polyethylene and polypropylene containers dominate bulk media distribution for high-volume fertility centers. ECHA scrutiny of phthalate-based plasticizers is forcing reformulation of closure systems and contact materials to maintain CE marking eligibility.
- Vials:Cryogenic-grade borosilicate glass or polymer vials withstand ultra-low temperature storage for cryopreserved specimens. Scandinavian networks specify these for single-dose aliquot protocols that eliminate freeze-thaw cycles.
- Ampoules:Glass ampoules provide inert containment for protein-supplemented media with limited shelf stability.
- Pouches:Flexible film packaging reduces shipping cube for distributed clinic networks with limited storage infrastructure.
Distribution volume runs through plastic bottles. Compliance investment is heaviest for vial configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized embryologist training programs in Germany and the Netherlands anchor European technical capacity, while cross-border reproductive tourism redistributes demand toward Central European fertility hubs.
Germany
University hospital andrology laboratories in Heidelberg and Münster drive specification requirements for protein-free formulations. The country's national pharmaceutical regulator enforces pharmaceutical-grade standards for clinical sperm preparation media. Berlin-Brandenburg fertility networks consolidate procurement through group purchasing organizations, redirecting volume toward suppliers with ISO 13485 harmonization.
Spain
Barcelona and Madrid fertility tourism corridors exhibit the most advanced GPO penetration, standardizing on single-source media contracts for vitrification workflows. The EU MDR Class IIa device reclassification forces manufacturers to rebuild quality management systems around notified body certification timelines. Andalusian clinics in Málaga and Seville attract cross-border patients from Northern Europe, expanding addressable volume for specialized cryoprotectant formulations.
United Kingdom
Multi-site fertility networks in London and Manchester consolidate procurement for high-complexity IVF applications, prioritizing suppliers with validated cold-chain documentation. The Medicines and Healthcare products Regulatory Agency maintains distinct compliance pathways for assisted reproductive technology consumables. Scotland's academic andrology laboratories in Edinburgh drive formulation innovation through investigator-initiated protocol development.
Sweden
Scandinavian regulatory preferences for xeno-free media create premium positioning opportunities distinct from Southern European cost-optimized purchasing. The Swedish Medical Products Agency enforces stringent quality benchmarks for protein-free formulations. Stockholm and Gothenburg fertility centers adopt time-lapse incubation media with pH-stable buffer systems at accelerated rates compared to continental clinics.
Poland
Cross-border reproductive tourism from Western Europe drives capital investment in Warsaw fertility centers, expanding laboratory capacity for sperm processing procedures. The country's national pharmaceutical regulator aligns with EU MDR timelines for medical device certification. Kraków and Wrocław clinics standardize procurement on buffered salt solutions for high-throughput andrology workflows.
Sperm Processing Media Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across a market structure consolidating around procurement authority held by multi-site fertility networks. Three strategic archetypes dominate: integrated life science conglomerates with broad reproductive health portfolios, specialized assisted reproductive technology consumables manufacturers with cGMP-compliant facilities, and regional distributors capturing clinic procurement through validated logistics infrastructure. Competitive moves center on ISO 13485 quality management harmonization and cold-chain validation investments that satisfy group purchasing organization qualification requirements.
Within the integrated conglomerate tier, Cooper Surgical Fertility Solutions and FUJIFILM Irvine Scientific exemplify scale-driven positioning through IVF clinic partnerships and North American manufacturing infrastructure respectively. Vitrolife occupies a specialist position representing premium-tier protein-free formulation capabilities. Among Germany-based fabricators, GYNEMED GmbH & Co. KG anchors regional supply relationships with university hospital laboratories. HI-TECH SOLUTIONS and Wondersperm exemplify mid-tier specialists competing on protocol customization for high-throughput laboratory workflows.
| Leading Market Players |
|---|
| Cooper Surgical Fertility Solutions |
| FUJIFILM Irvine Scientific |
| Vitrolife |
| HI-TECH SOLUTIONS |
| Wondersperm |
| GYNEMED GmbH & Co. KG |
| gynotec |
| Cryo-Genie India Pvt. Ltd. |
| Sperm Processor Pvt. Ltd. |
| Others |
Supply Flow & Price Mechanics
Specialized embryologist certification programs in Germany and the Netherlands anchor labor-cost differentials that widen pricing-tier spreads across European fertility networks. Premium protein-free formulations command substantial markups over commoditized buffered salt solutions as clinic procurement consolidates through group purchasing organizations.
Pricing Analysis
Service bundling versus unbundled media supply splits procurement contracts between comprehensive laboratory partnerships and transactional volume discounts. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification grade and cold-chain validation depth. Cost compression in standard buffered salt solutions is intensifying because multi-site fertility networks leverage consolidated purchasing power. Standalone clinics exhibit highest price sensitivity, while university hospital laboratories prioritize specification compliance over unit economics.
Supply Chain Analysis
Reverse-logistics infrastructure for temperature-excursion documentation and cryoprotectant returns feeds from redundant sensor networks and real-time monitoring investments. Manufacturing concentrates in Germany, Sweden, and the United States, with cGMP-compliant facilities anchoring pharmaceutical-grade output. Raw material dependencies center on HEPES and MOPS buffers, glycerol cryoprotectants, and recombinant albumin substitutes. Single-source vulnerability around notified body certification queues creates qualification bottlenecks. Distribution runs through validated cold-chain logistics providers serving multi-site fertility networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through protein-free formulation premiums displacing human serum albumin-dependent legacy products. Cost-down drivers in synthetic surfactant chemistry enable tier-upgrading without proportional input inflation.
For Market Incumbents: Deploy ISO 13485 harmonization investments to capture GPO-affiliated fertility clinic contracts before notified body certification queues clear. Consolidate procurement relationships with German university hospital laboratories through proprietary protein-free formulations. Deepen backward integration into recombinant albumin production to buffer against bovine serum supply disruptions from South American processing constraints.
For New Entrants and Emerging Players: The premium-economy price-point gap in cryoprotectant formulations opens white-space targeting of Spanish fertility tourism corridors converting vitrification workflows. Poland and Czech Republic clinic expansion driven by cross-border reproductive tourism presents the most penetrable geography. CE-IVD self-test integration through retail pharmacy channels offers a distinct go-to-market angle bypassing consolidated GPO gatekeepers.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier specialists with cGMP manufacturing capabilities but limited GPO contract penetration. Long-term viability over a five-to-ten-year window hinges on protein-free formulation portfolios aligned with Scandinavian regulatory preferences. Target acquisition archetypes include German fabricators with university hospital laboratory relationships. Monitor REACH substance restriction timelines on phthalate-based plasticizers as an inflection indicator for packaging reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR Class IIa device reclassification forces notified body certification rebuilds for market access. |
| Protein-Free Formulation Development | Scandinavian regulatory preferences for xeno-free media create premium positioning in Stockholm and Gothenburg. |
| Cold-Chain Logistics Partnership | Validated temperature-controlled distribution satisfies group purchasing organization qualification requirements. |
| Backward Integration into Synthetic Surfactants | In-house production of polymer-based alternatives buffers margins against human serum albumin price volatility. |
| AI-Assisted Sperm Selection Compatibility | Media formulations optimized for automated imaging align with computer vision system adoption in high-throughput laboratories. |
Methodological Framework
Bottom-up fertility clinic procurement modeling reconciled against top-down cryoprotectant manufacturing capacity tracking forms the analytical core. Primary interviews with embryologists, andrology laboratory directors, GPO contracts managers, and regulatory affairs specialists at notified bodies combined with secondary validation from EMA guidance documents, EU MDR technical files, ISO 13485 certification registries, and hospital procurement databases. Triangulation across stakeholder inputs and published regulatory frameworks ensures segment-level accuracy.
Input-output matrices map cryoprotectant formulation demand against vitrification protocol adoption rates across product type, application, end user, and packaging format dimensions. CAGRs derive from modeled procedure volumes and per-procedure media consumption intensities across the projection horizon. Industry-specific forecast inputs include EU MDR certification queue durations and REACH substance restriction implementation timelines.
Caveats apply where notified body bottleneck extensions or bovine serum supply disruptions could materially shift the outlook. Practitioners should monitor ECHA phthalate restriction proposals and synthetic surfactant substitution rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Petri Dishes Market
Medical Supplies
Freeze Drying Masks Market
Medical Supplies
Nonwoven Surgical Drapes Market
Medical Supplies
Medical Instruments Disinfection Market
Medical Supplies
Syringes and Cannulas Market
Medical Supplies
Mortuary Bags Market
Medical Supplies
Tracheostomy Securement Tapes Market
Medical Supplies
Smear Mask Market
Medical Supplies
Italy Ostomy Care and Accessories Market
Medical Supplies
Europe Medical Gloves Market
Medical Supplies
Plastic Medicine Spoons Market
Medical Supplies
Yankauer Suction Tips Market
Medical Supplies
Amniotic Membrane Market
Medical Supplies
Powder-Free Disposable Medical Gloves Market
Medical Supplies
Foley Trays Market
Medical Supplies
Asia-Pacific Ostomy Drainage Bags Market