
 Self-Ligating Bracket Sales Market | 2026-2036
Self-Ligating Bracket Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Ligating Bracket Sales Market Analytics
Digital treatment planning subscriptions is repositioning what orthodontists purchase, bundling hardware with software-defined archwire sequencing. 3M leverages its Unitek platform to anchor recurring revenue alongside bracket hardware. Ormco Corporation specializes in Damon system education to sustain practitioner loyalty and reduce switching costs. Dentsply Sirona controls digital workflow integration, extending its position from intraoral scanners into bracket placement robotics.
Self-ligating brackets are orthodontic appliances featuring integrated clip or slide mechanisms that eliminate elastic or wire ligatures, reducing friction between archwire and bracket slot to enable faster tooth movement with fewer adjustments. They are manufactured from stainless steel, titanium, or polycrystalline alumina through metal injection molding or ceramic pressing processes, serving orthodontic practices seeking reduced chair time and improved patient comfort. Metal brackets dominate unit volume due to durability and cost efficiency, while ceramic and aesthetic variants command premium positioning among adult patient segments. Orthodontists represent the core end user concentration, though general dentists are expanding into aligner-bracket hybrid treatments through distributor-supported training programs.
FDA 510(k) premarket notification requirements and EU MDR conformity assessment shape product development timelines and clinical evidence thresholds for bracket manufacturers entering major markets. ISO 13485 quality management certification remains mandatory for supply relationships with hospital purchasing groups and national health systems. Stakeholders must monitor evolving reimbursement codes for accelerated orthodontic protocols and the integration of artificial intelligence into bracket prescription selection.
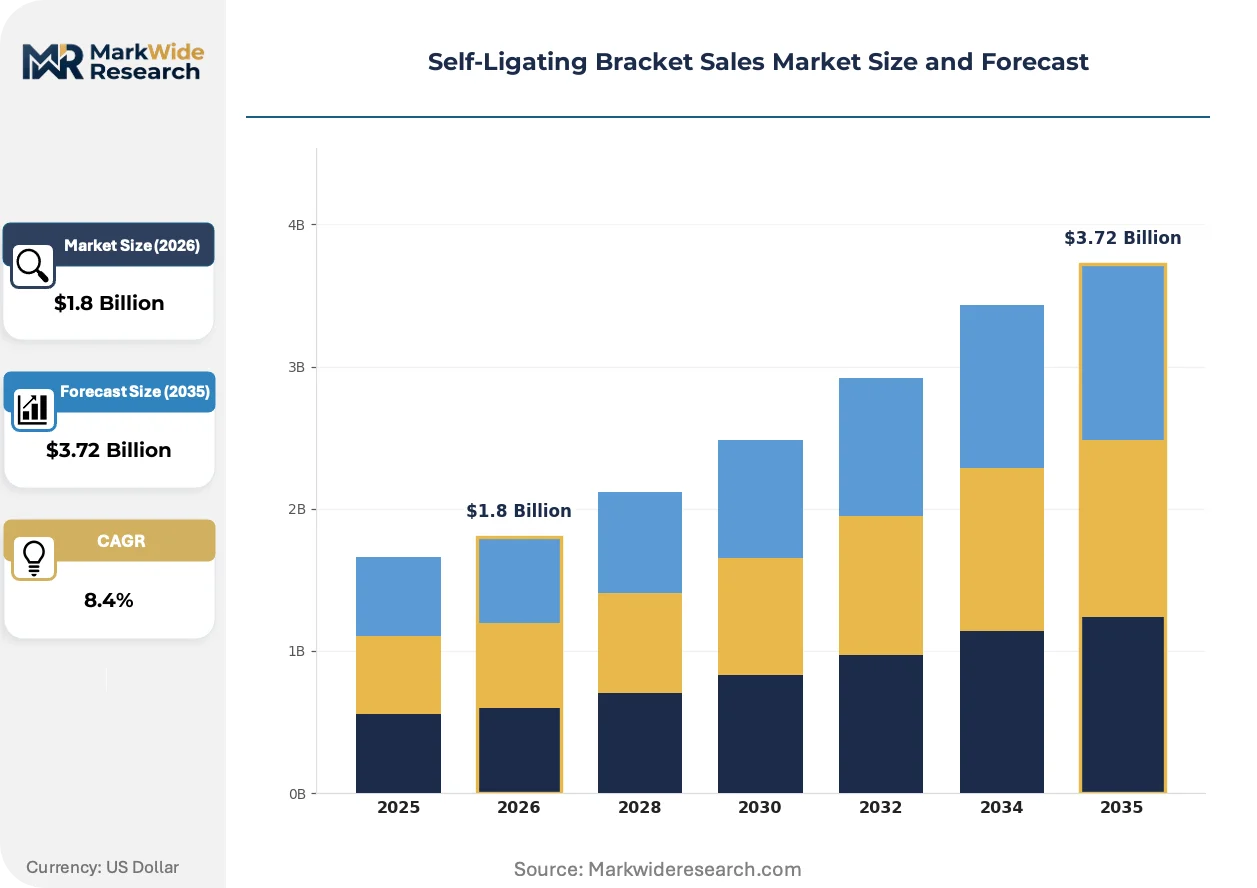
Market Dynamics
Digital workflow integration is compressing traditional bracket procurement cycles as orthodontists bundle hardware purchases with intraoral scanner ecosystems and treatment planning software subscriptions.
Growth Catalysts
- EU MDR streamlining:CE marking pathways under the updated Medical Device Regulation are accelerating product entry for manufacturers targeting Western European orthodontic practices.
- Adult aesthetic demand:Ceramic self-ligating variants are capturing premium positioning among adult patient segments seeking reduced visibility during treatment.
- Metal injection molding:Advanced manufacturing processes are enabling complex clip geometries that reduce friction coefficients and improve clinical outcomes.
Market Restraints
- Titanium supply concentration:Raw material sourcing for premium bracket alloys remains concentrated among limited specialty metal suppliers.
- FDA 510(k) evidence thresholds:Clinical documentation requirements for novel self-ligating mechanisms extend development timelines and raise capital barriers.
- Clear aligner substitution:Direct-to-consumer orthodontic platforms are capturing mild-to-moderate malocclusion cases previously treated with fixed appliances.
Strategic Opportunities
- Japan reimbursement expansion:National health insurance frameworks are progressively covering advanced bracket technologies for adolescent patients.
- AI-driven prescription selection:Machine learning algorithms integrated into digital treatment planning are creating demand for smart brackets with embedded sensors.
- General dentist channel:Distributor-supported training programs are opening hybrid aligner-bracket protocols to primary dental care providers.
Industry Challenges
- Orthodontic technician scarcity:Specialized training for digital bracket placement robotics is outpacing available certification programs.
- ISO 13485 audit complexity:Quality management recertification for multi-site manufacturing is consuming compliance resources.
- Legacy practice management integration:New digital workflows require costly upgrades to patient record systems and scheduling platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Ligating Bracket Sales Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal, Ceramic, Aesthetic, Lingual Application: Orthodontics, Dental Clinics, Hospitals, Private Practices End User: Orthodontists, General Dentists, Pediatric Dentists, Dental Technicians Distribution Channel: Direct Sales, Online Sales, Distributors, Dental Supply Companies |
| Companies Covered | 3M, Ormco Corporation, Dentsply Sirona, American Orthodontics, Rocky Mountain Orthodontics, G&H Orthodontics, TP Orthodontics, Henry Schein, GC Orthodontics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Ligating Bracket Sales Market Evolving Landscape
Orthodontic hardware is converging with software-defined treatment protocols, reshaping how practitioners evaluate and procure bracket systems.
Passive slide mechanisms with integrated nickel-titanium springs are rewriting friction dynamics in archwire engagement. Orthodontic private practices across North America are adopting these systems to reduce appointment frequency and chair time. The technology is compressing traditional adjustment intervals from four to six weeks toward eight to ten week cycles.
EU MDR conformity assessment procedures are elevating clinical evidence requirements for bracket manufacturers seeking CE marking. Post-market surveillance obligations now mandate systematic collection of real-world performance data. Ceramic and aesthetic variants face heightened scrutiny due to fracture-risk documentation requirements.
Subscription bundling is displacing standalone hardware purchasing in premium practice segments. Orthodontists are prioritizing ecosystem compatibility over individual bracket specifications when selecting suppliers. Germany and Japan exhibit the strongest concentration of practices transitioning to bundled procurement models.
Self-Ligating Bracket Sales Market Segmentation
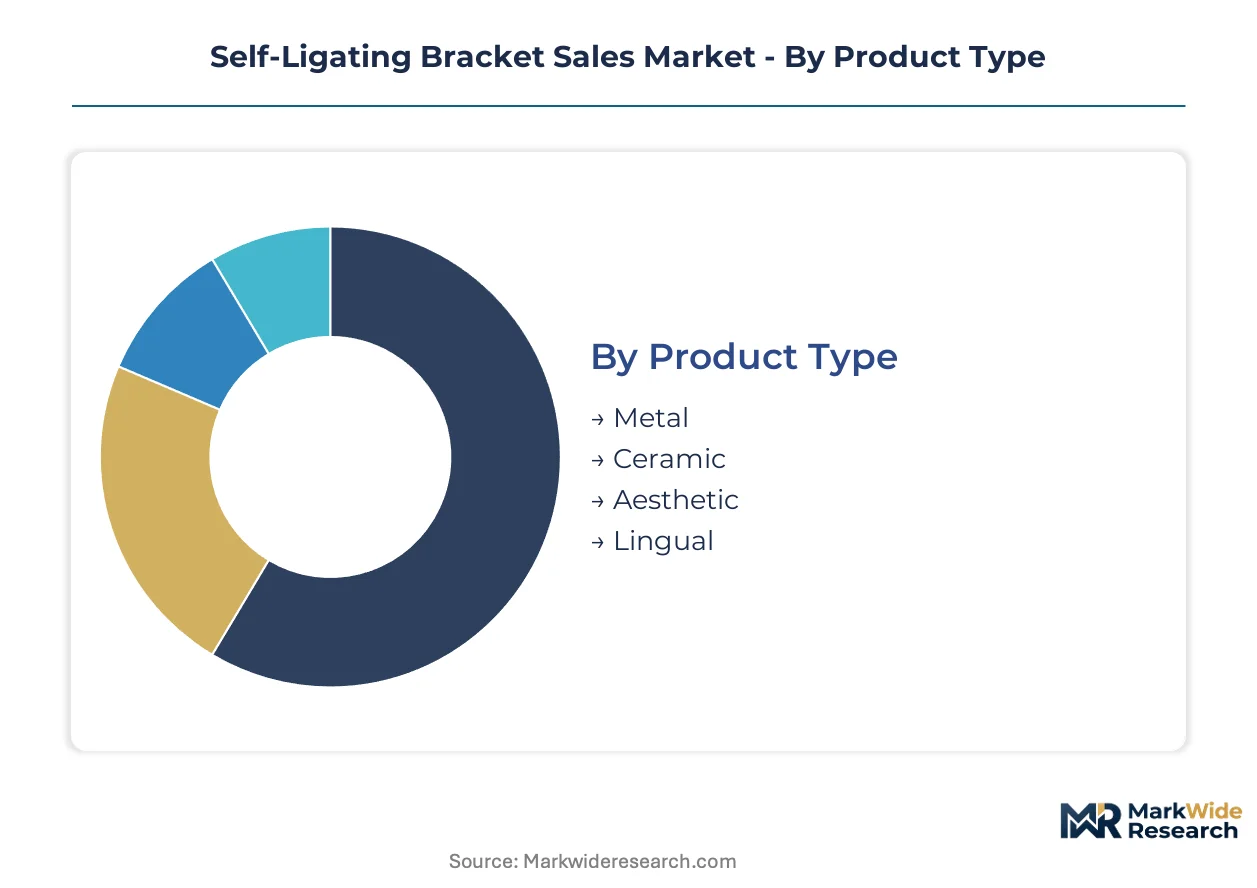
Self-ligating bracket procurement patterns diverge sharply across clinical settings and professional roles. Orthodontists prioritize passive friction reduction and digital workflow compatibility. General dentists entering hybrid aligner-bracket protocols drive demand for simplified, training-supported systems.
Product Type:
FDA 510(k) clearance timelines vary by material composition, with ceramic variants requiring additional fracture-risk documentation. CE marking under EU MDR demands systematic post-market surveillance for all passive clip mechanisms.
- Metal:Stainless steel and titanium alloys manufactured through metal injection molding dominate unit economics. Demand concentrates among high-volume orthodontic practices in the United States seeking durability and chair-time efficiency.
- Ceramic:Polycrystalline alumina pressing yields aesthetic brackets with reduced visibility. Adult patient segments in Germany and Japan absorb premium pricing for discreet treatment options.
- Aesthetic:Composite and polymer-ceramic hybrids target appearance-conscious demographics.
- Lingual:Custom-fabricated brackets bonded to tooth interiors serve specialized orthodontic protocols.
Leading the category by volume: Metal. Expanding most quickly: Ceramic.
Application:
Procurement authority shifts with practice scale, from hospital purchasing groups to independent clinician decision-making.
- Orthodontics:Dedicated specialty practices drive specification-setting for passive self-ligating systems. North American orthodontic groups bundle hardware with intraoral scanner ecosystems and treatment planning subscriptions.
- Dental Clinics:Multi-specialty facilities integrate bracket placement with general restorative workflows. Western European dental clinics prioritize CE-marked systems with streamlined conformity assessment.
- Hospitals:Academic medical centers anchor clinical trial recruitment and resident training.
- Private Practices:Solo and small-group orthodontists represent the price-sensitive volume tier.
Orthodontics commands procurement value. Dental clinics gain share fastest.
End User:
Training intensity and prescription autonomy separate professional categories.
- Orthodontists:Board-certified specialists control premium system selection and drive manufacturer education programming. United States orthodontists anchor demand for Damon and Unitek platform ecosystems.
- General Dentists:Primary care providers expanding into fixed appliances require distributor-supported certification. Japan's national health insurance expansion for adolescent brackets opens this channel.
- Pediatric Dentists:Early-intervention specialists prescribe interceptive appliances.
- Dental Technicians:Laboratory professionals fabricate custom lingual and indirect bonding setups.
Orthodontists retain specification authority. General dentists show steepest expansion trajectory.
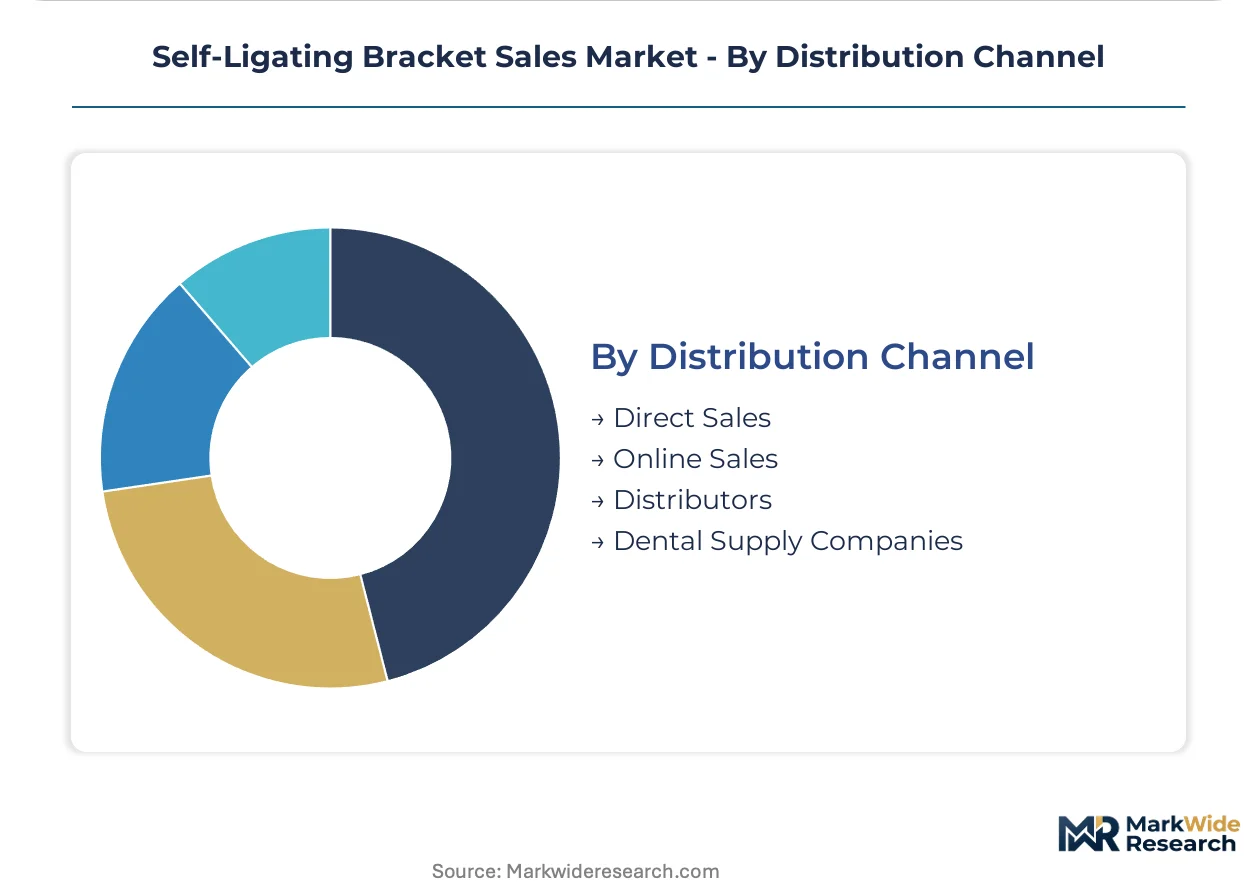
Distribution Channel:
Channel selection reflects practice digital maturity and inventory management preferences.
- Direct Sales:Manufacturer field representatives secure multi-year supply agreements with large orthodontic groups. 3M and Ormco deploy dedicated sales engineers for Unitek and Damon platform adoption.
- Online Sales:E-commerce portals serve smaller practices with standardized metal bracket SKUs. German and Japanese orthodontic supply platforms aggregate CE-marked and PMDA-registered inventory.
- Distributors:Regional dental supply houses provide local inventory and credit terms.
- Dental Supply Companies:Henry Schein and Patterson Dental integrate bracket procurement with practice management software.
Direct sales capture premium system volume. Online sales climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Germany and Japan where precision metalworking traditions serve orthodontic hardware production, while consumption tilts toward the United States where orthodontic private practice density drives procurement volume.
United States
FDA 510(k) premarket notification pathways streamline entry for passive self-ligating systems, reducing clearance timelines for manufacturers with predicate device references. Orthodontic private practices in Texas and California anchor hardware procurement, bundling bracket purchases with intraoral scanner ecosystems from Dentsply Sirona and 3M.
Germany
EU MDR conformity assessment elevates clinical evidence thresholds for ceramic bracket variants, mandating systematic post-market surveillance. Metal injection molding specialists in Baden-Württemberg supply complex clip geometries to Western European orthodontic practices seeking reduced friction coefficients.
Japan
PMDA marketing approval frameworks align with national health insurance reimbursement expansion for adolescent bracket treatments. Tokyo and Osaka orthodontic groups drive demand for aesthetic ceramic variants, absorbing premium pricing for discreet fixed appliances.
China
NMPA registration requirements for imported orthodontic devices channel foreign manufacturer partnerships through domestic distributors. Yangtze River Delta fabrication clusters produce stainless steel bracket components for cost-sensitive export markets.
United Kingdom
CE marking recognition under retained EU law post-Brexit maintains regulatory continuity for bracket imports from continental suppliers. London and Southeast England orthodontic practices concentrate procurement of subscription-bundled digital treatment planning platforms.
Self-Ligating Bracket Sales Market Competitive Landscape
Top-tier vendors anchor platform ecosystems, while mid-scale specialists compete on material differentiation and regional distributor relationships. The vendor base stratifies across integrated dental conglomerates, orthodontic-focused manufacturers, and regional supply houses. Three archetypes dominate: ecosystem bundlers anchoring digital workflow integration, friction-reduction specialists commanding premium positioning, and volume fabricators serving price-sensitive practice tiers. M&A activity concentrates on digital workflow assets, while strategic partnerships link bracket manufacturers with intraoral scanner platforms.
Within the ecosystem bundler tier, 3M and Dentsply Sirona represent integrated positioning, each anchoring hardware-software combinations that reshape orthodontist procurement patterns. Ormco Corporation exemplifies the orthodontic specialist archetype, occupying a position where practitioner education programs sustain platform loyalty and reduce switching costs. These three companies sit within distinct competitive vectors—industrial conglomerate, dental technology integrator, and category-dedicated manufacturer—reflecting how market structure rewards different scale and specialization profiles.
| Leading Market Players |
|---|
| 3M |
| Ormco Corporation |
| Dentsply Sirona |
| American Orthodontics |
| Rocky Mountain Orthodontics |
| G&H Orthodontics |
| TP Orthodontics |
| Henry Schein |
| GC Orthodontics |
| Others |
Value Network & Pricing Analysis
Metal injection molding adoption across German and Japanese fabrication clusters is compressing unit production costs while simultaneously concentrating supply relationships among ISO 13485-certified specialists. This technological shift rewards bracket manufacturers with captive molding capacity while marginalizing smaller players dependent on third-party foundry services.
Pricing Analysis
Margin tightening in economy-tier metal brackets reflects Yangtze River Delta fabrication overcapacity and aggressive export pricing from Chinese stainless steel component suppliers. Three-tier pricing structure across premium ceramic, standard titanium, and economy stainless steel levels dominates procurement, with ISO 13485 certification tier and archwire sequencing software bundling as primary differentiation drivers. Cost-down pressure accelerates as direct-to-consumer aligner platforms capture mild malocclusion cases previously treated with fixed appliances. Private practices in the United States exhibit highest price sensitivity, while Japanese orthodontic groups absorb premium positioning for aesthetic variants.
Supply Chain Analysis
CE marking and FDA 510(k) qualification gating concentrates component sourcing among Baden-Württemberg metal injection molding specialists, Osaka precision titanium processors, and Yangtze River Delta stainless steel fabricators. Raw material procurement draws from specialty nickel-titanium alloy suppliers, polycrystalline alumina ceramic feedstock producers, and medical-grade stainless steel mills. Single-source vulnerability persists in premium titanium clip geometries where only two Japanese suppliers meet PMDA medical device material standards. Distribution runs through Henry Schein and Patterson Dental supply networks, with direct manufacturer sales engineering reserved for Damon and Unitek platform ecosystem adoptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The self-ligating bracket market functions as a cost-of-compliance story where EU MDR post-market surveillance obligations and FDA 510(k) clinical evidence thresholds erect formidable barriers-to-entry that protect incumbent positions. Manufacturers without existing predicate device portfolios or ISO 13485 multi-site certification face capital requirements that deter competitive entry.
For Market Incumbents: Lock in practitioner loyalty through exclusive archwire sequencing software subscriptions that embed bracket specification into digital treatment planning workflows. Deepen backward integration into nickel-titanium alloy processing to insulate margin positions from specialty metal supply concentration. Prioritize CE marking pathway investments for ceramic variants ahead of EU MDR fracture-risk documentation deadline acceleration.
For New Entrants and Emerging Players: The mid-tier pricing gap between premium ceramic brackets and economy stainless steel systems offers white-space targeting for hybrid polymer-ceramic formulations with simplified clip mechanisms. General dentist channels in Japan represent the most penetrable segment given national health insurance reimbursement expansion for adolescent treatments. Pursue distributor-supported certification partnerships rather than direct sales engineering buildouts.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform ecosystem acquisitions by dental technology integrators seeking bracket hardware to anchor intraoral scanner workflows. Long-term viability favors manufacturers with software-defined treatment protocol integration and recurring revenue components alongside disposable hardware. Watch FDA 510(k) clearance velocity for novel passive clip mechanisms as inflection indicator for competitive repositioning potential.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR fracture-risk documentation for ceramic variants secures Western European market access ahead of surveillance mandate expansion. |
| Software Companion Development | Archwire sequencing algorithms bundled with bracket hardware create switching costs that protect specification authority against aligner substitution. |
| Hospital System Partnership | Academic medical center affiliations anchor clinical trial recruitment and resident training pipelines for next-generation bracket adoption. |
| Backward Integration into Alloys | Captive nickel-titanium processing capacity insulates margin positions from Japanese specialty metal supply concentration risks. |
| Reimbursement Strategy | National health insurance code expansion in Japan and Germany accelerates patient access for premium ceramic bracket protocols. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with orthodontic practice owners, biomedical equipment procurement managers, GPO contracts specialists, and dental supply distribution executives. FDA 510(k) premarket notification databases, EU MDR conformity assessment registries, and PMDA marketing approval filings provided regulatory trajectory validation. Orthodontic professional society membership directories and intraoral scanner ecosystem partnership announcements furnished competitive positioning intelligence. Bottom-up bracket unit shipment estimates from fabrication clusters reconciled against top-down orthodontic practice hardware expenditure surveys.
Data-stream reconciliation across supply-side production metrics and demand-side procurement surveys shaped the analytical framework. Segmentation modeling spanned material composition, application setting, professional end-user category, and distribution channel complexity across the projection horizon. CAGRs derived from bracket unit volume trajectories and average selling price evolution by tier, with metal injection molding capacity expansion schedules and clear aligner penetration rates as industry-specific forecast inputs.
Inputs from regulatory filing databases and orthodontic professional society directories were available through the study window; gaps in real-time hospital procurement transaction data introduce uncertainty bands around academic medical center segment estimates. Forecasts reflect documented assumptions regarding EU MDR implementation timelines and Japan reimbursement code expansion velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Implants and Dental Prosthetics Market
Dental Devices
Dental Curing Lights Market
Dental Devices
Intraoral Dental Sensors Market
Dental Devices
Asia-Pacific Dental Aligners Market
Dental Devices
Dental Liners and Bases Market
Dental Devices
Australia Dental Devices Market
Dental Devices
Dental CAD Market
Dental Devices
Europe Dental Implants and Prosthetics Market
Dental Devices
Dental Erbium Lasers Market
Dental Devices
South Korea Dental Devices Market
Dental Devices
Dental Scalers Market
Dental Devices
Dental Suction Systems Market
Dental Devices
Asia Pacific Acrylic Teeth Market
Dental Devices
Chile Dental Market
Dental Devices
Dental 3D Printing Market
Dental Devices
Dental Inlays and Onlays Market