
 Dental Prosthetics Market | 2026-2036
Dental Prosthetics Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Prosthetics Market Intelligence
The consolidation of purchasing power within large dental service organizations is hardening procurement terms for manufacturers. This trend forces suppliers to offer more competitive pricing and integrated service packages to secure large-volume contracts. Straumann Group leverages its premium brand positioning and extensive clinical research to command higher price points in the implant segment. Dentsply Sirona competes through a broad portfolio that encompasses both prosthetic components and the digital equipment used in their design and placement.
Dental prosthetics are custom-fabricated medical devices designed to replace missing teeth or restore damaged tooth structures. These devices are manufactured from biocompatible materials like zirconia or resin composites, often using precision CAD/CAM milling or 3D printing technologies. Their primary purpose is to restore oral function, such as mastication and speech, as well as aesthetic appearance. While implants represent the highest-value product category, crowns and bridges continue to generate significant volume. Material selection is shifting, with zirconia and advanced ceramics displacing traditional metal-based options due to superior aesthetics and biocompatibility.
The market operates under a strict regulatory framework enforced by national and regional health authorities. In the United States, the FDA classifies most prosthetics as Class II medical devices, requiring 510(k) clearance. In Europe, the Medical Device Regulation (MDR) imposes stringent requirements for clinical evidence and post-market surveillance. These regulations ensure patient safety and product efficacy, creating high barriers to entry. Navigating the evolving landscape of digital dentistry versus traditional fabrication methods remains the central strategic decision for laboratories and manufacturers alike.
Market Dynamics
The dental prosthetics market is defined by the tension between traditional analog fabrication and the rapid adoption of digital CAD/CAM workflows. This technological shift alters the competitive basis from manual artistry to digital proficiency, impacting laboratory economics and material science.
Growth Catalysts
- Aging Demographics:The expanding elderly population in developed nations like Japan and Germany directly increases the patient pool requiring restorative dental procedures such as crowns, bridges, and dentures.
- Digital Workflow Adoption:The integration of CAD/CAM systems in dental laboratories and clinics significantly improves the precision, speed, and efficiency of prosthetic fabrication, reducing turnaround times for patients.
- Advanced Materials:The development of high-translucency zirconia and lithium disilicate ceramics provides superior aesthetic and biocompatible alternatives to traditional metal-based restorations, meeting patient demand for natural-looking results.
Market Restraints
- High Capital Costs:The substantial initial investment required for CAD/CAM milling units, 3D printers, and intraoral scanners creates a significant financial barrier for smaller dental laboratories and independent clinics.
- Reimbursement Hurdles:Inconsistent or limited reimbursement from public and private insurers for premium prosthetic options, such as all-ceramic implants, can constrain patient access and limit market penetration.
- Substitution by Preventive Care:Advances in preventive dentistry and oral hygiene products, which reduce the incidence of tooth loss and severe decay, can temper long-term demand for restorative prosthetic solutions.
Strategic Opportunities
- Teledentistry Platforms:Integrating digital impression data with teledentistry platforms enables remote prosthetic design and consultation, expanding market access to patients in rural or underserved geographic areas.
- Emerging Economies:Rising disposable incomes and an increasing focus on aesthetic dental care in countries like Brazil and India present substantial growth opportunities for prosthetic manufacturers and laboratories.
- Customized Implant Abutments:Leveraging 3D printing for patient-specific implant abutments offers improved soft tissue management and aesthetic outcomes, creating a high-value niche beyond standard components.
Industry Challenges
- Digital Skills Shortage:A persistent lack of dental technicians trained in advanced CAD software, digital design principles, and equipment maintenance creates an operational bottleneck for laboratories seeking to scale digital production.
- System Interoperability:A lack of standardization between different manufacturers' digital scanning, design software, and milling systems can lead to workflow inefficiencies and vendor lock-in for dental practices and labs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Prosthetics Market |
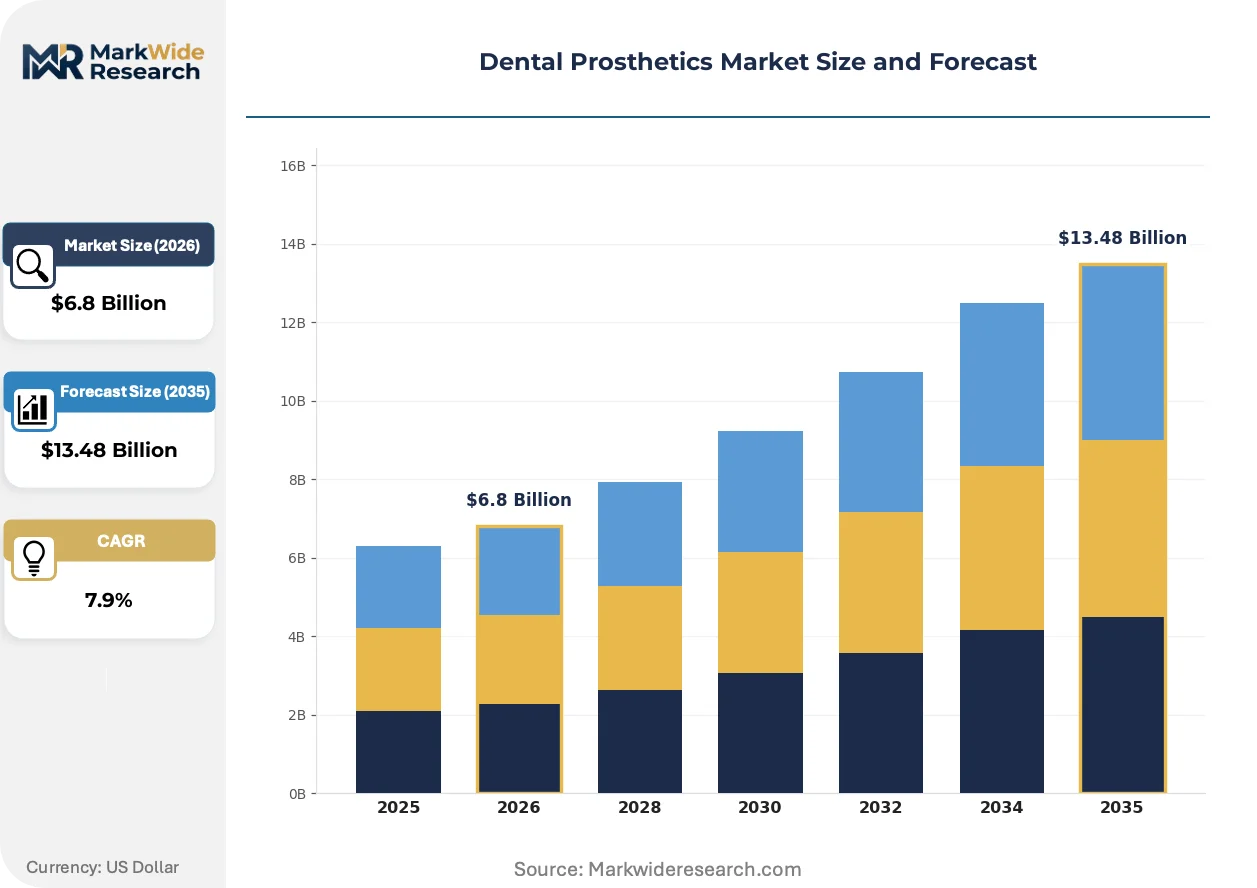
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.48 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implants, Dentures, Crowns, Bridges, Veneers, Inlays Material: Ceramics, Resin Composites, Metals, Zirconia, Acrylics, Polymers Application: Permanent Restoration, Temporary Restoration, Cosmetic Enhancement, Orthodontic Support, Maxillofacial Reconstruction, Pediatric Solutions End User: Dental Laboratories, Private Clinics, Academic Institutions, Hospitals, Specialty Centers, Mobile Clinics |
| Companies Covered | Dentsply Sirona, BioHorizons, Straumann Group, Ivoclar Vivadent, 3M, Nobel Biocare Services, Osstem Implant, MegaGen, Zimmer Biomet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Prosthetics Market Strategic Shifts & Innovations
The evolution from analog craft to digital manufacturing is fundamentally altering the value chain for dental prosthetics. This transition reconfigures the economic and operational relationships between clinicians, laboratories, and material suppliers, prioritizing system integration and digital fluency.
Chairside 3D printing and milling systems enable the fabrication of permanent crowns, inlays, and bridges within a single patient visit. Dental practices are adopting this technology to enhance patient convenience and gain greater control over the final restoration. This trend is decentralizing production from large, centralized labs to the point of care, compressing traditional supply chain timelines.
Europe's Medical Device Regulation (MDR) imposes significantly stricter requirements for clinical evidence, quality management, and post-market surveillance. This forces manufacturers to invest heavily in documentation and traceability, particularly for custom-made devices. The high compliance burden disproportionately affects smaller dental laboratories, which may struggle to meet the new standards for placing products on the EU market.
Patient decision-making is increasingly influenced by aesthetic considerations, driving a preference for metal-free restorations that offer superior biocompatibility and a more natural appearance. This behavioral shift is eroding the market share of traditional porcelain-fused-to-metal (PFM) crowns in favor of monolithic zirconia and glass-ceramic materials. This trend is most prominent within the elective, out-of-pocket cosmetic dentistry sector in North America and Western Europe.
Dental Prosthetics Market Segmentation
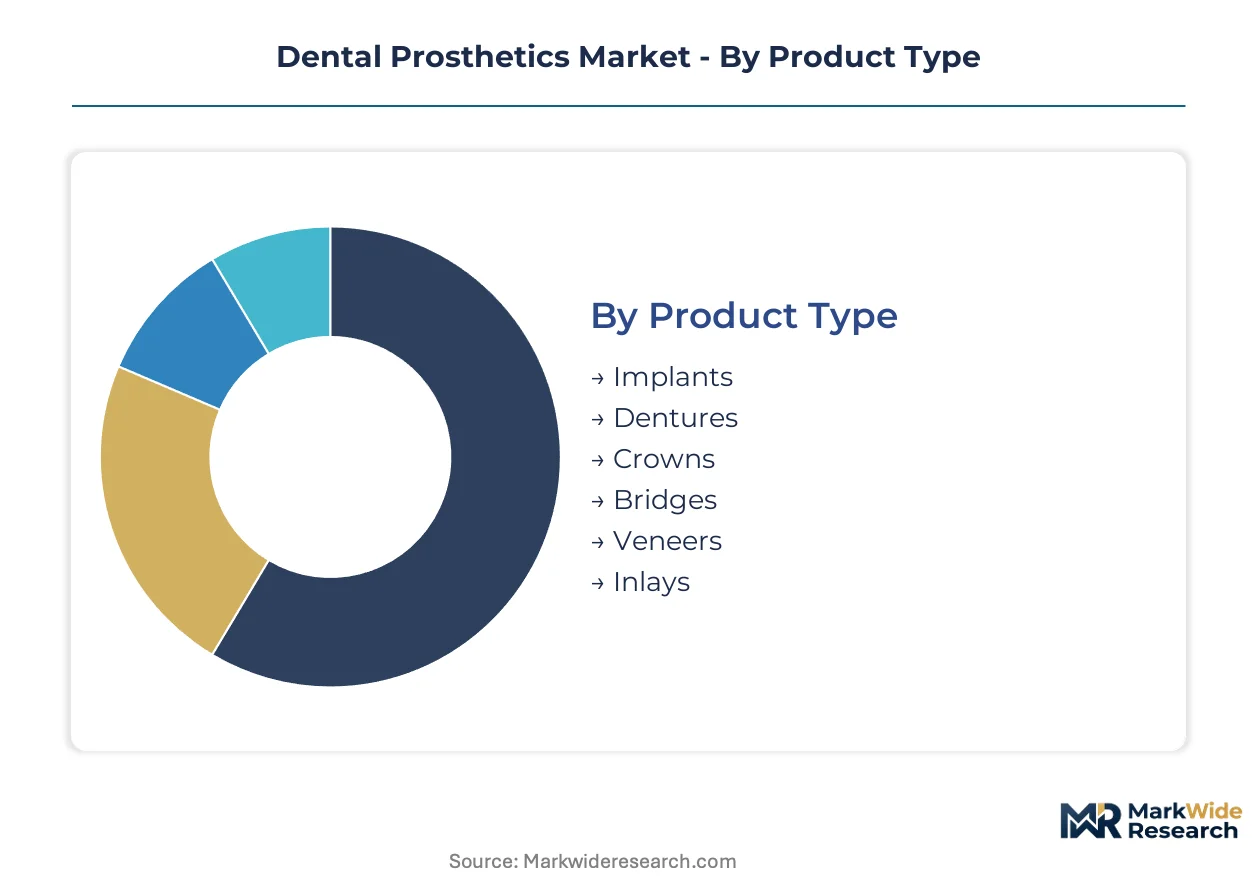
The dental prosthetics market is highly stratified, reflecting diverse patient needs, material science advancements, and fabrication technologies. Understanding these distinct segments allows manufacturers and laboratories to tailor product development and service offerings, optimizing resource allocation.
Product Type:
The customization-versus-standardization spectrum significantly influences product type offerings, with implants requiring highly individualized planning and dentures offering more standardized solutions.
- Implants:These prosthetic devices are surgically placed into the jawbone, serving as artificial tooth roots. Demand for implants concentrates in developed markets like Germany and the United States, driven by high patient expenditure and a focus on long-term oral health solutions.
- Crowns:Dental crowns are custom-fitted caps that cover damaged teeth, restoring their shape, size, strength, and appearance. The aging population in Japan and Europe drives consistent demand for crowns, which benefit significantly from digital CAD/CAM workflows for faster fabrication.
- Dentures:Removable appliances replace multiple missing teeth, supported by surrounding soft and hard tissues.
- Bridges:Fixed prosthetics span the gap created by one or more missing teeth, anchored to natural teeth or implants.
- Veneers:Thin, custom-made shells bond to the front surface of teeth, primarily for cosmetic enhancement.
- Inlays:Indirect restorations fit into a prepared cavity within a tooth, used for conservative repairs of chewing surfaces.
Leading the category by volume: Crowns. Growing fastest: Implants.
Material:
Material selection often reflects a balance between aesthetic demands, mechanical properties, and cost, creating distinct tiers of product performance and price points.
- Zirconia:This ceramic material offers exceptional strength, biocompatibility, and aesthetic translucency for crowns, bridges, and implant abutments. Its use is expanding in North America and Western Europe due to patient preferences for metal-free, natural-looking restorations.
- Resin Composites:Versatile and tooth-colored, these materials are widely used for direct restorations, inlays, and some temporary prosthetics. Their affordability and ease of use make them a staple in emerging economies like India and Brazil.
- Ceramics:These non-metallic, inorganic materials provide excellent aesthetics and biocompatibility, commonly used for crowns and veneers.
- Metals:Alloys like gold, palladium, and nickel-chromium offer high strength and durability, traditionally used for crowns and bridges, though their market share is declining.
- Acrylics:Polymers primarily used for denture bases and temporary prosthetics due to their ease of fabrication and cost-effectiveness.
- Polymers:Advanced polymer materials are gaining traction for temporary restorations and some 3D-printed applications, offering flexibility and lightweight properties.
The shift towards zirconia reflects a strong patient preference for aesthetics and biocompatibility.
Application:
The functional objective of the prosthetic dictates its design and material, ranging from long-term oral health solutions to immediate aesthetic improvements.
- Permanent Restoration:This core application focuses on long-term replacement of missing teeth or damaged tooth structures, aiming for durability and full oral function. Demand for permanent restorations is consistent across all developed markets due to an aging population.
- Cosmetic Enhancement:Procedures primarily address aesthetic concerns, improving the appearance of teeth through veneers, crowns, and teeth whitening. This application expands most quickly in North America and Western Europe, driven by discretionary spending.
- Temporary Restoration:Interim solutions protect prepared teeth and maintain function while permanent prosthetics are being fabricated.
- Orthodontic Support:Prosthetics that assist in tooth movement or retention, often as part of a broader orthodontic treatment plan.
- Maxillofacial Reconstruction:Complex prosthetics used to restore facial and oral structures following trauma, cancer, or congenital defects.
- Pediatric Solutions:Prosthetics specifically designed for children, addressing issues like early tooth loss or developmental anomalies.
Demand here is largely driven by the long-term functional needs of patients.
End User:
The distribution and fabrication model for dental prosthetics varies significantly across end-user types, influencing technology adoption and procurement patterns.
- Dental Laboratories:These facilities specialize in custom fabrication of a wide range of prosthetics, increasingly adopting digital CAD/CAM workflows. Consolidation among dental laboratories in the United States and Europe is reshaping procurement terms for material suppliers.
- Private Clinics:Individual dental practices provide direct patient care, with some integrating chairside CAD/CAM systems for same-day restorations. Patient convenience drives the adoption of chairside solutions in countries like Germany and Canada.
- Hospitals:Medical centers with dental departments handle complex cases, including oral surgery and maxillofacial prosthetics.
- Academic Institutions:Universities and dental schools focus on research, education, and advanced treatment modalities.
- Specialty Centers:Clinics dedicated to specific dental disciplines, such as periodontics or prosthodontics, often utilizing advanced technologies.
- Mobile Clinics:Outreach programs and portable units provide basic dental care and some prosthetic services to underserved populations.
The evolution of dental laboratories is reshaping the competitive landscape through digital integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for dental prosthetics is pronounced in developed economies, with Germany leading in patient expenditure and sophisticated dental care infrastructure. The expanding elderly population in these regions directly increases the patient pool requiring restorative dental procedures.
Germany
Germany's demand for dental prosthetics stems from an aging population and high patient expenditure on restorative procedures. The Medical Device Regulation (MDR) imposes stringent requirements on product efficacy and safety for devices placed on the EU market. Major dental technology clusters in Bavaria and North Rhine-Westphalia drive innovation in CAD/CAM fabrication and material science.
Japan
Japan's expanding elderly population consistently drives demand for crowns and bridges, alongside a preference for advanced ceramic materials. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates dental prosthetics, ensuring product quality and safety. Tokyo and Osaka remain key hubs for advanced dental research and material science development, fostering new aesthetic solutions.
United States
The United States market exhibits high patient expenditure and a strong preference for advanced implant solutions and cosmetic enhancements. The FDA classifies most prosthetics as Class II medical devices, requiring 510(k) clearance for market entry. Innovation centers in California and the Boston area foster the development of digital dentistry technologies and specialized implant systems.
Brazil
Brazil presents substantial growth opportunities due to rising disposable incomes and an increasing focus on aesthetic dental care. ANVISA oversees the regulation of medical devices, including dental prosthetics, to ensure public health and safety. São Paulo serves as a manufacturing hub, attracting investments in dental material production and distribution for the Latin American market.
India
India's market growth is driven by the affordability and ease of use of resin composites for restorations, alongside a rising awareness of dental aesthetics. The Central Drugs Standard Control Organization (CDSCO) regulates medical devices, focusing on quality standards and market access. Emerging digital dentistry centers in Bengaluru and Hyderabad are adopting CAD/CAM workflows for efficiency and customized solutions.
Dental Prosthetics Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue digital dentistry solutions and advanced material innovation. The market structure exhibits a tiered consolidation, with premium brands commanding higher price points and broad-portfolio players competing on comprehensive offerings. Key archetypes include specialized implant manufacturers, integrated digital workflow providers, and material science innovators. Competitive moves focus on portfolio diversification and securing large-volume contracts with dental service organizations.
On the premium-tier vector, Straumann Group exemplifies leadership through extensive clinical research and high-value implant offerings, targeting discerning clinicians and patients who prioritize long-term oral health solutions. Dentsply Sirona occupies a position as a broad-portfolio provider, encompassing both prosthetic components and the digital equipment used in their design and placement, thereby supporting integrated workflows across various practice sizes. Meanwhile, Ivoclar Vivadent sits within the material science innovator archetype, focusing on advanced ceramics and resin composites for superior aesthetic and biocompatible restorations, meeting evolving patient preferences for metal-free options.
| Leading Market Players |
|---|
| Dentsply Sirona |
| BioHorizons |
| Straumann Group |
| Ivoclar Vivadent |
| 3M |
| Nobel Biocare Services |
| Osstem Implant |
| MegaGen |
| Zimmer Biomet |
| Others |
Cost & Logistics Intelligence
Zirconia and advanced ceramic material costs influence the downstream pricing of premium dental prosthetics, directly impacting laboratory margins and patient expenditure across developed markets.
Pricing Analysis
Volume-driven segments like crowns and bridges operate on transactional pricing, while high-value implants command premium margins due to extensive clinical research and brand positioning. Price differentiation stems from material quality, particularly for advanced ceramics, and the level of customization required for patient-specific solutions. Pricing softness is intensifying due to the consolidation of purchasing power within large dental service organizations. Patients seeking elective cosmetic enhancements exhibit lower price sensitivity compared to those relying on public or private insurance reimbursement.
Supply Chain Analysis
Skilled technician availability in Germany and Japan significantly impacts the fabrication capacity for advanced dental prosthetics. The supply chain for high-performance materials draws from specialized chemical manufacturers for zirconia powder and resin composites, often concentrated in Europe and Asia. Regulatory compliance, particularly with Europe's MDR, creates a structural risk by increasing documentation burdens for manufacturers. Downstream distribution runs predominantly through specialized dental distributors and direct channels to dental laboratories and private clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dental prosthetics market is supply-constrained by a persistent digital skills shortage among dental technicians, which props up pricing for advanced CAD/CAM fabricated devices. This bottleneck limits the scalability of digital production workflows across the industry.
For Market Incumbents: Lock in long-term contracts with large dental service organizations to secure volume and maintain market share against emerging entrants offering lower-cost digital solutions. Incumbents should deepen vertical integration into material science, particularly for high-translucency zirconia, to control input costs and material quality. Investing in advanced CAD/CAM training programs for laboratory staff mitigates the digital skills shortage. Extensive clinical research in implantology further reinforces premium brand positioning.
For New Entrants and Emerging Players: A significant price-point gap exists between premium implant solutions and more affordable resin composite restorations, creating an entry point for agile players. New entrants can target customized implant abutments using 3D printing for superior patient-specific aesthetics, a high-value niche. The most penetrable segment is the growing aesthetic dental care market in emerging economies like Brazil. Offering subscription-based digital workflow software to smaller independent clinics provides a compelling go-to-market angle.
For Investors and Strategic Acquirers: Accelerated FDA 510(k) clearances for novel 3D printing materials is the leading indicator that production methods are shifting rapidly. The long-term viability of this market over the next 5-10 years hinges on continuous technological advancements and regulatory adaptation. Acquisition targets should include specialized digital dental laboratories with proprietary CAD/CAM workflows or material science innovators developing advanced biocompatible ceramics. Watch for increased venture capital funding in teledentistry platforms as a signal of market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Digital Workflow Integration | Streamlines prosthetic fabrication for dental laboratories, enhancing precision and reducing turnaround times. |
| Develop Advanced Zirconia Formulations | Meets patient demand for superior aesthetic and biocompatible metal-free restorations in North America. |
| Expand Teledentistry Platform Offerings | Extends market access for prosthetic design and consultation to underserved geographic areas. |
| Secure Large Dental Service Organization Contracts | Guarantees stable volume and strengthens market presence against competitive pricing pressures. |
| Focus on Patient-Specific Implant Abutments | Leverages 3D printing to improve soft tissue management and aesthetic outcomes for clinicians. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing a foundational market overview. Primary interviews with dental laboratory owners, prosthodontists, material scientists, and regulatory affairs specialists offered critical qualitative insights. Secondary validation drew from FDA 510(k) databases, PMDA reports, and peer-reviewed academic journals to ensure data integrity. This approach employed both bottom-up and top-down triangulation to derive robust market estimates.
Market sizing and forecast models were built with granular detail across product type, material, application, end user, and digital workflow adoption. The analytical framework projected market growth across the analysis window by correlating historical trends with future drivers. Compound annual growth rates were derived from a multi-factor regression analysis. Key industry-specific inputs included aging population demographics and CAD/CAM equipment sales data.
Underlying measurement precision varies by segment; established product types like crowns and bridges carry tighter precision than emerging 3D-printed solutions. Forecasts reflect assumptions regarding regulatory stability and technological adoption. Material deviation in European MDR updates or significant CAD/CAM disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
3D-Printed Dental Restoration Market
Dental Devices
Europe Dental Aligners Market
Dental Devices
Turkey CAD/CAM Dental Devices Market
Dental Devices
Intraoral Dental Scanner Market
Dental Devices
Europe CBCT Dental Imaging Market
Dental Devices
Dental Liners and Bases Market
Dental Devices
Dental Articulators Market
Dental Devices
Orthodontics Market
Dental Devices
UAE Dental Devices Market
Dental Devices
Periodontal Scalers and Curettes Market
Dental Devices
Dental Composite Resin Filling Market
Dental Devices
Malocclusion Market
Dental Devices
Dental Devices and Consumables Market
Dental Devices
China Dental Devices Market
Dental Devices
Dental Laboratories Market
Dental Devices
Dental Healing Caps Market