
 Titanium Dental Implants Market | 2026-2036
Titanium Dental Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Titanium Dental Implants Market Intelligence
A shortage of board-certified prosthodontists and oral surgeons is unwinding capacity constraints across implant dentistry. Straumann Holding AG leverages its integrated digital workflow platform to sustain premium positioning in guided surgery. Nobel Biocare anchors European market presence through specialized training academies that deepen clinician loyalty. Zimmer Biomet Holdings, Inc. competes on manufacturing scale across its broad implant portfolio.
Titanium dental implants are biocompatible endosseous fixtures typically composed of commercially pure titanium or Ti-6Al-4V alloy, manufactured through precision machining and surface modification to achieve osseointegration with jawbone tissue. These devices permanently replace missing tooth roots to support crowns, bridges, or dentures. Endosteal implants dominate procedural volume due to decades of clinical validation and established reimbursement pathways. Acid-etched and sandblasted surface treatments command attention for their demonstrated bone-to-implant contact rates. Full arch restoration represents the fastest-growing application as edentulous patients seek fixed alternatives to removable prostheses.
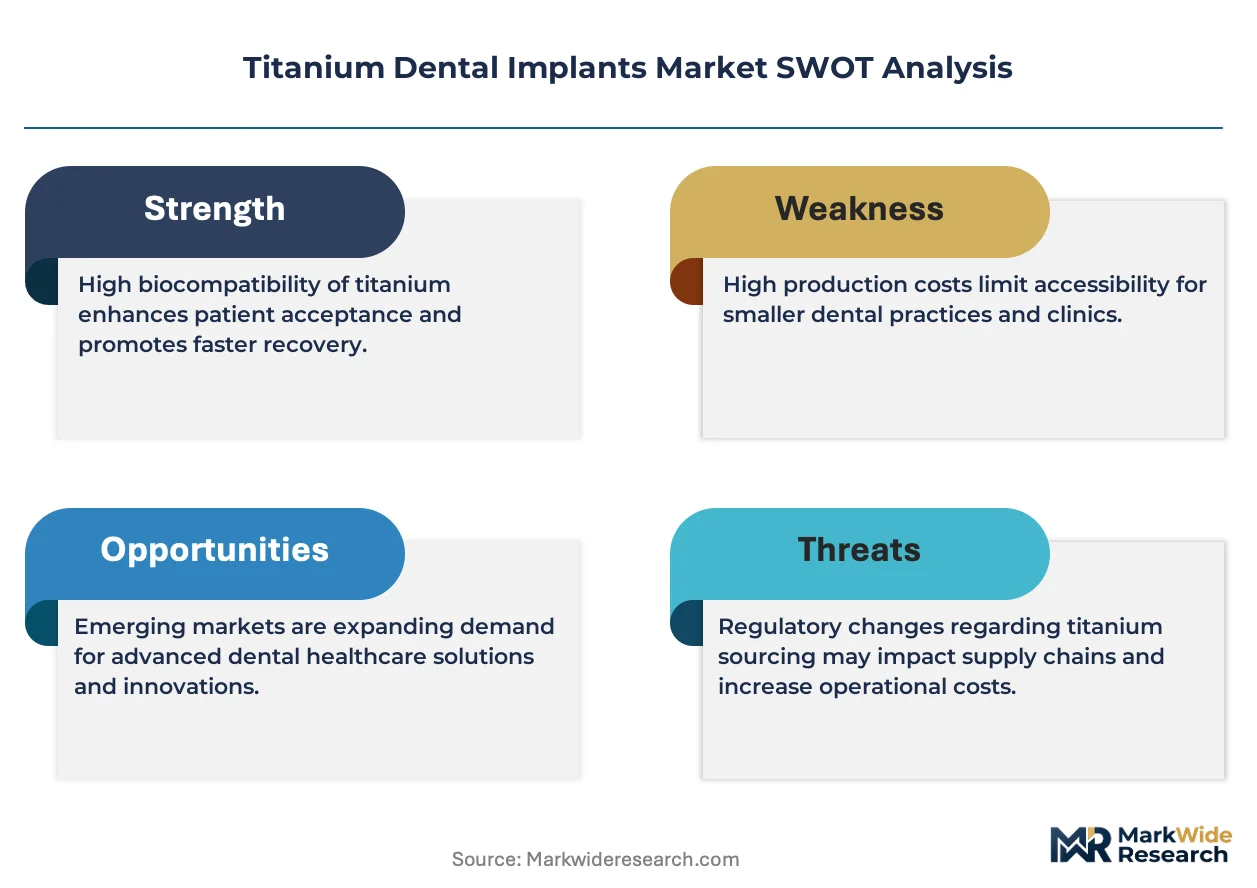
FDA 510(k) clearance requirements and CE marking under the EU MDR govern biocompatibility, mechanical fatigue, and surface characterization standards for titanium implants. ISO 10993 biological evaluation protocols and ASTM F67/F136 material specifications further constrain which alloys and treatments gain market access. Stakeholders must monitor how evolving cybersecurity requirements for connected surgical guidance systems reshape product development priorities and regulatory submission strategies.
Market Dynamics
Digital surgical guidance systems are compressing the traditional learning curve for implant placement, enabling general dentists to capture cases historically reserved for specialists and redistributing procedural volume across practice types.
Growth Catalysts
- EU MDR surface characterization mandates:Stricter biocompatibility documentation under the Medical Device Regulation is accelerating adoption of validated acid-etched and sandblasted treatments that demonstrate superior osseointegration rates in clinical dossiers.
- Subperiosteal implant innovation:Advancements in patient-specific titanium mesh frameworks are expanding treatment options for patients with severe bone resorption who were previously ineligible for endosteal placement.
- South Korea's aging demographic:The country's rapidly expanding over-65 population is driving fixed full-arch restoration demand as edentulous patients reject removable dentures.
Market Restraints
- Commercially pure titanium supply concentration:Primary sponge production concentrates in a limited number of metallurgical facilities, creating input cost volatility that compresses margin predictability for precision-machined implant manufacturers.
- Zirconia aesthetic substitution:All-ceramic alternatives are capturing anterior segment cases where soft tissue transparency and metal-free appearance drive patient preference.
- FDA 510(k) fatigue testing requirements:Extended mechanical validation timelines for novel surface geometries delay commercialization and elevate pre-market capital requirements.
Strategic Opportunities
- India's underpenetrated tier-2 cities:Rising disposable incomes and expanding dental insurance coverage in secondary urban centers create whitespace for mid-priced titanium implant systems.
- Same-day digital workflow integration:Convergence of intraoral scanning, chairside milling, and guided surgery is enabling immediate loading protocols that differentiate premium service offerings.
- Japan's PMDA fast-track pathway:The Pharmaceuticals and Medical Devices Agency's priority review designation for regenerative medicine products accelerates market entry for surface-modified implants with enhanced osteoconductive properties.
Industry Challenges
- Prosthodontist training pipeline constraints:Extended fellowship durations and limited program slots are constraining the specialist workforce needed to support complex full-arch reconstruction volume.
- Cybersecurity certification for connected surgical guides:FDA's evolving software validation requirements for network-enabled planning systems are extending development cycles and demanding new engineering competencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Titanium Dental Implants Market |
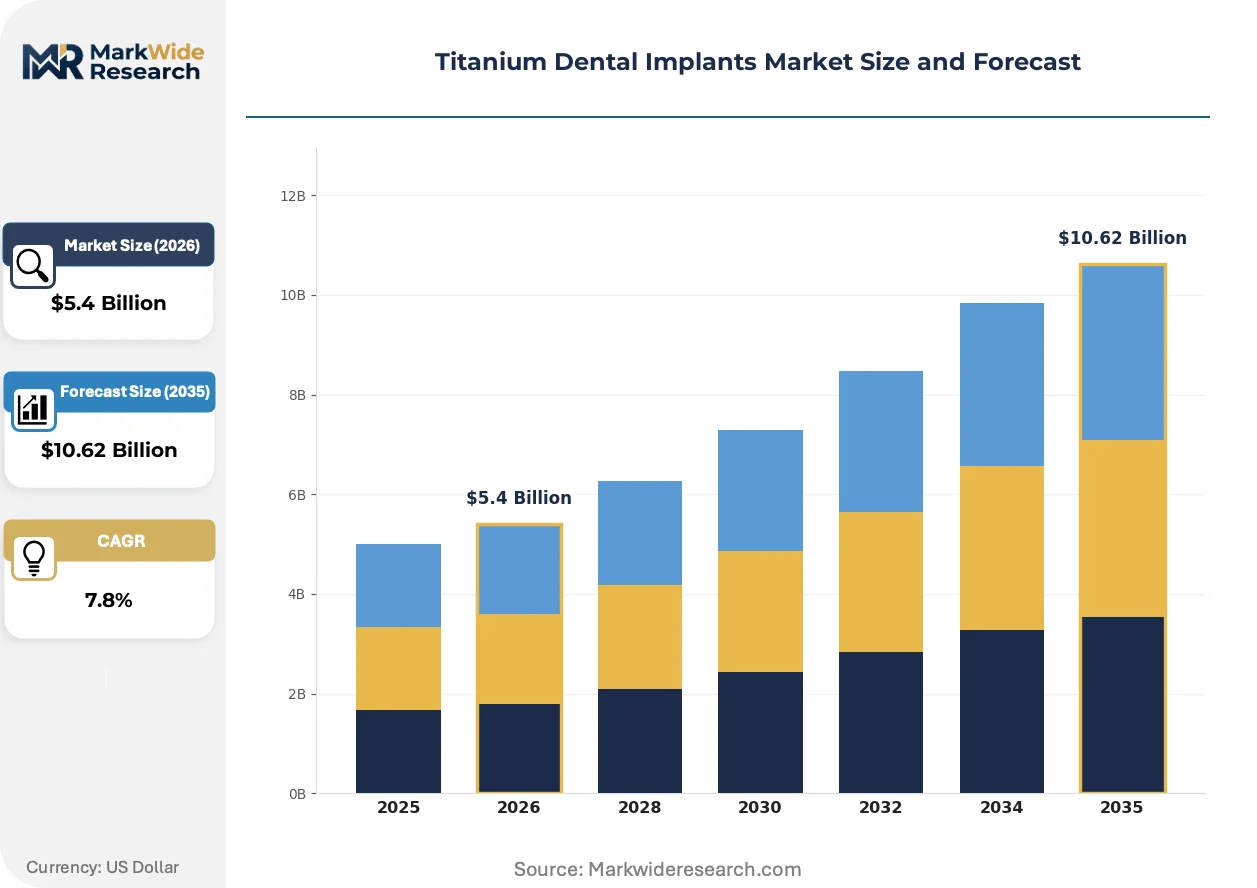
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $10.62 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endosteal Implants, Subperiosteal Implants, Zygomatic Implants, Mini Implants Implant Surface Treatment: Plasma Sprayed, Acid Etched, Sandblasted, Anodized, Laser Treated Application: Single Tooth Replacement, Multiple Teeth Replacement, Full Arch Restoration, Maxillofacial Prosthetics End User: Dental Clinics, Oral Surgery Centers, Dental Laboratories, Prosthodontic Offices |
| Companies Covered | Nobel Biocare, MegaGen Implant Co., Ltd., Straumann Holding AG, Dentium Co., Ltd., BioHorizons, LLC, Dentsply Sirona Inc., Osstem Implant Co., Ltd., Euroteknika, Zimmer Biomet Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Titanium Dental Implants Market Strategic Shifts & Innovations
Additive manufacturing is reshaping how titanium implant components reach the market, with powder-bed fusion enabling lattice structures and patient-specific geometries that subtractive methods cannot achieve.
Nanostructured surface modification is fragmenting the competitive landscape for premium implant positioning. Electrochemical anodization and hydroxyapatite coating technologies create topographical features at the nanometer scale that accelerate bone apposition timelines. Mid-tier manufacturers are licensing these surface treatments to close the clinical evidence gap with established players. The resulting technology diffusion is compressing price premiums previously commanded by proprietary surface patents.
REACH substance restriction evaluations are tightening scrutiny on alloying elements in Ti-6Al-4V implants. The European Chemicals Agency's ongoing assessment of vanadium biocompatibility is pressuring manufacturers to document leaching profiles and accelerate development of vanadium-free alternatives such as Ti-6Al-7Nb. European implant portfolios are responding with expanded commercially pure titanium offerings to preempt regulatory exclusion.
Consolidated procurement by dental service organizations is concentrating purchasing power and unbundling traditional distributor relationships. Large DSOs in the United States are negotiating direct manufacturer contracts that bypass conventional dealer networks and demand volume-based pricing transparency. This channel compression is most visible in Sun Belt states where private equity-backed dental rollups have achieved regional density sufficient to justify dedicated supply agreements.
Titanium Dental Implants Market Segmentation
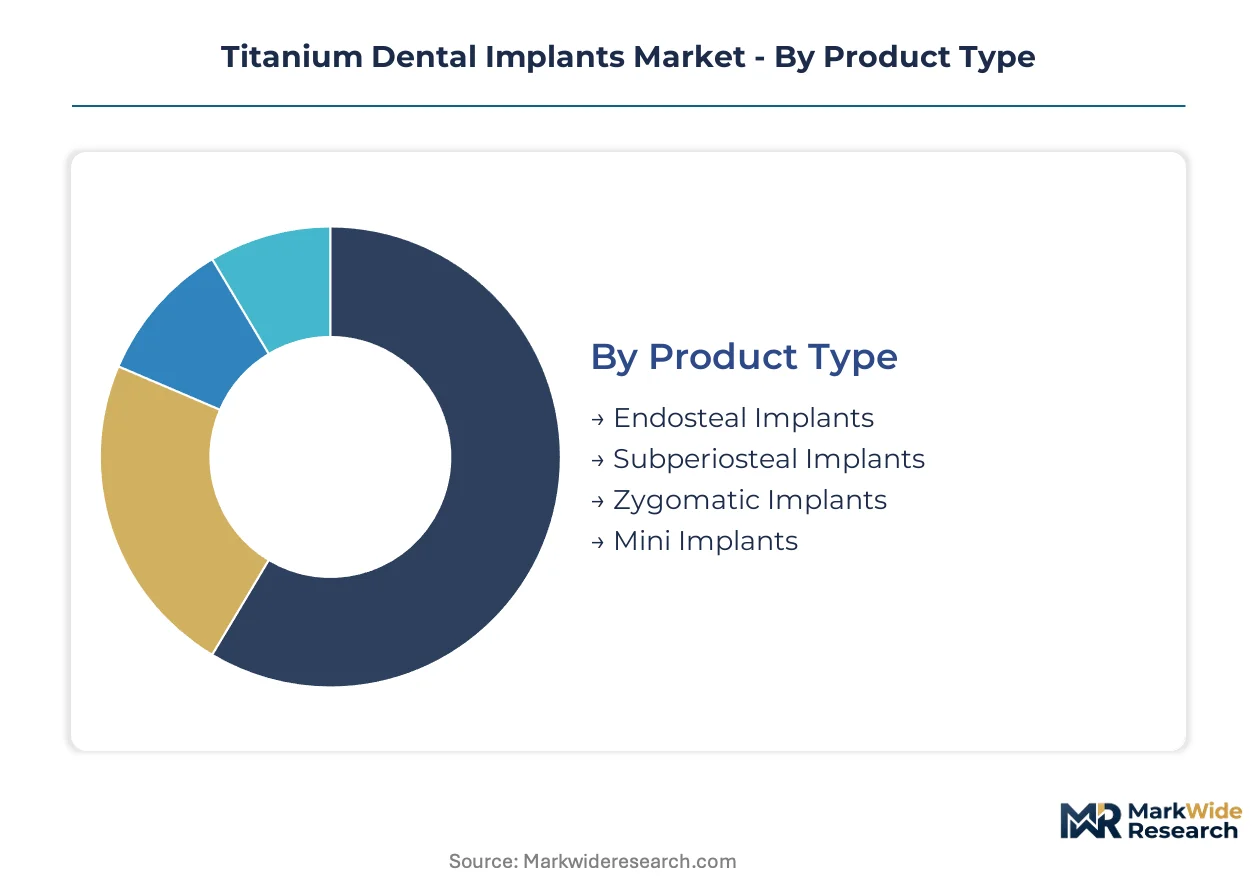
Titanium dental implant segmentation reveals how clinical specialization, surface engineering sophistication, and procedural setting reshape procurement patterns. Each dimension carries distinct margin profiles and regulatory exposure that manufacturers must navigate.
Product Type:
Domestic procedural volume concentrates on endosteal systems validated through decades of reimbursement history, while zygomatic and subperiosteal innovations drive export-led growth into markets with severe bone resorption prevalence.
- Endosteal Implants:These screw-type or cylinder fixtures composed of commercially pure titanium or Ti-6Al-4V alloy integrate directly into the jawbone through osseointegration. Demand concentrates in Germany and the United States where established reimbursement codes support high-volume placement, though margin pressure intensifies as digital guidance commoditizes placement accuracy.
- Subperiosteal Implants:Custom-cast titanium frameworks sit atop the bone beneath the periosteum for patients with insufficient ridge height. Export-led growth centers on South Korea and Japan where aging populations with severe resorption seek alternatives to bone grafting protocols.
- Zygomatic Implants:Extended-length fixtures anchor into the cheekbone for maxillary atrophy cases.
- Mini Implants:Narrow-diameter temporary or transitional supports for denture stabilization.
Endosteal implants hold the largest share; momentum sits with subperiosteal systems as CAD/CAM personalization reduces fabrication costs.
Implant Surface Treatment:
Surface engineering separates premium positioning from commodity competition, with validated treatments commanding price premiums in regulatory-stringent markets while basic finishes dominate cost-sensitive procurement.
- Acid Etched:Hydrofluoric or nitric acid treatment creates micro-roughened topography that accelerates osteoblast attachment and bone apposition. Demand concentrates in oral surgery centers across the United States where FDA 510(k) dossiers with bone-to-implant contact data support premium pricing, though EU MDR documentation requirements are elevating validation costs.
- Sandblasted:Alumina or titanium oxide particle bombardment generates controlled surface roughness for mechanical interlocking. Adoption spreads fastest in South Korean dental clinics where national insurance expansion for fixed restorations drives volume procurement of mid-tier validated surfaces.
- Plasma Sprayed:Thermal deposition of hydroxyapatite coatings for enhanced bioactivity.
- Anodized:Electrochemical oxidation creating nanostructured titanium dioxide layers.
- Laser Treated:Precision surface patterning for controlled cell response engineering.
Acid-etched surfaces dominate revenue; sandblasted treatments are climbing the fastest as manufacturing scale reduces per-unit differentials.
Application:
Procedure complexity stratifies customer economics, with single-unit restorations sustaining general practice volume while full-arch reconstruction concentrates in specialized settings with higher equipment investment.
- Single Tooth Replacement:Individual implant-supported crowns address isolated edentulism with straightforward surgical and restorative protocols. Volume concentrates in United States dental clinics where digital intraoral scanning and chairside milling compress turnaround times, though zirconia substitution threatens anterior titanium placement.
- Full Arch Restoration:Four-to-six implant fixed prostheses replace entire dental arches for edentulous patients. German oral surgery centers drive adoption where technician partnerships and on-site milling capabilities enable immediate loading protocols that differentiate against removable alternatives.
- Multiple Teeth Replacement:Implant-supported bridges spanning several edentulous spaces.
- Maxillofacial Prosthetics:Craniofacial reconstruction and oncology rehabilitation applications.
Single tooth replacement holds the largest share; full arch restoration shows the steepest expansion trajectory as aging demographics reject removable dentures.
End User:
Practice type determines purchasing authority and technical support requirements, with institutional buyers consolidating volume and independent operators demanding flexible inventory terms.
- Oral Surgery Centers:Specialist facilities with advanced imaging and guided surgery infrastructure perform complex and full-arch procedures. Procurement concentrates in South Korea where hospital-affiliated centers leverage scale for direct manufacturer negotiations, though prosthodontist shortages constrain case throughput expansion.
- Dental Clinics:General practice settings capturing routine single-tooth placement through digital guidance adoption. United States DSO consolidation is compressing distributor margins as regional rollups achieve density for dedicated supply contracts.
- Dental Laboratories:Fabrication partners influencing implant selection through restorative component compatibility.
- Prosthodontic Offices:Specialist restorative practices handling complex rehabilitation cases.
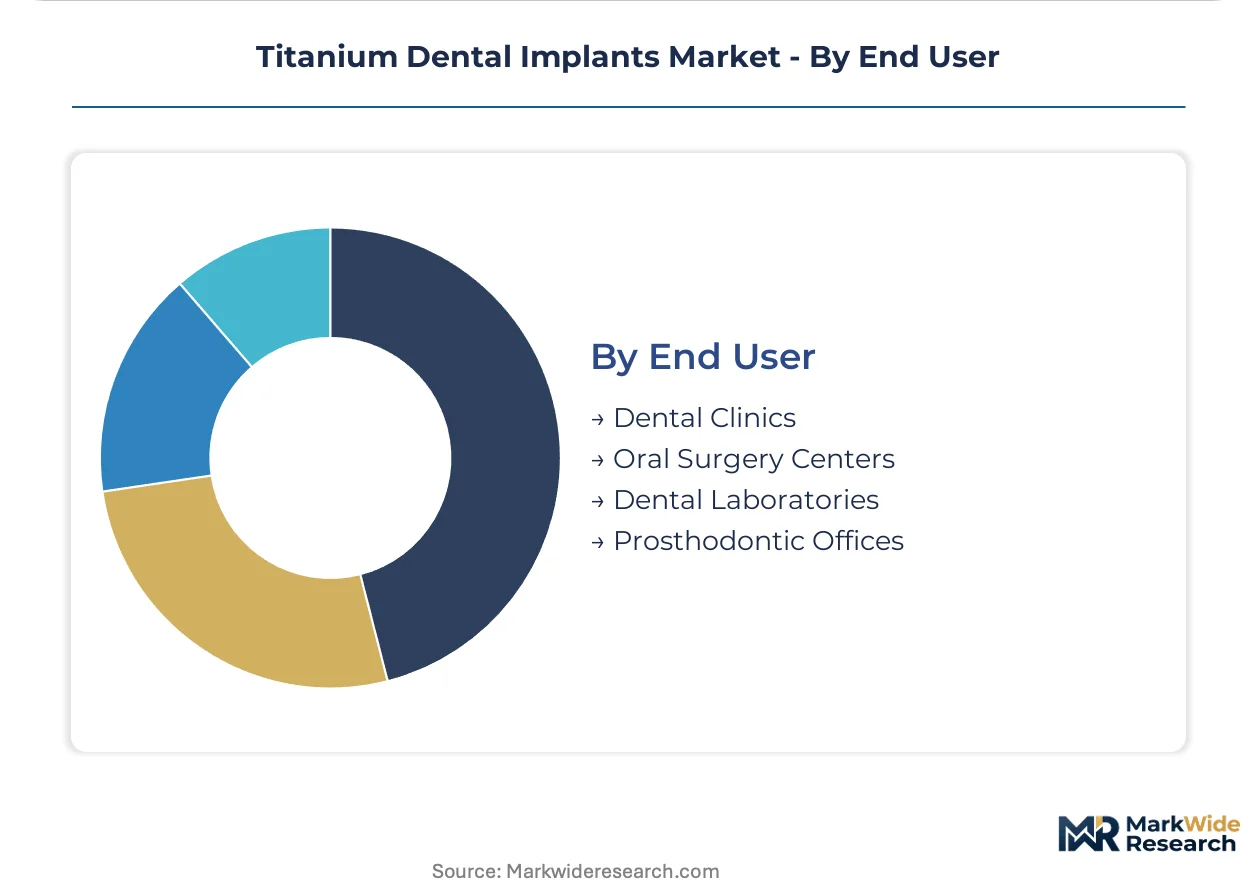
Dental clinics hold the largest share; oral surgery centers are gaining share fastest as procedure complexity migrates toward specialist settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance requirements anchor the United States as the procedural volume leader, while EU MDR surface characterization mandates and South Korea's national insurance expansion reshape competitive positioning across developed markets.
United States
Oral surgery centers in Texas and Florida drive fixed full-arch restoration volume as private equity-backed dental service organizations achieve regional density for direct manufacturer contracts. FDA 510(k) fatigue testing requirements for novel surface geometries extend validation timelines but reinforce established players with existing dossiers. The Sun Belt corridor concentrates DSO procurement power, compressing traditional distributor margins.
Germany
Baden-Württemberg and Bavaria host specialized training academies that deepen clinician loyalty to premium implant systems through technician partnerships and on-site milling capabilities. EU MDR biocompatibility documentation requirements accelerate adoption of validated acid-etched treatments in clinical dossiers. Stuttgart and Munich anchor European market presence for guided surgery platforms.
South Korea
Seoul Capital Area hospital-affiliated centers leverage scale for direct negotiations with implant manufacturers as the over-65 population rejects removable dentures. National insurance expansion for fixed restorations drives volume procurement of mid-tier validated surfaces. Busan-Ulsan clusters concentrate export-oriented production for Asian markets.
Japan
PMDA fast-track priority review for regenerative medicine products accelerates market entry for surface-modified implants with enhanced osteoconductive properties in Osaka and Nagoya clusters. Aging demographics in Kanto drive edentulous patient demand for alternatives to bone grafting protocols. Tokyo-based specialists capture complex zygomatic placement cases.
India
Tier-2 cities in Maharashtra and Gujarat create whitespace for mid-priced titanium implant systems as rising disposable incomes meet expanding dental insurance coverage. CDSCO import regulations and local manufacturing incentives reshape procurement patterns for domestic versus foreign suppliers. Mumbai and Ahmedabad clusters concentrate technician training infrastructure.
Titanium Dental Implants Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with premium positioning sustained through digital workflow platforms and manufacturing scale. The structure rewards clinical evidence accumulation and regulatory dossier depth over pure price competition. Three archetypes dominate: full-stack solution providers with guided surgery ecosystems, surface technology licensors closing evidence gaps, and scale manufacturers competing on portfolio breadth. Consolidated procurement by dental service organizations and technology licensing agreements represent the dominant competitive moves reshaping channel relationships.
Among Swiss-anchored full-stack providers, Straumann Holding AG exemplifies premium positioning through integrated digital workflows, while Nobel Biocare occupies a comparable tier with European training academy investments. Zimmer Biomet Holdings, Inc. represents the scale-driven archetype with broad portfolio manufacturing reach. Korean specialists Osstem Implant Co., Ltd. and Dentium Co., Ltd. sit within the export-oriented mid-tier segment serving Asian market expansion.
| Leading Market Players |
|---|
| Nobel Biocare |
| MegaGen Implant Co., Ltd. |
| Straumann Holding AG |
| Dentium Co., Ltd. |
| BioHorizons, LLC |
| Dentsply Sirona Inc. |
| Osstem Implant Co., Ltd. |
| Euroteknika |
| Zimmer Biomet Holdings, Inc. |
| Others |
Cost & Logistics Intelligence
Ninety-day titanium sponge inventory cycles at precision machining facilities compress margin buffers for implant manufacturers while amplifying pricing power among primary metallurgical suppliers in China and Japan. This lead-time structure concentrates cost volatility exposure in the mid-tier implant segment, where manufacturers lack backward integration into sponge production and must absorb spot-price fluctuations or pass them through to price-sensitive dental clinics.
Pricing Analysis
United States-Germany price spreads for acid-etched endosteal systems exceed three-to-one, reflecting FDA 510(k) dossier depth and reimbursement code density. Three-tier pricing structure across premium, standard, and economy levels segments by surface validation rigor and guided surgery bundling. Cost compression in the economy tier intensifies as Indian and Chinese manufacturers achieve CE marking parity. Dental service organizations exhibit highest price sensitivity through consolidated procurement, while oral surgery centers prioritize clinical evidence over unit cost.
Supply Chain Analysis
Sixty-to-ninety day lead times for Ti-6Al-4V alloy bar stock from Japanese and German metallurgical mills constrain production scheduling for mid-sized implant manufacturers. Commercially pure titanium sponge production draws from Chinese, Russian, and Ukrainian primary facilities, creating tariff exposure and single-source vulnerability for European fabricators. Distribution runs through authorized dealer networks facing compression from direct manufacturer contracts with dental service organizations in the United States Sun Belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates acquisition opportunities as digital workflow adoption splinters procurement authority between general dentists and specialists, generating niche positioning openings for surface-technology licensors and regional manufacturing specialists.
For Market Incumbents: Fortify regulatory dossier depth through accelerated EU MDR surface characterization documentation to preempt mid-tier competitors. Deepen backward integration into titanium sponge sourcing through offtake agreements with Japanese metallurgical facilities, securing margin stability against commodity volatility. Channel control through exclusive distributor relationships in Germany and South Korea defends premium positioning against DSO procurement consolidation.
For New Entrants and Emerging Players: Differentiate on nanostructured surface modification licensing to close clinical evidence gaps without proprietary R&D infrastructure. Target India's tier-2 cities through mid-priced validated surfaces and technician training partnerships that mirror Osstem's Asian expansion playbook. Go-to-market leverage rests on CDSCO import pathway navigation and local manufacturing joint ventures.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medtech conglomerates with underperforming dental divisions lacking digital workflow integration. Long-term viability hinges on surface-technology patent estates and regulatory dossier transferability. Signal to watch: PMDA fast-track designations for osteoconductive surface modifications indicating premium-tier repositioning potential.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Surface Characterization Dossier Expansion | Accelerates market access for acid-etched treatments against unvalidated competitors in German oral surgery centers. |
| Direct Manufacturer Contracting with DSOs | Bypasses traditional dealer networks and captures volume procurement in Texas and Florida consolidation corridors. |
| Nanostructured Surface Technology Licensing | Closes clinical evidence gaps for mid-tier manufacturers competing with Straumann and Nobel Biocare premium portfolios. |
| Japanese Sponge Supply Agreement | Secures Ti-6Al-4V alloy feedstock against REACH vanadium restriction uncertainty and Russian supply disruption. |
| PMDA Fast-Track Pathway Navigation | Accelerates regenerative medicine designation for osteoconductive implants in Osaka and Nagoya metropolitan clusters. |
Research Approach
Initial hypotheses were tested against primary input from oral surgeons, prosthodontists, dental laboratory technicians, and GPO contracts managers and refined through secondary validation. Primary interviews captured placement protocol evolution and procurement decision criteria across United States, German, and South Korean clinical settings. Secondary sources encompassed FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement schedules, and ISO 10993 biological evaluation protocols. Bottom-up implant volume modeling triangulated against top-down demographic edentulism projections.
Variance decomposition across product type, surface treatment, application complexity, and end-user practice setting anchored the analytical framework. Segmentation dimensions modeled implant system architecture, surface engineering sophistication, procedural indication, and regional regulatory cluster. CAGRs derived from procedure volume elasticity to aging demographic penetration and insurance reimbursement expansion. Industry-specific inputs included prosthodontist workforce pipeline constraints and DSO consolidation velocity.
The analysis sits within stated boundaries; outcomes outside sustained FDA and EU MDR regulatory stringency or accelerated zirconia aesthetic substitution would require recalibration. Forecasts reflect documented assumptions regarding osseointegration validation timelines and cybersecurity certification trajectories for connected surgical guidance. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Calipers Market
Dental Devices
Global Professional Teeth Whitening and Power Toothbrushes Market
Dental Devices
Dental Composite Resin Filling Market
Dental Devices
Dental Rapid Prototyping Systems Market
Dental Devices
Global Dental Labs Market
Dental Devices
Europe Dental Implants and Prosthetics Market
Dental Devices
Dental Chair Market
Dental Devices
North America Aligner Sheet Market
Dental Devices
Asia Pacific Dental Market
Dental Devices
UAE Dental Devices Market
Dental Devices
Dental Caries Market
Dental Devices
Orthodontic Wax Market
Dental Devices
Dental Handpieces Market
Dental Devices
Prophy Dental Handpiece Market
Dental Devices
India Dental Devices Market
Dental Devices
Dental Dam Market