
 Argentina Dental Devices Market | 2026-2036
Argentina Dental Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Dental Devices Market Outlook
Buyer concentration among private dental clinics in Buenos Aires and Córdoba is rebalancing toward mid-sized regional chains that now account for rising procurement volumes. Henry Schein, Inc. leverages its distribution network to supply these expanding clinic networks with chairside equipment and consumables. Envista Holdings Corporation anchors its position through specialized implantology and orthodontic portfolios tailored to Argentine practitioners. Straumann Holding AG differentiates via premium implant systems and digital workflow solutions that appeal to clinics investing in technology upgrades.
Dental devices encompass instruments, equipment, and consumables engineered from biocompatible materials such as titanium alloys, zirconia ceramics, and photopolymer resins, manufactured through CNC milling, 3D printing, and injection molding processes to diagnose, treat, or restore oral structures. Restorative applications dominate procedure volumes in Argentina's dental services sector, with ceramic and composite materials capturing preference for aesthetic outcomes. Orthodontics represents the fastest-expanding product category as clear aligner therapy displaces traditional brackets among adult patients seeking discreet treatment options.
ANMAT regulates medical device registration under Mercosur Resolution GMC/Res. No. 16/2013, requiring foreign manufacturers to designate local authorized representatives and submit technical documentation for product clearance. The Argentine Ministry of Health periodically updates biocompatibility testing protocols, compelling suppliers to recertify materials against evolving safety benchmarks. Stakeholders must monitor pending Mercosur regulatory harmonization proposals that could streamline multi-country market access or introduce additional conformity assessment layers for imported dental technologies.
Market Dynamics
Clear aligner therapy is compressing orthodontic procedure economics while expanding addressable patient segments in Argentina's private dental sector, forcing clinics to reconfigure chairside workflows and capital allocation priorities.
Growth Catalysts
- ANMAT registration pathways:Mercosur Resolution GMC/Res. No. 16/2013 harmonization is gradually streamlining cross-border device approvals, reducing redundant technical documentation burdens for imported CAD/CAM systems.
- Photopolymer resin printing:Chairside 3D printing adoption is accelerating same-day crown and bridge production, eliminating laboratory turnaround delays for Buenos Aires clinics.
- Mid-sized regional chains:Consolidation among private dental networks in Córdoba and Rosario is generating volume procurement contracts that favor integrated equipment-consumable suppliers.
Market Restraints
- Titanium alloy import dependency:Argentine manufacturers lack domestic smelting capacity for medical-grade titanium, exposing implant producers to currency-driven input cost volatility.
- Biocompatibility recertification cycles:Argentine Ministry of Health protocol updates force suppliers to repeat ISO 10993 testing sequences, extending product launch timelines.
- Zirconia ceramic substitution:Full-contour zirconia crowns are displacing metal-ceramic restorations in posterior applications, compressing margins for traditional porcelain-fused-to-metal laboratories.
Strategic Opportunities
- Tele-diagnostics integration:Remote orthodontic monitoring platforms are opening access to patients in Mendoza and Tucumán provinces underserved by specialist orthodontists.
- ANMAT fast-track incentives:Pending regulatory amendments for software-as-medical-device classification could accelerate AI-powered radiology tool market entry.
- Subscription-based aligner models:Direct-to-patient financing structures are penetrating Argentina's credit-constrained middle-class demographic previously excluded from private orthodontic care.
Industry Challenges
- CAD/CAM technician scarcity:Argentine dental schools graduate insufficient operators proficient in 3Shape and Exocam design software, forcing clinics to outsource digital workflows.
- Legacy equipment integration:Open-architecture intraoral scanners are struggling to interface with proprietary mill firmware in older CEREC installations, complicating technology upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Dental Devices Market |
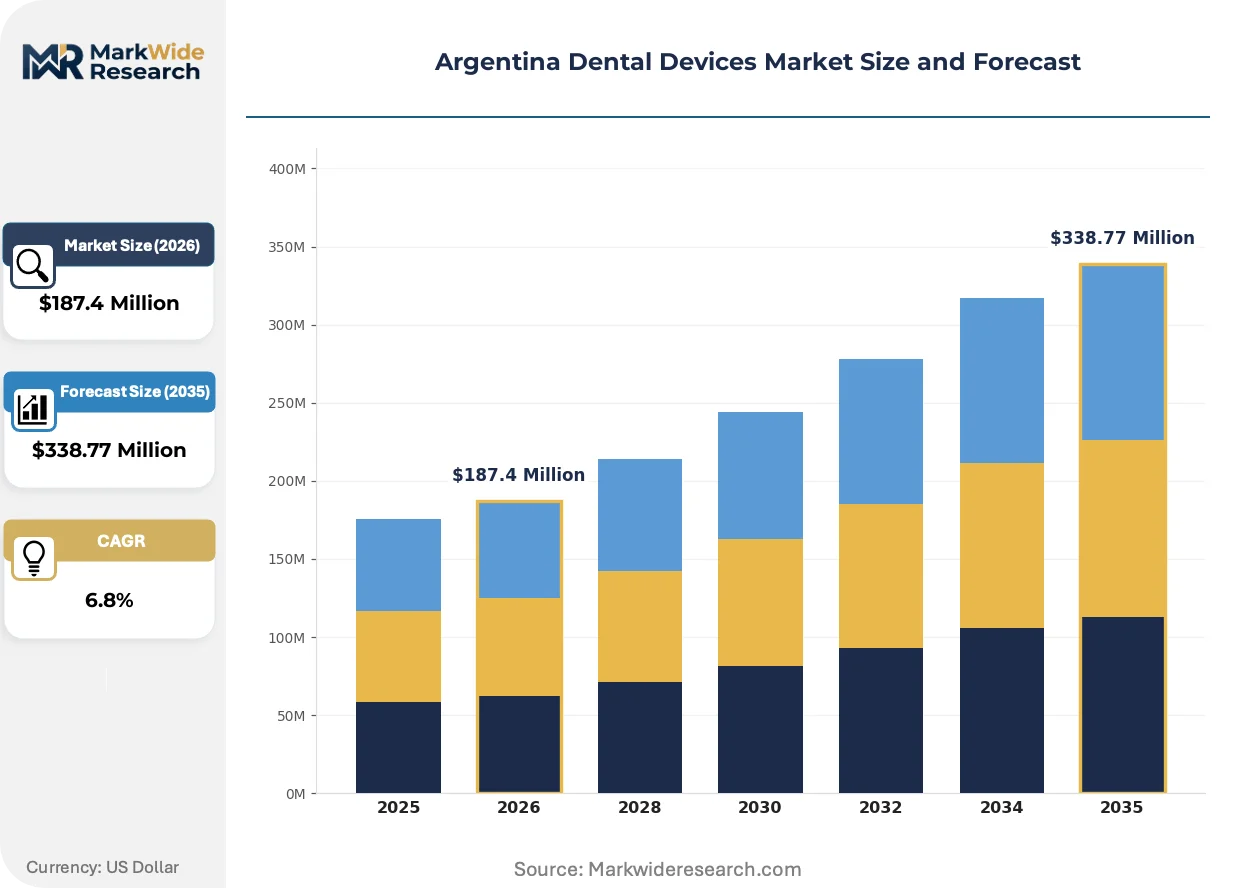
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthodontics, Endodontics, Restorative, Preventive Material: Metal, Ceramic, Composite, Polymer Application: Cosmetic Dentistry, Oral Surgery, Periodontics, Pediatric Dentistry End User: Dental Clinics, Hospitals, Laboratories, Educational Institutions |
| Companies Covered | Henry Schein, Inc., Envista Holdings Corporation, 3M, Straumann Holding AG, Planmeca OY, Dentsply Sirona, Align Technology, Carestream Health Inc., Ivoclar Vivadent, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Dental Devices Market Strategic Shifts
Digital workflow convergence is collapsing traditional boundaries between diagnosis, design, and fabrication in Argentine dental practices, compressing treatment timelines while elevating technical competency requirements.
Intraoral scanning is electrifying impression capture protocols across Buenos Aires orthodontic practices. Private clinics are retiring polyvinyl siloxane trays in favor of Primescan and iTero systems, cutting appointment times by half. The technology is electrifying same-day treatment planning, compressing the interval between initial consultation and aligner production from weeks to hours.
ANMAT's evolving software-as-medical-device guidance is reshaping regulatory boundaries for AI-powered radiographic analysis tools. Manufacturers must now submit algorithm validation datasets alongside traditional hardware technical files, elevating compliance costs for foreign entrants. Argentine radiology specialists are responding by consolidating purchasing decisions around vendors with established local authorized representatives capable of navigating documentation complexity.
Patient financing platforms are fragmenting traditional fee-for-service collection models in Argentina's private dental sector. Third-party credit intermediaries are embedding installment options directly into clinic management software, displacing upfront cash payment expectations. This behavioral shift is most visible among adult orthodontic patients in Greater Buenos Aires, where monthly payment structures are expanding aligner therapy access beyond historically insured demographics.
Argentina Dental Devices Market Segmentation
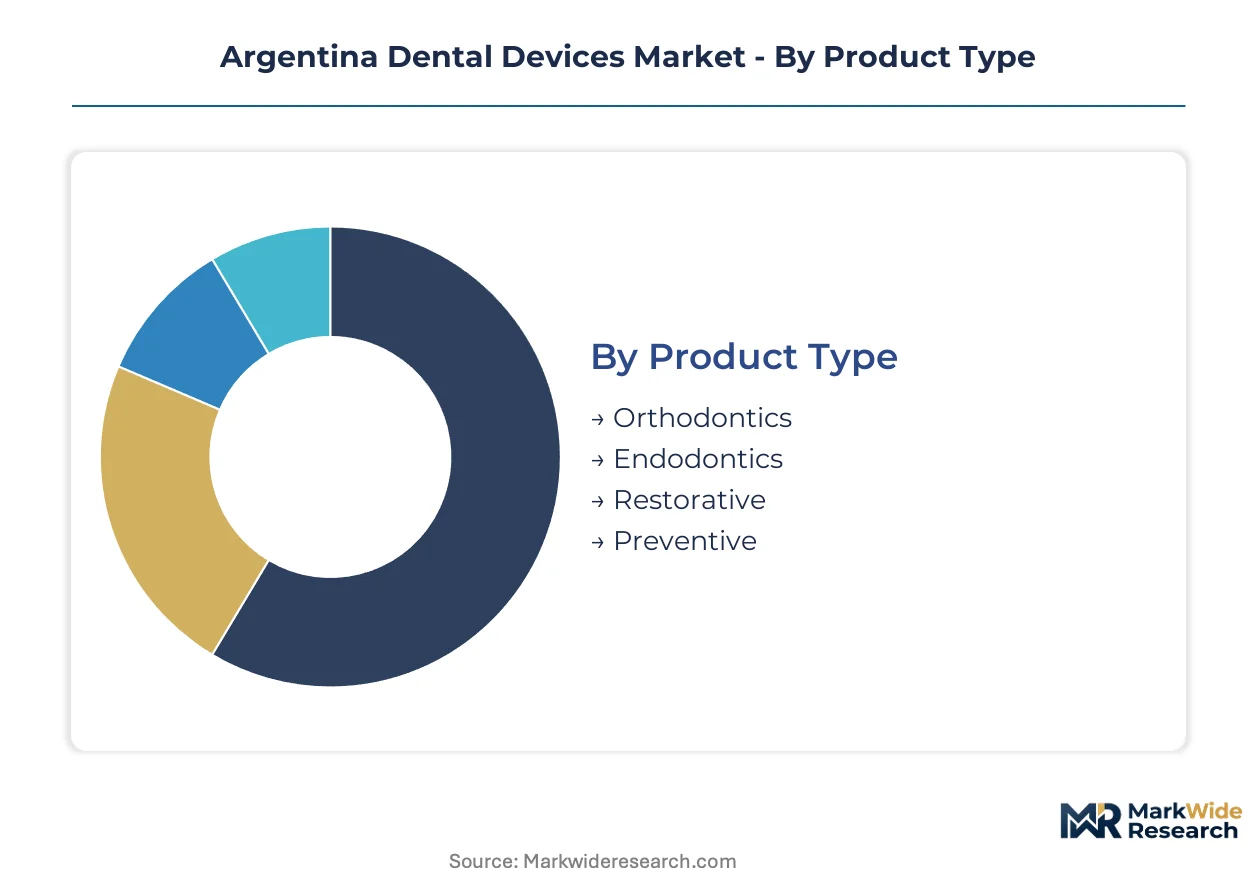
Argentina's dental devices market fragments across four critical dimensions that determine procurement patterns, regulatory pathways, and margin structures. Product type and material composition drive manufacturing investment priorities, while application focus and end-user channel dictate distribution architecture and service intensity requirements.
Product Type:
Procurement volume splits sharply between high-frequency consumable procedures and capital-intensive technology platforms, with clinic buyers prioritizing different performance metrics across each.
- Orthodontics:Clear aligner systems and self-ligating bracket technologies command premium positioning through Buenos Aires cosmetic practices. Demand concentrates among adult patients in Palermo and Recoleta districts seeking discreet treatment alternatives to traditional fixed appliances.
- Restorative:CAD/CAM-enabled crown and bridge fabrication dominates chairside investment, with ceramic and composite material systems displacing metal-based alternatives. Córdoba's expanding clinic networks are prioritizing same-day milling capacity to capture patient volume from conventional laboratory workflows.
- Endodontics:Nickel-titanium rotary instrumentation and electronic apex locators standardize root canal therapy across Argentine general practices.
- Preventive:Ultrasonic scaling units and fluoride delivery systems represent baseline equipment for hygiene service expansion.
Restorative leads volumes today; Orthodontics is gaining share fastest.
Material:
Cost tier and clinical indication determine material selection, with Argentine practitioners balancing aesthetic outcomes against durability requirements and ANMAT biocompatibility compliance costs.
- Metal:Titanium alloys anchor implantology applications, though import dependency exposes Argentine manufacturers to peso volatility. Premium cobalt-chrome frameworks persist in posterior bridgework where occlusal load tolerance outweighs aesthetic considerations.
- Ceramic:Zirconia and lithium disilicate formulations capture anterior restoration demand through Buenos Aires aesthetic-focused practices. Full-contour monolithic zirconia is compressing metal-ceramic laboratory margins as chairside milling adoption accelerates.
- Composite:Nanohybrid and bulk-fill resin formulations dominate direct restoration volumes in Argentine general practice.
- Polymer:Photopolymer resins enable aligner and splint fabrication through desktop 3D printing deployments.
Metal retains the largest installed base; Ceramic shows the steepest expansion trajectory.
Application:
Procedure reimbursement structures and specialist availability shape application-level demand concentration across Argentina's provincial healthcare landscape.
- Cosmetic Dentistry:Veneer, whitening, and aligner procedures concentrate in Buenos Aires and Córdoba private clinics serving credit-accessible middle-class demographics. Patient financing platform integration is expanding addressable segments beyond historically insured populations.
- Oral Surgery:Implant placement and bone grafting procedures require specialized surgical infrastructure concentrated in metropolitan hospital affiliates. Straumann and Envista distribution networks prioritize surgeon training partnerships in these high-value intervention settings.
- Periodontics:Regenerative membrane and growth factor applications serve specialist practices in Rosario and Mendoza.
- Pediatric Dentistry:Behavior management tools and preventive sealant systems address public health program requirements.
Cosmetic Dentistry commands premium pricing; Oral Surgery delivers highest per-procedure equipment intensity.
End User:
Channel structure determines service bundling requirements, with direct clinic relationships favoring integrated equipment-consumable contracts versus laboratory and institutional procurement patterns.
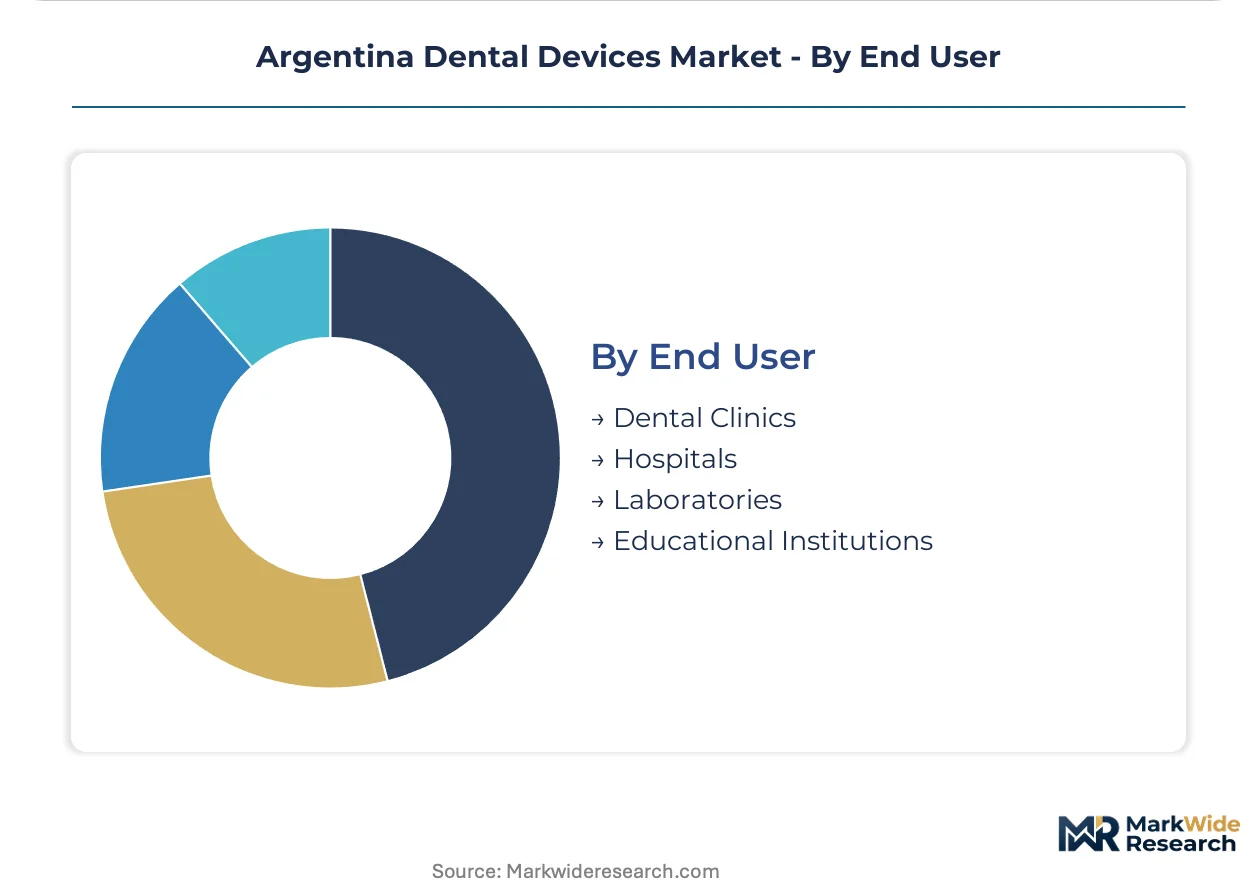
- Dental Clinics:Private practice networks in Buenos Aires and Córdoba drive chairside digitalization investment, consolidating purchasing through Henry Schein distribution agreements. Mid-sized regional chains are displacing independent practitioners as volume concentration points.
- Laboratories:Outsourced crown and bridge fabrication faces compression from clinic-level CAD/CAM adoption, forcing technical centers to specialize in complex implant bar and removable prosthesis work.
- Hospitals:Academic medical centers and trauma facilities manage acute oral surgery caseloads with centralized sterilization and anesthesia support.
- Educational Institutions:Dental schools in Buenos Aires and La Plata shape future practitioner preferences through equipment standardization in training clinics.
Dental Clinics absorb the majority of device procurement; Laboratories face structural volume pressure from chairside digital workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's dental device procurement volumes substantially exceed Argentina's, though Argentine clinics demonstrate faster adoption rates for chairside CAD/CAM systems and clear aligner platforms.
Buenos Aires Metropolitan Area
Palermo and Recoleta districts concentrate cosmetic dentistry demand, with adult patients financing aligner therapy through embedded credit platforms. ANMAT's Mercosur harmonization protocols govern all imported device registrations. Private clinic chains along Avenida del Libertador are consolidating purchasing power through Henry Schein distribution agreements.
Córdoba Province
Mid-sized regional dental networks are displacing independent practitioners as volume concentration points for restorative equipment. The Argentine Ministry of Health periodically updates biocompatibility testing protocols, forcing suppliers to recertify materials. Córdoba city clinics are prioritizing same-day milling capacity to capture patient volume from conventional laboratory workflows.
Rosario
Periodontal specialist practices in this Santa Fe hub are driving regenerative membrane and growth factor applications. ANMAT registration requirements under Resolution GMC/Res. No. 16/2013 compel foreign manufacturers to designate local authorized representatives. The city's expanding clinic networks are generating volume procurement contracts favoring integrated equipment-consumable suppliers.
Mendoza
Tele-diagnostics platforms are opening orthodontic access to patients underserved by specialist practitioners in this western province. Provincial health authorities coordinate with national regulators on device safety monitoring. Mendoza's wine-country middle-class demographic is expanding private dental service utilization beyond historically insured populations.
Argentina Dental Devices Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Argentina's dental device procurement channels. The market structure tiers between premium implantology portfolios and volume-driven consumable suppliers. Three archetypes dominate: integrated distribution networks, specialized orthodontic technology vendors, and premium implant system manufacturers. Competitive moves center on clinic network consolidation partnerships and chairside digital workflow integration.
Among US-based healthcare conglomerates, Henry Schein, Inc. and 3M occupy positions anchoring broad distribution and materials supply respectively. European specialists Straumann Holding AG and Dentsply Sirona exemplify premium-tier implant and restorative technology archetypes. Envista Holdings Corporation represents the focused dental pure-play model, sitting within the specialized equipment-manufacturer tier alongside Planmeca OY's imaging systems positioning.
| Leading Market Players |
|---|
| Henry Schein, Inc. |
| Envista Holdings Corporation |
| 3M |
| Straumann Holding AG |
| Planmeca OY |
| Dentsply Sirona |
| Align Technology |
| Carestream Health Inc. |
| Ivoclar Vivadent |
| Others |
Value Chain & Pricing Dynamics
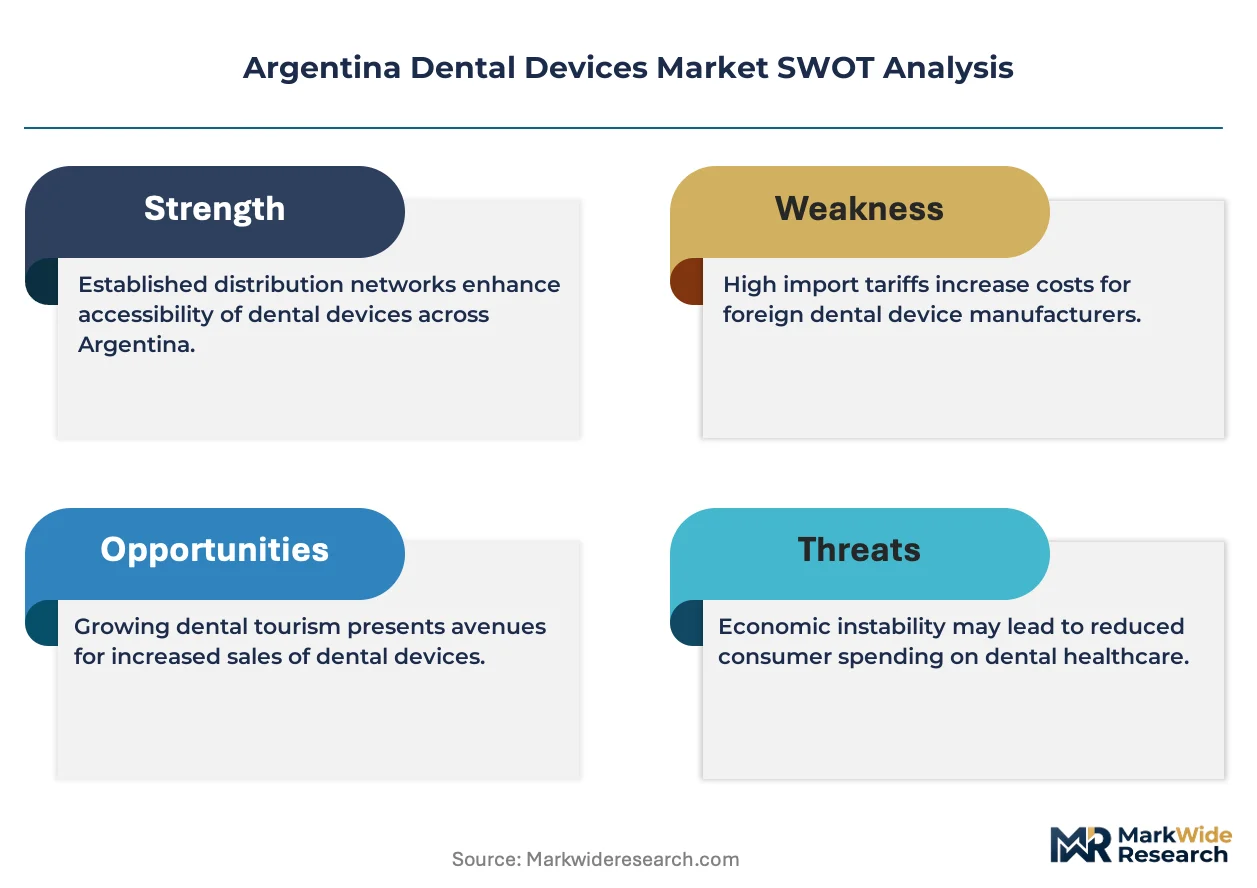
Titanium alloy import costs from US and European smelters cascade through Argentine dental implant pricing tiers, with peso volatility amplifying spreads between premium Straumann systems and mid-tier alternatives sourced through Henry Schein distribution networks.
Pricing Analysis
Capacity additions in Swiss and German precision manufacturing hubs are reshaping price floors for CAD/CAM milling units serving Buenos Aires clinic networks. Three-tier pricing structure across premium, standard, and economy levels separates Straumann implant portfolios from Envista mid-range offerings and regional consumable suppliers. Pricing pressure stems from zirconia ceramic substitution compressing metal-ceramic laboratory margins. Independent practitioners in Mendoza and Tucumán provinces exhibit highest price sensitivity; Palermo cosmetic clinics demonstrate lowest.
Supply Chain Analysis
Skilled CNC machining technicians in Switzerland and Germany anchor upstream production of chairside milling equipment destined for Argentine private clinics. Titanium alloy feedstock draws from Ukrainian and Russian sponge suppliers, though medical-grade bar stock processing concentrates in US and EU forges. Single-source vulnerability persists for photopolymer resin monomers tied to Chinese petrochemical complexes. Distribution runs through Henry Schein's Buenos Aires logistics hub to regional clinic networks in Córdoba and Rosario.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANMAT's pending software-as-medical-device classification amendments compound regulatory complexity for AI-powered radiology entrants, simultaneously creating compliance moats for established players with authorized representative infrastructure already deployed.
For Market Incumbents: Deepen technician training partnerships with Buenos Aires and La Plata dental schools to counter CAD/CAM operator scarcity threatening chairside workflow adoption. Anchor distribution exclusivity with mid-sized Córdoba clinic chains before regional consolidation accelerates procurement centralization. Lock in multi-year titanium alloy offtake contracts to hedge peso-driven input cost volatility eroding implant margin stability.
For New Entrants and Emerging Players: Enter via tele-diagnostics platforms targeting Mendoza and Tucumán provinces where specialist orthodontist density falls below metropolitan benchmarks. Capture adult aligner patients through embedded financing partnerships with Argentine credit intermediaries. Prioritize ANMAT fast-track pathway for AI radiology tools before regulatory amendments close window.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-sized regional clinic chains in Córdoba and Rosario outgrow independent purchasing patterns. Five-to-ten year viability favors platforms integrating chairside digital workflows with patient financing infrastructure. Monitor ANMAT registration backlog duration as inflection signal for import-dependent equipment categories.
| Strategic Initiative | Industry Significance |
|---|---|
| ANMAT Fast-Track Registration | Accelerates AI radiology market entry before software classification amendments finalize. |
| Dental School Training Partnership | Secures 3Shape and Exocam operator pipeline for CAD/CAM workflow adoption. |
| Regional Clinic Chain Consolidation | Captures volume procurement contracts displacing independent practitioner purchasing. |
| Tele-Diagnostics Platform Launch | Extends orthodontic access to Mendoza and Tucumán specialist-underserved populations. |
| Patient Financing Integration | Embeds installment options into clinic software for credit-constrained middle-class segments. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Argentine clinic owners, ANMAT regulatory affairs specialists, Henry Schein distribution managers, and Straumann territory representatives with secondary validation against ANMAT registration databases, Mercosur harmonization protocols, and Argentine Ministry of Health biocompatibility bulletins. Bottom-up clinic equipment procurement surveys and top-down import trade flow analysis provided triangulation anchors.
Segment-weighted modeling distributed value across product type, material composition, application focus, and end-user channel dimensions throughout the forecast period. CAGRs derived from procedure volume trajectories, technology substitution curves, and regulatory approval pipeline velocity. Industry-specific inputs incorporated aligner patient financing penetration rates and chairside CAD/CAM adoption thresholds by clinic network size tier.
Inputs from ANMAT registration filings and Argentine customs trade records were available through the study window; gaps in provincial clinic-level equipment inventory data introduce uncertainty bands for Córdoba and Rosario market sizing. Forecasts reflect documented assumptions regarding Mercosur harmonization timeline and peso exchange rate stability. Material deviation in ANMAT software classification finalization or titanium alloy supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Global Digital Dentistry Market
Dental Devices
Malocclusion Market
Dental Devices
Dental Piezoelectric Ultrasonic Unit Market
Dental Devices
Nano Dentistry Market
Dental Devices
Dental Orthodontic Wax Market
Dental Devices
Dental Diagnostic and Surgical Market
Dental Devices
Dental Composite Filling Market
Dental Devices
Australia Dental Devices Market
Dental Devices
Dental Radiometer Market
Dental Devices
Canada Dental Devices Market
Dental Devices
Single Tooth Implants and Dental Bridges Market
Dental Devices
Dental Articulators Market
Dental Devices
Dental Autoclave Market
Dental Devices
Dental Carpule Market
Dental Devices
Dental Curing Lights Market
Dental Devices
North America Dental Aligners Market