
 Dental Needle Market | 2026-2036
Dental Needle Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Needle Market Analysis
Asset-light leasing models for precision injection equipment is fragmenting the competitive landscape for dental needle suppliers, lowering capital barriers for regional distributors and specialty manufacturers. Septodont leverages backward integration into stainless steel cannula production to sustain margin control across European dental clinics. Dentsply Sirona anchors its position through proprietary hub designs that integrate with its broader anesthesia delivery systems. TERUMO Corporation competes on manufacturing scale, operating high-volume automated lines that supply hospital oral surgery departments across multiple continents.
A dental needle is a hollow, bevel-tipped metallic cannula, typically manufactured from 304-grade stainless steel with a polypropylene or polycarbonate hub, designed to penetrate soft oral tissue and deliver local anesthetic agents with controlled flow rates and minimal tissue trauma. Safety needles incorporating retractable or shielded mechanisms now dominate procurement specifications in regulated markets, while conventional non-safety configurations retain volume in cost-sensitive segments. Stainless steel remains the primary material category due to its tensile strength and compatibility with ethylene oxide sterilization cycles, though coated metal variants are gaining traction where reduced insertion force is prioritized. The 27 gauge and 30 gauge dimensions lead clinical preference for infiltration and block anesthesia respectively, with finer gauges representing the fastest-expanding specification tier as patient comfort metrics influence purchasing decisions.
FDA 510(k) clearance pathways and EU MDR Class IIa conformity requirements shape product development timelines and market access costs for dental needle manufacturers, with ISO 7864 standards governing cannula performance testing. OSHA's Bloodborne Pathogens Standard and REACH chemical compliance obligations in Europe further constrain material selections and disposal protocols for end users. Stakeholders must monitor evolving sharps injury prevention regulations and gauge standardization initiatives that could force portfolio rationalization decisions.
Market Dynamics
OSHA's Bloodborne Pathogens Standard and EU MDR Class IIa conformity requirements are forcing simultaneous redesign of safety mechanisms and sterilization protocols across manufacturing footprints. Suppliers must now engineer retractable shield systems while maintaining ISO 7864 cannula performance benchmarks.
Growth Catalysts
- Single-use safety mandates:OSHA's Bloodborne Pathogens Standard and comparable EU MDR requirements accelerate replacement cycles for conventional non-safety configurations in regulated markets.
- Oral surgery volume expansion:Ambulatory dental clinic networks in the United States are scaling procedural throughput for implantology and third-molar extraction.
- Finer gauge preference:30 gauge and 33 gauge specifications are displacing legacy 25 gauge inventory as patient comfort metrics penetrate procurement specifications.
Market Restraints
- Stainless steel price volatility:304-grade stainless steel input costs fluctuate with nickel and chromium commodity markets, compressing margin predictability for hub-and-cannula assemblers.
- High-volume manufacturer concentration:Automated line capacity clusters in East Asian manufacturing zones, creating geographic supply vulnerability for European and North American distributors.
- Ethylene oxide sterilization constraints:EPA emissions restrictions and residual gas limits extend production cycle times and require capital-intensive aeration infrastructure.
Strategic Opportunities
- Coated cannula penetration:Silicone and PTFE surface treatments reduce insertion force metrics, opening premium positioning in pediatric and geriatric dental practices.
- Leasing model expansion:Asset-light precision injection equipment leasing fragments procurement channels, lowering capital barriers for regional specialty distributors.
- EU Green Deal alignment:REACH chemical compliance and circular economy packaging mandates create first-mover advantage for bio-based hub materials and recyclable sterilization pouches.
Industry Challenges
- 510(k) pathway congestion:FDA review timelines for novel safety mechanisms extend market access delays, requiring parallel EU MDR conformity investments to sustain revenue continuity.
- Legacy hub incompatibility:Proprietary luer-lock geometries from dominant anesthesia delivery system manufacturers fragment standardization efforts and complicate aftermarket positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Needle Market |
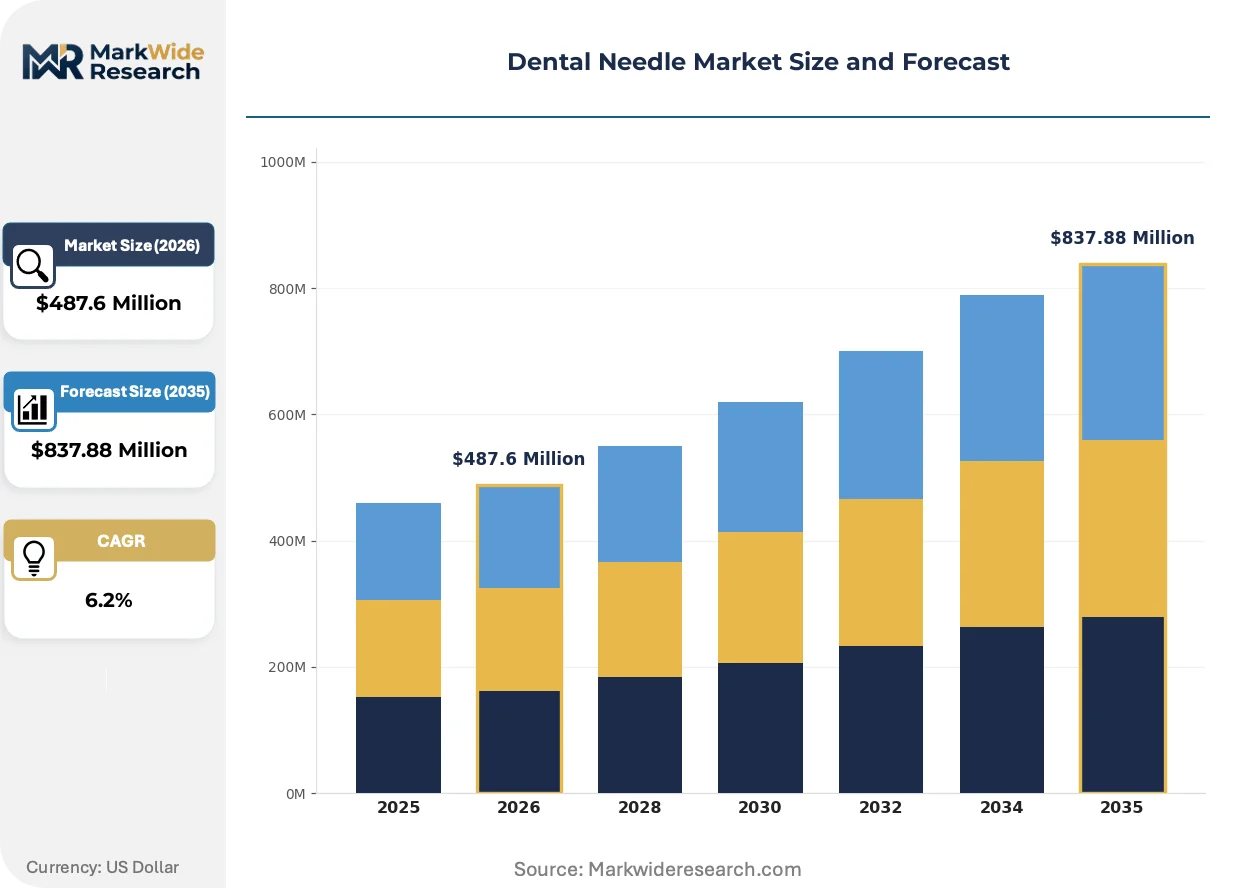
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $837.88 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Needles, Reusable Needles, Safety Needles, Conventional Needles Material: Stainless Steel, Plastic, Coated Metal, Alloy Needle Gauge: 30 Gauge, 27 Gauge, 25 Gauge, 21 Gauge End User: Dentists, Dental Clinics, Hospitals, Oral Surgeons |
| Companies Covered | Septodont, Dentsply Sirona, TERUMO Corporation, NIPRO Medical Corporation, Shinhung Co., Ltd, MORITA Corporation, EXELINT International, TSK Laboratory Europe B.V., Acteon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Needle Market Emerging Trajectories
Retractable safety mechanisms and passive shielding technologies are collapsing the traditional price-performance hierarchy between conventional and safety-engineered configurations. Material science advances in hub polymers and surface-coated cannulas are compressing the feature gap across specification tiers.
Silicone-coated 30 gauge cannulas are collapsing the force-differential advantage previously held by larger-bore conventional needles. Pediatric dental practices and anxiety-management clinics in Germany and Japan are adopting these configurations for infiltration anesthesia. The technology is collapsing premium pricing power for uncoated legacy gauges in comfort-sensitive segments.
EU MDR Class IIa conformity requirements and FDA 510(k) substantial equivalence pathways are diverging on biocompatibility testing protocols. Manufacturers now face parallel validation burdens for cytotoxicity and sensitization endpoints. Small-to-mid scale suppliers in Italy and Spain are consolidating regulatory affairs functions to manage dual-track submissions.
Group purchasing organizations and dental service organization networks are consolidating procurement decisions for multi-clinic footprints. Independent practitioners in the United Kingdom are losing price negotiation leverage as DSO-affiliated oral surgery departments centralize anesthesia supply contracts. This concentration is most visible in metropolitan clusters where hospital-affiliated dental residency programs anchor volume commitments.
Dental Needle Market Segmentation
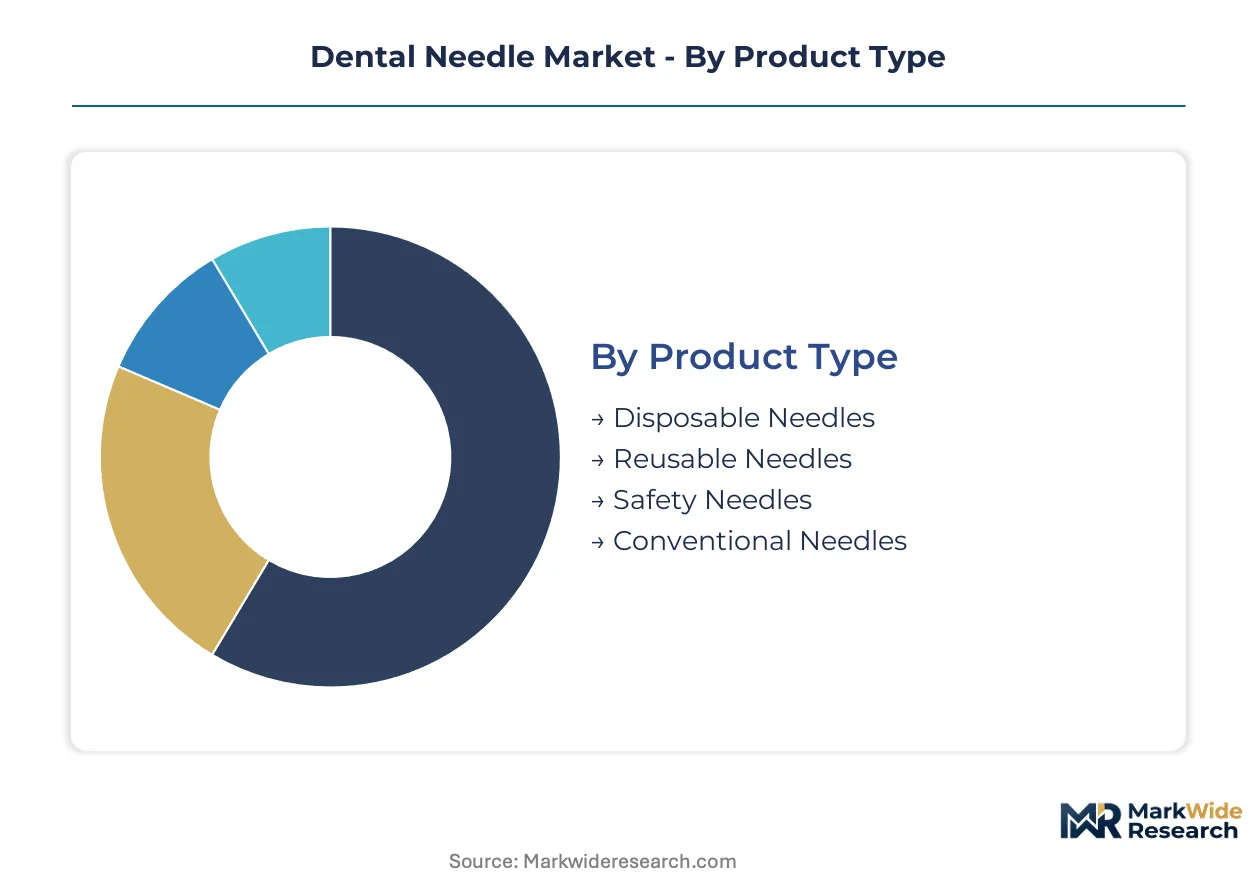
Dental needle procurement splits across safety mandates, material specifications, and clinical settings. Understanding these divisions reveals where margin pressure concentrates and which configurations command premium positioning.
Product Type:
Cost tier differentiation separates single-use disposable configurations from capital-intensive reusable systems and regulatory-driven safety variants.
- Safety Needles:Retractable shield and passive guard mechanisms satisfy OSHA Bloodborne Pathogens Standard and EU MDR Class IIa conformity requirements. US ambulatory dental clinic networks and hospital-affiliated oral surgery departments in Germany and Japan now specify these exclusively, with procurement contracts penalizing conventional alternatives.
- Disposable Needles:Polypropylene hubs married to 304-grade stainless steel cannulas dominate volume economics. These configurations absorb the procedural expansion in implantology and third-molar extraction across metropolitan dental service organization networks.
- Conventional Needles:Non-safety configurations retain footholds in cost-sensitive procurement channels where regulatory enforcement lags.
- Reusable Needles:Autoclavable metal hubs with replaceable cannula assemblies serve niche academic and military dental training programs with sterilization infrastructure.
Safety Needles holds installed capacity. Disposable Needles is rotating up the share rankings.
Material:
Application requirements drive material selection — tensile strength for penetration reliability, surface properties for insertion force reduction, and sterilization compatibility for reuse protocols.
- Stainless Steel:304-grade austenitic steel delivers tensile strength and ethylene oxide sterilization compatibility. This material anchors production across East Asian automated manufacturing zones supplying hospital oral surgery departments.
- Coated Metal:Silicone and PTFE surface treatments reduce insertion force metrics. Pediatric dental practices in Germany and anxiety-management clinics in Japan are adopting these for infiltration anesthesia where patient comfort metrics penetrate procurement specifications.
- Plastic:Polycarbonate and polypropylene hub polymers dominate disposable configurations, with bio-based variants emerging under EU Green Deal circular economy mandates.
- Alloy:Nickel-titanium formulations enable superelastic properties for specialized block anesthesia applications in oral surgery residency programs.
Stainless Steel holds installed capacity. Coated Metal is climbing the fastest.
Needle Gauge:
Volume and patient comfort metrics are displacing legacy specifications as finer dimensions penetrate procurement standards.
- 30 Gauge:Ultra-fine cannulas with silicone coatings are collapsing the force-differential advantage previously held by larger-bore conventional needles. These specifications dominate infiltration anesthesia in comfort-sensitive segments.
- 27 Gauge:The workhorse dimension for block anesthesia balances flow rate requirements with tissue trauma minimization. This specification leads clinical preference across US dental clinic networks.
- 25 Gauge:Legacy inventory in cost-sensitive markets faces accelerated replacement cycles as finer gauges gain formulary preference.
- 21 Gauge:Larger-bore configurations retain utility for high-viscosity anesthetic delivery and specific oral surgery applications.
27 Gauge holds installed capacity. 30 Gauge is gaining share fastest.
End User:
Customer type determines procurement channel structure — centralized purchasing for institutional networks versus fragmented decision-making for independent practitioners.
- Dental Clinics:Ambulatory networks and group purchasing organizations consolidate anesthesia supply contracts across multi-clinic footprints. These entities now specify safety-engineered configurations as standard.
- Hospitals:Hospital-affiliated oral surgery departments anchor volume commitments with centralized procurement through integrated delivery networks.
- Dentists:Independent practitioners in the United Kingdom and smaller European markets are losing price negotiation leverage as dental service organization concentration advances.
- Oral Surgeons:Specialized procedural requirements for implantology and third-molar extraction drive premium specification adoption.
Dental Clinics holds installed capacity. Hospitals is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German dental clinics while US procurement consolidation squeezes distributor margins. Japanese manufacturers capture premium positioning through coated cannula technology. Emerging volume shifts toward ambulatory networks in Spain and South Korea reshape regional competitive dynamics.
United States
Ambulatory dental clinic networks and hospital-affiliated oral surgery departments anchor procurement volume. OSHA's Bloodborne Pathogens Standard mandates single-use safety needle specifications across all covered employment settings. Metropolitan clusters in Texas and Florida concentrate dental service organization headquarters where centralized purchasing contracts penalize conventional non-safety configurations.
Germany
Pediatric dental practices and anxiety-management clinics drive coated cannula adoption for infiltration anesthesia. EU MDR Class IIa conformity requirements and REACH chemical compliance obligations constrain material selections and sterilization protocols. The Baden-Württemberg industrial corridor hosts precision metalworking suppliers serving hub-and-cannula assemblers with ISO 7864 testing capabilities.
Japan
Comfort-sensitive patient demographics accelerate 30 gauge and 33 gauge specification penetration. METI industrial standards and PMDA medical device regulations govern biocompatibility testing protocols for silicone surface treatments. The Osaka-Kobe manufacturing zone sustains automated production lines supplying hospital oral surgery departments across multiple continents.
Spain
Independent practitioners in Madrid and Barcelona face eroding price negotiation leverage as group purchasing organizations consolidate anesthesia supply contracts. EU Green Deal circular economy mandates create first-mover advantage for bio-based hub materials and recyclable sterilization pouches. The Catalonia medical device cluster attracts regulatory affairs consolidation among small-to-mid scale suppliers managing dual-track FDA and EU MDR submissions.
South Korea
Cosmetic dentistry volume expansion and implantology procedural growth expand the addressable base for specialized needle configurations. MFDS medical device regulations align with international standards while maintaining distinct documentation requirements. The Seoul Capital Area concentrates precision injection equipment leasing operations that fragment procurement channels for regional specialty distributors.
Dental Needle Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream capturing margin through captive cannula production or proprietary hub geometries. The vendor base arranges across three tiers: diversified dental equipment conglomerates with anesthesia delivery ecosystems, mid-scale safety-engineering specialists with regional regulatory expertise, and high-volume automated manufacturers supplying hospital oral surgery departments. Strategic differentiation clusters around backward integration into stainless steel supply, proprietary luer-lock compatibility, and dual-track FDA-EU regulatory capacity. Competitive moves concentrate on portfolio rationalization under diverging biocompatibility testing protocols and geographic expansion through asset-light leasing model partnerships.
Among diversified platform operators, Dentsply Sirona and Septodont exemplify contrasting integration strategies. Dentsply Sirona anchors system-tier positioning through proprietary hub designs that integrate with broader anesthesia delivery ecosystems. Septodont represents backward integration archetypes with captive stainless steel cannula production sustaining margin control across European dental clinics. TERUMO Corporation occupies the scale-driven manufacturing tier, with high-volume automated lines supplying hospital oral surgery departments across multiple continents. These three patterns—system integration, upstream supply control, and manufacturing scale—define the competitive fault lines reshaping procurement relationships.
| Leading Market Players |
|---|
| Septodont |
| Dentsply Sirona |
| TERUMO Corporation |
| NIPRO Medical Corporation |
| Shinhung Co., Ltd |
| MORITA Corporation |
| EXELINT International |
| TSK Laboratory Europe B.V. |
| Acteon |
| Others |
Supply Flow & Price Mechanics
The Osaka-Kobe manufacturing zone anchors global production capacity for precision cannula assemblies, with automated line concentration there translating directly into pricing leverage for hospital oral surgery departments across multiple continents. East Asian supply dominance compresses margin buffers for European and North American distributors who lack captive stainless steel processing or proprietary hub geometries.
Pricing Analysis
The customization-premium spread separates standard disposable configurations from silicone-coated specialty gauges and proprietary luer-lock integrated systems. Three-tier pricing structure across premium, standard, and economy levels stratifies by safety mechanism complexity and cannula surface treatment, with coated 30 gauge variants commanding position in pediatric and geriatric channels. Cost compression in the conventional non-safety tier is intensifying because group purchasing organizations centralize anesthesia supply contracts across multi-clinic footprints. Independent practitioners exhibit highest price sensitivity, while hospital-affiliated oral surgery departments prioritize safety specification compliance over unit cost.
Supply Chain Analysis
Tariff exposure between East Asian manufacturing zones and North American distribution hubs dominates supply chain risk calculations for hub-and-cannula assemblers. Production gravity centers on Japan, South Korea, and China, with 304-grade stainless steel and polypropylene hub polymers drawing from commodity markets subject to nickel and chromium price volatility. Single-source vulnerability concentrates in automated sterilization infrastructure, where ethylene oxide aeration capacity clusters constrain throughput. Distribution runs through dental service organization networks and group purchasing organizations that consolidate procurement decisions for metropolitan clinic clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dental needle market sits at a platform-economics inflection where proprietary anesthesia delivery ecosystems are collapsing aftermarket positioning for non-integrated suppliers. Interoperability requirements around luer-lock geometries and dual-track FDA-EU regulatory capacity are redefining competitive moats.
For Market Incumbents: Harden regulatory affairs infrastructure to manage diverging FDA 510(k) and EU MDR biocompatibility testing protocols. Backward integration into stainless steel cannula production defends margin control against commodity input volatility. Captive supply of coated metal surface treatments protects positioning in comfort-sensitive pediatric and geriatric segments.
For New Entrants and Emerging Players: Establish a beachhead in asset-light precision injection equipment leasing channels that fragment procurement relationships for regional specialty distributors. EU Green Deal circular economy mandates create white-space for bio-based hub materials and recyclable sterilization pouches. Target anxiety-management clinics in Germany and Japan with silicone-coated 30 gauge configurations as a differentiated go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because dual-track regulatory capacity scarcity will force portfolio rationalization among small-to-mid scale Italian and Spanish suppliers. Acquisition targets should display captive cannula production or proprietary hub geometries integrated with anesthesia delivery ecosystems. The signal to watch is OSHA enforcement intensity for Bloodborne Pathogens Standard compliance across ambulatory dental clinic networks.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Supply | Captive cannula production insulates margin control from nickel and chromium commodity volatility. |
| Dual-Track FDA-EU Regulatory Capacity Buildout | Parallel 510(k) and MDR conformity investments sustain revenue continuity amid pathway divergence. |
| Silicone Surface Treatment Certification | PMDA and METI biocompatibility validation unlocks premium positioning in Japanese anxiety-management clinics. |
| Asset-Light Leasing Model Partnerships | Regional distributor fragmentation lowers capital barriers and reshapes procurement channel structures. |
| Bio-Based Hub Material Development | REACH compliance and EU Green Deal alignment creates first-mover advantage in circular economy packaging. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dental clinic procurement managers, hospital oral surgery department heads, biomedical engineers at GPOs, regulatory affairs leads at hub-and-cannula assemblers, and distribution channel partners. Secondary validation drew from FDA 510(k) filings, EU MDR conformity assessment databases, OSHA enforcement records, ISO 7864 testing protocols, and hospital procurement contract disclosures. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Calibration anchored on historical procedural volume trajectories in oral surgery and implantology, with segmentation modeling across safety mechanism type, cannula material specification, gauge dimension, and end-user procurement channel. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity expansion announcements. Industry-specific inputs included ethylene oxide sterilization throughput constraints and REACH chemical compliance cost pass-through assumptions.
Stress conditions across stainless steel commodity volatility, EPA emissions restriction intensity, and dental service organization consolidation pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement trajectories and procedural volume elasticity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Titanium Dental Implants Market
Dental Devices
Turkey CAD/CAM Dental Devices Market
Dental Devices
Guided Biofilm Therapy Market
Dental Devices
South Africa Dental Devices Market
Dental Devices
North America Dental Lasers Market
Dental Devices
Prophy Dental Handpiece Market
Dental Devices
Dental Prosthetics Market
Dental Devices
United Kingdom Dental Devices Market
Dental Devices
3D-Printed Dental Restoration Market
Dental Devices
Nano Dentistry Market
Dental Devices
Plaque Disclosing Aids Market
Dental Devices
Dental CAD Market
Dental Devices
Latin America Dental Devices Market
Dental Devices
Dental Anaesthetic Market
Dental Devices
Global Dental Lasers Market
Dental Devices
Europe Dental Implants and Prosthetics Market