
 Dental CAD/CAM Market | 2026-2036
Dental CAD/CAM Market Size, Share, and Industry Trends Forecast 2026-2036
Dental CAD/CAM Market Analysis
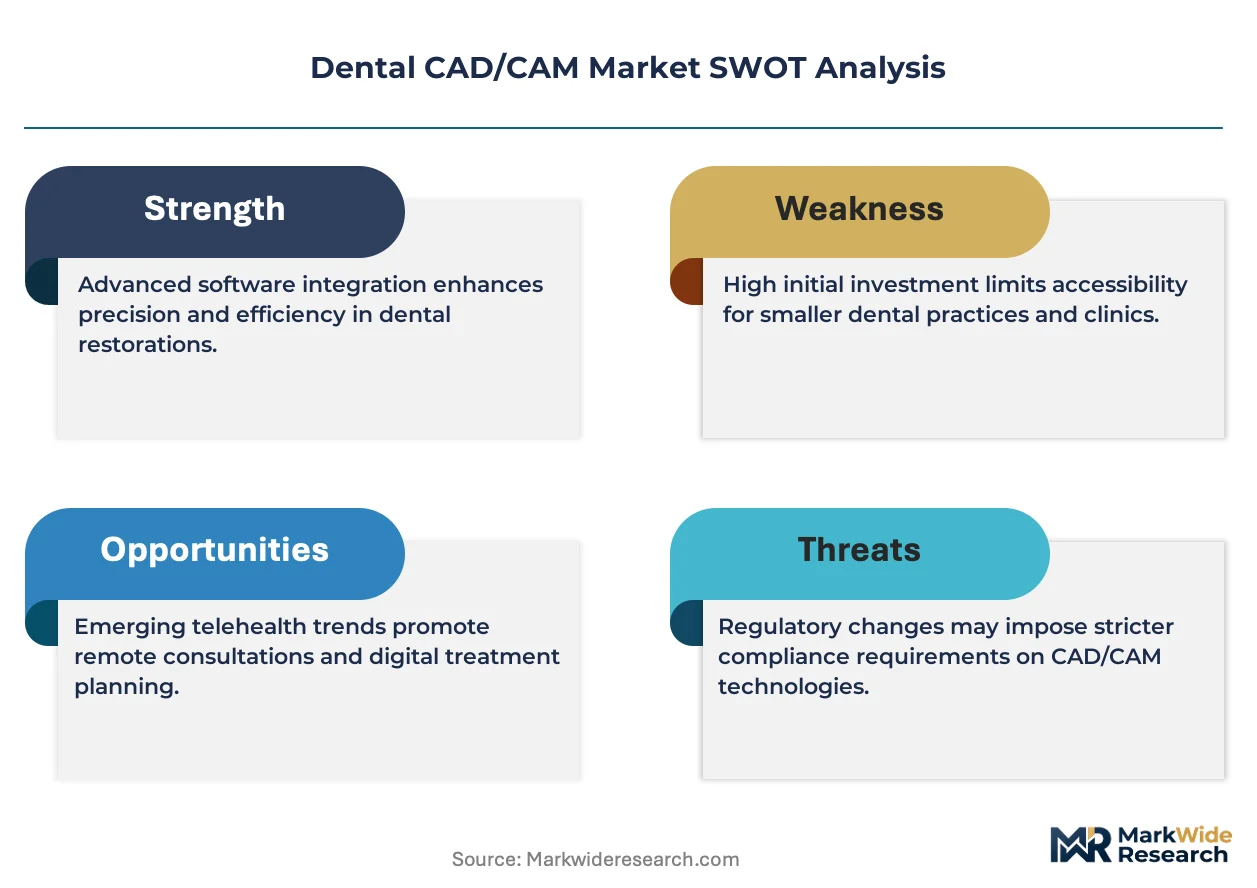
Buyer concentration among dental laboratories is decoupling from traditional solo-practice procurement as multi-site dental service organizations expand in-house milling capacity. Dentsply Sirona leverages its integrated scanner-to-mill ecosystem to anchor enterprise contracts. 3Shape A/S competes through open-architecture software that accommodates third-party hardware. Straumann Holding AG sustains premium positioning via proprietary material-scanner compatibility.
Dental CAD/CAM encompasses computer-aided design and computer-aided manufacturing systems for digital dental restoration production, typically operating with sub-50-micron accuracy across ceramic, resin, and metal substrates to fabricate crowns, bridges, and prosthetic frameworks. Hardware dominates current revenue as intraoral scanner replacements drive recurring capital expenditure, while software margins expand fastest through subscription-based treatment planning modules. Milling technology retains installed-base dominance though 3D printing displaces it for full-arch denture production where polymerization speed improves throughput.
FDA 510(k) premarket notification requirements govern scanner and mill classifications in the United States, while EU MDR and CE marking obligations extend conformity assessment burdens for European market access. ISO 13485 quality management certification shapes supplier qualification criteria for dental laboratory procurement teams. Stakeholders must monitor harmonization gaps between FDA digital dentistry guidance and evolving EU AI Act implications for automated crown-design algorithms.
Market Dynamics
Multi-site dental service organizations are decoupling procurement from solo practices, forcing suppliers to restructure pricing and service architectures around enterprise-scale milling contracts rather than individual chairside unit sales.
Growth Catalysts
- FDA 510(k) pathway streamlining:The premarket notification framework for Class II scanners and mills accelerates product launch timelines, compressing development-to-revenue cycles for hardware manufacturers targeting the United States.
- Chairside polymerization speed gains:Photopolymer resins with sub-10-second layer cure times enable same-day full-arch denture delivery, expanding addressable procedure volume beyond traditional crown-and-bridge fabrication.
- German laboratory consolidation:Dense clusters of mid-to-large dental labs in Bavaria and North Rhine-Westphalia generate concentrated demand for automated five-axis milling centers with unmanned overnight operation capability.
Market Restraints
- Zirconia powder supply concentration:Ceramic precursor manufacturing concentrates among Japanese and Chinese chemical suppliers, exposing mill operators to input cost volatility and long-order-lead inventory requirements.
- EU MDR conformity assessment burden:The extended clinical evaluation and notified body review timelines for scanner software algorithms delay European market access by 12-18 months relative to FDA-cleared equivalents.
- Sub-50-micron accuracy ceiling:Mechanical milling tolerances plateau against biological fit requirements for implant-abutment interfaces, ceding precision-critical applications to electrical discharge machining.
Strategic Opportunities
- India's import substitution push:The PLI scheme for medical devices creates manufacturing cost advantages for domestic milling center assembly, positioning local producers to serve price-sensitive Southeast Asian laboratory markets.
- AI-Act-compliant automated design:Conformity with EU artificial intelligence risk-classification requirements for diagnostic algorithms opens premium positioning for crown-design software with embedded anatomical libraries.
- Subscription-based treatment planning:Cloud-hosted case management platforms replace perpetual licenses, generating recurring revenue streams and reducing upfront capital barriers for small laboratory adoption.
Industry Challenges
- CAD/CAM technician certification gaps:ISO 13485 quality management implementation requires specialized training that outpaces vocational program output, constraining laboratory scaling.
- Legacy scanner data migration:Proprietary file formats from first-generation intraoral systems resist interoperability with modern mill control software, forcing costly case-by-case reconstruction.
- Five-axis mill maintenance specialization:Spindle calibration and ball-screw replacement demand vendor-certified technicians with limited geographic availability, extending equipment downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental CAD/CAM Market |
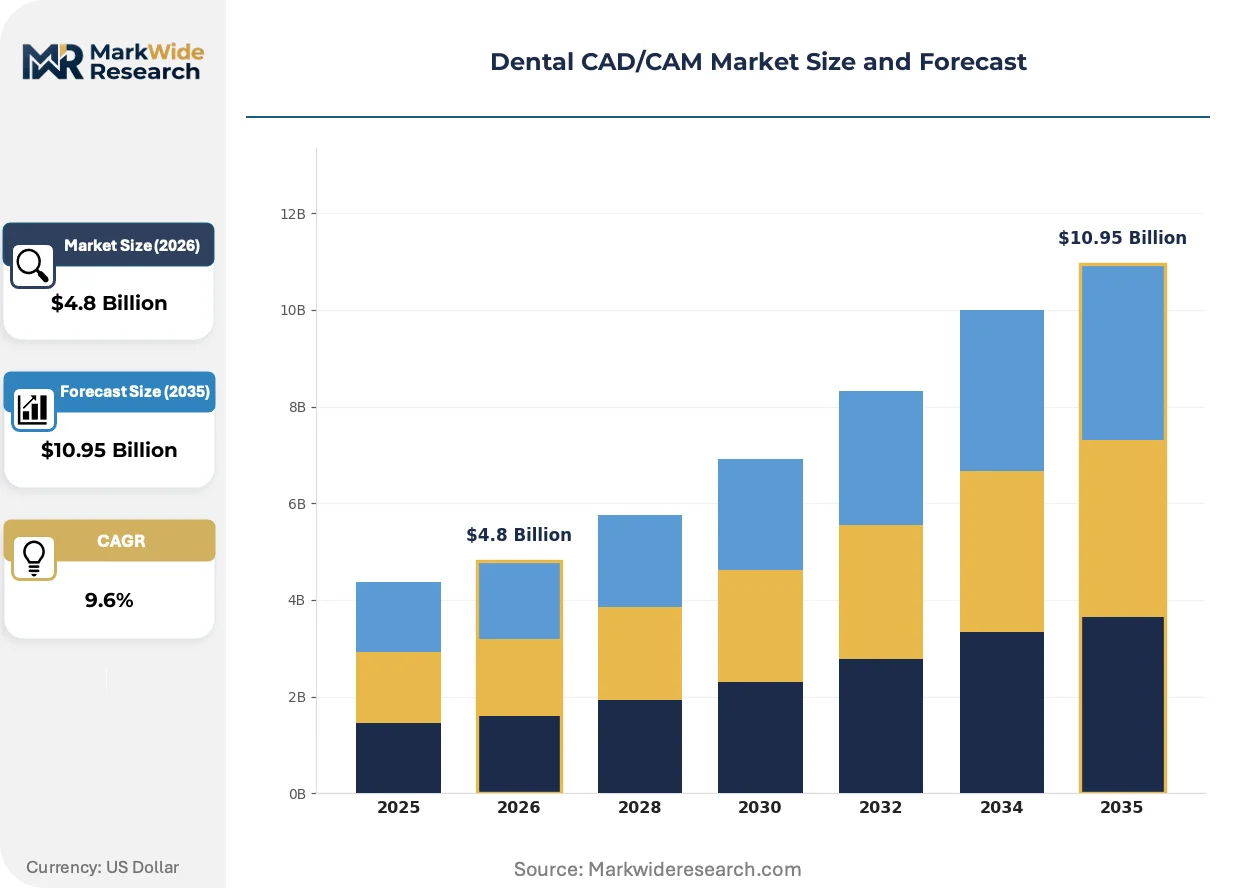
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.95 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Materials End User: Dentists, Dental Laboratories, Orthodontists, Oral Surgeons Technology: 3D Printing, Milling, Scanning, Imaging Application: Crowns, Bridges, Dentures, Inlays |
| Companies Covered | Planmeca Group, Align Technology, Dentsply Sirona, Amann Girrbach, Roland DG Corporation, Ivoclar Vivadent, Straumann Holding AG, imes-icore, 3Shape A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental CAD/CAM Market Emerging Trajectories
Digital workflow integration is compressing restoration delivery timelines while regulatory frameworks for algorithmic design reshape software competitive moats across major markets.
Photopolymer vat polymerization is consolidating its position in full-arch denture production. Large dental laboratories in the United States and Germany are replacing subtractive milling for polymer-based appliances, driven by 4x throughput advantages and material cost reductions. This consolidation is compressing equipment supplier margins in the denture segment while expanding resin formulation specialist influence.
EU MDR and the emerging EU AI Act are creating dual conformity obligations for automated crown-design software. Manufacturers must now document clinical performance evidence for algorithmic anatomical suggestions alongside traditional device safety. European laboratories are prioritizing suppliers with established notified body relationships, disadvantaging newer market entrants lacking MDR transition experience.
After-sales service unbundling is disrupting traditional hardware vendor economics. Dental laboratories in China increasingly procure third-party maintenance contracts and software subscriptions separately from capital equipment, fragmenting supplier revenue streams. This pattern is most pronounced in Shanghai and Shenzhen, where independent technical service providers have achieved critical mass.
Dental CAD/CAM Market Segmentation
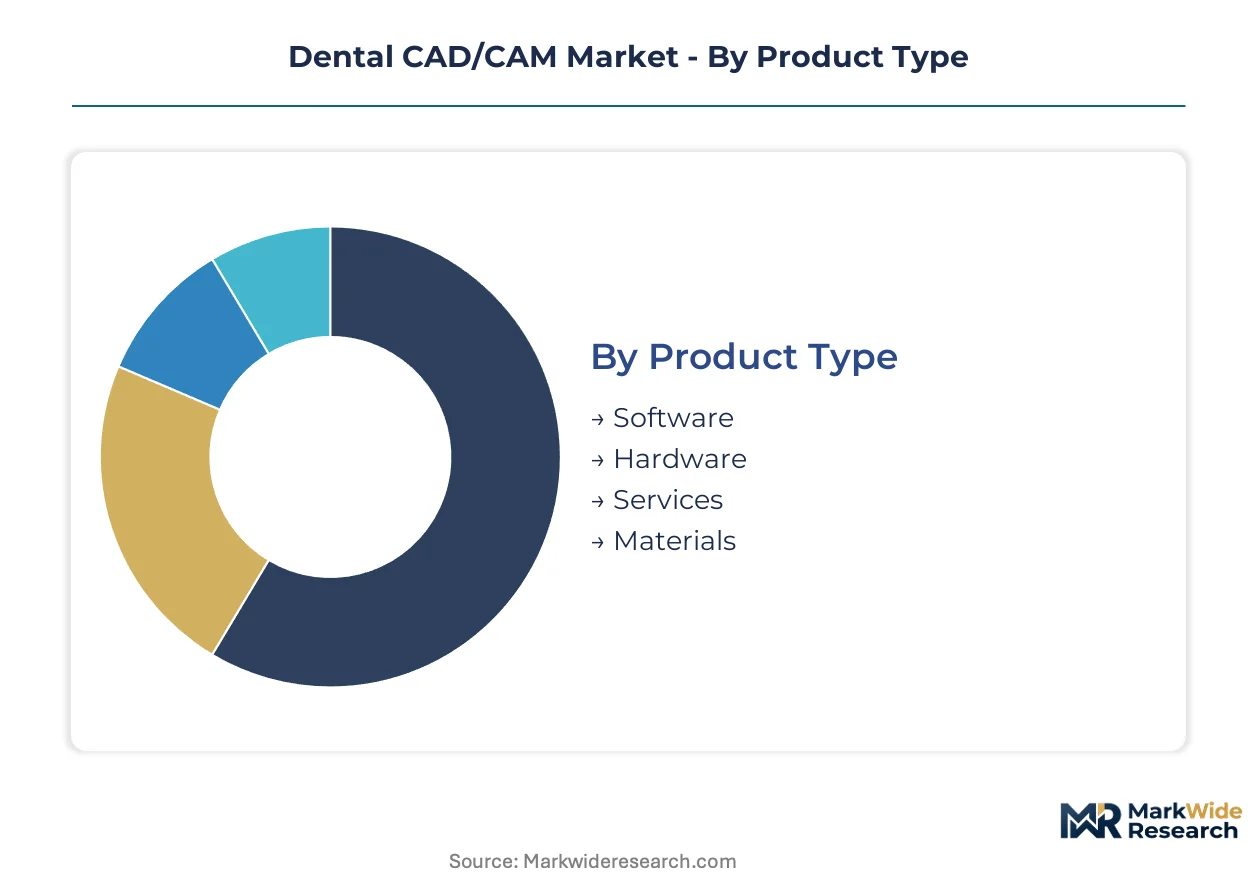
Dental CAD/CAM procurement patterns diverge sharply across user scale and restoration complexity. Equipment replacement cycles, software licensing models, and material compatibility requirements create distinct value pools that suppliers must address through differentiated positioning.
Product Type:
Intraoral scanner refresh rates drive capital expenditure timing, with laboratories upgrading hardware every four to six years to maintain competitive turnaround speeds.
- Hardware:Intraoral scanners, five-axis milling units, and 3D printers constitute the dominant capital outlay category. German dental laboratories in Bavaria and North Rhine-Westphalia anchor demand for automated five-axis systems with unmanned overnight operation capability.
- Software:Treatment planning modules, design automation platforms, and mill control interfaces generate recurring subscription revenue. Cloud-hosted case management adoption is climbing fastest among United States multi-site dental service organizations seeking reduced upfront capital barriers.
- Services:Installation, calibration, maintenance contracts, and technician training support equipment lifecycle performance. Vendor-certified spindle calibration specialists remain geographically concentrated, extending downtime for laboratories outside major metropolitan clusters.
- Materials:Zirconia blocks, photopolymer resins, and metal substrates determine restoration mechanical properties and aesthetic outcomes. Ceramic precursor supply concentrates among Japanese and Chinese chemical suppliers, exposing mill operators to input cost volatility.
Hardware sits at the top of the volume ranking, with software climbing the fastest.
End User:
Procurement authority is consolidating as multi-site dental service organizations internalize production capacity previously outsourced to independent laboratories.
- Dental Laboratories:Mid-to-large facilities in Germany and the United States deploy enterprise-scale milling centers for high-throughput crown and bridge fabrication. These operations prioritize ISO 13485-certified suppliers for quality management compliance.
- Dentists:Chairside systems enable same-day restoration delivery in solo and group practices. Photopolymer resins with sub-10-second layer cure times are expanding addressable procedure volume beyond traditional crown-and-bridge applications.
- Orthodontists:Clear aligner production and indirect bonding tray fabrication drive specialized scanner and printer demand. Digital workflow integration compresses treatment planning timelines while requiring orthodontic-specific software modules.
- Oral Surgeons:Implant surgical guide production and custom abutment design require sub-50-micron accuracy for biological fit. Precision-critical applications are ceding ground to electrical discharge machining for implant-abutment interfaces.
Dental laboratories command the largest installed base, with dentists gaining share fastest through chairside system adoption.
Technology:
Process selection hinges on restoration geometry complexity, material requirements, and throughput economics rather than universal platform substitution.
- Milling:Subtractive machining retains dominance for ceramic and metal restorations requiring high flexural strength. Five-axis systems with automated tool changers support unmanned production runs in high-volume German laboratories.
- 3D Printing:Vat polymerization and material jetting consolidate position in full-arch denture production. Large United States laboratories are replacing subtractive milling for polymer-based appliances, driven by throughput advantages and material cost reductions.
- Scanning:Intraoral and laboratory benchtop systems capture digital impressions with sub-50-micron accuracy. Proprietary file formats from first-generation systems resist interoperability with modern mill control software, forcing costly case reconstruction.
- Imaging:CBCT integration enables implant planning and surgical guide design within unified workflows. FDA 510(k) premarket notification requirements govern scanner classifications in the United States, accelerating product launch timelines relative to EU MDR pathways.
Milling maintains the largest equipment installed base, with 3D printing expanding most quickly in denture applications.
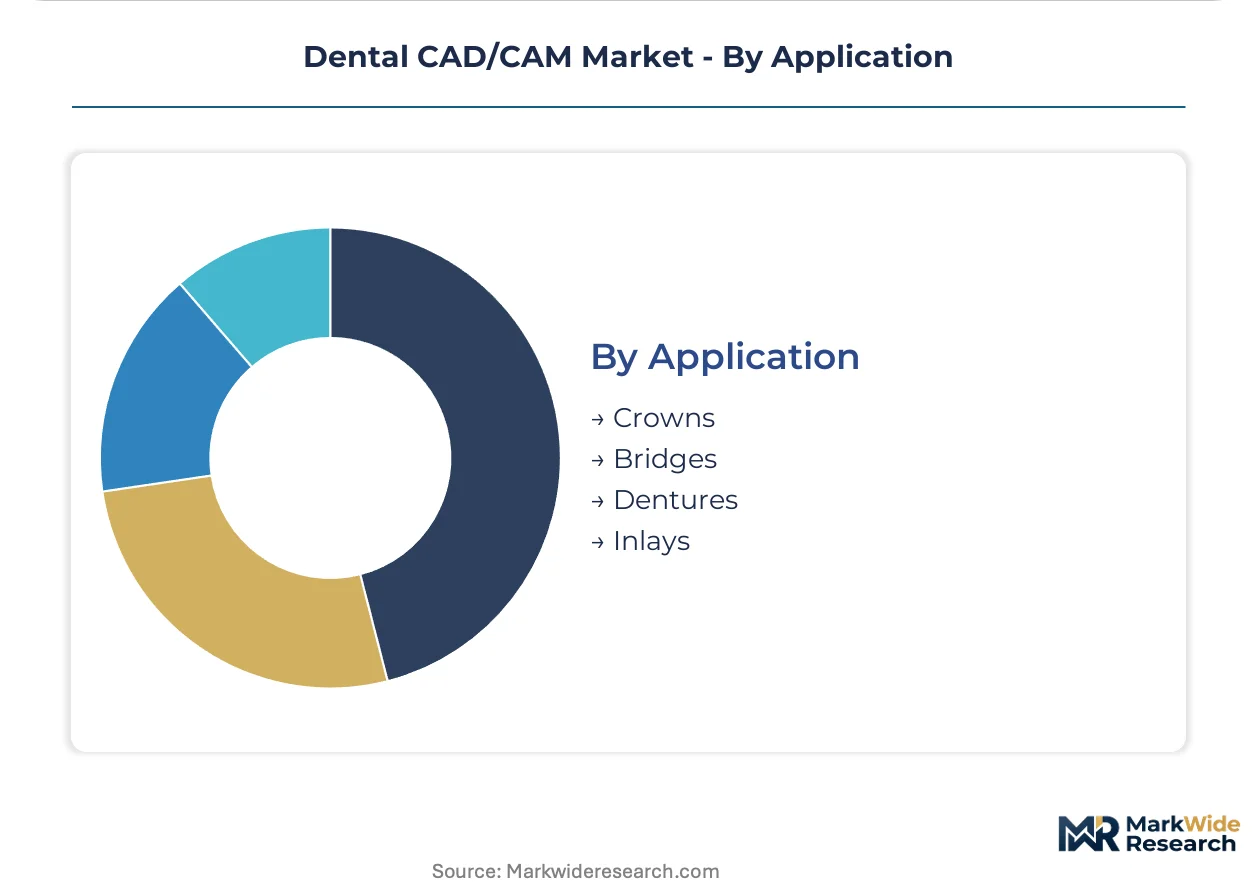
Application:
Restoration type dictates material selection, manufacturing process, and regulatory classification requirements across major markets.
- Crowns:Single-unit restorations represent the highest procedure volume category, fabricated from zirconia, lithium disilicate, or hybrid ceramics. German laboratory consolidation concentrates demand for automated production systems.
- Bridges:Multi-unit fixed prostheses require connector strength verification and occlusal load distribution analysis. Milling technology dominates due to material property requirements for span rigidity.
- Dentures:Full-arch removable appliances are shifting rapidly to photopolymer vat polymerization. Large United States and German laboratories drive equipment displacement as polymerization speed improves throughput economics.
- Inlays:Conservative restorations leverage CAD/CAM for precise cavity adaptation and minimal invasive preparation. Chairside milling systems in dentist offices target this application for same-day delivery.
Crowns lead procedure volume, with dentures showing the steepest technology-transition trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's laboratory consolidation outpaces United States chairside adoption, while China scales domestic manufacturing capacity through targeted industrial policy. Demand clusters concentrate where dental service organizations internalize production and regulatory pathways accelerate product clearance.
United States
Multi-site dental service organizations in Texas and Florida are deploying enterprise-scale milling centers, displacing independent laboratory outsourcing. FDA 510(k) premarket notification pathways compress hardware launch timelines relative to European equivalents. Dallas and Houston anchor demand for automated five-axis systems with unmanned overnight operation capability.
Germany
Bavarian and North Rhine-Westphalian laboratories drive concentrated demand for high-throughput crown and bridge fabrication systems. EU MDR conformity assessment requirements extend software algorithm review timelines, favoring established notified body relationships. Stuttgart and Munich clusters prioritize ISO 13485-certified suppliers for quality management compliance.
China
Shanghai and Shenzhen laboratories increasingly unbundle after-sales service from capital equipment procurement, fragmenting supplier revenue streams. The PLI scheme for medical devices creates manufacturing cost advantages for domestic milling center assembly. Pearl River Delta producers target price-sensitive Southeast Asian laboratory markets.
India
Maharashtra and Gujarat dental laboratories scale CAD/CAM technician training programs to address ISO 13485 certification gaps constraining industry expansion. CDSCO medical device regulations align with international quality standards, facilitating export-oriented production. Mumbai and Ahmedabad clusters attract contract manufacturing for European and North American equipment vendors.
Japan
Tokyo and Osaka metropolitan laboratories prioritize sub-50-micron accuracy systems for implant-abutment interface applications. PMDA regulatory frameworks govern scanner and mill classifications, with harmonization efforts reducing duplication with FDA pathways. Kanto region dental schools integrate CAD/CAM curricula to address technician pipeline constraints.
Dental CAD/CAM Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware, software, and materials verticals. The vendor base stratifies into three tiers: integrated ecosystem providers commanding enterprise contracts, open-architecture software houses accommodating third-party hardware, and regional equipment fabricators serving price-sensitive markets. Dominant competitive moves include strategic partnerships bridging scanner-to-mill workflows and backward integration into proprietary material formulations.
Within the integrated ecosystem tier, Dentsply Sirona and Straumann Holding AG occupy positions defined by captive material-scanner compatibility and end-to-end workflow control. 3Shape A/S exemplifies the open-architecture archetype, with Copenhagen-based software development supporting multi-vendor hardware interoperability. Roland DG Corporation and imes-icore represent German and Japanese precision manufacturing heritage respectively, anchoring regional equipment supply with five-axis milling specialization.
| Leading Market Players |
|---|
| Planmeca Group |
| Align Technology |
| Dentsply Sirona |
| Amann Girrbach |
| Roland DG Corporation |
| Ivoclar Vivadent |
| Straumann Holding AG |
| imes-icore |
| 3Shape A/S |
| Others |
Supply Flow & Price Mechanics
Multi-site dental service organizations in Texas and Florida are consolidating procurement authority, compressing hardware margins and forcing suppliers toward subscription-based software pricing models with multi-year enterprise lock-in terms.
Pricing Analysis
Capacity additions in China through the PLI scheme for medical devices are reshaping price floors for five-axis milling centers, intensifying cost competition in Southeast Asian laboratory markets. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified systems from uncertified alternatives and used-equipment channels. Price differentiation hinges on after-sales service bundling and FDA 510(k) clearance status. Small dental laboratories in India exhibit highest price sensitivity, while German mid-to-large facilities prioritize unmanned overnight operation capability over upfront capital outlay.
Supply Chain Analysis
Freight cost volatility from Japanese and Chinese ceramic precursor suppliers extends inventory carrying requirements for zirconia block-dependent mill operators. Zirconia powder manufacturing concentrates in Japan and China, with photopolymer resin formulation anchored in Germany and the United States. Raw material dependencies span yttria-stabilized zirconia, high-purity alumina, and photoinitiator compounds. Single-source vulnerability in Japanese chemical supply exposes operators to input cost swings. Distribution runs through authorized dealer networks in developed markets and direct procurement platforms in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU MDR conformity assessment burdens extend European market access timelines by 12-18 months relative to FDA-cleared equivalents, creating cost and timing advantages for United States-first product launches.
For Market Incumbents: Acquire cloud-hosted case management platforms to anchor recurring revenue streams against hardware margin compression. Consolidate notified body relationships to defend European market position against MDR transition delays threatening newer entrants. Prioritize backward integration into proprietary zirconia formulations to offset Japanese and Chinese chemical supplier concentration. For New Entrants and Emerging Players: Independent technical service providers in Shanghai and Shenzhen represent the most accessible channel partner type for aftermarket service unbundling strategies. Target India's price-sensitive laboratory market through PLI scheme-qualified domestic assembly partnerships. White-space exists in orthodontic-specific software modules for clear aligner production workflows. For Investors and Strategic Acquirers: Dental service organizations are the most active acquirer in this space, consolidating in-house milling capacity across multi-site footprints. Long-term viability rests on software subscription attach rates rather than hardware shipment volumes. Watch for FDA-EU MDR harmonization progress as inflection indicator for regulatory arbitrage window closure.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Investment | Automated crown-design algorithms gain premium positioning through conformity with risk-classification requirements. |
| Cloud Subscription Migration | Recurring revenue models reduce upfront capital barriers for small laboratory adoption in the United States. |
| Five-Axis Mill Localization | PLI scheme advantages in India enable cost-competitive export production for Southeast Asian markets. |
| Photopolymer Resin Formulation | Sub-10-second layer cure times expand addressable procedure volume beyond traditional crown applications. |
| Notified Body Relationship Building | Established MDR assessment partnerships accelerate European market access relative to inexperienced competitors. |
Methodological Framework
Multiple input streams — primary interviews with dental laboratory directors, equipment procurement managers, and CAD/CAM technicians; secondary validation through FDA 510(k) filings, EU MDR notified body databases, and dental industry trade publications; plus customs and trade flow records — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, end user scale, technology process, application complexity, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis, software subscription attach rate trajectories, and material consumption intensity per restoration type.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR-MDR harmonization gaps, zirconia supply concentration disruptions, and photopolymer cure-speed technology thresholds. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
3D Printing Dental Device Market
Dental Devices
Dental Sealants Market
Dental Devices
Prophylaxis Pastes Market
Dental Devices
Intraoral Dental Sensors Market
Dental Devices
Global Dental Hygiene Devices Market
Dental Devices
Europe Dental Implants Market
Dental Devices
Dental Veneers Market
Dental Devices
United Kingdom Dental Devices Market
Dental Devices
United States Dental Implants Market
Dental Devices
Endodontics and Orthodontics Market
Dental Devices
Dental Microsurgery Market
Dental Devices
North America Dental Lasers Market
Dental Devices
3D Printed Clear Dental Aligners Market
Dental Devices
Dental Handpieces Market
Dental Devices
Single Tooth Implants and Dental Bridges Market
Dental Devices
Dental Composite Resin Filling Market