
 3D Printed Clear Dental Aligners Market | 2026-2036
3D Printed Clear Dental Aligners Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printed Clear Dental Aligners Market Outlook
Pay-per-aligner leasing and asset-light chairside production models is rewriting competitive economics for smaller dental practices. Align Technology leverages its scanner-to-aligner ecosystem to sustain premium positioning across orthodontist channels. SmileDirectClub competes through teledentistry-linked remote monitoring that reduces chair time. Dentsply Sirona anchors its presence via integrated CAD/CAM hardware and consumable bundling with dental equipment fleets.
3D printed clear dental aligners are custom-fabricated orthodontic appliances produced through additive manufacturing of biocompatible photopolymer resins, typically achieving layer resolutions below 50 microns to ensure precise tooth movement tracking and patient comfort. These devices function as sequential removable trays that apply calibrated orthodontic force to reposition teeth according to digital treatment plans. Invisible aligners dominate volume as the primary aesthetic alternative to fixed braces, while polyurethane and copolyester materials capture margin pools through superior clarity and stress-retention properties. DLP manufacturing technology leads in chairside adoption due to faster print speeds compatible with same-day patient workflows.
FDA 510(k) clearance requirements for direct-print dental devices and EU MDR Class IIa medical device regulations govern material biocompatibility, print validation, and clinical evidence standards for market access. ISO 13485 quality management systems and FDA quality system regulation compliance shape manufacturing scalability and supplier qualification processes for aligner resin producers. Stakeholders must monitor evolving FDA guidance on point-of-care 3D printing and EU notified body capacity constraints as these will determine which production models achieve sustainable regulatory approval.
Market Dynamics
Direct-print chairside manufacturing is collapsing traditional centralized aligner production timelines, compressing patient turnaround from weeks to hours and redistributing value capture toward dental practices with capital equipment deployment.
Growth Catalysts
- FDA 510(k) Clearance Pathways:Streamlined premarket notification for direct-print dental devices accelerates chairside technology adoption across US orthodontic practices.
- Polyurethane-Copolyester Material Advances:Next-generation photopolymer resins deliver superior optical clarity and stress retention for precise orthodontic force application.
- Digital Dentistry Infrastructure Buildout:Germany, China, and the United States invest in intraoral scanner networks and clinical workforce training on same-day 3D printing workflows.
Market Restraints
- Photopolymer Resin Supply Concentration:Specialized biocompatible aligner materials depend on a limited supplier base concentrated in North American and European chemical producers.
- EU MDR Class IIa Compliance Burden:Custom medical appliance regulations demand extensive clinical evidence and notified body review, extending approval timelines for new market entrants.
- Fixed Braces Substitution Persistence:Complex malocclusion cases and price-sensitive patient segments continue selecting traditional orthodontic appliances for severe corrections.
Strategic Opportunities
- China Digital Dentistry Expansion:Underpenetrated tier-two and tier-three cities present whitespace for chairside 3D printing deployment as dental clinic chains consolidate.
- Teledentistry-Remote Monitoring Convergence:Integration of intraoral scanning with asynchronous clinical oversight reduces mandatory chair time and expands addressable patient geography.
- Pay-per-Aligner Leasing Models:Asset-light production structures enable smaller practices to access DLP manufacturing without upfront capital commitment.
Industry Challenges
- ISO 13485 Quality Management Implementation:Dental practices transitioning to in-house production face complex documentation and validation requirements for medical device manufacturing.
- Biocompatible Resin Print Validation:Each chairside installation requires material-specific calibration protocols and ongoing quality assurance to maintain FDA compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printed Clear Dental Aligners Market |
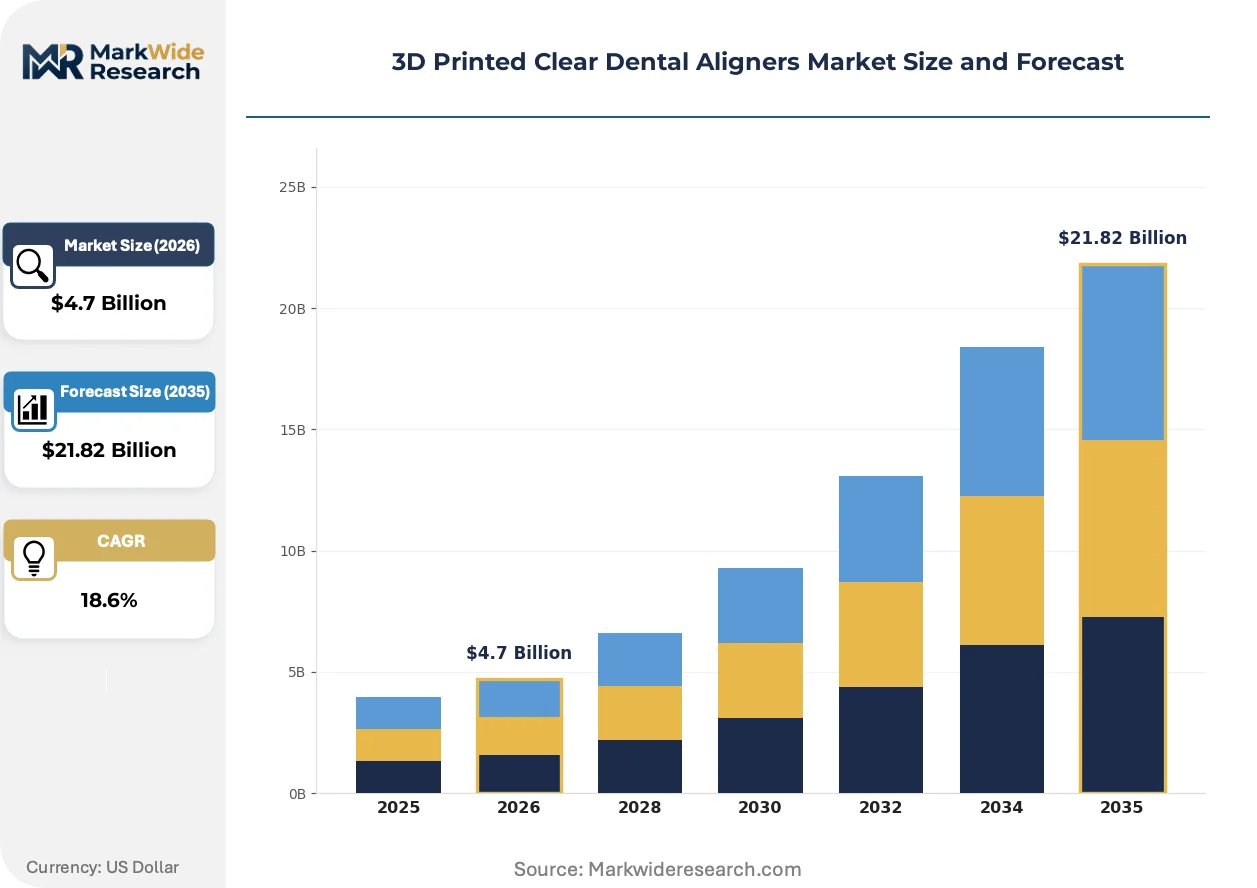
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Litigating Aligners, Invisible Aligners, Retainers, Expanders End User: Orthodontists, Dentists, Dental Clinics, Aesthetic Practitioners Material: Polyurethane, Polypropylene, Copolyester, Thermoplastic Manufacturing Technology: SLA, SLS, FDM, DLP |
| Companies Covered | SprintRay, SmileDirectClub, Align Technology, Formlabs, Graphy Inc., LuxCreo, Dentsply Sirona, Asiga, 3D Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printed Clear Dental Aligners Market Strategic Shifts
Digital workflow integration is compressing the traditional aligner value chain, eliminating intermediary fabrication steps and enabling point-of-care production models that reshape competitive economics.
DLP additive manufacturing is collapsing conventional centralized production economics by enabling same-day aligner fabrication within dental practices. Orthodontists and high-volume dental clinics adopt chairside systems to capture margin previously allocated to external laboratories. This technology compression eliminates shipping logistics and treatment planning delays, converting patient visits into immediate production events.
EU MDR notified body capacity constraints are reshaping market entry pathways for custom medical appliances. Extended review timelines for Class IIa device certifications favor established manufacturers with dedicated regulatory affairs infrastructure. Smaller resin suppliers and equipment entrants face qualification bottlenecks that concentrate competitive position among ISO 13485-certified incumbents.
Subscription-based equipment access is displacing outright purchase models among independent dental practices. Orthodontists in the United States and Germany increasingly favor per-aligner production fees over capital-intensive hardware acquisition. This preference shift aligns with broader healthcare asset-lighting trends and reduces balance sheet risk for mid-sized clinic operators.
3D Printed Clear Dental Aligners Market Segmentation
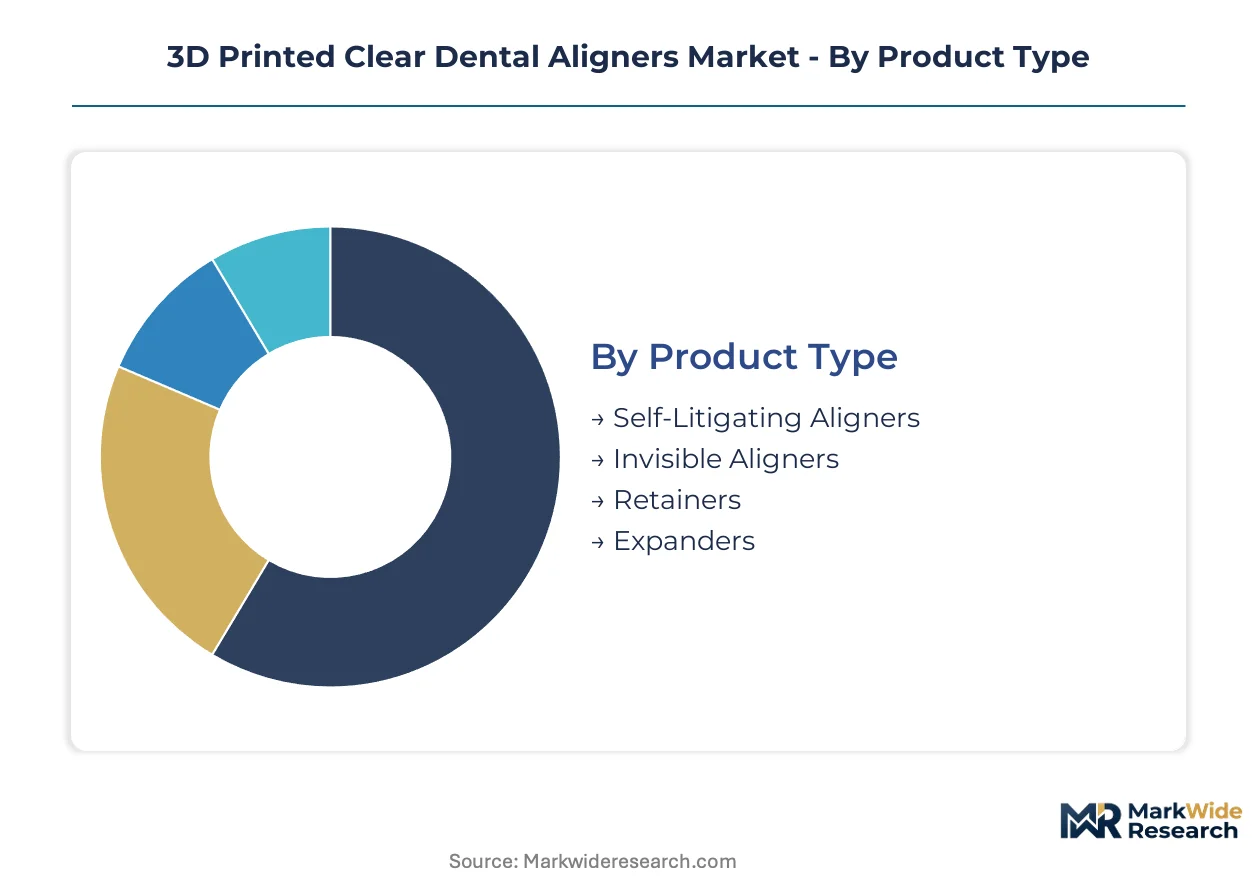
Segmentation in the 3D printed clear dental aligners market reveals how technology choice, clinical setting, and material specification determine production economics and regulatory pathways. Each dimension carries distinct margin profiles and compliance requirements that reshape competitive positioning across orthodontist and dental clinic channels.
Product Type:
Application purpose separates aesthetic correction appliances from retention and expansion devices, with each category demanding different print resolution standards and clinical oversight intensity.
- Invisible Aligners:Sequential removable trays fabricated from biocompatible photopolymer resins with sub-50-micron layer resolution for precise orthodontic force calibration. Demand concentrates among orthodontists in the United States and Germany where patient aesthetic preferences drive premium pricing and chairside production adoption.
- Self-Litigating Aligners:Integrated clip mechanisms reduce friction during tooth movement, requiring specialized resin formulations with enhanced elastic modulus retention. Dental clinic chains in China prioritize this format for complex malocclusion cases where reduced chair time improves throughput economics.
- Retainers:Post-treatment stabilization devices with lower force requirements permit faster print speeds and reduced material costs per unit.
- Expanders:Palatal expansion appliances for mixed dentition cases, typically produced through centralized manufacturing due to size constraints on chairside build platforms.
Invisible aligners command the established base. The steepest expansion runs through self-litigating aligners.
End User:
Customer type determines equipment deployment scale, with capital intensity and regulatory compliance burden varying sharply across solo practitioners and consolidated clinic networks.
- Orthodontists:Specialists with dedicated orthodontic practices achieve highest chairside utilization rates through concentrated case volume and advanced intraoral scanner integration. German orthodontic practices lead European DLP adoption due to favorable reimbursement structures for same-day aligner production.
- Dental Clinics:High-volume general dentistry operations capture margin through integrated CAD/CAM workflows, with Chinese clinic chains driving Asia-Pacific deployment of subscription-based equipment access models.
- Dentists:General practitioners with intermittent aligner case volume favor centralized laboratory relationships over in-house production investments.
- Aesthetic Practitioners:Cosmetic-focused operators in urban United States markets leverage teledentistry platforms to extend geographic reach beyond traditional orthodontic referral networks.
Dental clinics command the established base. The steepest expansion runs through aesthetic practitioners.
Material:
Material specification governs optical clarity, stress retention, and biocompatibility certification requirements, with resin chemistry selection directly impacting FDA 510(k) clearance pathways.
- Polyurethane:Superior optical clarity and elastic recovery properties enable precise orthodontic force application over extended wear cycles. United States orthodontists specify polyurethane formulations for premium aligner tiers where patient comfort drives treatment adherence.
- Copolyester:Balanced transparency and mechanical durability at moderate cost points, with German dental clinics favoring this material for standard treatment protocols under EU MDR Class IIa compliance frameworks.
- Polypropylene:Lower-cost alternative with adequate clarity for short-duration aligner sequences, gaining traction in price-sensitive Chinese market segments.
- Thermoplastic:Legacy material category with established supplier bases, primarily utilized for retainer and expander applications where optical properties are secondary to mechanical retention.
Polyurethane commands the established base. The steepest expansion runs through copolyester.
Manufacturing Technology:
Print methodology determines speed, resolution, and equipment cost structure, with technology selection constraining which clinical workflows achieve viable unit economics.
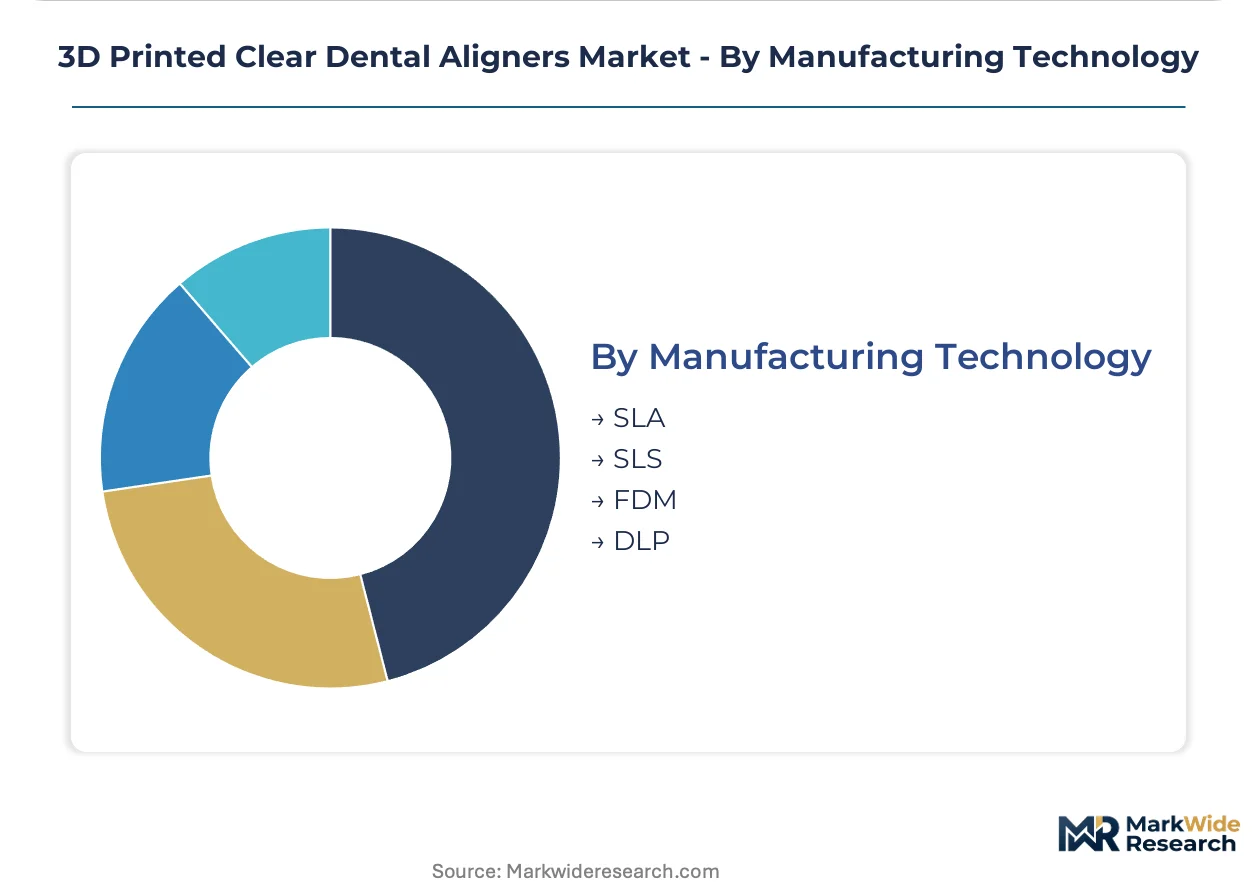
- DLP:Digital light projection delivers fastest layer curing speeds compatible with same-day patient workflows, dominating chairside adoption among United States and German orthodontic practices seeking immediate production turnaround.
- SLA:Stereolithography achieves finest surface resolution for complex tooth movement tracking, with centralized aligner laboratories in China deploying multi-unit SLA fleets for high-volume contract manufacturing.
- SLS:Selective laser sintering of nylon-based materials serves specialized expander and retainer applications where material flexibility exceeds photopolymer capabilities.
- FDM:Fused deposition modeling remains limited to prototype and educational applications due to inferior surface finish and layer visibility incompatible with aesthetic aligner requirements.
SLA commands the established base. The steepest expansion runs through DLP.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways and EU MDR Class IIa compliance frameworks are accelerating chairside 3D printing deployment across orthodontic practices in developed markets. Digital dentistry infrastructure investments in Germany, China, and the United States concentrate demand for DLP manufacturing systems and biocompatible photopolymer resins.
United States
Orthodontists in metropolitan markets drive DLP equipment adoption through concentrated case volumes and favorable reimbursement for same-day aligner production. FDA quality system regulation compliance shapes supplier qualification processes for resin producers seeking 510(k) clearance. Greater Boston and Pacific Northwest dental clusters anchor early chairside deployment among high-volume practices.
Germany
Digital dentistry infrastructure buildout across Baden-Württemberg and Bavaria supports intraoral scanner network expansion and clinical workforce training. EU MDR notified body capacity constraints favor established manufacturers with dedicated regulatory affairs infrastructure. Stuttgart and Munich orthodontic practices lead European adoption of subscription-based equipment access models.
China
Tier-two and tier-three city dental clinic chains present whitespace for chairside 3D printing deployment as consolidation accelerates. NMPA medical device registration requirements govern biocompatible resin importation and domestic manufacturing qualification. Yangtze River Delta dental manufacturing clusters in Shanghai and Suzhou anchor centralized SLA production for contract aligner fabrication.
Japan
PMDA medical device approval processes and JIS standards compliance shape market entry timelines for foreign resin suppliers and equipment manufacturers. METI industrial policy supports precision manufacturing technology adoption across dental laboratory networks. Kanto region orthodontic practices in Tokyo and Yokohama concentrate demand for premium polyurethane aligner formulations.
South Korea
MFDS medical device regulations and digital health infrastructure investments accelerate teledentistry platform integration with remote monitoring capabilities. Seoul Capital Area aesthetic practitioners leverage asynchronous clinical oversight to extend geographic reach beyond traditional orthodontic referral networks. Busan-Ulsan manufacturing clusters support domestic photopolymer resin production for regional supply security.
3D Printed Clear Dental Aligners Market Competitive Environment
On the supply side, the industry is consolidating around integrated scanner-to-aligner ecosystems and specialized chairside equipment manufacturers. Three strategic archetypes dominate: full-stack platform operators controlling digital workflow capture, point-of-care hardware specialists enabling practice-level production, and centralized manufacturing laboratories serving price-sensitive volume segments. Competitive moves concentrate on M&A for digital workflow integration and strategic partnerships for resin formulation exclusivity.
Among United States-based platform operators, Align Technology and SmileDirectClub exemplify divergent channel strategies—orthodontist-centric premium positioning versus teledentistry-linked direct-to-consumer access. SprintRay represents the chairside equipment specialist archetype, anchoring DLP manufacturing adoption among independent dental practices seeking same-day production capabilities without centralized laboratory dependency.
| Leading Market Players |
|---|
| SprintRay |
| SmileDirectClub |
| Align Technology |
| Formlabs |
| Graphy Inc. |
| LuxCreo |
| Dentsply Sirona |
| Asiga |
| 3D Systems |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta manufacturing clusters in Shanghai and Suzhou anchor global photopolymer resin supply, with their capacity utilization rates directly transmitting into pricing power for downstream aligner producers. FDA 510(k) clearance timelines and EU MDR notified body bottlenecks create asymmetric cost structures that concentrate margin capture among ISO 13485-certified incumbents.
Pricing Analysis
Certification level creates the primary spread across pricing tiers, with FDA-cleared premium formulations commanding substantial premiums over CE-marked standard grades. Subscription-based per-aligner leasing models now displace capital purchase structures, compressing upfront hardware costs while embedding recurring resin and service fees. Cost compression in economy-tier polypropylene segments intensifies as Chinese domestic suppliers expand capacity. Price-sensitive independent dental practices in tier-two cities drive procurement toward standard-grade copolyester alternatives, while United States orthodontists with concentrated case volume absorb premium polyurethane pricing.
Supply Chain Analysis
Specialized contract manufacturers in Germany, the United States, and China hold concentrated capacity for biocompatible photopolymer resin synthesis. Aligner production draws from specialized acrylic monomers, photoinitiator packages, and precision DLP optical engines as critical inputs. Single-source vulnerability in photoinitiator supply creates exposure to pharmaceutical-grade chemical allocation decisions. Distribution runs through dental equipment distributors and direct manufacturer partnerships with consolidated clinic chains, with teledentistry platforms emerging as alternative channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue layers expand faster than hardware across this market, with resin subscription programs and remote monitoring software outpacing DLP equipment sales growth. Recurring revenue per patient case now exceeds one-time production fees as the dominant value capture mechanism.
For Market Incumbents: Entrench regulatory moats through accelerated FDA 510(k) submissions for next-generation resin formulations while consolidating backward integration into photoinitiator supply. Capacity addition in Baden-Württemberg and Bavaria dental clusters secures European market position against emerging Chinese equipment competitors. Certification investment in ISO 13485 quality management systems creates disqualifying barriers for capital-constrained entrants. For New Entrants and Emerging Players: Pursue whitespace in tier-two and tier-three Chinese cities where dental clinic consolidation outpaces chairside equipment deployment. Teledentistry-linked remote monitoring platforms present the most penetrable segment, enabling geographic reach without physical infrastructure investment. Go-to-market execution should anchor on pay-per-aligner leasing models that eliminate upfront capital barriers for independent practitioners. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because scanner-to-aligner workflow integration determines sustainable competitive position. Acquisition targets should prioritize DLP hardware specialists with established FDA clearance pathways and resin formulation IP. The signal to watch is EU MDR notified body capacity expansion timelines, which would accelerate market entry for qualified new resin suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined premarket notification compresses chairside technology adoption timelines across orthodontic practices. |
| Resin Formulation Exclusivity Partnership | Proprietary photopolymer supply agreements lock in margin capture and differentiate equipment bundling. |
| Teledentistry Platform Integration | Asynchronous clinical oversight extends patient geography beyond traditional referral network constraints. |
| Subscription Equipment Access Model | Per-aligner leasing structures reduce balance sheet risk for mid-sized clinic operators. |
| EU MDR Class IIa Certification Investment | Notified body qualification bottlenecks favor early movers with dedicated regulatory infrastructure. |
Study Parameters
Cross-validation between primary fieldwork with orthodontic practitioners and secondary regulatory filing analysis anchors the qualitative findings. Orthodontists, dental clinic operations directors, biomedical engineers, GPO contracts managers, and resin R&D chemists provided structured input. FDA 510(k) databases, EU MDR notified body registers, NMPA medical device filings, and intraoral scanner deployment records supplied secondary validation. Bottom-up patient case volume estimates and top-down equipment shipment data triangulate market sizing.
Calibration against historical DLP adoption curves in dental laboratories and orthodontic practice capital expenditure patterns informs the projection framework. Segmentation dimensions span product type, end-user archetype, material chemistry, manufacturing technology, and regional regulatory cluster. CAGRs derive from weighted average of equipment installation trajectories and per-practice utilization intensity. Photopolymer resin price elasticity and chairside workflow training completion rates serve as industry-specific forecast inputs across the modeling period.
Macroeconomic conditions sit as an overlay; deviation in dental reimbursement rates and private practice capital availability would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory clearance timelines and resin supplier qualification progress. Supply concentration in North American and European chemical producers, EU notified body capacity constraints, and photoinitiator allocation volatility constitute primary revision risks. Quarterly review of FDA 510(k) clearance volumes and NMPA registration approvals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Europe Dental Implants Market
Dental Devices
CBCT Dental Imaging Market
Dental Devices
Dental Dam Market
Dental Devices
Dental Hand Tools Market
Dental Devices
US Orthodontics Market
Dental Devices
Europe Dental Implants and Prosthetics Market
Dental Devices
Dental Whitening Lamps Market
Dental Devices
Dental Erbium Lasers Market
Dental Devices
Asia Pacific Acrylic Teeth Market
Dental Devices
Single Tooth Implants and Dental Bridges Market
Dental Devices
Electric Dental Handpieces Market
Dental Devices
Orthodontics Market
Dental Devices
Dental Orthodontic Wax Market
Dental Devices
Global Dentures Market
Dental Devices
Dental Veneers Market
Dental Devices
Dental Radiometer Market