
 Dental CAD Market | 2026-2036
Dental CAD Market Size, Share, and Industry Trends Forecast 2026-2036
Dental CAD Market Outlook
Prosthodontic laboratories is decoupling from traditional chairside-only workflows as larger lab networks absorb scanning and design functions previously housed in dental practices. Planmeca leverages its Nordic installed base of imaging hardware to bundle CAD seats with cone-beam CT contracts. 3Shape dominates intraoral scanning data formats, which sustains its software ecosystem lock-in across third-party mills. Dentsply Sirona anchors North American distribution through its dealer network, competing with Institut Straumann's direct-to-lab subscription model for implant planning modules.
Dental CAD comprises computer-aided design systems that generate three-dimensional digital models of oral anatomy using point-cloud data from optical or mechanical scanners, typically outputting STL or proprietary mesh files with tolerances below 50 micrometers for crown margin fit. These systems automate the geometric definition of restorations, abutments, and orthodontic appliances before CAM milling or additive manufacturing execution. Scanner hardware captures the largest revenue share due to capital replacement cycles and multimodal integration with face scanners for full-digital smile design. Software licensing is expanding fastest among dental labs seeking cloud-native collaboration tools that bypass per-seat installation limits. CAM Integration remains the most margin-accretive segment because bundled toolpath generation commands premium pricing from labs running multi-axis titanium and zirconia mills.
FDA 510(k) clearance requirements govern CAD software marketed for definitive restoration design, while the EU Medical Device Regulation (MDR) reclassifies certain implant planning modules to Class IIb, extending notified body review timelines for vendors serving European dental labs. ISO 13485 quality management certification has become a de facto market access threshold for software suppliers seeking OEM partnerships with major milling machine producers. Stakeholders must monitor whether FDA digital health pre-certification pilots expand to CAD algorithms, as this would reshape competitive entry costs for cloud-native entrants.
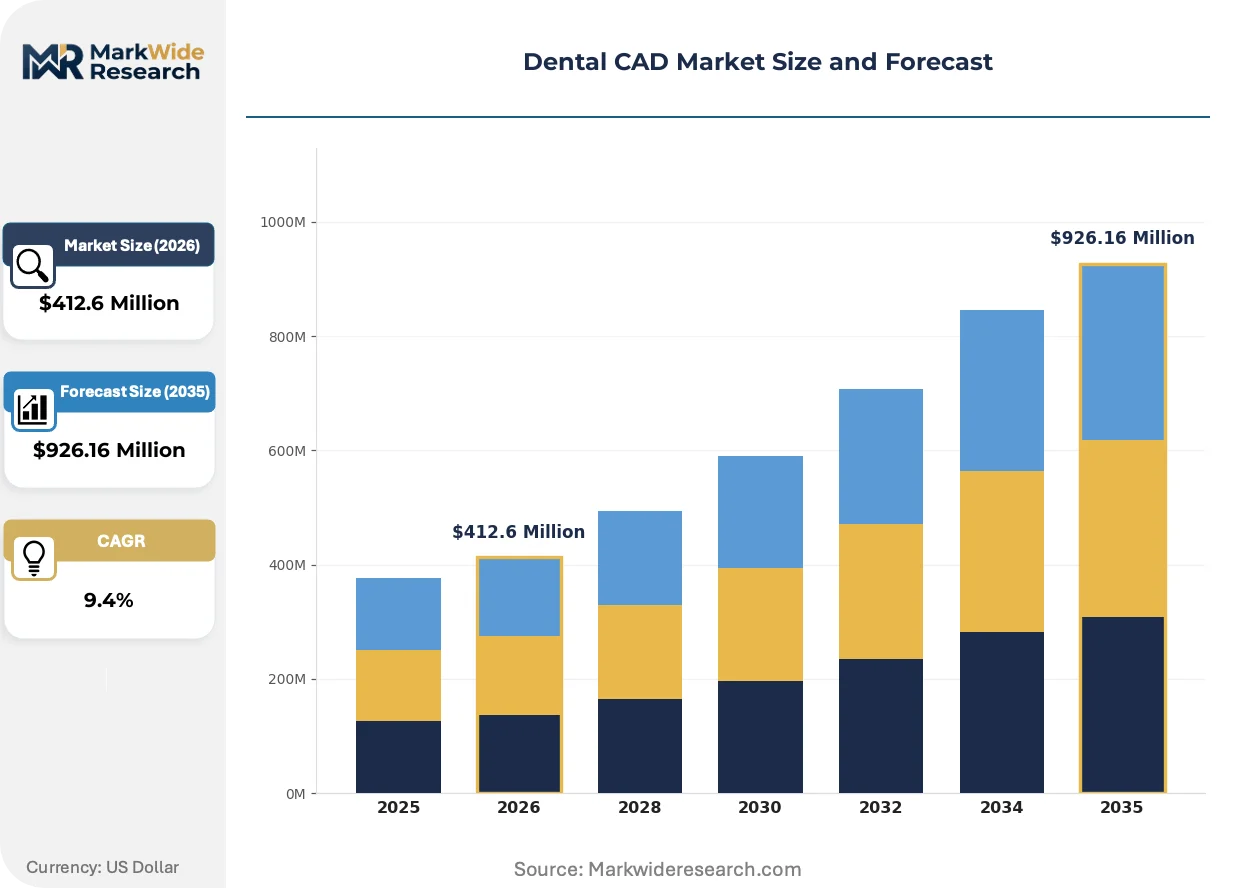
Market Dynamics
Prosthodontic laboratories are consolidating scanning and design functions previously distributed across dental practices, creating network effects that favor multi-site lab operators over single-location competitors.
Growth Catalysts
- FDA 510(k) Streamlining:Expedited clearance pathways for Class II medical device software reduce time-to-market for CAD-based restoration design tools, accelerating vendor innovation cycles.
- DIN Standards Leadership:Germany's precision manufacturing clusters around milling equipment producers reinforce technical specifications that propagate across European dental prosthetics workflows.
- Cloud-Native Collaboration:Dental labs are migrating from per-seat licensing to browser-based design platforms that enable distributed technician teams and real-time case sharing.
Market Restraints
- Capital Equipment Concentration:Multi-axis titanium and zirconia milling machines require substantial upfront investment, concentrating production capacity among well-capitalized laboratory networks.
- EU MDR Reclassification:Implant planning modules now fall under Class IIb review timelines, extending notified body certification periods for vendors serving European dental labs.
- Scanner Hardware Lock-in:Proprietary mesh formats from dominant intraoral scanner manufacturers create switching costs that constrain software vendor competition.
Strategic Opportunities
- Underpenetrated Lab Networks:Mid-sized dental laboratories in Southern Europe and Eastern Europe remain below digital adoption thresholds seen in Nordic and German markets.
- AI-Assisted Margin Detection:Machine learning algorithms for automated crown margin identification are converging with optical scanning hardware to reduce technician design time.
- Subscription Distribution Models:Direct-to-lab pricing for implant planning modules bypasses traditional dealer networks, capturing recurring revenue from specialized prosthodontic practices.
Industry Challenges
- ISO 13485 Certification Burden:Quality management system requirements have become de facto market access thresholds, extending compliance timelines for software suppliers seeking OEM partnerships with milling machine producers.
- Legacy System Integration:Dental labs operating hybrid analog-digital workflows face friction connecting new CAD seats to existing practice management software and patient record systems.
- Technician Skill Stratification:Advanced digital design competencies concentrate among younger technicians, creating workforce gaps as senior ceramists transition toward retirement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental CAD Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $926.16 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Printers, Scanners, Software, Milling Machines End User: Dentists, Dental Labs, Orthodontists, Clinics Technology: CAD Software, CAM Integration, Digital Impressions, Additive Manufacturing Application: Crowns, Bridges, Aligners, Implants |
| Companies Covered | Planmeca, Medit, Align Technology, Dental Axess, ZimVie, Dentsply Sirona, Institut Straumann, Amann Girrbach, 3Shape, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental CAD Market Strategic Shifts
Workflow unification across imaging, design, and manufacturing stages is compressing traditional handoffs between dental practices and laboratories, with cloud platforms now mediating most data exchanges.
Artificial intelligence is unifying point-cloud processing with automated restoration geometry generation, reducing technician intervention in routine crown and bridge cases. Mid-sized dental laboratories are adopting these tools fastest, using algorithmic design suggestions to maintain throughput without proportional headcount expansion. This compression of the design-to-mill pipeline is enabling same-day restoration promises that reshape competitive positioning against chairside milling systems.
EU MDR implementation is extending notified body review timelines for implant planning software, forcing vendors to restructure quality management documentation and clinical evidence packages. European dental laboratories now prioritize suppliers with established Class IIb certifications, creating a two-tier vendor landscape. Software developers are responding by pre-submission engagement with German and Dutch notified bodies to secure predictable approval pathways.
Buying patterns among dental laboratories are gravitating toward bundled hardware-software contracts that consolidate scanner, design seat, and maintenance obligations under single vendor relationships. Independent milling centers and multi-site lab networks are displacing transactional per-case pricing with multi-year subscription commitments. This concentration is most visible in Germany and Switzerland, where precision manufacturing expectations drive preference for integrated technology stacks over best-of-breed component assembly.
Dental CAD Market Segmentation
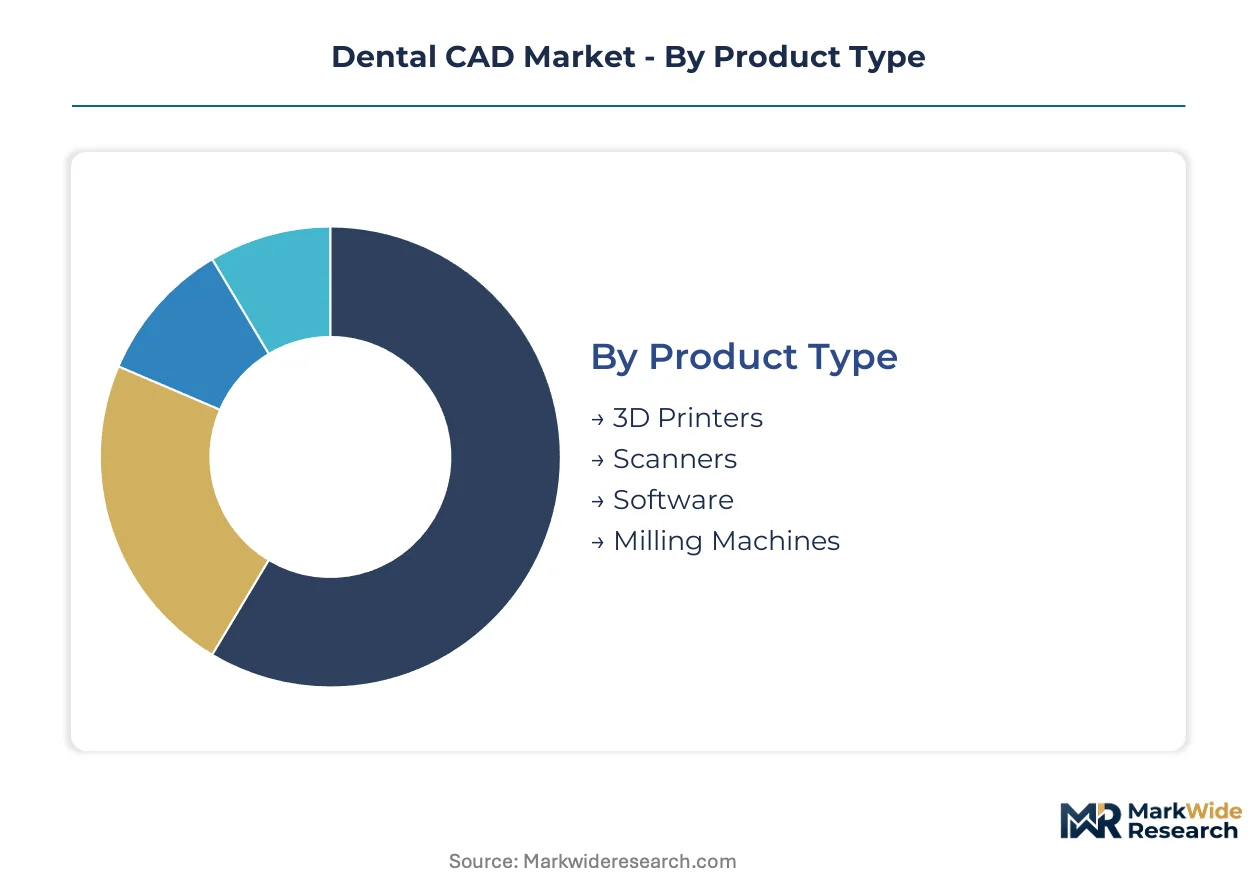
Dental CAD segmentation reveals how capital equipment, software licensing, and service delivery models compete for revenue share across distinct clinical workflows. Understanding these boundaries exposes where vendor bundling strategies succeed and where point solutions retain defensible positions.
Product Type:
Standalone hardware systems dominate capital expenditure budgets, while embedded software modules increasingly ship pre-integrated with multimodal imaging platforms.
- Scanners:Intraoral and laboratory optical scanners capture point-cloud data with sub-50-micrometer tolerances for crown margin definition. German milling equipment manufacturers anchor European demand through bundled scanner-seat contracts that lock labs into proprietary mesh formats.
- Software:Cloud-native design seats enable distributed technician collaboration without per-workstation installation limits. Dental laboratories in Nordic markets migrate fastest to browser-based platforms that bypass traditional licensing constraints.
- Milling Machines:Multi-axis titanium and zirconia mills command premium pricing from labs running high-throughput restoration production.
- 3D Printers:Resin and metal additive systems serve orthodontic aligner fabrication and surgical guide production.
Scanner hardware leads volumes today; software licensing is gaining share fastest.
End User:
Customer type determines purchasing authority, with consolidated lab networks exercising procurement scale that individual practices cannot match.
- Dental Labs:Multi-site laboratory networks absorb scanning and design functions previously distributed across dental practices, creating concentrated demand for enterprise-grade collaboration tools. ISO 13485 certification requirements filter vendor access to these high-volume accounts.
- Dentists:Chairside CAD adoption concentrates among prosthodontic specialists seeking same-day restoration capabilities. FDA 510(k) clearance pathways for Class II software streamline procurement decisions for definitive restoration design tools.
- Orthodontists:Clear aligner production workflows drive specialized scanner and thermoforming equipment demand.
- Clinics:Group practice structures enable shared design seat licensing across multiple operatories.
Dental labs command the largest procurement volumes; orthodontists show the steepest expansion trajectory.
Technology:
Technology layers stack from data acquisition through manufacturing execution, with integration depth determining workflow efficiency.
- CAD Software:Three-dimensional modeling systems generate restoration geometries from optical scan data, outputting STL or proprietary mesh files. EU MDR reclassification of implant planning modules to Class IIb extends notified body review timelines for vendors serving European dental labs.
- CAM Integration:Bundled toolpath generation commands premium pricing by automating the transition from digital model to physical restoration. German precision manufacturing clusters reinforce technical specifications that propagate across European prosthetics workflows.
- Digital Impressions:Chairside scanning eliminates physical impression material from clinical workflows.
- Additive Manufacturing:Layered construction methods produce complex geometries unm achievable through subtractive milling.
CAM Integration captures the highest margins; Additive Manufacturing is climbing the fastest.
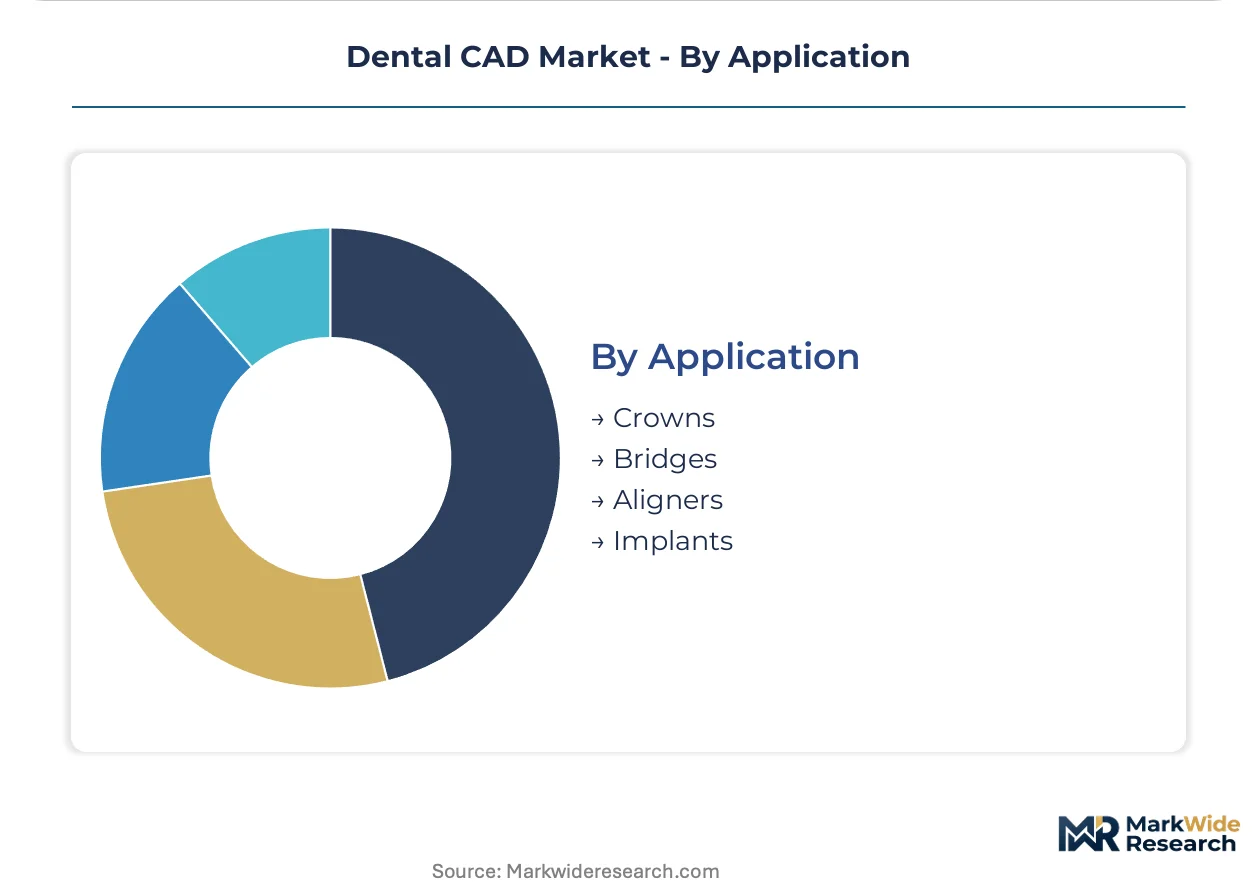
Application:
Restoration category determines material specifications, manufacturing method, and regulatory scrutiny intensity.
- Crowns:Single-unit restorations represent the highest case volume, with automated margin detection algorithms reducing technician design time. Mid-sized dental laboratories adopt AI-assisted tools fastest to maintain throughput without proportional headcount expansion.
- Aligners:Orthodontic appliances require sequential staging software and thermoforming equipment integration. Cloud-native platforms mediate data exchanges between imaging, design, and manufacturing stages for these complex case workflows.
- Bridges:Multi-unit fixed prostheses demand precise connector geometry and occlusal alignment.
- Implants:Surgical planning modules face heightened regulatory review under EU MDR Class IIb classification.
Crowns dominate case volumes today; Aligners are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision manufacturing clusters anchor European dental CAD demand through dense concentrations of milling equipment producers and DIN-standard prosthetics workflows.
United States
FDA 510(k) clearance pathways for Class II medical device software accelerate vendor innovation cycles and streamline procurement for prosthodontic laboratories. The agency's digital health pre-certification pilots reshape competitive entry costs for cloud-native CAD entrants. Multi-site lab networks in California and Texas concentrate scanning and design functions previously distributed across dental practices.
Germany
DIN standards for dental prosthetics propagate technical specifications across European workflows, reinforcing leadership in precision milling equipment. EU MDR reclassification of implant planning modules to Class IIb extends notified body review timelines, favoring established vendors with German and Dutch certifications. Stuttgart and Munich host dense clusters of multi-axis titanium and zirconia mill manufacturers.
Switzerland
Swissmedic oversight of Class IIb medical device software ensures rigorous quality management certification for implant planning modules serving European dental labs. Precision manufacturing expectations in Zurich and Basel drive preference for integrated technology stacks over best-of-breed component assembly. Direct-to-lab subscription models capture recurring revenue from specialized prosthodontic practices.
Japan
PMDA regulatory frameworks govern CAD software marketed for definitive restoration design, with ISO 13485 certification serving as de facto market access threshold. METI industrial policy supports digital workflow adoption among mid-sized dental laboratories. Tokyo and Osaka metropolitan areas concentrate demand for cloud-native collaboration tools enabling distributed technician teams.
China
NMPA medical device registration requirements structure competitive entry for CAD-based restoration design tools targeting domestic dental laboratories. MIIT industrial standards promote interoperability between scanner hardware and design software platforms. Shanghai and Shenzhen manufacturing clusters supply optical scanning hardware with sub-50-micrometer tolerance specifications.
Dental CAD Market Competitive Environment
Strategic partnerships dominate the current landscape as vendors bundle hardware, software, and maintenance obligations under single-relationship contracts. The vendor base separates into three tiers: imaging equipment manufacturers with captive CAD ecosystems, standalone software specialists seeking cloud-native differentiation, and precision milling equipment producers integrating design-to-manufacture workflows. Consolidation pressures favor multi-site lab networks exercising procurement scale unavailable to individual practices. Technology licensing agreements and geographic expansion constitute the dominant competitive moves reshaping market access.
Within the integrated-systems tier, Planmeca leverages its Nordic installed base to bundle CAD seats with imaging hardware contracts. Dentsply Sirona anchors North American distribution through dealer networks, competing with Institut Straumann's direct-to-lab subscription positioning. These three entities exemplify divergent channel strategies: hardware-led bundling, traditional distribution dependence, and recurring-revenue specialization.
| Leading Market Players |
|---|
| Planmeca |
| Medit |
| Align Technology |
| Dental Axess |
| ZimVie |
| Dentsply Sirona |
| Institut Straumann |
| Amann Girrbach |
| 3Shape |
| Others |
Value Chain & Pricing Dynamics
Zirconia powder and precision-machined optical components flow from German and Japanese specialty suppliers through milling equipment manufacturers into tiered software-hardware bundles that dental laboratories procure under multi-year subscription frameworks.
Pricing Analysis
Distributor margins absorb 15-25 points before equipment reaches mid-sized dental laboratories, while direct-to-lab subscriptions from implant planning specialists bypass this layer entirely. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified vendors from uncertified competitors and entry-level scanner producers. Pricing pressure stems from cloud-native entrants undercutting per-seat licensing with browser-based collaboration tools. Mid-sized labs in Southern Europe exhibit highest price sensitivity; German multi-site networks prioritize integration depth over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese optical sensor manufacturers supplying sub-50-micrometer tolerance components for intraoral scanners. German milling equipment producers and Chinese machining centers anchor hardware assembly, while zirconia powder draws from Japanese and Australian specialty ceramic suppliers. Tariff exposure runs through EU-China component trade for scanner assembly. Distribution runs through dealer networks in North America and direct OEM partnerships in European precision manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German DIN-standard workflows command 20-30% pricing premiums over Southern European markets, creating arbitrage opportunities for vendors with regulatory bandwidth to navigate divergent EU MDR and FDA 510(k) clearance pathways.
For Market Incumbents: Lock in cloud-native design seat subscriptions before mid-sized laboratories complete migration from perpetual licensing. Backward integration into optical sensor production reduces exposure to Taiwanese supply constraints. Prioritize ISO 13485 certification maintenance as EU MDR Class IIb timelines extend competitive moats against uncertified entrants. For New Entrants and Emerging Players: Launch via direct-to-lab subscription models targeting orthodontist practices in Spain and Italy where digital adoption lags Nordic benchmarks. White-space concentrates in AI-assisted margin detection software for crown workflows. Partner with Shenzhen-based scanner hardware producers to bypass proprietary mesh format lock-in from dominant incumbents. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-sized dental laboratories seek exit liquidity rather than capital investment in multi-axis milling capacity. Long-term viability favors vendors with established notified body relationships in Germany and the Netherlands. Watch FDA digital health pre-certification pilot expansion as inflection signal for cloud-native competitive entry costs.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Browser-based design seats bypass per-workstation installation limits that constrain lab technician collaboration. |
| ISO 13485 Certification Investment | Quality management certification opens OEM partnerships with German milling equipment manufacturers. |
| AI-Assisted Margin Detection Development | Machine learning algorithms compress crown design time for mid-sized laboratories facing technician shortages. |
| Direct-to-Lab Subscription Launch | Recurring revenue models capture implant planning demand from specialized prosthodontic practices. |
| Notified Body Pre-Submission Engagement | Early EU MDR Class IIb pathway alignment secures predictable approval timelines for implant software vendors. |
Study Parameters
Direct dialogue with prosthodontic laboratory directors, CAD software product managers, milling equipment procurement leads, and FDA regulatory affairs specialists grounded qualitative insights. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body registries, DIN standards documentation, and ISO 13485 certification records. Bottom-up and top-down triangulation cross-checked laboratory equipment shipment data against software licensing disclosures.
Bottom-up modeling aggregated scanner hardware volumes, design seat deployments, and CAM integration modules across product type segments. Top-down constraints applied macroeconomic healthcare expenditure patterns and dental prosthetics reimbursement frameworks. Segmentation dimensions spanned deployment model, laboratory network scale, regulatory certification tier, and regional adoption maturity. CAGR derivation incorporated replacement cycle dynamics for capital equipment and subscription renewal rates for cloud-native platforms.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR implementation delays or FDA digital health pre-certification expansion. Forecasts reflect documented assumptions about technician workforce demographics and cloud migration velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Diagnostic and Surgical Market
Dental Devices
Toothbrush Sterilizer Market
Dental Devices
Electric Dental Handpieces Market
Dental Devices
Self-Ligating Bracket Sales Market
Dental Devices
Dental Piezoelectric Ultrasonic Unit Market
Dental Devices
Asia Pacific Acrylic Teeth Market
Dental Devices
Global Restorative Dentistry Market
Dental Devices
Root Canal Market
Dental Devices
Dental Etching Liquid Market
Dental Devices
Dental Restoration Market
Dental Devices
Global Dentures Market
Dental Devices
US Dental Splint Market
Dental Devices
Dental Caries Market
Dental Devices
Titanium Dental Implants Market
Dental Devices
Dental Caries and Endodontic Market
Dental Devices
CBCT Dental Imaging Market