
 Muscle Tension Dysphonia Treatment Market | 2026-2036
Muscle Tension Dysphonia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Muscle Tension Dysphonia Treatment Market Foresight
Professional voice users is hardening as the dominant end-use cohort, with singers, educators, and broadcast anchors driving referral volumes into specialized laryngology practices. Pfizer Inc. leverages its neurology portfolio to sustain physician mindshare in pharmacologic dysphonia management. Merz Pharmaceuticals GmbH anchors the botulinum toxin segment through targeted laryngeal injection formulations. SpeakSuite, Inc. competes via digital voice therapy platforms that extend clinician reach beyond traditional clinic boundaries.
Muscle tension dysphonia treatment encompasses behavioral, pharmacologic, and procedural interventions targeting hyperfunctional laryngeal muscle patterns without underlying organic lesion; voice therapy employs resonant voice techniques and laryngeal manual therapy to reduce supraglottic compression. The treatment type dimension shows voice therapy occupying the volume base while botulinum toxin injections capture premium positioning through precision electromyography guidance. Technology segmentation reveals speech devices gaining traction in home-based rehabilitation protocols, whereas corticosteroids remain confined to acute inflammatory overlap cases.
FDA oversight governs botulinum toxin products and speech therapy device classifications, while HIPAA frameworks dictate telehealth platform compliance for remote voice therapy delivery. The Centers for Medicare & Medicaid Services shapes demand through reimbursement coding for speech-language pathology services, directly influencing provider adoption of prolonged intervention protocols. Stakeholders must monitor evolving digital health reimbursement parity laws and FDA software-as-medical-device guidance to calibrate platform investments against regulatory latency.
Market Dynamics
Telemedicine reimbursement parity laws are compressing the geographic distance between voice patients and specialized laryngology centers, fundamentally altering referral patterns and service delivery economics across the treatment landscape.
Growth Catalysts
- CMS reimbursement expansion:Medicare coding updates for speech-language pathology services enable prolonged voice therapy protocols previously constrained by visit limits.
- Professional voice users:Singers, educators, and broadcast anchors generate sustained referral volumes into academic voice centers as occupational voice demands intensify.
- Electromyography-guided injection techniques:Precision targeting of thyroarytenoid and cricothyroid muscles improves botulinum toxin outcomes and reduces adverse events.
Market Restraints
- Botulinum toxin supply concentration:Manufacturing complexity and cold-chain requirements limit viable suppliers to a handful of specialized facilities.
- Voice therapy labor intensity:High clinician-to-patient ratios constrain throughput compared to procedural interventions.
- Substitution by alternative diagnoses:Laryngopharyngeal reflux and vocal fold paresis often displace MTD as primary diagnostic codes, diverting reimbursement.
Strategic Opportunities
- Home-based speech devices:FDA-cleared wearable biofeedback tools extend therapy beyond clinic walls into patient daily routines.
- HIPAA-compliant telehealth platforms:Remote voice therapy delivery penetrates rural and underserved metropolitan catchments previously unreachable.
- Dual therapy protocols:Convergence of resonant voice techniques with laryngeal manual therapy creates bundled service offerings.
Industry Challenges
- Specialized laryngology training pipelines:Fellowship programs produce fewer than fifty voice-specialized surgeons annually across the United States.
- Software-as-medical-device classification uncertainty:FDA guidance lag delays platform commercialization timelines for digital voice therapy applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Muscle Tension Dysphonia Treatment Market |
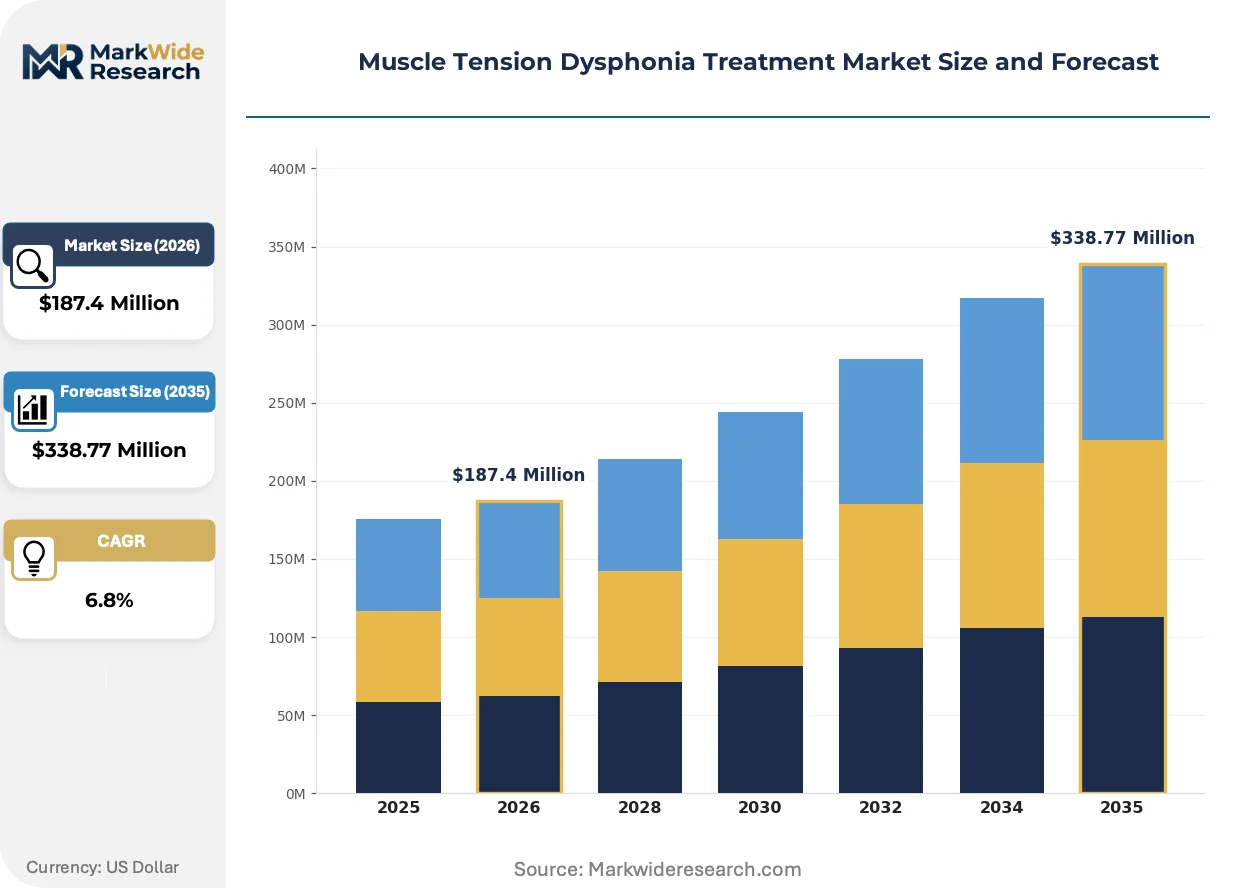
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Voice Therapy, Medication, Surgery, Injection End User: Clinics, Hospitals, Rehabilitation Centers, Private Practices Technology: Botulinum Toxin, Corticosteroids, Speech Devices, Manual Techniques Application: Professional Voice Users, Educators, Singers, Actors |
| Companies Covered | Verboso LLC, SpeakSuite, Inc., Pfizer Inc., Merck & Co., Inc., Astellas Pharma Inc., AbbVie Inc., Merz Pharmaceuticals GmbH, Ipsen S.A., Cipl Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Muscle Tension Dysphonia Treatment Market Shifts & Advancements
Artificial intelligence and remote monitoring capabilities are embedding themselves into voice assessment workflows, compressing diagnostic timelines and enabling continuous patient engagement outside traditional clinical encounters.
Machine learning algorithms trained on acoustic voice samples are automating preliminary screening for hyperfunctional voice patterns. Tertiary voice centers deploy these tools to triage referral queues and prioritize complex cases. The technology is automating documentation burdens previously consuming twenty to thirty percent of clinician contact time.
CMS digital health reimbursement parity mandates reshape service economics for remote voice therapy delivery. Speech-language pathologists now bill equivalent rates for synchronous telehealth sessions, eliminating prior geographic penalty structures. Academic medical centers in California, Texas, and New York accelerate platform investments to capture expanded addressable populations.
Subscription-based therapy access models displace traditional per-visit billing in employer-sponsored occupational voice programs. Entertainment industry unions and school districts pilot annual voice wellness contracts covering preventive screening and acute intervention. Broadway performers and university lecture faculty constitute the earliest adopting cohorts in this payment restructuring.
Muscle Tension Dysphonia Treatment Market Segmentation
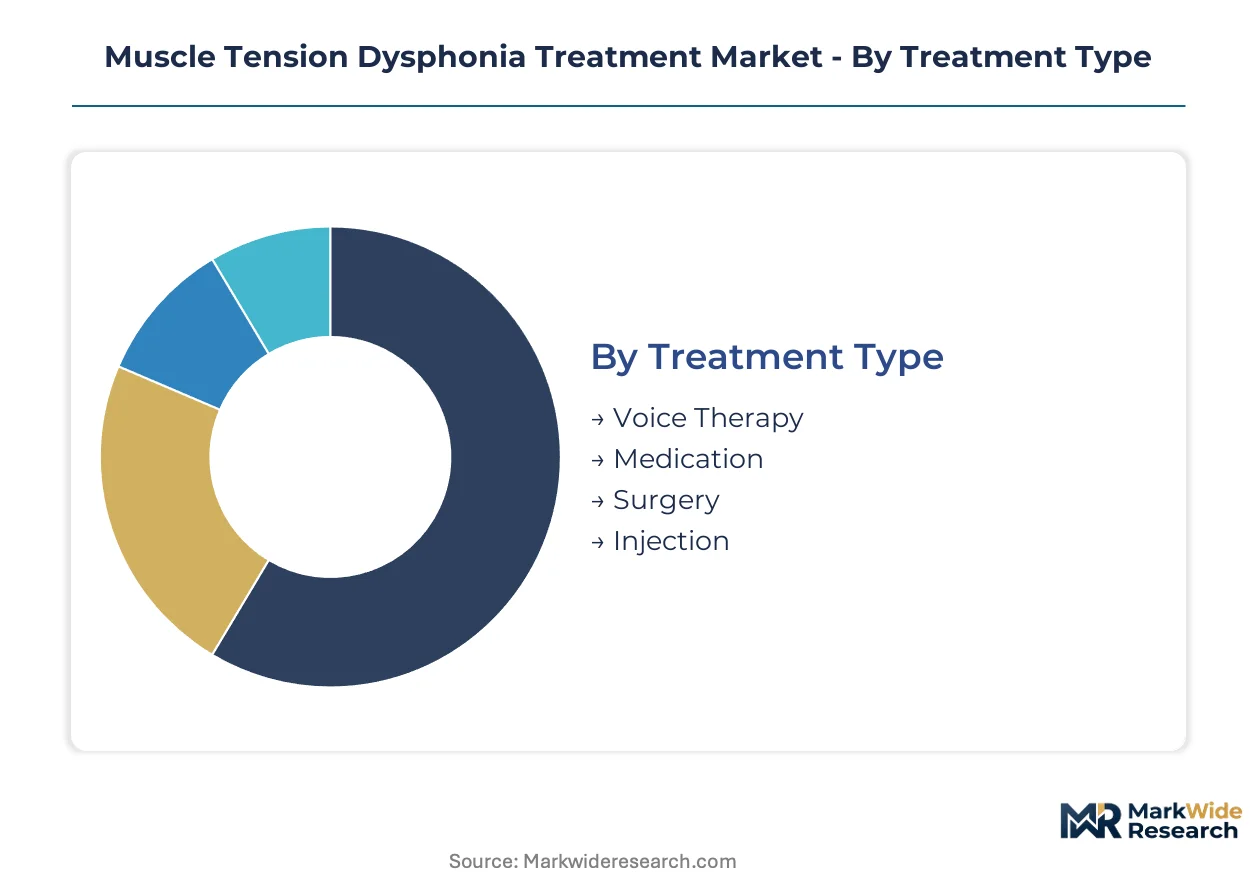
Segmentation in muscle tension dysphonia treatment reveals distinct clinical workflows where behavioral interventions operate as standalone protocols while procedural and pharmacologic options embed within multidisciplinary care pathways. Understanding these integration patterns enables stakeholders to align platform investments with reimbursement structures and patient throughput economics.
Treatment Type:
Standalone behavioral protocols dominate outpatient volume, while procedural interventions concentrate in surgical suites and injection clinics requiring specialized equipment and physician oversight.
- Voice Therapy:Resonant voice techniques and laryngeal manual therapy form the foundational behavioral intervention, delivered primarily by speech-language pathologists in outpatient settings. Demand concentrates in academic medical center voice clinics across the United States, driven by CMS reimbursement expansion for prolonged intervention protocols. Professional voice users—particularly Broadway performers and university lecturers—generate sustained referral volumes into these specialized practices.
- Injection:Electromyography-guided botulinum toxin delivery targets thyroarytenoid and cricothyroid muscles with precision dosing, occupying the procedural premium tier. Adoption clusters in metropolitan tertiary centers where laryngology fellowship-trained physicians maintain injection privileges, constrained by botulinum toxin cold-chain logistics and FDA oversight requirements.
- Medication:Corticosteroids and neuromodulatory agents address acute inflammatory overlap and adjunctive symptom management, typically prescribed in conjunction with voice therapy rather than as monotherapy.
- Surgery:Selective laryngeal adductor denervation and reinnervation procedures remain reserved for refractory cases failing conservative management, performed exclusively in high-volume voice centers with microsurgical capabilities.
Voice therapy leads volumes today; injection is gaining share fastest.
End User:
Service delivery economics vary sharply by facility type, with reimbursement rates and patient acuity driving site-of-care decisions across the treatment continuum.
- Hospitals:Tertiary academic medical centers anchor complex case management, integrating laryngology, speech-language pathology, and neurology services under single institutional umbrellas. These facilities capture the procedural premium for injection and surgical interventions while maintaining the highest voice therapy visit volumes.
- Private Practices:Independent laryngology and speech-language pathology practices leverage lower overhead structures to compete on voice therapy access, particularly in metropolitan markets with sufficient professional voice user density to sustain specialized caseloads.
- Clinics:Outpatient voice clinics affiliated with hospital systems extend geographic reach through community-based locations, though they typically lack injection and surgical capabilities.
- Rehabilitation Centers:Post-acute and occupational voice rehabilitation programs serve employer-sponsored wellness contracts, expanding fastest in entertainment industry union and school district segments.
Hospitals capture the revenue concentration; private practices are expanding most quickly.
Technology:
Technology selection follows a cost-tier logic where premium precision-guided interventions command specialist margins and commoditized tools enable scaled behavioral delivery.
- Botulinum Toxin:Purified neurotoxin formulations require electromyography guidance for laryngeal muscle targeting, with manufacturing complexity limiting viable suppliers to specialized cold-chain facilities. Merz Pharmaceuticals GmbH and established neurology portfolios dominate physician mindshare in this segment.
- Speech Devices:FDA-cleared wearable biofeedback tools extend therapy into home-based rehabilitation protocols, penetrating rural catchments previously unreachable by specialized voice centers. SpeakSuite, Inc. and digital platform competitors drive commercialization in this expanding category.
- Manual Techniques:Laryngeal manual therapy and resonant voice training rely on clinician skill rather than capital equipment, constraining throughput but eliminating supply chain dependencies.
- Corticosteroids:Systemic and inhaled anti-inflammatory agents address acute vocal fold edema and laryngopharyngeal reflux overlap, confined to short-course protocols due to adverse event profiles.
Botulinum toxin commands the premium tier; speech devices show the steepest expansion trajectory.
Application:
Occupational voice demands create distinct risk profiles and reimbursement pathways across professional categories.
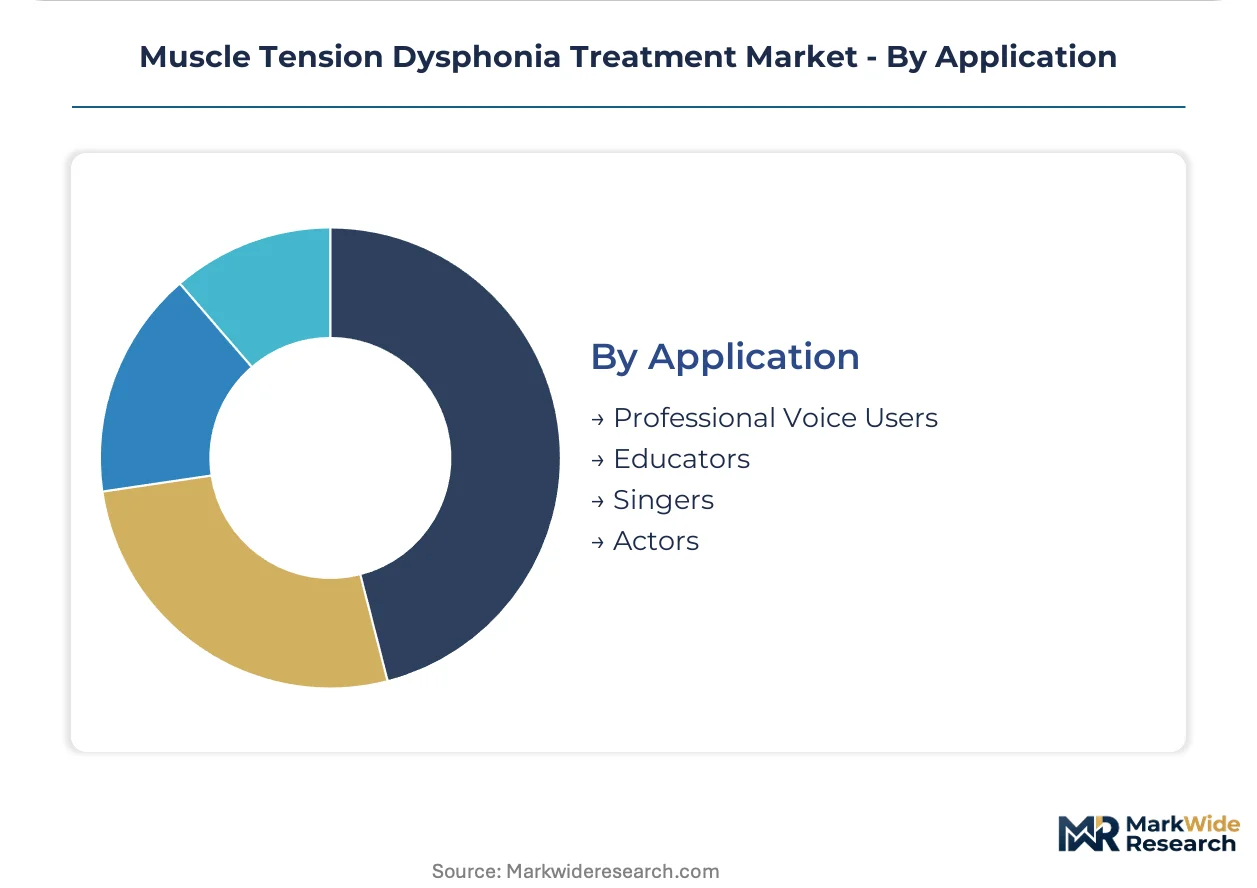
- Professional Voice Users:Broadcast anchors, call center operators, and clergy face sustained occupational phonotrauma, driving preventive screening and acute intervention demand through employer-sponsored and individual payment models.
- Educators:K-12 teachers and university faculty represent the largest addressable population, with school district wellness contracts piloting subscription-based access models replacing per-visit billing structures.
- Singers:Classical and commercial vocal performers require specialized performance voice therapy, concentrating demand in metropolitan cultural centers with conservatory and entertainment industry presence.
- Actors:Stage and screen performers present unique demands for vocal characterization and projection, with Broadway and regional theater unions funding early pilot programs in occupational voice wellness.
Educators represent the broadest population base; professional voice users generate the highest per-capita expenditure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics favor jurisdictions with streamlined FDA-equivalent pathways for speech therapy devices and botulinum toxin formulations. Manufacturers migrate toward markets offering accelerated digital health approvals and favorable reimbursement coding for telemedicine-delivered voice care.
United States
CMS reimbursement expansion for speech-language pathology services drives demand concentration in metropolitan clinical corridors. FDA oversight governs botulinum toxin products and speech therapy device classifications, while HIPAA frameworks dictate telehealth platform compliance. Tertiary academic voice centers in California, Texas, and New York anchor complex case management and injection procedures.
Germany
EMA regulations harmonize botulinum toxin approval pathways across EU member states, reducing cross-border market entry friction. The country's statutory health insurance system covers voice therapy for occupational dysphonia, supporting specialized laryngology practices in Berlin and Munich. Baden-Württemberg hosts several voice research institutes advancing resonant voice technique protocols.
United Kingdom
NHS England commissioning frameworks increasingly recognize muscle tension dysphonia within specialized voice service specifications. MHRA post-Brexit regulatory autonomy enables tailored digital health guidance for AI-assisted voice assessment tools. London's Royal National Throat, Nose and Ear Hospital maintains Europe's highest-volume voice therapy caseload.
Japan
PMDA streamlined approval pathways for software-as-medical-device applications accelerate telehealth platform commercialization. METI occupational health directives mandate voice hazard assessments for call center and broadcast industry employers. Tokyo and Osaka metropolitan areas concentrate specialized laryngology fellowship programs and voice center infrastructure.
Australia
TGA medical device regulations align with FDA predicate pathways, facilitating parallel submissions for speech biofeedback wearables. Medicare Benefits Schedule item numbers for speech-language pathology services support private practice voice therapy expansion. Sydney and Melbourne voice clinics pilot subscription-based employer wellness contracts for educator and performer populations.
Muscle Tension Dysphonia Treatment Market Competitive Landscape
Portfolio diversification dominates the current landscape as pharmaceutical incumbents and digital health entrants reposition around converging behavioral-procedural care models. The market exhibits tiered concentration: established neurology and dermatology players anchor the botulinum toxin premium segment, while venture-backed platforms capture telehealth-enabled voice therapy expansion. Three archetypes define competitive positioning: legacy pharmaceutical manufacturers with laryngeal injection formulations, digital therapy platform specialists, and diversified healthcare conglomerates with cross-portfolio synergies. M&A activity and strategic technology licensing represent the dominant competitive vectors as participants seek to bridge behavioral and procedural intervention capabilities.
Within the pharmaceutical archetype, Merz Pharmaceuticals GmbH and Pfizer Inc. exemplify contrasting approaches to physician mindshare in dysphonia management. Among digital platform specialists, SpeakSuite, Inc. occupies a position representing telehealth-first service delivery models. These three entities anchor distinct strategic postures: German-origin precision formulation expertise, diversified neurology portfolio leverage, and HIPAA-compliant remote therapy infrastructure respectively.
| Leading Market Players |
|---|
| Verboso LLC |
| SpeakSuite, Inc. |
| Pfizer Inc. |
| Merck & Co., Inc. |
| Astellas Pharma Inc. |
| AbbVie Inc. |
| Merz Pharmaceuticals GmbH |
| Ipsen S.A. |
| Cipl Inc. |
| Others |
Supply & Pricing Matrix
Academic medical center procurement committees concentrate purchasing power for botulinum toxin and electromyography systems, forcing manufacturers toward value-based contracting with bundled service tiers rather than unit-based transactional models.
Pricing Analysis
Distributor margins on laryngeal injection products compress as direct hospital system contracting expands. Three-tier pricing structure across premium electromyography-guided formulations, standard botulinum toxin vials, and economy unguided injection protocols reflects certification requirements and cold-chain handling complexity. Pricing pressure stems from CMS reimbursement rate stagnation for speech-language pathology services. Private practice voice therapy clinics exhibit highest price sensitivity due to cash-pay patient mixes, while tertiary academic centers absorb premium tiers through institutional purchasing power.
Supply Chain Analysis
Cold-chain logistics costs for botulinum toxin constrain distribution radius and inflate landed costs in non-metropolitan catchments. Manufacturing concentrates in Germany, Ireland, and the United States, with active pharmaceutical ingredient sourcing anchored in Switzerland and Japan. Supply chain risk centers on single-source vulnerability for electromyography needle electrodes, which draw from Japanese precision manufacturing. Distribution runs through specialty pharmaceutical wholesalers with laryngology-focused sales forces, bypassing general medical distributors for injection products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory-arbitrage opportunities favor jurisdictions with accelerated FDA-equivalent pathways for software-as-medical-device classifications, where Japan's PMDA streamlines telehealth platform approvals faster than US FDA timelines compress go-to-market costs.
For Market Incumbents: Deploy dual-therapy bundling to entrench voice therapy and injection services within single institutional contracts. Deepen backward integration into electromyography needle manufacturing to offset Japanese supply concentration risk. Fortify against digital platform substitution by embedding AI-assisted voice assessment into proprietary clinic workflows, creating switching costs for academic medical center customers. For New Entrants and Emerging Players: Rural school district occupational health programs represent the most penetrable buyer archetype, underserved by metropolitan voice center density gaps. Capture this white-space through subscription-based telehealth delivery models that bypass per-visit reimbursement constraints. Partner with state education agencies to embed voice wellness screening into mandatory teacher health assessments, securing anchor contracts for platform scaling. For Investors and Strategic Acquirers: Diversified healthcare conglomerates with neurology and rehabilitation portfolios are the most active acquirer in this space, seeking digital therapy assets to complement injection franchises. Long-term viability hinges on reimbursement parity durability for telehealth-delivered voice care. Monitor state-level digital health legislation adoption as the inflection signal for platform valuation expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Submission | Clearance enables billing codes for AI-assisted voice assessment in CMS-reimbursed telehealth sessions. |
| Academic Medical Center Partnership | Integration with tertiary laryngology programs secures referral volume for complex injection cases. |
| Reimbursement Strategy Development | CPT code optimization for prolonged voice therapy protocols expands addressable patient populations. |
| Hospital System Partnership | Community clinic network access extends geographic reach beyond metropolitan voice center corridors. |
| CE Marking Pathway | EMA harmonization enables single regulatory entry into German statutory insurance-covered markets. |
Research Methodology
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with laryngology fellowship directors, speech-language pathology clinic managers, hospital GPO contract specialists, and digital health platform executives informed demand-side assumptions. Secondary sources include FDA 510(k) filings, CMS Medicare reimbursement databases, PMDA software-as-medical-device approval registers, and hospital procurement contract disclosures. Bottom-up patient volume estimates triangulated against top-down pharmaceutical shipment data.
Rate-of-change decomposition isolates volume expansion from price-mix effects across the projection horizon. Segmentation dimensions modeled include treatment type, end-user facility category, technology tier, and professional voice user application. CAGRs derive from logistic diffusion curves for telehealth adoption and procedure volume trend extrapolation. Forecast inputs incorporate CMS coding updates, fellowship program graduation rates, and employer wellness contract penetration assumptions.
Underlying measurement precision varies by segment; voice therapy visit volumes carry tighter precision than emerging speech device adoption curves. Forecasts reflect assumptions about reimbursement parity durability and regulatory guidance timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Intravenous (IV) Ibuprofen Market
Pain Management
Global Analgesic Infusion Pumps Market
Pain Management
Asia-Pacific Chronic Disease Management Market
Pain Management
Global Fibromyalgia Treatment Market
Pain Management
Axial Spondyloarthritis Management Market
Pain Management
Topical Pain Relief Cream Market
Pain Management
Global Visceral Pain Treatment Market
Pain Management
Bone Pain Treatment Market
Pain Management
Advanced Cancer Pain Management Market
Pain Management
Opioid Withdrawal Management Market
Pain Management
Cluster Headache Market
Pain Management
Lumbosacral Radicular Pain Management Market
Pain Management
Topical Pain Relief Market
Pain Management
Provoked Vestibulodynia Treatment Market
Pain Management
Medical Morphine Market
Pain Management
Pain Management Devices Market