
 North America Dental Lasers Market | 2026-2036
North America Dental Lasers Market Size, Share, and Industry Trends Forecast 2026-2036
North America Dental Lasers Market Insights
Market Dynamics
Canada is reconfiguring its dental laser distribution infrastructure through expanded training partnerships with Canadian dental schools. Biolase Inc leverages its proprietary Waterlase technology to sustain premium positioning across North American dental clinics. Dentsply Sirona Inc anchors its market presence through integrated CAD/CAM and laser workflow ecosystems. Fotona competes on dual-wavelength platform versatility across soft and hard tissue applications.
Technology and Segmentation
Dental lasers are solid-state or semiconductor devices emitting coherent light at specific wavelengths—typically 810–980 nm for diode systems and 2940 nm for Er:YAG platforms—to enable precise tissue ablation with minimal thermal collateral damage. Er:YAG lasers dominate hard tissue applications due to peak hydroxyapatite absorption, while diode systems lead soft tissue surgery volumes on lower capital thresholds. Fiber optic delivery technology commands the technology segment through compatibility advantages across multiple laser families. Dental clinics represent the primary end-user channel, absorbing systems through equipment financing programs and group purchasing organizations.
Regulatory Environment
FDA 510(k) premarket notification requirements govern dental laser device commercialization in the United States, while Health Canada's Medical Devices Bureau enforces parallel licensing standards across provinces. The ADA Council on Scientific Affairs publishes technology assessments that shape payer reimbursement attitudes and clinical adoption curves. Stakeholders must monitor evolving state-level scope-of-practice regulations that determine which dental professionals may operate laser systems independently.
Market Dynamics
Metropolitan dental service organizations across California, Texas, and Ontario are consolidating procurement through group purchasing organizations, compressing vendor margins while demanding integrated training and service bundles.
Growth Catalysts
- FDA 510(k) pathway acceleration:Streamlined premarket notification reviews for new wavelengths are shortening commercialization timelines for diode and Er:YAG platforms.
- Canadian dental school partnerships:Expanded training infrastructure at University of Toronto and University of British Columbia is building operator confidence and system utilization rates.
- Periodontal procedure volume expansion:Laser-assisted periodontal therapy is displacing conventional scalpel techniques in high-volume urban clinics.
Market Restraints
- Er:YAG crystal supply concentration:Synthetic garnet substrate production clusters in select East Asian facilities, exposing North American OEMs to input volatility.
- State scope-of-practice fragmentation:Inconsistent hygienist laser operation permissions across US states create training and liability complexity for multi-state dental service organizations.
- Diode wavelength substitution pressure:Lower-cost 810 nm systems from non-specialized photonics manufacturers erode premium positioning of established dental-specific platforms.
Strategic Opportunities
- Canadian provincial procurement centralization:Ontario and Alberta health system purchasing reforms favor bundled device-service-training contracts for dental clinic networks.
- Er:YAG-hard tissue CAD/CAM convergence:Integrated laser-milling workflows are opening same-visit crown preparation and fabrication protocols.
- ADA technology assessment tailwinds:Evolving clinical validation protocols are accelerating payer reimbursement acceptance for laser-assisted procedures.
Industry Challenges
- Laser safety certification bottlenecks:ANSI Z136.3 compliance training capacity constraints delay staff credentialing and system deployment timelines.
- Legacy billing system integration:Dental practice management software requires custom coding to capture laser-specific procedure codes accurately.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Dental Lasers Market |
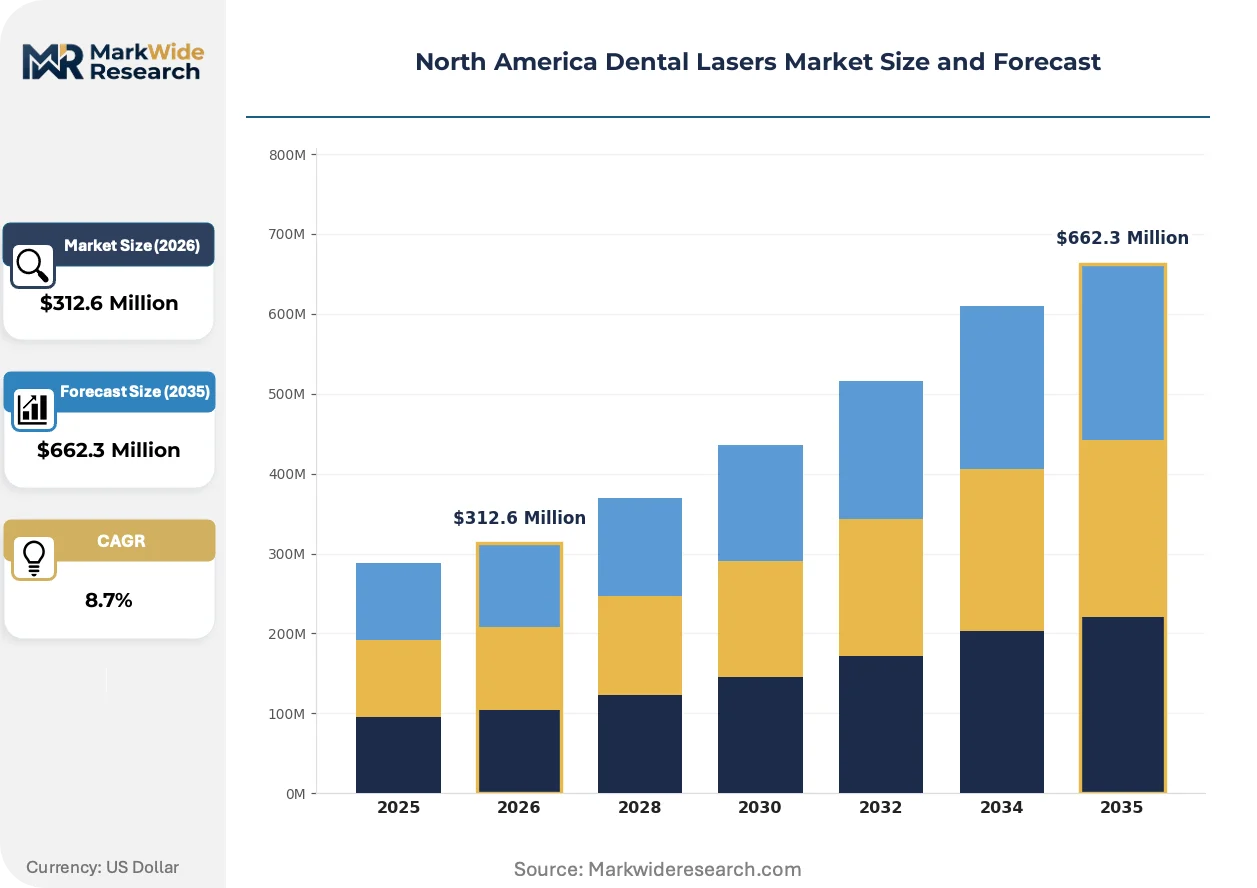
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $662.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diode Lasers, Nd:YAG Lasers, Er:YAG Lasers, Solid-State Lasers End User: Dental Clinics, Hospitals, Research Institutions, Universities Application: Soft Tissue Surgery, Teeth Whitening, Periodontal Treatment, Endodontics Technology: Fiber Optic, Calibrated Arm, Tabletop, Portable |
| Companies Covered | Biolase Inc, Dentsply Sirona Inc, Fotona, Convergent Dental, AMD Lasers, CAO Group Inc, Lumenis, Envista Holdings Corp, IPG Photonics Corp, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Dental Lasers Market Trends and Innovations
Device architecture is pivoting toward modular platforms that accommodate wavelength swapping without full system replacement, reducing capital barriers for mid-sized clinic groups.
Er:YAG laser systems are migrating from standalone hard tissue ablation tools toward integrated periodontal-endodontic platforms. Multi-specialty dental groups in Texas and Florida are adopting these versatile configurations at accelerated replacement cycles. This convergence is compressing the addressable market for single-wavelength diode systems in high-volume metropolitan practices.
Health Canada's Medical Devices Bureau is harmonizing laser classification standards with FDA 510(k) technical documentation requirements. This regulatory alignment reduces redundant testing burdens for manufacturers seeking simultaneous US-Canada market entry. Canadian distributors are responding by consolidating cross-border logistics and technical support infrastructure.
Equipment financing programs are displacing outright capital purchase as the dominant acquisition mode. Dental service organizations in California and Ontario are negotiating master lease agreements with bundled maintenance and upgrade provisions. This shift is most visible among 10-25 location clinic groups seeking to standardize technology platforms without balance sheet concentration.
North America Dental Lasers Market Segmentation
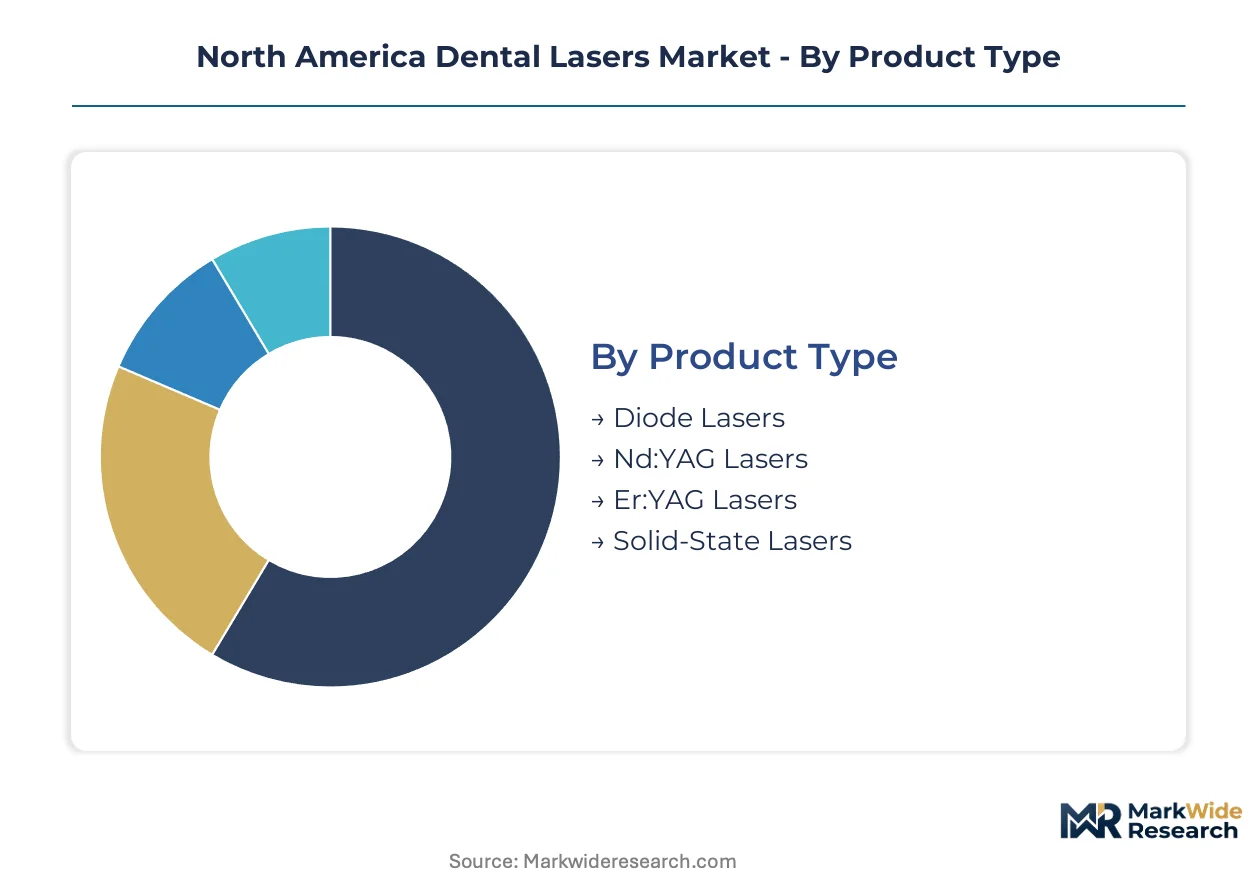
Dental laser procurement patterns diverge sharply across clinical settings and procedure types. Equipment financing terms, operator certification requirements, and reimbursement coding complexity create distinct purchasing behaviors for each segment.
Product Type:
After-sales service intensity varies dramatically by laser family, with crystal-based platforms demanding specialized technical support that shapes vendor selection criteria.
- Diode Lasers:Semiconductor devices emitting coherent light at 810–980 nm wavelengths. Demand concentrates in high-volume soft tissue practices across Texas and Florida, where lower capital thresholds enable rapid payback on gingivectomy and frenectomy volumes. By volume, Diode Lasers lead. By growth pace, Er:YAG Lasers are ahead.
- Er:YAG Lasers:Solid-state platforms operating at 2940 nm with peak hydroxyapatite absorption for hard tissue ablation. Adoption accelerates in California metropolitan dental service organizations seeking same-visit crown preparation workflows integrated with CAD/CAM systems.
- Nd:YAG Lasers:Neodymium-doped yttrium aluminum garnet systems penetrating periodontal therapy niches with deeper tissue penetration capabilities.
- Solid-State Lasers:Broad category encompassing crystal and glass laser media, serving multi-wavelength platform requirements in academic medical center settings.
Service contract attachment rates run highest for Er:YAG platforms due to optical component degradation sensitivity.
End User:
Procurement scale and decision velocity separate these channels, with group purchasing organization leverage creating tiered pricing outcomes.
- Dental Clinics:Independent and group practice settings absorbing the majority of system placements. California and Ontario dental service organizations are consolidating procurement through master lease agreements with bundled maintenance provisions.
- Hospitals:Academic medical centers and integrated delivery networks requiring multi-specialty compatibility across oral surgery and ENT departments. Equipment committees extend evaluation cycles but generate larger average order values.
- Research Institutions:Limited-volume channel prioritizing wavelength flexibility and data acquisition capabilities for clinical validation studies.
- Universities:Canadian dental schools at University of Toronto and University of British Columbia are expanding training fleet purchases to build operator confidence pipelines.
Volume concentration sits with Dental Clinics, while Universities are expanding most quickly as training infrastructure investments accelerate.
Application:
Procedure reimbursement coding maturity determines adoption friction, with established codes accelerating deployment and emerging indications facing payer skepticism.
- Soft Tissue Surgery:Gingivectomy, frenectomy, and biopsy procedures represent the highest-procedure-volume application. Diode systems dominate this segment due to capital efficiency and established ADA coding recognition.
- Periodontal Treatment:Laser-assisted periodontal therapy is displacing conventional scalpel techniques in high-volume urban clinics across Texas and Florida. ADA technology assessment tailwinds are accelerating payer acceptance.
- Teeth Whitening:Low-power activation applications with limited hardware requirements and compressed margins.
- Endodontics:Emerging application segment leveraging Er:YAG wavelength compatibility for canal disinfection protocols in multi-specialty dental groups.
Soft Tissue Surgery commands procedure volume leadership, while Periodontal Treatment is gaining share fastest as clinical validation accumulates.
Technology:
Delivery mechanism selection constrains wavelength compatibility and operator mobility, creating platform lock-in effects that shape replacement cycles.
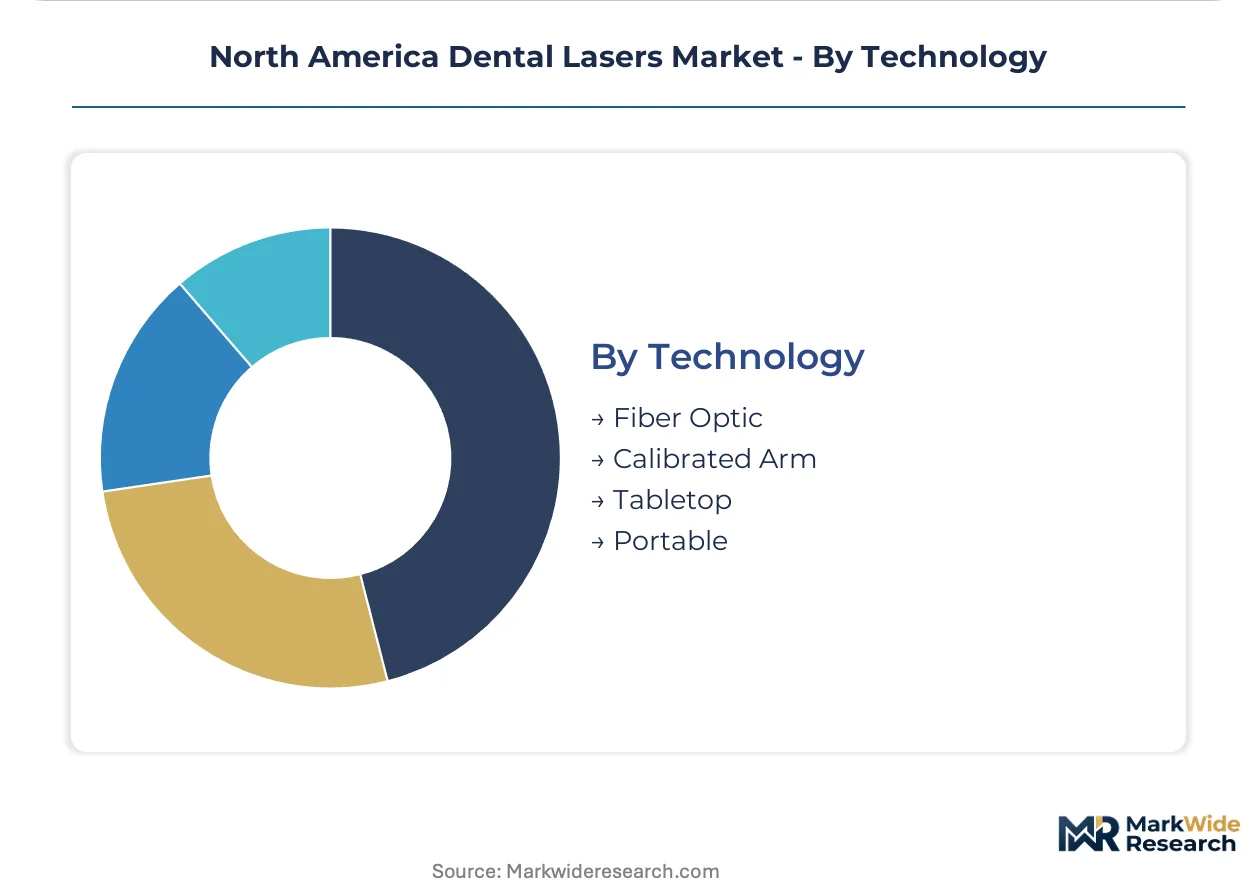
- Fiber Optic:Flexible silica-based delivery systems compatible across diode and Nd:YAG families. Dominates technology segment through multi-platform compatibility advantages in dental clinic settings.
- Calibrated Arm:Articulated beam delivery systems enabling precise positioning for hard tissue applications. Preferred for Er:YAG integration with CAD/CAM milling workflows.
- Tabletop:Fixed-configuration systems serving high-volume specialty practices with dedicated operatories.
- Portable:Battery-powered and lightweight configurations targeting mobile dental units and rural outreach programs.
Fiber Optic holds volume leadership, though Calibrated Arm configurations are climbing the fastest as hard tissue-CAD/CAM convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles-Long Beach maritime complex underwrites California's dominance in dental laser distribution, handling precision optical component imports from East Asian crystal foundries that feed West Coast assembly operations.
United States
Metropolitan dental service organizations across California, Texas, and Florida are consolidating procurement through group purchasing organizations. FDA 510(k) premarket notification pathways govern device commercialization timelines. Los Angeles and Dallas-Fort Worth dental clinic networks are negotiating master lease agreements with bundled maintenance provisions.
Canada
Ontario and British Columbia dental schools are expanding training fleet purchases to build operator confidence pipelines. Health Canada's Medical Devices Bureau enforces licensing standards harmonizing with FDA technical documentation requirements. Toronto and Vancouver metropolitan clinic networks are centralizing provincial procurement through bundled device-service-training contracts.
Mexico
Northern border states are emerging as secondary distribution corridors for US-manufactured diode systems serving cross-border dental tourism flows. Mexico's national health regulator, COFEPRIS, maintains parallel medical device registration requirements. Tijuana and Monterrey dental clinic clusters are adopting laser-assisted periodontal protocols at accelerated rates.
North America Dental Lasers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying optical crystals, fiber delivery systems, and solid-state gain media. The vendor base stratifies across three tiers: established multi-modality dental equipment conglomerates, pure-play laser specialists with proprietary wavelength platforms, and contract manufacturers serving private-label distributors. Two dominant competitive moves are reshaping positioning: wavelength modularity investments that reduce replacement cycle friction, and integrated CAD/CAM workflow partnerships that harden ecosystem lock-in.
Among North American platform specialists, Biolase Inc and Dentsply Sirona Inc occupy distinct archetype positions. Biolase exemplifies the wavelength-proprietary specialist model through its integrated water-cooled delivery systems. Dentsply Sirona represents the conglomerate integrator archetype, anchoring market presence through cross-platform workflow ecosystems. Fotona, with its dual-wavelength platform heritage, sits within the European-origin specialist tier competing on versatility across soft and hard tissue applications.
| Leading Market Players |
|---|
| Biolase Inc |
| Dentsply Sirona Inc |
| Fotona |
| Convergent Dental |
| AMD Lasers |
| CAO Group Inc |
| Lumenis |
| Envista Holdings Corp |
| IPG Photonics Corp |
| Others |
Pricing and Supply Chain Analysis
Synthetic garnet substrate production clusters in select East Asian facilities, concentrating upstream optical crystal supply and tethering margin pools to diode and Er:YAG system vendors with captive technical service capabilities. Equipment financing programs now dominate capital acquisition, compressing upfront price realization while extending vendor revenue recognition across bundled maintenance and upgrade cycles.
Pricing Analysis
FDA 510(k) premarket notification requirements dictate the pricing tier structure across North American dental laser markets, separating premium-positioned Waterlase-integrated platforms from standard diode configurations and economy-tier non-specialized photonics imports. Price differentiation rests on after-sales service bundling and ANSI Z136.3 laser safety certification completeness, with California dental service organizations exhibiting highest price sensitivity through group purchasing organization leverage while academic medical centers absorb premium positioning for multi-specialty compatibility.
Supply Chain Analysis
Export control regimes governing high-purity synthetic crystal growth technology limit Er:YAG substrate flows from select East Asian foundries, exposing North American OEMs to input volatility. Supply concentration centers on China, Japan, and South Korea for garnet substrates, fiber optic delivery systems, and solid-state gain media, with tariff exposure on precision optical components representing the dominant structural risk. Distribution runs through Los Angeles-Long Beach maritime terminals feeding West Coast assembly operations and Toronto-Vancouver corridors serving Canadian provincial procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against conventional scalpel and mechanical instrumentation techniques that retain cost advantages in rural and price-sensitive metropolitan segments. Incumbents must navigate reimbursement coding gaps that delay laser-assisted procedure adoption in Medicaid-dependent patient populations.
For Market Incumbents: Harden ecosystem lock-in through integrated CAD/CAM workflow partnerships that embed laser systems within same-visit crown preparation protocols, while deepening backward integration into fiber optic delivery manufacturing to defend margin position against 810 nm diode substitution pressure from non-specialized photonics entrants.
For New Entrants and Emerging Players: Mexico's northern border states offer underpenetrated white-space access through COFEPRIS-registered diode systems serving cross-border dental tourism flows, with Tijuana and Monterrey clinic clusters representing the most penetrable geography for portable, battery-powered configurations targeting mobile dental units.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed dental equipment conglomerates seeking platform rationalization, positioning modular wavelength-swapping specialists for acquisition at favorable multiples. Watch Health Canada-FDA regulatory harmonization progress as the inflection signal for cross-border logistics consolidation plays.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Wavelength Platform Development | Reduces replacement cycle friction for mid-sized California and Ontario clinic groups seeking capital efficiency. |
| Canadian Dental School Training Partnership | Builds operator confidence pipelines at University of Toronto and University of British Columbia to accelerate utilization rates. |
| Integrated CAD/CAM Workflow Partnership | Embeds Er:YAG systems within same-visit crown preparation protocols at Dallas-Fort Worth and Los Angeles metropolitan networks. |
| Master Lease Agreement Standardization | Aligns equipment financing terms with bundled maintenance provisions for 10-25 location dental service organizations. |
| ANSI Z136.3 Compliance Training Expansion | Resolves laser safety certification bottlenecks delaying staff credentialing and system deployment timelines. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) premarket notification databases, Health Canada Medical Devices Bureau licensing records, and ADA Council on Scientific Affairs technology assessments. Interviews with dental clinic procurement directors, biomedical equipment specialists at academic medical centers, GPO contracts managers, and periodontal practice owners combined with bottom-up procedure volume modeling and top-down equipment shipment analysis.
Forecast inputs span laser family adoption curves, replacement cycle compression from modular platforms, and provincial procurement centralization patterns across the analysis window. Segmentation dimensions include product type, end-user channel, application procedure category, and delivery technology. CAGRs derive from equipment financing penetration rates and training infrastructure expansion timelines.
Practitioners should monitor Er:YAG crystal supply disruptions, state-level scope-of-practice liberalization for hygienist laser operation, and ADA reimbursement coding updates for early signals. Material shifts in FDA 510(k) review timelines or Health Canada classification harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
China Dental Devices Market
Dental Devices
GCC Dental Implants Market
Dental Devices
Spain Dental Devices Market
Dental Devices
Dental Veneers Market
Dental Devices
Dental Hand Tools Market
Dental Devices
Dental Crown Removal Market
Dental Devices
Prophylaxis Pastes Market
Dental Devices
Global Digital Dentistry Market
Dental Devices
Global Veterinary Dentistry Instruments and Equipment Market
Dental Devices
Root Canal Market
Dental Devices
Self-Ligating Bracket Sales Market
Dental Devices
India Dental Devices Market
Dental Devices
Nano Dentistry Market
Dental Devices
Global Periodontal Market
Dental Devices
Gingivitis Treatment Market
Dental Devices
Global Dental Bone Graft Substitutes Market