
 3D Printing Dental Device Market | 2026-2036
3D Printing Dental Device Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing Dental Device Market Outlook
Dental laboratory buyer concentration is rebalancing as midsize labs consolidate procurement while independent clinics fragment into distributed manufacturing nodes. Stratasys leverages polymer expertise to anchor high-throughput orthodontic aligner production. Formlabs competes through desktop resin systems that occupy chairside workflows in smaller practices. SprintRay differentiates with specialized dental resin ecosystems that control material-to-printer compatibility.
3D printing dental devices are additively manufactured prosthetics, restorations, and appliances produced through layer-by-layer deposition with typical build resolutions of 25-100 microns, serving the core purpose of replacing or supporting intraoral structures with patient-matched geometry. Crown and bridge fabrication within the device type segment sustains the largest revenue pool due to restoration volume, while orthodontic appliances represent the fastest-expanding category as clear aligner production scales. Resin materials dominate current utilization because photopolymer formulations enable biocompatible, tooth-colored outputs with acceptable mechanical properties for provisional and definitive restorations.
FDA 510(k) clearance requirements and ISO 13485 quality management standards shape product development timelines and capital requirements for manufacturers entering the United States market. The EU Medical Device Regulation imposes stricter clinical evidence thresholds on custom-made dental devices, compressing margin structures for firms lacking notified body relationships. Stakeholders must monitor evolving biocompatibility testing protocols for novel ceramic-filled resins as material innovation outpaces standardization.
Market Dynamics
Chairside manufacturing is compressing turnaround times for dental restorations while FDA 510(k) pathways accelerate device clearance velocity. This dual pressure is fragmenting production geography and rewiring procurement relationships between laboratories and clinical practices.
Growth Catalysts
- Photopolymer formulation advances:Ceramic-filled resins achieve flexural strength thresholds for definitive crown placement. Dental laboratories in Germany and Italy are converting milling workflows to vat polymerization.
- ISO 13485 certification expansion:Quality management standardization reduces regulatory friction for mid-cap manufacturers seeking multi-jurisdiction entry. This lowers capital barriers for specialized resin producers.
- Clear aligner volume surge:Orthodontic appliance demand is pulling high-throughput printer installations into centralized production facilities serving multi-clinic networks.
Market Restraints
- Raw material concentration:Photoinitiator supply chains cluster in Chinese chemical manufacturing zones, exposing resin formulators to input volatility and tariff exposure.
- Biocompatibility testing bottlenecks:ISO 10993 cytotoxicity protocols require 12-18 month validation cycles for novel ceramic-filled formulations, delaying product launches.
- Digital impression substitution:Intraoral scanning is displacing physical impressions, compressing demand for traditional model-based workflows in smaller practices.
Strategic Opportunities
- Underpenetrated Japanese market:PMDA regulatory harmonization with ISO standards is streamlining 3D-printed device approval, opening access to 60,000+ dental clinics with low current additive penetration.
- Same-day surgical guide production:Implantology practices are integrating chairside printing for patient-matched drilling templates, bypassing laboratory intermediaries.
- EU MDR custom-device pathways:Stricter clinical evidence requirements for mass-produced devices create competitive shelter for validated custom-manufacturing workflows.
Industry Challenges
- CAD/CAM integration complexity:Dental practices face steep learning curves bridging intraoral scan data to printer-native file formats, requiring dedicated technician hiring.
- Post-processing labor intensity:Resin washing and UV curing steps demand manual handling that erodes chairside efficiency gains, pushing clinics toward hybrid lab-clinic models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing Dental Device Market |
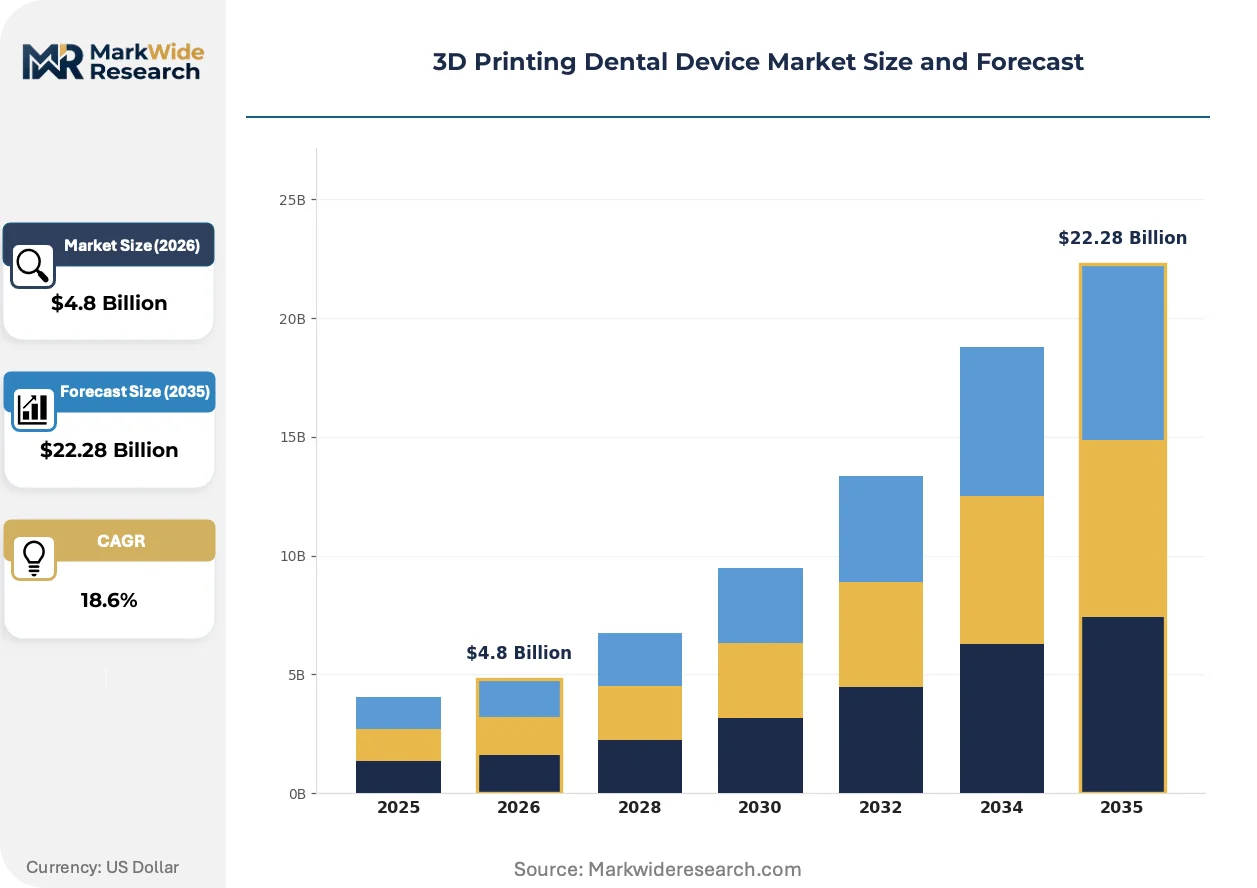
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Denture, Crown, Implant, Orthodontic Appliance Material: Resin, Metal, Ceramic, Plastic Technology: SLA, SLS, FDM, DLP End User: Dental Clinics, Dental Labs, Hospitals, Individuals |
| Companies Covered | 3D Systems, Stratasys, Formlabs, Dentsply Sirona, Desktop Metal, SprintRay, Renishaw, Asiga, Ackuretta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing Dental Device Market Strategic Shifts
Artificial intelligence is reshaping design-to-manufacture pipelines for patient-matched dental devices. Three converging developments are compressing production timelines and redistributing value capture across the supply chain.
AI-powered nesting algorithms are automating build preparation for multi-unit crown batches. Dental laboratories serving high-volume prosthodontics are adopting these tools to maximize printer bed utilization and reduce resin waste per build. This compression of pre-production labor is enabling smaller labs to achieve throughput parity with centralized competitors.
The EU Medical Device Regulation is tightening clinical evidence requirements for novel material formulations. Manufacturers seeking CE marking for ceramic-filled resins must now submit biocompatibility data beyond ISO 10993 baseline testing. German notified bodies are processing these expanded dossiers, creating regulatory capacity constraints that favor established players with existing body relationships.
Subscription-based equipment financing is displacing capital purchase models among independent dental practices. Printer OEMs are bundling resin supply agreements with hardware leases, locking in material volume commitments. This shift is most visible in the United States, where IRA-related tax incentives for medical equipment investment are accelerating lease adoption over outright ownership.
3D Printing Dental Device Market Segmentation
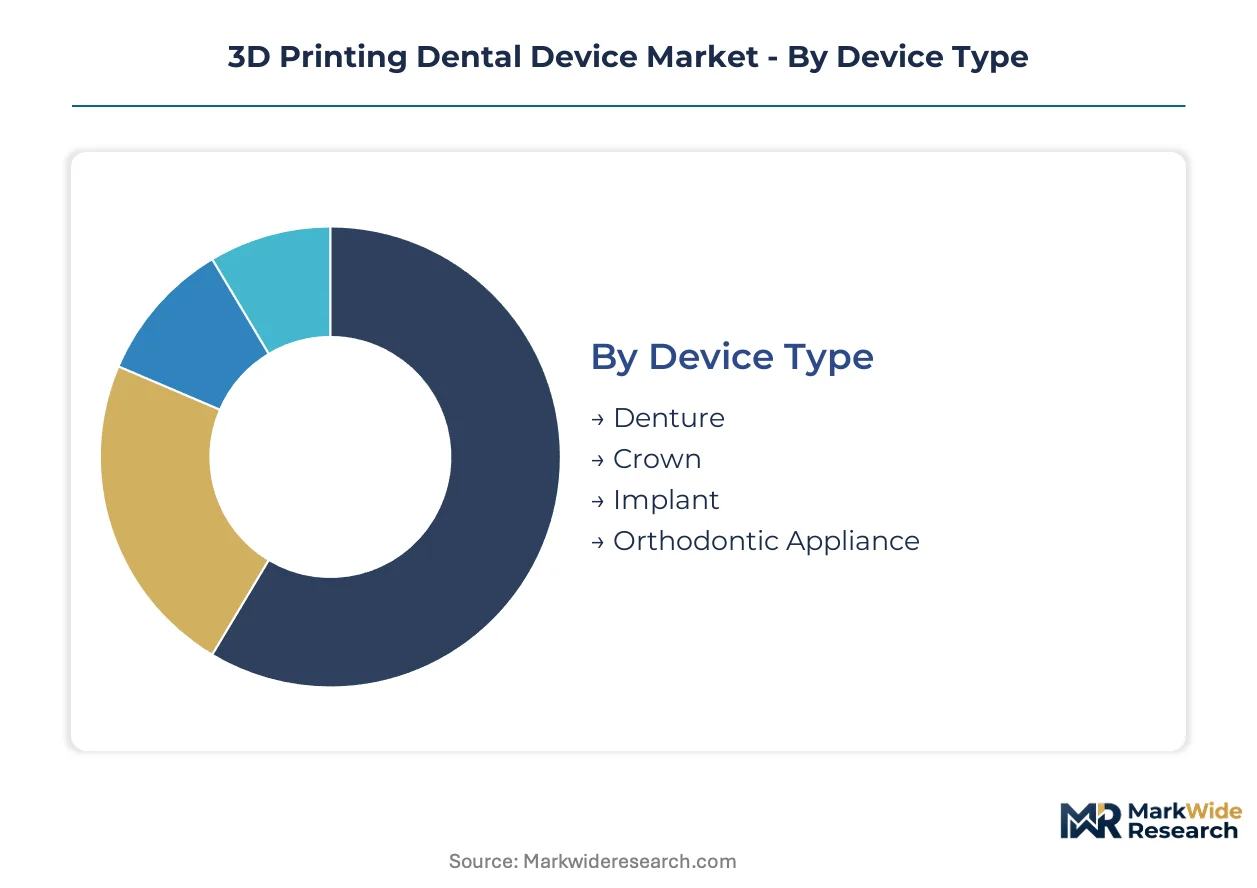
Segmentation in 3D printing dental devices reveals how procurement decisions split across clinical workflow integration, material biocompatibility requirements, and production scale economics. Understanding these divides exposes where printer OEMs and resin suppliers capture margin.
Device Type:
Clinical indication determines whether buyers prioritize mechanical strength, aesthetic matching, or production throughput in their printer selection.
- Crown:Layer-by-layer resin deposition produces patient-matched anatomical restorations with 25-50 micron resolution. German dental laboratories in Stuttgart and Munich clusters are converting milling workflows to vat polymerization for single-visit definitive placement.
- Orthodontic Appliance:Clear aligner manufacturing demands high-throughput stereolithography systems capable of 24-hour batch production. United States multi-clinic networks are installing centralized printing facilities to serve geographic patient bases.
- Denture:Digital denture base fabrication uses biocompatible photopolymers with validated color stability protocols. Demand concentrates in Japan's aging patient population with PMDA-cleared material workflows.
- Implant:Surgical guides and custom abutments require ISO 13485-validated titanium or PEEK printing. Italian implantology practices in Milan and Bologna are adopting chairside production for immediate loading protocols.
Crown fabrication leads volumes today; orthodontic appliances are gaining share fastest.
Material:
Material selection locks buyers into specific printer ecosystems and determines regulatory pathway complexity for biocompatibility clearance.
- Resin:Photopolymer formulations dominate current utilization through ceramic-filled and nanohybrid compositions achieving 120-150 MPa flexural strength. FDA 510(k) clearances for temporary and definitive crown resins are accelerating in the United States market.
- Metal:Cobalt-chrome and titanium powder bed fusion serves implant superstructures and removable partial frameworks. German dental laboratories leverage existing milling expertise to adopt selective laser melting for high-strength applications.
- Ceramic:Zirconia and alumina suspensions in photopolymer matrices enable aesthetic anterior restorations. EU MDR clinical evidence requirements for ceramic-filled resins are compressing development timelines for novel formulations.
- Plastic:ABS and PLA filaments serve orthodontic model production and thermoforming templates. Cost-sensitive independent practices in India favor fused deposition modeling for diagnostic wax-up fabrication.
Resin materials command the largest installed base; ceramic-filled formulations are climbing the fastest as definitive indication approvals expand.
Technology:
Technology choice reflects the trade-off between capital intensity, build speed, and surface finish requirements across different clinical applications.
- SLA:Laser-based stereolithography delivers sub-25 micron precision for crown margin accuracy. Large dental laboratories in Germany deploy industrial SLA systems for overnight batch production of 50-plus units.
- DLP:Digital light projection enables full-layer curing in single exposures, compressing build times for aligner manufacturing. United States clear aligner producers favor DLP for high-throughput centralized facilities.
- SLS:Selective laser sintering of nylon and PEEK supports durable removable appliances and surgical guides. Italian dental labs integrate SLS for metal-free partial denture frameworks.
- FDM:Fused deposition modeling offers lowest capital entry point for model printing and thermoforming templates. Indian dental colleges deploy FDM systems for pre-surgical planning education.
SLA retains the broadest installed base; DLP is expanding most quickly in aligner production.
End User:
End-user category determines whether additive manufacturing occurs in centralized production facilities or distributed chairside workflows.
- Dental Labs:High-volume prosthodontic production centers in Germany and Italy aggregate printer investments across multi-clinic client bases. These facilities achieve economies of scale through 24-hour batch operations and specialized technician staffing.
- Dental Clinics:Chairside integration demands compact footprint systems with simplified post-processing. United States group practices are leasing printer-resin bundles to bypass laboratory intermediaries for crown delivery.
- Hospitals:Academic medical centers combine 3D printing with maxillofacial surgical planning. Japanese university hospitals deploy additive manufacturing for complex craniofacial reconstruction templates.
- Individuals:Direct-to-consumer aligner companies operate captive printing networks. Regulatory scrutiny from FDA and state dental boards constrains this channel in the United States.
Dental laboratories lead production volumes today; dental clinics are gaining share fastest through chairside adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's dental laboratory density contrasts with Japan's emerging clinic-level adoption, illustrating how mature manufacturing ecosystems diverge from regulatory-driven catch-up growth in additive dental production.
United States
FDA 510(k) clearance velocity accelerates market entry for ceramic-filled crown resins while group practice consolidation drives centralized aligner printing investments. The IRA medical equipment tax incentive is shifting procurement toward lease-based printer-resin bundles. Texas and Florida dental service organizations are deploying chairside systems to bypass laboratory intermediaries.
Germany
Stuttgart and Munich laboratory clusters achieve 24-hour batch economies through industrial vat polymerization systems serving multi-clinic prosthodontic networks. EU MDR notified body relationships favor established resin formulators with existing CE marking pathways. Baden-Württemberg dental labs are converting subtractive milling workflows to additive crown production.
Japan
PMDA regulatory harmonization with ISO 13485 standards is streamlining 3D-printed device approval for 60,000 dental clinics with low current additive penetration. METI industrial policy supports domestic printer-resin ecosystem development. Tokyo and Osaka university hospitals deploy additive manufacturing for complex craniofacial surgical templates.
Italy
Milan and Bologna implantology practices adopt chairside printing for immediate-loading surgical guides and custom abutments. ANSM clinical evidence requirements for ceramic-filled resins compress development timelines for novel formulations. Emilia-Romagna dental laboratories integrate selective laser sintering for metal-free partial denture frameworks.
India
Cost-sensitive independent practices in Maharashtra and Gujarat favor fused deposition modeling for diagnostic wax-up fabrication and thermoforming templates. CDSCO medical device rules are formalizing quality management requirements for imported printer systems. Karnataka dental colleges deploy additive systems for pre-surgical planning education.
3D Printing Dental Device Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across equipment, materials, and software layers. The vendor base stratifies into three tiers: industrial-scale system manufacturers, desktop workflow integrators, and regional resin formulators. Strategic moves concentrate on M&A for digital workflow integration and capacity expansion for aligner production networks.
Among diversified industrial players, 3D Systems and Stratasys occupy positions spanning multiple additive modalities and end-market verticals. Formlabs exemplifies the desktop-specialist archetype through compact resin system deployment. SprintRay represents the dental-native pure-play model with controlled material-to-printer compatibility ecosystems.
| Leading Market Players |
|---|
| 3D Systems |
| Stratasys |
| Formlabs |
| Dentsply Sirona |
| Desktop Metal |
| SprintRay |
| Renishaw |
| Asiga |
| Ackuretta |
| Others |
Value Chain & Pricing Dynamics
Photoinitiator feedstock costs originating in Chinese chemical manufacturing zones cascade through resin formulation tiers before reaching dental laboratory procurement desks in Germany and the United States. This input concentration grants material suppliers pricing leverage over printer OEMs bundling resin subscriptions, while tariff exposure on specialty chemicals compresses margin structures for mid-cap formulators lacking backward integration.
Pricing Analysis
Capacity additions in Chinese photopolymer manufacturing are reshaping price floors for ceramic-filled resin formulations across export markets. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified definitive indications from provisional crown resins and unvalidated economy grades. Price differentiation hinges on FDA 510(k) clearance status and flexural strength certification, with United States group practices showing lowest price sensitivity due to bundled lease-tax incentives, while Indian independent clinics drive volume at economy tiers.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Dallas, and Singapore maintain hub-and-spoke patterns serving dental laboratory clusters with 48-hour resin replenishment cycles. Photoinitiator supply concentrates in Jiangsu and Zhejiang provinces, with German and Japanese resin formulators drawing from these inputs for ceramic-filled formulations. Single-source vulnerability in specialty photoinitiator chemistry exposes formulators to regulatory restriction risk from China's export control protocols. Distribution runs through authorized dealer networks controlling printer-resin compatibility ecosystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory ratcheting, with FDA 510(k) clearance velocity for definitive crown resins accelerating replacement demand from legacy milling workflows.
For Market Incumbents: Anchor market position through captive resin supply agreements that lock dental laboratories into material-to-printer ecosystems, while accelerating ISO 13485 certification for ceramic-filled formulations to exploit EU MDR clinical evidence bottlenecks. Defend against chairside disruption by leasing hardware-resin bundles to United States group practices, compressing new entrant access to high-volume clinic networks. For New Entrants and Emerging Players: AI-powered nesting algorithms offer entry wedge through build-preparation software serving midsize German laboratories converting from subtractive workflows. Target Japan's 60,000 dental clinics with PMDA-harmonized quality systems and simplified chairside post-processing, bypassing saturated United States aligner production. Lead with subscription-based equipment financing paired with domestic resin supply partnerships. For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 13485 certification scarcity meets EU MDR notified body capacity constraints, favoring targets with existing CE marking pathways over de novo entrants. Long-term viability centers on vertical integration into photoinitiator chemistry or AI design software, not hardware manufacturing scale. Watch FDA 510(k) clearance velocity for ceramic-filled definitive resins as inflection signal for laboratory workflow conversion rates.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Accelerates definitive crown resin clearance velocity in United States laboratories. |
| CE Marking Pathway | Secures EU MDR access through German notified body relationships. |
| Hospital System Partnership | Deploys craniofacial surgical templates through Japanese university hospitals. |
| Software Companion Development | Integrates AI nesting algorithms with printer-native file formats. |
| Reimbursement Strategy | Aligns clear aligner production with United States dental insurance codes. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dental laboratory technicians, prosthodontic clinicians, resin formulation chemists, and biomedical engineers at notified bodies with secondary validation from FDA 510(k) databases, PMDA approval registries, ISO 13485 certification directories, and customs trade data for photoinitiator imports. Bottom-up printer installation counts triangulated against top-down resin consumption estimates.
Segment-weighting across device type, material formulation, technology modality, and end-user category shaped the analytical framework over the projection horizon. CAGRs derived from installed base growth curves, replacement cycle assumptions, and penetration rate modeling for chairside versus laboratory workflows. Forecast inputs incorporated photopolymer flexural strength advancement trajectories and regulatory clearance velocity by jurisdiction.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to photoinitiator supply disruption, EU MDR notified body capacity constraints, and FDA guidance evolution for AI-designed devices. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Global Dental Crowns and Bridges Market
Dental Devices
Global Restorative Dentistry Market
Dental Devices
Europe Dental Implants Market
Dental Devices
Intraoral Dental Scanner Market
Dental Devices
Europe Dental Lab Market
Dental Devices
Canada Dental Devices Market
Dental Devices
Titanium Dental Implants Market
Dental Devices
Electric Dental Handpieces Market
Dental Devices
Global Dental Hygiene Devices Market
Dental Devices
Mexico Dental Devices Market
Dental Devices
Plaque Disclosing Aids Market
Dental Devices
Dental 3D Printing Market
Dental Devices
Global Dental Obturators Market
Dental Devices
Asia-Pacific Dental Aligners Market
Dental Devices
Dental Chair Market
Dental Devices
North America Dental Aligners Market