
 Dental Veneers Market | 2026-2036
Dental Veneers Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Veneers Market Intelligence
Multi-source ceramic procurement is decoupling from traditional single-supplier dependence among large dental lab networks. Ivoclar Vivadent leverages proprietary lithium disilicate pressing technology to sustain premium positioning across European and North American channels. Dentsply Sirona anchors digital workflow integration, connecting intraoral scanning with chairside veneer milling. Kuraray Noritake Dental competes on zirconia layering expertise, supplying thin-profile substrates to aesthetic-focused practices in Japan and Southeast Asia.
Dental veneers are thin, custom-fabricated shells, typically 0.3–1.0 mm in thickness, that bond to the facial surface of anterior teeth to modify color, shape, or alignment; they are produced through CAD/CAM milling, heat-pressing, or hand-layered sintering and serve primarily elective aesthetic and minor restorative indications. Porcelain and ceramic categories command the dominant margin pool due to superior light-transmission properties and longevity exceeding composite alternatives. Ultra-thin laminates represent the fastest-growing thickness segment, driven by minimal-prep protocols that preserve natural tooth structure and reduce chairside time. Composite resin occupies a mature, price-sensitive tier, sustaining volume in emerging markets where cost barriers limit porcelain uptake.
FDA 510(k) clearance pathways and CE marking under the EU Medical Device Regulation shape material biocompatibility standards and adhesive system validation requirements, directly influencing product development timelines and market access costs for manufacturers. ISO 6872 standards for ceramic dental materials establish flexural strength and fracture toughness benchmarks that differentiate premium from economy-tier offerings. Stakeholders must monitor evolving regulatory convergence between FDA digital dentistry guidance and EUDAMED post-market surveillance obligations, as compliance complexity will increasingly determine which suppliers retain shelf space across dual-continent distribution networks.
Market Dynamics
Minimal-prep ceramic protocols are compressing chairside time and reshaping patient throughput economics across premium dental networks. This procedural shift is redistributing margin from traditional lab-fabricated workflows toward chairside CAD/CAM systems and same-day delivery models.
Growth Catalysts
- Smile-makeover tourism clusters:Seoul and Dubai cosmetic dentistry clinics attract international patients seeking bundled veneer packages, creating cross-border demand amplification.
- FDA 510(k) pathway streamlining:Digital dentistry guidance is accelerating biocompatibility validation for adhesive bonding systems, shortening time-to-market for novel ceramic formulations.
- Ultra-thin laminate technology:Sub-0.5mm pressed lithium disilicate enables no-prep protocols that preserve enamel structure and expand candidacy pools.
Market Restraints
- Zirconia powder supply concentration:Sintering-grade zirconia feedstock depends on concentrated Chinese and Japanese chemical processors, exposing labs to input volatility.
- EU MDR compliance costs:CE marking under the EU Medical Device Regulation demands expanded clinical documentation for ceramic materials, elevating market access barriers for mid-tier suppliers.
- Composite resin substitution:Direct composite layering retains cost advantage in price-sensitive segments, capping porcelain penetration in emerging economies.
Strategic Opportunities
- Chairside milling convergence:Intraoral scanner-to-milling unit integration enables single-visit veneer delivery, capturing premium positioning in United States urban markets.
- Japan aesthetic practice expansion:Thin-profile zirconia layering expertise from Japanese ceramic labs addresses unmet demand across Southeast Asian dental tourism corridors.
- ISO 6872 certification differentiation:Flexural strength benchmarking creates tiered positioning opportunities for labs demonstrating superior fracture toughness metrics.
Industry Challenges
- CAD/CAM technician training deficits:Digital design workflows require specialized ceramic nesting and milling optimization skills that outpace vocational program output.
- Adhesive system shelf-life management:Multi-bottle resin cement protocols demand precise inventory rotation to prevent bond-strength degradation in high-humidity climates.
- Legacy lab-dentist relationship friction:Chairside production models disrupt established referral networks and case-flow economics for independent dental technicians.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Veneers Market |
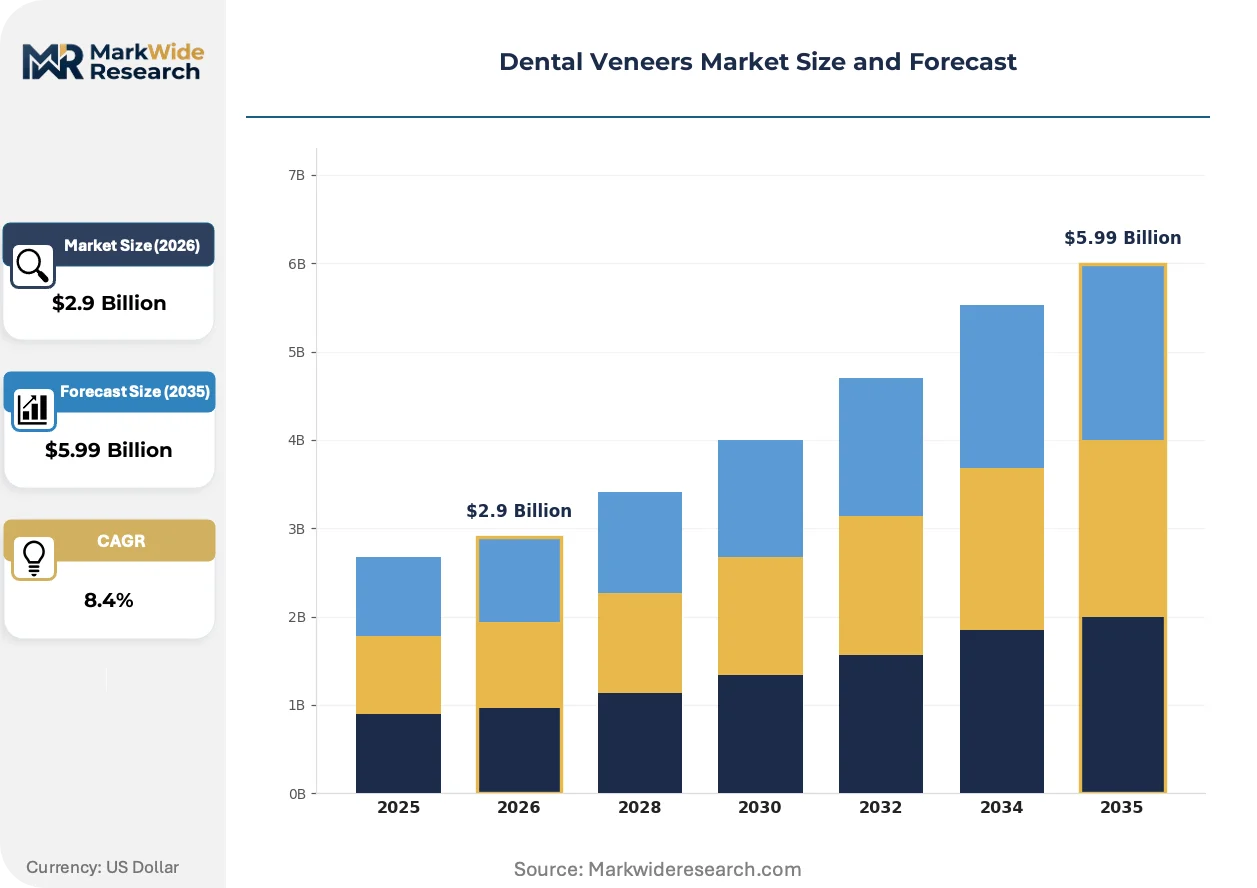
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $5.99 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
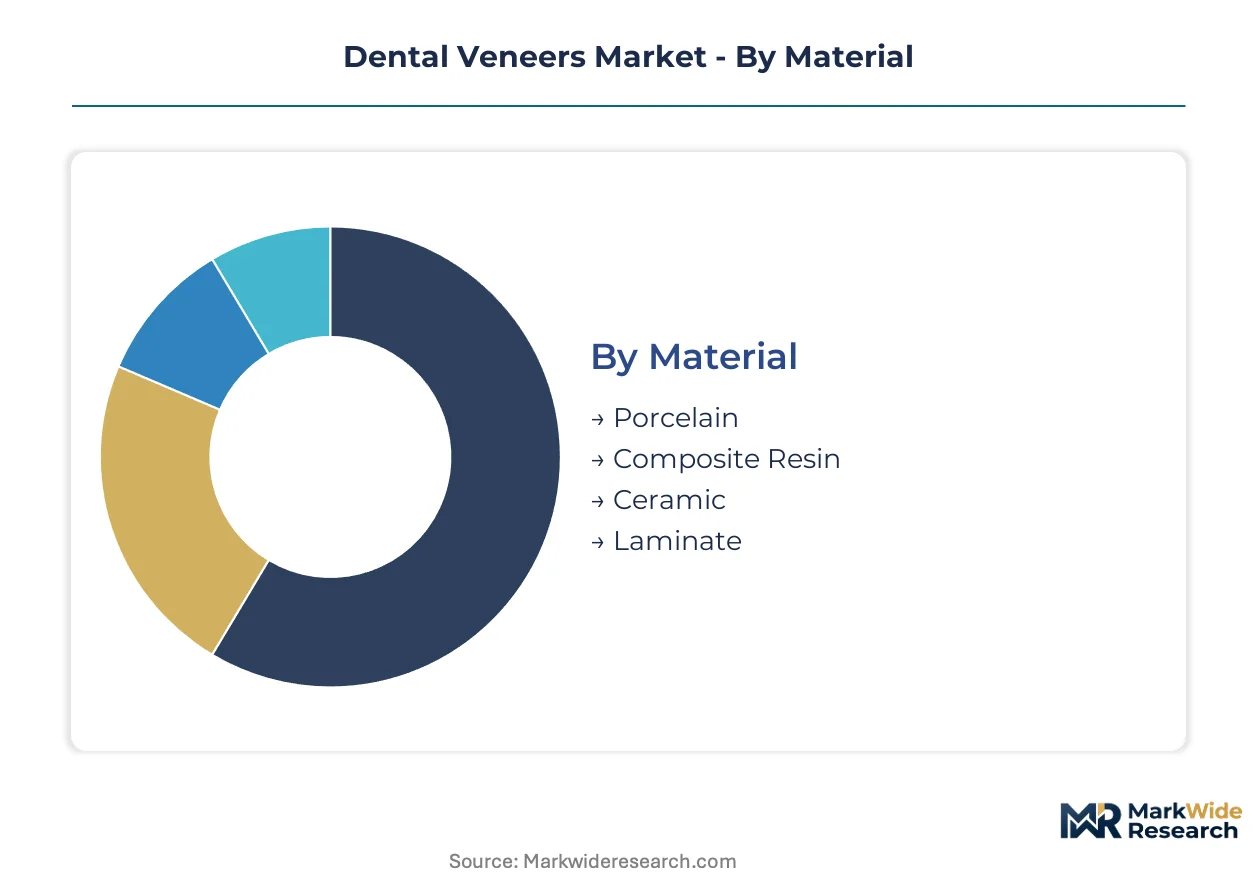
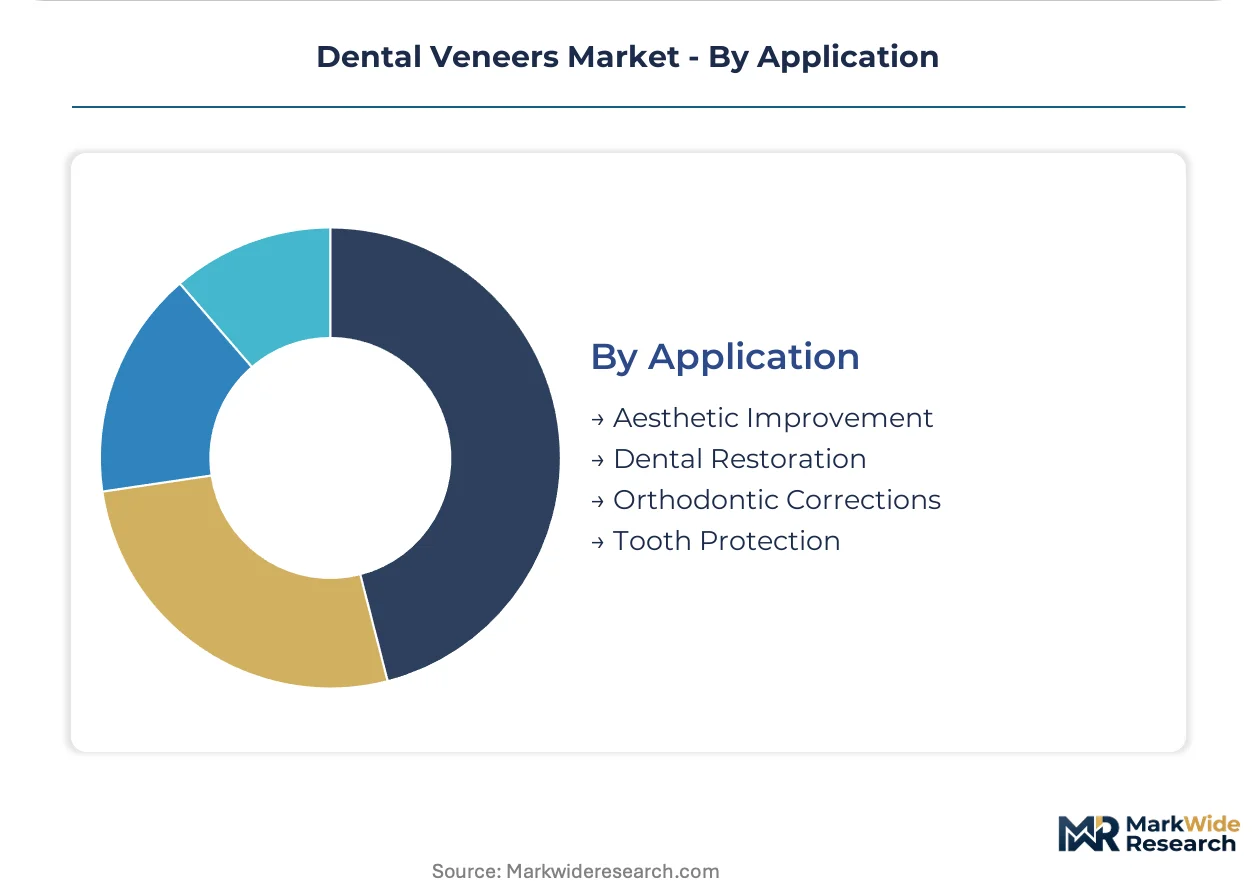
| Segmentation | Material: Porcelain, Composite Resin, Ceramic, Laminate End User: Clinics, Hospitals, Dental Labs, Orthodontists Thickness: Thin, Medium, Thick, Ultra-Thin Application: Aesthetic Improvement, Dental Restoration, Orthodontic Corrections, Tooth Protection |
| Companies Covered | Dentsply Sirona, Ivoclar Vivadent, 3M, Ultradent Products, Glidewell Laboratories, DenMat Holdings, VITA Zahnfabrik, Coltene Group, Kuraray Noritake Dental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Veneers Market Strategic Shifts & Innovations
Digital workflow penetration is compressing fabrication timelines from weeks to hours while elevating precision standards. This transformation is redistributing competitive advantage toward vertically integrated equipment-and-materials suppliers.
AI-powered smile design software is integrating facial analysis algorithms with automated veneer proportioning to reduce design iteration cycles. Aesthetic-focused practices in Germany and South Korea adopt these platforms fastest. The technology is integrating diagnostic photography with milling parameters, collapsing the traditional lab prescription bottleneck.
CE marking enforcement under the EU Medical Device Regulation is tightening post-market surveillance for ceramic dental materials. Manufacturers must now submit periodic safety update reports and maintain EUDAMED device registrations. European premium lab networks are consolidating supplier relationships to reduce compliance fragmentation across multi-country distribution.
Direct-to-consumer aligner platforms are conditioning patients to expect accelerated aesthetic outcomes, compressing veneer consultation-to-delivery expectations. Traditional multi-visit protocols now compete against same-day alternatives in United States metropolitan markets. This behavioral shift is forcing independent dentists toward equipment financing or lab partnership models they previously avoided.
Dental Veneers Market Segmentation
Dental veneer procurement patterns diverge sharply across material grades and clinical settings. Upgrade cycles for existing restorations and first-time aesthetic treatments create distinct demand profiles that suppliers must address through differentiated product architectures.
Material:
Replacement timelines for existing veneers—typically 10-15 years for early-generation composites—are accelerating upgrade decisions toward higher-performance ceramics. Patients with aging restitutions now demand superior light transmission and stain resistance unavailable in original treatments.
- Porcelain:Feldspathic and leucite-reinpressed ceramics deliver translucency matching natural dentin. Premium dental chains in Germany and the United States concentrate procurement here, driven by patient willingness to pay for 15-20 year functional lifespans.
- Ceramic:Lithium disilicate and zirconia formulations offer flexural strength exceeding 400 MPa. Seoul cosmetic clinics specify these for smile-makeover tourism packages where durability under travel schedules matters.
- Composite Resin:Direct-layered bis-GMA materials retain cost advantage in Indian and Brazilian municipal clinics where porcelain barriers limit uptake.
- Laminate:Pre-fabricated veneer blanks enable rapid chairside customization for emergency aesthetic repairs in Dubai same-day dentistry practices.
Volume placements concentrate in porcelain; the faster expansion belongs to ceramic.
End User:
Procurement authority sits differently across settings—dentists control chairside material selection while lab networks negotiate bulk ceramic supply contracts. Cost tier separation between independent practices and corporate chains determines supplier access strategies.
- Clinics:Private cosmetic dentistry practices in Seoul and Dubai generate premium-margin demand through bundled veneer tourism packages. These settings prioritize same-day delivery capabilities over unit cost.
- Dental Labs:Centralized fabrication facilities in Germany and Japan purchase sintering-grade zirconia in volume, pressing for ISO 6872 certification differentiation in their output specifications.
- Hospitals:Academic medical centers in the United States combine veneer placement with orthognathic surgery, requiring materials validated for adhesive bonding under compromised oral conditions.
- Orthodontists:Post-aligner finishing work drives demand for ultra-thin laminates that accommodate minor rotations without enamel reduction.
Revenue concentrates in clinics; dental labs are climbing the fastest as digital workflow adoption centralizes fabrication.
Thickness:
Patient candidacy and enamel preservation requirements segment demand across preparation protocols. Volume economics favor minimal-prep approaches that reduce chairside time and expand treatable populations.
- Ultra-Thin:Sub-0.5mm pressed lithium disilicate enables no-prep placement preserving 100% enamel structure. German aesthetic practices lead adoption, driven by patient demand for reversible treatments.
- Thin:0.3-0.5mm profiles balance minimal preparation with adequate material strength for anterior guidance function. United States urban markets concentrate here as chairside milling compresses delivery timelines.
- Medium:0.5-0.7mm specifications accommodate moderate color correction in Southeast Asian dental tourism corridors where cost sensitivity limits ultra-thin premium.
- Thick:0.7-1.0mm traditional preparations retain application in severe discoloration cases and emerging markets where technician hand-layering skills exceed CAD/CAM infrastructure.
Placement volume concentrates in thin profiles; ultra-thin specifications are gaining share fastest as digital design precision improves.
Application:
Functional restoration needs versus elective aesthetic desires create divergent material specifications and pricing tolerance. Insurance reimbursement availability separates these demand pools sharply.
- Aesthetic Improvement:Elective color and shape modification drives premium porcelain selection. Dubai and Seoul cosmetic clinics specialize here, bundling veneers with hospitality packages for international patients.
- Dental Restoration:Post-trauma or caries reconstruction requires durable ceramic substrates. United States prosthodontic practices specify lithium disilicate for anterior crowns with veneer facings.
- Orthodontic Corrections:Minor malposition masking after aligner therapy employs ultra-thin laminates. German orthodontists integrate this into retention protocols.
- Tooth Protection:Erosion and abrasion coverage in bruxism patients uses thicker zirconia formulations. Japanese geriatric dentistry practices concentrate demand here.
Case volume concentrates in aesthetic improvement; orthodontic correction applications show the steepest expansion trajectory as aligner penetration creates finishing demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zirconia powder processors in Japan and lithium disilicate foundries in Germany anchor raw-material supply for veneer fabrication. These feedstock localities concentrate high-grade ceramic production and shape regional competitive positioning.
United States
Cosmetic dentistry chains in Los Angeles and Miami drive ultra-thin laminate demand through same-day delivery protocols. FDA 510(k) clearance pathways for adhesive bonding systems accelerate biocompatibility validation timelines. Premium dental networks in Manhattan and Chicago compress chairside time via chairside CAD/CAM integration.
Germany
Aesthetic practices in Munich and Düsseldorf specify feldspathic porcelain for 15-20 year functional lifespans. CE marking under EU Medical Device Regulation demands expanded clinical documentation for ceramic materials. Centralized fabrication facilities in North Rhine-Westphalia purchase sintering-grade zirconia in volume for ISO 6872-certified output.
South Korea
Seoul cosmetic clinics attract international patients through bundled veneer tourism packages. MFDS regulates biocompatibility standards for pressed lithium disilicate formulations. Gangnam district practices prioritize same-day capabilities over unit cost in procurement decisions.
Japan
Geriatric dentistry practices in Tokyo and Osaka specify thicker zirconia formulations for bruxism patients. METI oversees JIS standards for ceramic dental materials establishing flexural strength benchmarks. Nagoya ceramic labs supply thin-profile substrates to Southeast Asian dental tourism corridors.
United Arab Emirates
Dubai same-day dentistry practices employ pre-fabricated veneer blanks for emergency aesthetic repairs. MOHAP regulates dental device imports and clinical facility licensing. Jumeirah district cosmetic clinics bundle hospitality packages with elective veneer procedures for Gulf and European patients.
Dental Veneers Market Key Industry Players
Portfolio diversification dominates the current landscape as suppliers expand from single-material dependence into integrated digital workflow offerings. The vendor base clusters around three tiers: multinational equipment-and-materials conglomerates, specialized ceramic foundries, and regional dental lab networks. Two strategic archetypes predominate: vertically integrated digital dentistry platforms and premium ceramic specialists. Competitive intensity concentrates on M&A activity targeting CAD/CAM software capabilities and strategic partnerships bridging scanner manufacturers with milling unit providers.
Among European-based ceramic specialists, Ivoclar Vivadent and VITA Zahnfabrik exemplify the premium-materials archetype through proprietary pressing technologies. Dentsply Sirona anchors the integrated-platform tier, connecting intraoral scanning with chairside production systems. These three companies represent contrasting pathways—specialized ceramic expertise versus end-to-end digital workflow control—in the competitive positioning matrix.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Ivoclar Vivadent |
| 3M |
| Ultradent Products |
| Glidewell Laboratories |
| DenMat Holdings |
| VITA Zahnfabrik |
| Coltene Group |
| Kuraray Noritake Dental |
| Others |
Cost & Logistics Intelligence
Premium dental chains in the United States and Germany command purchasing power that compresses supplier margins while sustaining three-tier pricing structures across premium, standard, and economy levels. This buyer concentration forces ceramic foundries to unbundle warranty coverage and technical support, shifting cost exposure downstream to independent labs and clinics.
Pricing Analysis
Warranty and post-placement service bundling separates premium-tier lithium disilicate suppliers from economy-grade competitors who sell bare ceramic blanks. Pricing stratifies across premium, standard, and economy tiers based on ISO 6872 certification level and chairside technical support inclusion. Cost compression in the composite resin segment intensifies as direct-layered alternatives capture price-sensitive demand in Indian and Brazilian municipal clinics. Hospital-based prosthodontic practices exhibit lowest price sensitivity due to bundled surgical-aesthetic reimbursement protocols.
Supply Chain Analysis
Dual-sourcing mandates from large dental lab networks in Germany and Japan now require qualified suppliers in at least two of China, Japan, and Germany for sintering-grade zirconia feedstock. Raw material procurement draws from Japanese chemical processors for yttria-stabilized zirconia, German lithium disilicate foundries, and Chinese alumina suppliers. Single-source vulnerability concentrates in sub-0.5mm pressed ceramic substrates where Ivoclar Vivadent's proprietary technology dominates. Distribution runs through regional dental supply distributors who consolidate small-lab orders and manage CE marking documentation for EU market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR compliance cost escalation and FDA 510(k) pathway complexity are forcing mid-tier ceramic suppliers toward exit or acquisition, consolidating viable vendor relationships around vertically integrated equipment-and-materials platforms.
For Market Incumbents: Lock in chairside CAD/CAM technician training partnerships to defend against same-day dentistry disruption from independent milling unit providers. Deepen backward integration into lithium disilicate pressing technology to capture margin lost to third-party ceramic foundries. Prioritize ISO 6872 certification maintenance as CE marking documentation requirements expand under EUDAMED surveillance obligations.
For New Entrants and Emerging Players: Begin with ultra-thin laminate specialization targeting Southeast Asian dental tourism corridors where Japanese ceramic lab supply relationships remain underdeveloped. White-space opportunity concentrates in pre-fabricated veneer blanks for emergency aesthetic repair services in Dubai and Seoul same-day practices. Go-to-market positioning should emphasize rapid chairside customization protocols over laboratory fabrication partnerships.
For Investors and Strategic Acquirers: The window for entry favors digital workflow software specialists with intraoral scanner-to-milling integration capabilities. Long-term viability hinges on capturing dentist practice management system relationships before incumbent equipment manufacturers consolidate these channels. Watch FDA digital dentistry guidance convergence with EU MDR post-market surveillance as the inflection signal for regulatory-compliant acquisition premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Chairside CAD/CAM Integration | Compresses veneer delivery from weeks to hours, capturing premium positioning in United States urban markets. |
| ISO 6872 Certification Investment | Differentiates ceramic output specifications for German centralized fabrication facilities purchasing sintering-grade zirconia. |
| Dual-Sourcing Supply Agreement | Mitigates zirconia powder concentration risk across Chinese and Japanese chemical processors for large dental lab networks. |
| AI-Powered Smile Design Platform | Integrates facial analysis algorithms with automated veneer proportioning in German and South Korean aesthetic practices. |
| Southeast Asian Distribution Partnership | Addresses unmet thin-profile zirconia layering demand across dental tourism corridors from Nagoya ceramic labs. |
Research Approach
Multi-period observation of veneer replacement cycle timing, CAD/CAM adoption rates, and regulatory filing volumes anchored the trend analysis, supplemented by interviews with dental lab network procurement directors, ceramic materials R&D leads, aesthetic practice clinicians, and dental supply distributor category managers. Secondary validation drew from FDA 510(k) clearance databases, EUDAMED device registrations, ISO 6872 certification records, and EU MDR technical documentation filings. Bottom-up demand modeling from clinic procedure volumes and top-down ceramic materials consumption estimates were triangulated against manufacturer production disclosures.
Segment-weighting across material type, thickness specification, end-user setting, and geographic regulatory cluster shaped the analytical framework throughout the projection horizon. CAGRs were derived from fitted growth curves against historical placement data and forward-looking adoption assumptions for digital workflow penetration. Industry-specific forecast inputs included smile-makeover tourism patient flow estimates and chairside milling unit installation rates across premium dental networks.
Underlying measurement precision varies by segment; ultra-thin laminate and ceramic material categories carry tighter precision than composite resin and thick-profile legacy specifications due to more consolidated supplier reporting. Forecasts reflect documented assumptions regarding regulatory convergence timelines and dental tourism recovery trajectories. Deviation in FDA digital dentistry guidance implementation pace or EU MDR enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Periodontal Scalers and Curettes Market
Dental Devices
China Dental Devices Market
Dental Devices
Dental Implants and Abutment Systems Market
Dental Devices
Global Dental Hygiene Devices Market
Dental Devices
Global Veterinary Dentistry Instruments and Equipment Market
Dental Devices
Dental Impression Tray Market
Dental Devices
Dental Impression System Market
Dental Devices
Dental Laboratory Handpiece Market
Dental Devices
Dental Restoration Market
Dental Devices
Australia Dental Devices Market
Dental Devices
Dental Fittings Market
Dental Devices
Gingivitis Treatment Market
Dental Devices
Global Dental Crowns and Bridges Market
Dental Devices
Dental Carpule Market
Dental Devices
Europe Dental Implants Market
Dental Devices
Global Periodontal Market