
 Dental Handpieces Market | 2026-2036
Dental Handpieces Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Handpieces Market Intelligence
Modular handpiece system bundling is shifting procurement patterns across dental practices, with buyers favoring configurable platforms that pair handpiece motors with interchangeable contra-angle and straight attachments. Dentsply Sirona leverages its integrated CAD/CAM ecosystem to anchor recurring consumable revenue alongside hardware placements. NSK Ltd. competes through specialized high-torque electric handpiece engineering that targets implantology and oral surgery workflows. KaVo Dental dominates premium European dental school channels with extended warranty structures and dedicated technical training programs.
Dental handpieces are precision rotary instruments engineered to operate at speeds from 5,000 to 400,000 RPM, utilizing ceramic bearings and tungsten carbide burs for cutting, finishing, and polishing tooth structure and restorative materials. Electric handpiece technology leads the technology dimension with superior torque consistency and programmable speed profiles that reduce operator fatigue during extended procedures. Air-driven handpieces retain substantial share in high-speed cavity preparation where lightweight ergonomics and lower capital outlay sustain volume demand. Cosmetic dentistry applications within the application dimension concentrate margin pools, as practices command premium fees for veneer preparations and aesthetic contouring that require precision instrumentation.
FDA 510(k) premarket notification requirements govern powered dental handpiece clearance in the United States, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence and post-market surveillance obligations on manufacturers distributing in European markets. ISO 14457 specifies dimensional and performance standards for dental handpieces that facilitate cross-border regulatory alignment and reduce retesting burdens. Stakeholders must monitor evolving MDR notified body capacity constraints and FDA digital health pre-certification pilots that could reshape submission pathways for smart handpiece systems with embedded usage sensors.
Market Dynamics
Electric handpiece technology is compressing replacement cycles across dental practices as torque precision requirements intensify for implantology workflows. The shift from air-driven to electric systems reconfigures capital allocation patterns and technical training priorities.
Growth Catalysts
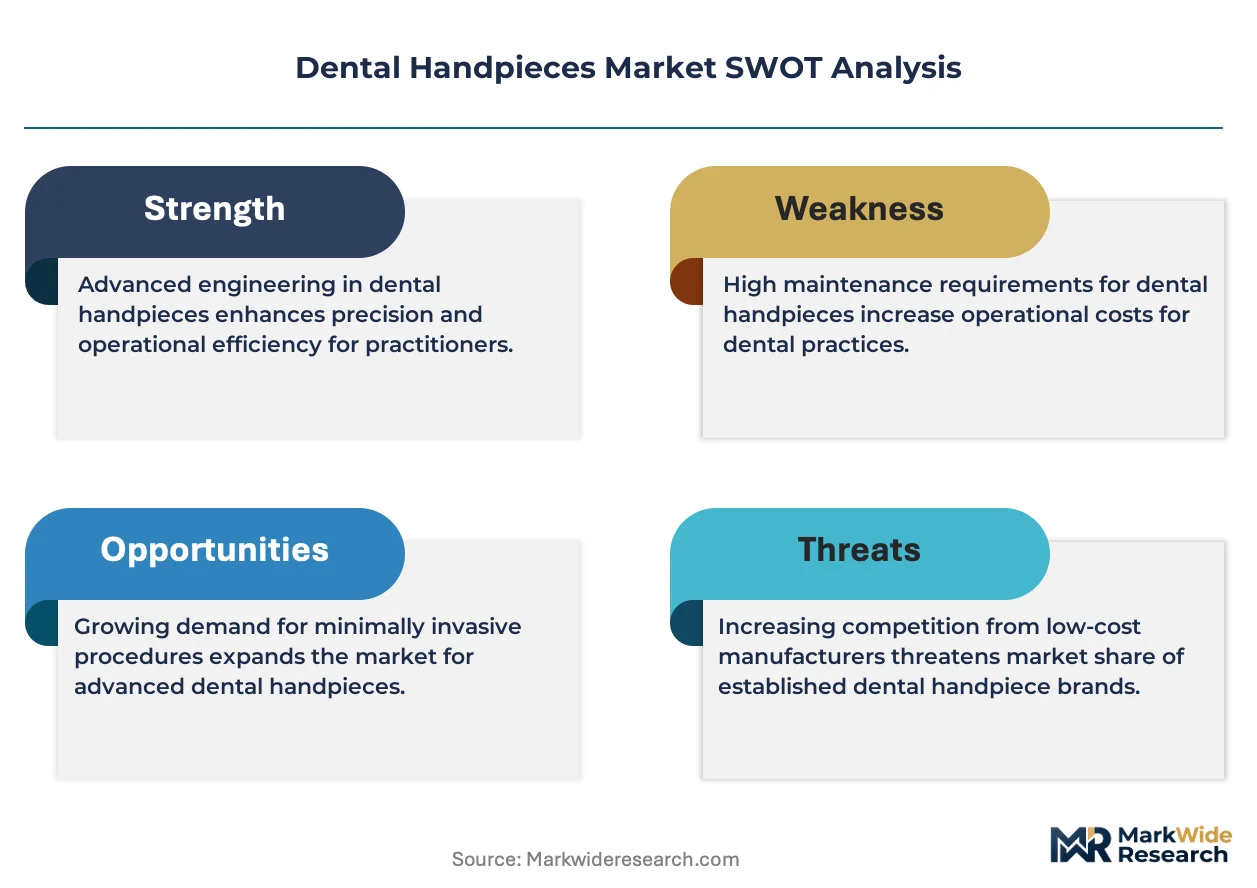
- FDA 510(k) pathway streamlining:Accelerated premarket notification processing for powered surgical instruments reduces manufacturer time-to-market for next-generation handpiece systems.
- Dental service organization consolidation:Multi-site practice networks in the United States standardize equipment fleets, generating volume procurement contracts that favor integrated system suppliers.
- Ceramic bearing advancement:Extended operational lifespan and reduced maintenance intervals lower total cost of ownership for high-rotation clinical environments.
Market Restraints
- Tungsten carbide bur supply concentration:Specialized cutting tool manufacturing clusters in Central Europe create single-source dependency risks for precision bur procurement.
- EU MDR clinical evidence requirements:Stricter post-market surveillance obligations extend certification timelines and elevate documentation costs for European market entry.
- Air-driven handpiece residual demand:Lightweight ergonomics and lower capital thresholds sustain volume preference in cost-sensitive practice segments, delaying full electric conversion.
Strategic Opportunities
- Smart handpiece sensor integration:Embedded usage monitoring and predictive maintenance algorithms create recurring software revenue streams alongside hardware placements.
- Indian dental infrastructure expansion:Government clinic modernization programs and private chain growth generate first-time electric handpiece demand in previously underserved markets.
- ISO 14457 harmonization leverage:Standardized dimensional and performance specifications reduce retesting burdens for manufacturers pursuing multi-jurisdiction product registration.
Industry Challenges
- Electric handpiece technician scarcity:Specialized motor repair and electronic diagnostics capabilities lag behind equipment deployment rates, extending service downtime.
- Legacy air-system infrastructure retrofit costs:Practice-level compressed air and coupling compatibility modifications complicate electric system transitions.
- MDR notified body capacity constraints:European certification backlog delays product launches and compresses competitive windows for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Handpieces Market |
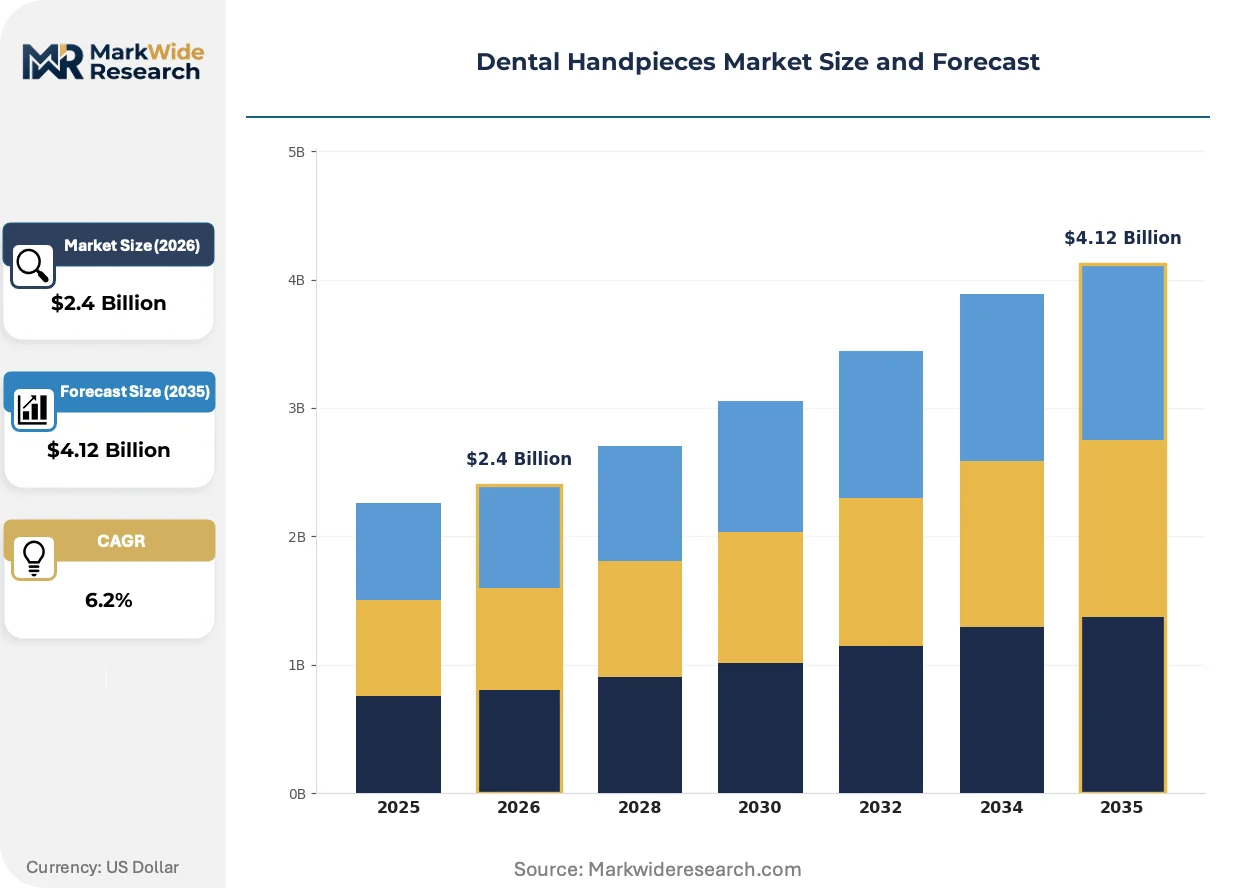
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.12 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Speed Handpieces, Low-Speed Handpieces, Laser Handpieces, Surgical Handpieces Technology: Electric Handpieces, Air-Driven Handpieces, Battery-Powered Handpieces, Fiber-Optic Handpieces End User: Dentists, Dental Clinics, Dental Schools, Research Laboratories Application: Cosmetic Dentistry, Restorative Dentistry, Surgery, Orthodontics |
| Companies Covered | KaVo Dental, Dentsply Sirona, Bien-Air Dental SA, W&H Dentalwerk, NSK Ltd., Nakanishi Inc., A-dec Inc., J. Morita Corporation, SciCan Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Handpieces Market Strategic Shifts & Innovations
CAD/CAM workflow integration is redefining handpiece functionality requirements as digital dentistry protocols standardize across developed markets. Precision demands from chairside milling and same-day restoration fabrication reshape instrument specification priorities.
Brushless DC motor technology is converging with programmable speed control interfaces to enable procedure-specific torque profiles that reduce operator fatigue during extended oral surgery sessions. Academic dental centers in Germany and Switzerland pilot adaptive feedback systems that adjust rotation parameters in real-time based on tissue resistance. This convergence is compressing the performance gap between premium and mid-tier electric handpiece categories.
The EU Medical Device Regulation imposes enhanced clinical evidence and post-market surveillance obligations that elevate documentation standards for powered dental instrument clearance. Manufacturers must maintain systematic vigilance data and periodic safety update reports across product lifecycles. Implantology-focused handpiece configurations face the steepest compliance burden given their higher-risk classification under MDR Annex VIII rules.
Equipment-as-a-service contracting is displacing outright purchase models among large United States dental service organizations seeking to align capital expenditure with patient volume fluctuations. Subscription structures bundle handpiece hardware, preventive maintenance, and consumable replenishment into per-procedure cost metrics. This shift concentrates procurement authority at corporate headquarters rather than individual practice managers.
Dental Handpieces Market Segmentation
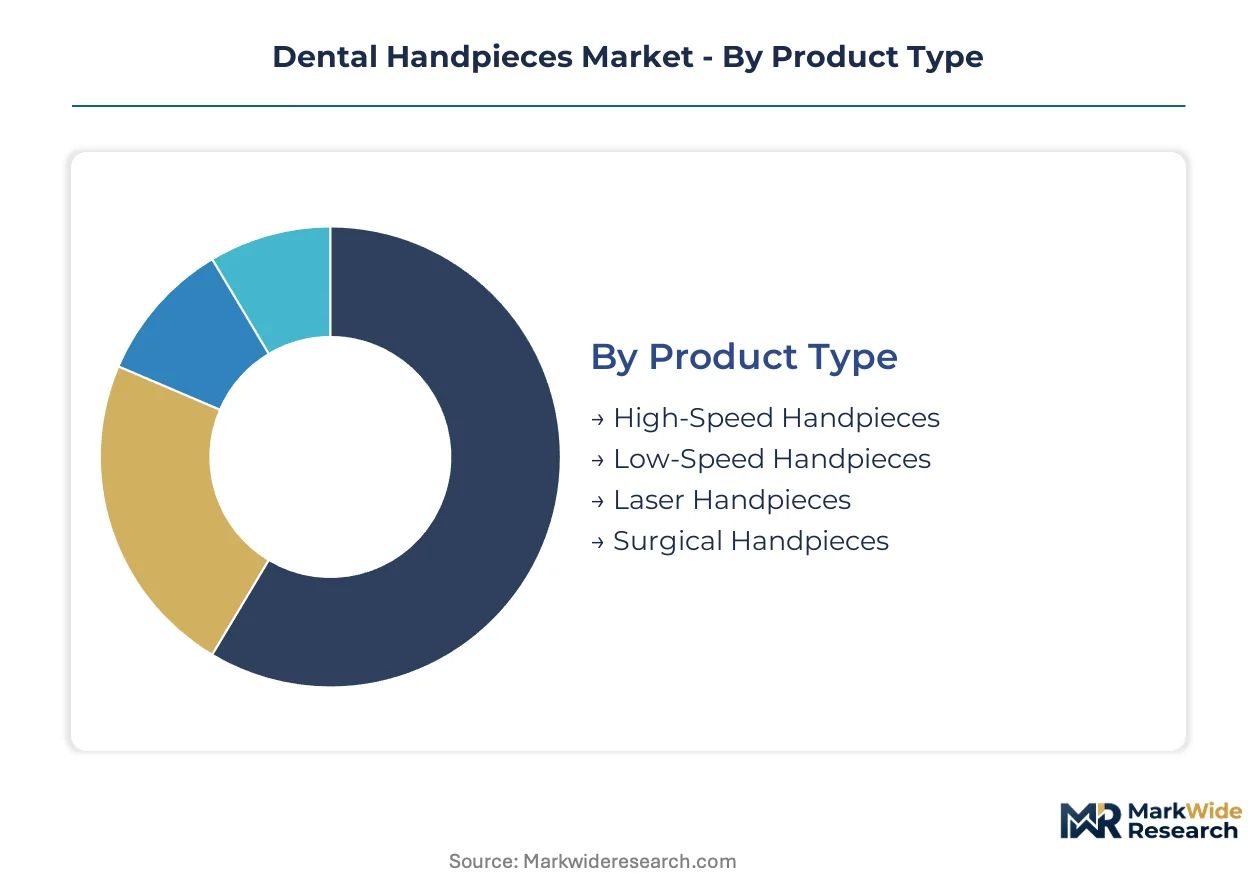
Dental handpiece segmentation reveals distinct regulatory pathways and procurement economics across product architectures. Technology choices dictate certification complexity, while end-user scale determines service contracting structures and capital deployment cycles.
Product Type:
FDA 510(k) clearance requirements vary sharply by rotational speed and intended tissue contact, with surgical classifications triggering stricter clinical evidence thresholds than standard cavity preparation tools.
- High-Speed Handpieces:Air-turbine and electric variants operate between 180,000 and 400,000 RPM for rapid enamel and dentin removal. United States dental service organizations concentrate procurement here, driven by same-day restoration throughput targets and chairtime optimization mandates.
- Low-Speed Handpieces:Contra-angle and straight attachments deliver 5,000 to 40,000 RPM for finishing, polishing, and laboratory work. German and Swiss dental schools favor these for extended procedural training where torque control precision outweighs raw speed.
- Laser Handpieces:Erbium and diode wavelengths for soft tissue ablation fall under FDA device classifications requiring biocompatibility documentation.
- Surgical Handpieces:Implantology-focused configurations face EU MDR Class IIa obligations with heightened post-market surveillance duties.
Leading the category by volume: High-Speed Handpieces. Growing fastest: Surgical Handpieces.
Technology:
Cost tier stratification separates capital-intensive electric platforms from disposable-friendly battery units, with fiber-optic premiums commanding three-to-five-year amortization horizons.
- Electric Handpieces:Brushless DC motors deliver constant torque across 5,000 to 200,000 RPM ranges with programmable speed profiles. United States multi-site dental networks standardize on these for implantology workflows where torque consistency reduces osseointegration failure rates.
- Air-Driven Handpieces:Lightweight turbine designs using ceramic bearings sustain dominance in high-speed cavity preparation. India's government clinic modernization programs absorb volume here due to lower capital thresholds and existing compressed air infrastructure.
- Battery-Powered Handpieces:Cordless lithium-ion systems target mobile dentistry and field outreach programs with limited utility access.
- Fiber-Optic Handpieces:Integrated LED illumination commands premium positioning in aesthetic dentistry suites where shadow-free visibility justifies per-procedure fees.
Margin concentration sits with Electric Handpieces. Volume expansion is steepest for Battery-Powered Handpieces.
End User:
Customer type determines service bundling intensity, with institutional buyers demanding training inclusion and warranty extensions unavailable to independent practitioners.
- Dentists:Solo and small-group practitioners prioritize ergonomic weight distribution and noise reduction for eight-hour clinical days. United States independent operators delay electric conversion due to technician scarcity and compressed air retrofit costs.
- Dental Clinics:Corporate-owned multi-chair facilities in Brazil and Mexico negotiate fleet-standardization contracts with predictive maintenance clauses and per-procedure consumable replenishment.
- Dental Schools:European institutions specify extended warranty structures and dedicated technical training programs for curriculum integration.
- Research Laboratories:Academic and commercial R&D facilities drive demand for prototype-compatible mounting systems and open-architecture control interfaces.
Procurement volume concentrates at Dental Clinics. Fastest expansion trajectory belongs to Dental Schools.
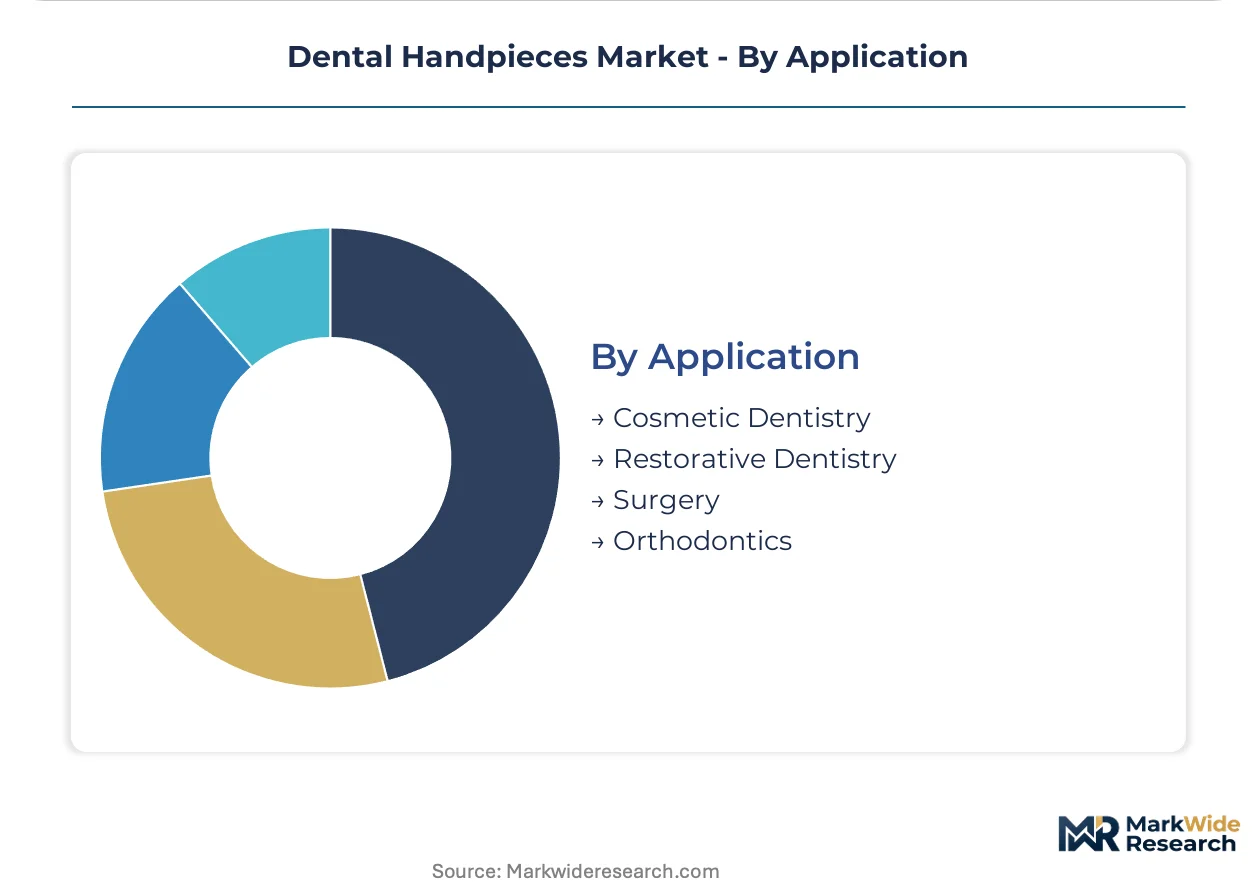
Application:
Margin pools diverge sharply between commodity restorative work and aesthetic procedures commanding fee premiums, with orthodontic applications requiring specialized torque limitations.
- Cosmetic Dentistry:Veneer preparations and aesthetic contouring demand sub-0.1mm precision tolerances and vibration-dampened handpiece engineering. United States metropolitan practices in Los Angeles and Miami absorb premium electric systems here, justified by per-tooth fees exceeding restorative baselines by threefold.
- Restorative Dentistry:Amalgam and composite cavity preparation sustains highest absolute procedure volumes globally. India's private dental chains deploy air-driven handpieces for this segment, balancing throughput requirements against capital constraints.
- Surgery:Implant placement and bone augmentation procedures require sterilizable surgical motors with irrigation integration.
- Orthodontics:Debonding and interproximal reduction applications specify lower torque ceilings to protect enamel integrity during bracket removal.
Revenue per procedure peaks in Cosmetic Dentistry. Procedure volume dominance rests with Restorative Dentistry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of precision dental handpieces clusters in Germany, Switzerland, and Japan, while consumption tilts toward the United States, China, and India where clinic modernization and dental school expansion drive procurement volumes.
United States
Dental service organization consolidation across Texas, Florida, and California generates fleet-standardization contracts for electric handpiece systems. FDA 510(k) pathway streamlining accelerates product registration timelines for powered surgical instruments. The Dallas-Fort Worth metroplex anchors multi-site practice networks negotiating predictive maintenance clauses and per-procedure consumable bundling.
Germany
Academic dental centers in Berlin, Munich, and Hamburg specify extended warranty structures and dedicated technical training programs for curriculum integration. EU Medical Device Regulation imposes stricter clinical evidence and post-market surveillance obligations on manufacturers distributing in European markets. The Baden-Württemberg precision engineering corridor concentrates ceramic bearing and tungsten carbide bur production for global supply chains.
China
Government clinic modernization programs in Shanghai, Beijing, and Guangzhou absorb volume for air-driven handpieces due to lower capital thresholds and existing compressed air infrastructure. National Medical Products Administration device classifications govern powered dental instrument clearance with biocompatibility documentation requirements. The Yangtze River Delta manufacturing cluster produces mid-tier electric handpiece motors for domestic and Southeast Asian export markets.
India
Private dental chain growth in Maharashtra, Karnataka, and Telangana generates first-time electric handpiece demand in previously underserved markets. Central Drugs Standard Control Organization regulates powered surgical instruments with quality certification pathways for imported equipment. Mumbai and Bangalore host distribution hubs serving government clinic modernization programs and metropolitan cosmetic dentistry practices.
Switzerland
Research laboratories in Zurich and Geneva drive demand for prototype-compatible mounting systems and open-architecture control interfaces. Swissmedic imposes medical device surveillance obligations that elevate documentation standards for powered dental instrument clearance. The Basel pharmaceutical-industrial corridor extends into precision instrument engineering for implantology-focused handpiece configurations.
Dental Handpieces Market Key Industry Players
The competitive structure tilts toward integrated system suppliers with recurring consumable revenue models. Tiered concentration separates premium European engineering houses from mid-tier Asian fabricators and specialized Japanese precision motor specialists. Dominant competitive moves include equipment-as-a-service contracting displacing outright purchase models and CAD/CAM ecosystem integration anchoring hardware placements. Strategic partnerships between handpiece manufacturers and dental school networks secure curriculum specification and extended warranty structures.
Among Swiss and German precision engineering houses, Bien-Air Dental SA and W&H Dentalwerk exemplify the premium-tier archetype with ceramic bearing specialization and extended operational lifespan engineering. NSK Ltd. occupies a position within the Japanese high-torque electric motor specialist tier targeting implantology and oral surgery workflows. These three companies represent distinct geographic and technical positioning vectors that shape procurement patterns across academic, corporate, and independent practice channels.
| Leading Market Players |
|---|
| KaVo Dental |
| Dentsply Sirona |
| Bien-Air Dental SA |
| W&H Dentalwerk |
| NSK Ltd. |
| Nakanishi Inc. |
| A-dec Inc. |
| J. Morita Corporation |
| SciCan Ltd. |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap precision engineering houses in Germany and Switzerland anchor supply-side discipline through multi-generational capital allocation patterns that resist quarterly margin pressure. Their patient reinvestment timelines stabilize premium-tier pricing even as Asian fabricators compress mid-market quotations.
Pricing Analysis
Margin tightening in mid-tier electric handpieces reflects ceramic bearing oversupply from Yangtze River Delta manufacturers. Pricing stratifies across premium Swiss-German engineering, ISO 14457-certified standard tiers, and economy air-driven systems for Indian government clinics. Cost-down pressure accelerates because dental service organizations negotiate per-procedure subscription bundles that collapse upfront hardware premiums. Independent solo practitioners exhibit highest price sensitivity; United States multi-site networks absorb premium electric systems with embedded maintenance clauses.
Supply Chain Analysis
Direct-to-dental school channels handle European academic demand while distributor networks serve fragmented independent practices. Manufacturing concentrates in Germany, Switzerland, and Japan for precision motors; China produces mid-tier electric assemblies. Tungsten carbide bur fabrication draws from Central European tooling clusters. Single-source vulnerability concentrates in ceramic bearing supply from Baden-Württemberg specialists. Distribution runs through authorized service partners for warranty-honored technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric handpiece technology is displacing air-driven legacy systems across implantology workflows, compressing replacement cycles and reconfiguring procurement authority toward corporate dental service organization headquarters.
For Market Incumbents: Deploy predictive maintenance software integration to lock in recurring revenue streams alongside hardware placements. Defend against mid-tier Asian entrants by accelerating FDA 510(k) clearance timelines for next-generation brushless DC motor platforms. Deepen backward integration into ceramic bearing production to secure supply continuity against Central European concentration risk. For New Entrants and Emerging Players: Indian government clinic modernization programs represent the most penetrable white-space target, given first-time electric handpiece demand and existing compressed air infrastructure retrofit constraints. Brazilian and Mexican corporate dental chains seek fleet-standardization contracts with consumable bundling. Pursue equipment-as-a-service contracting to bypass capital-threshold barriers in cost-sensitive segments. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier electric handpiece specialists with ISO 14457 certification and dormant European distribution relationships. Long-term viability hinges on software companion development capabilities for usage analytics and predictive maintenance. Monitor FDA digital health pre-certification pilot expansion as inflection signal for smart handpiece system valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Sensor Integration | Embedded usage monitoring creates recurring software revenue alongside hardware placements for United States dental service organizations. |
| EU MDR Certification Investment | Stricter clinical evidence requirements elevate documentation barriers that concentrate market share among capitalized incumbents. |
| Indian Distribution Partnership | Central Drugs Standard Control Organization pathways and government clinic programs unlock first-time electric handpiece penetration. |
| CAD/CAM Ecosystem Anchoring | Integrated digital dentistry workflows lock in recurring consumable revenue through chairside milling compatibility requirements. |
| Extended Warranty Structuring | Dental schools in Germany and Switzerland specify training-inclusive service contracts that exclude independent practitioners. |
Research Approach
Independent corroboration across dental equipment procurement managers, biomedical engineering directors, GPO contracts specialists, and aftermarket service heads underwrites the qualitative findings. Primary fieldwork combined with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and customs trade records. Bottom-up installation base modeling and top-down market sizing triangulate volume estimates.
Comparable-period anchoring to historical electric handpiece adoption curves in United States multi-site networks structured the projection framework. Segmentation dimensions span technology tier, end-user scale, application precision requirements, and regional regulatory cluster across the modeling period. CAGRs derive from equipment replacement cycle compression and dental service organization consolidation trajectories. Implantology procedure volume growth and ceramic bearing lifespan extension curves inform demand elasticity assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR notified body capacity constraints and FDA digital health pathway evolution. Periodic stress-testing of base assumptions is recommended given electric handpiece technician scarcity and air-system infrastructure retrofit cost volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Latin America Dental Devices Market
Dental Devices
Dental Impression Tray Market
Dental Devices
Global Dental Lasers Market
Dental Devices
Dental Implants and Dental Prosthetics Market
Dental Devices
Dental Implant Motors Market
Dental Devices
Dental Apex Locator Market
Dental Devices
Electric Dental Handpieces Market
Dental Devices
Americas Acrylic Teeth Market
Dental Devices
Dental Healing Caps Market
Dental Devices
Canada Dental Devices Market
Dental Devices
Global Dental Hygiene Devices Market
Dental Devices
Gingivitis Treatment Market
Dental Devices
Global Dental Labs Market
Dental Devices
Dental Amalgamators Market
Dental Devices
Europe CBCT Dental Imaging Market
Dental Devices
Global Dental Endodontics Market