
 Global Indirect Calorimeter Market | 2026-2036
Global Indirect Calorimeter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Indirect Calorimeter Market Foresight
The premium segment of indirect calorimeters is consolidating around FDA-cleared metabolic carts with integrated gas analysis, while commodity-grade portable devices face margin compression from Asian manufacturers. COSMED Srl leverages its Italian manufacturing base to dominate European hospital procurement. Parvo Medics sustains technology leadership in breath-by-breath analysis for sports science applications. KORR Medical Technologies anchors the North American wellness center channel with simplified operator interfaces.
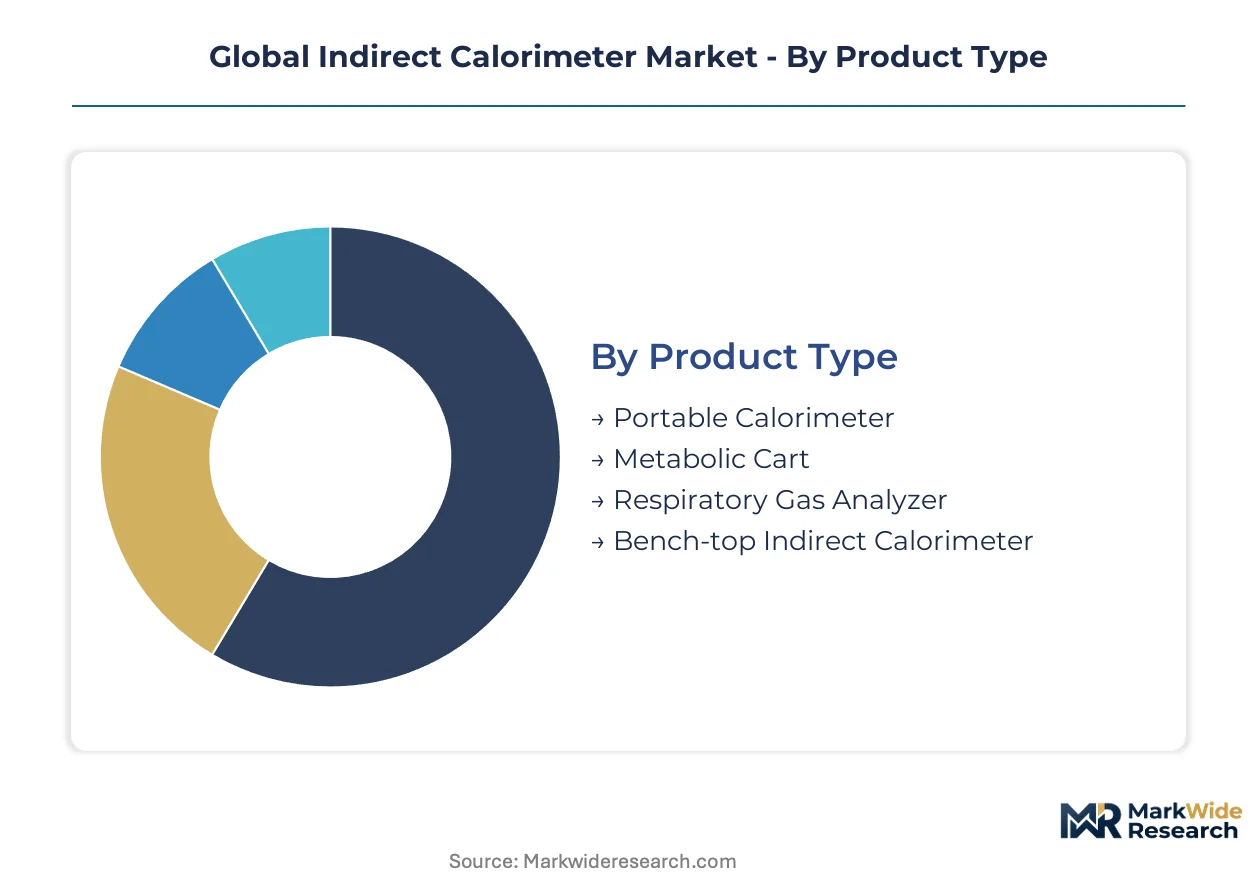
An indirect calorimeter measures oxygen consumption and carbon dioxide production to calculate energy expenditure through respiratory gas exchange, typically achieving accuracy within one percent using paramagnetic oxygen sensors or zirconium oxide fuel cells. Metabolic carts retain the largest revenue share due to their institutional adoption in intensive care and bariatric surgery protocols, while portable calorimeters represent the fastest-growing product type as point-of-care metabolic testing expands beyond hospital walls. Open-circuit calorimetry leads technology adoption in research institutes, whereas closed-circuit systems occupy niche applications requiring controlled environmental conditions.
The FDA's 510(k) framework governs device clearance in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for software-integrated gas analyzers sold in Europe. Japan's PMDA maintains distinct approval pathways that delay market entry for foreign manufacturers of respiratory diagnostic equipment. Stakeholders must monitor evolving reimbursement codes for indirect calorimetry in critical care, as coverage decisions will determine whether hospital capital budgets prioritize metabolic monitoring upgrades against competing diagnostic investments.
Market Dynamics
Hospital procurement committees now weight metabolic monitoring accuracy against total cost of ownership, compressing margins for manufacturers lacking integrated software ecosystems or service bundling capabilities.
Growth Catalysts
- Critical care protocol expansion:ICU departments in university hospitals now mandate indirect calorimetry for ventilated patient nutritional support, embedding the technology into standard-of-care pathways.
- FDA 510(k) pathway clarity:The respiratory diagnostic device clearance framework provides predictable timelines for metabolic cart manufacturers seeking US market entry.
- Zirconium oxide fuel cell maturation:Solid-state oxygen sensing technology reduces calibration frequency and maintenance burden in high-throughput clinical settings.
Market Restraints
- Paramagnetic sensor supply concentration:Three specialized component suppliers in Germany and Switzerland control the precision oxygen sensor market, creating single-source vulnerability for metabolic cart assembly.
- EU MDR clinical evidence burden:The Medical Device Regulation imposes retrospective clinical validation requirements on software-integrated gas analyzers, extending recertification timelines by 18-24 months.
- Portable device margin erosion:Asian contract manufacturers now produce commodity-grade indirect calorimeters at 40-60% below European production costs, pressuring mid-tier pricing.
Strategic Opportunities
- Home-based metabolic monitoring:Post-acute care providers in the United States seek remote patient monitoring solutions for bariatric surgery follow-up, opening ambulatory channels previously closed to hospital-grade equipment.
- CE marking acceleration:Notified bodies in the Netherlands and Germany now offer parallel technical file reviews for software-integrated diagnostic devices, compressing EU market entry timelines.
- Breath-by-breath AI integration:Machine learning algorithms analyzing respiratory patterns are converging with traditional gas exchange measurement, enabling real-time metabolic trajectory prediction in sports science applications.
Industry Challenges
- Clinical engineering talent scarcity:Hospitals report 18-month average vacancies for biomedical technicians qualified to service multi-sensor metabolic carts, delaying equipment deployment and uptime guarantees.
- Legacy EMR integration complexity:Proprietary data formats from incumbent calorimeter manufacturers require custom HL7 interface development, inflating IT implementation budgets for health system rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Indirect Calorimeter Market |
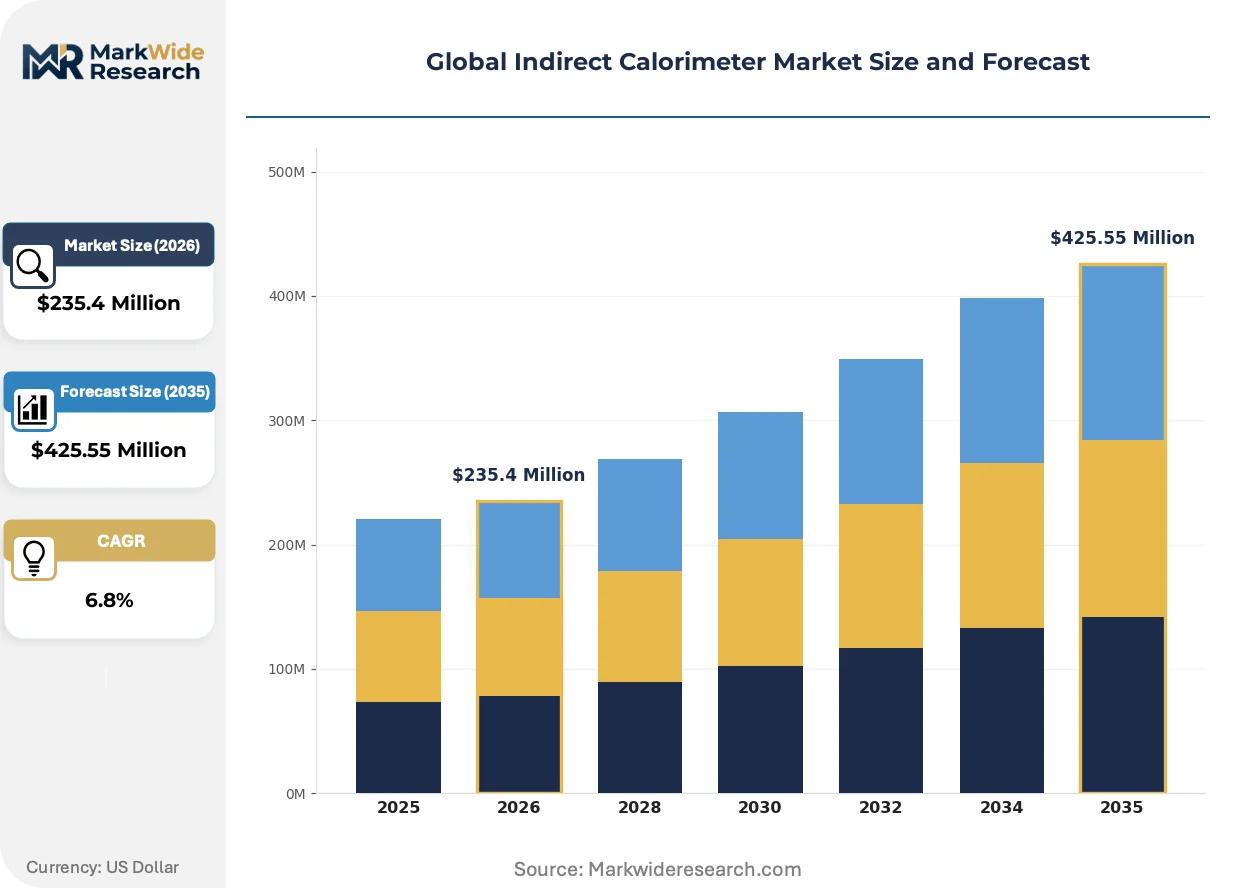
| Market Size in 2026 | $235.4 Million |
| Market Size in 2035 | $425.55 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Calorimeter, Metabolic Cart, Respiratory Gas Analyzer, Bench-top Indirect Calorimeter Application: Sports Science, Nutritional Research, Critical Care, Weight Management, Metabolic Studies End User: Healthcare Facilities, Research Institutes, Fitness Centers, Sports Clinics, Wellness Centers Technology: Open-circuit Calorimetry, Closed-circuit Calorimetry, Breath-by-breath Analysis, Paramagnetic Oxygen Sensor |
| Companies Covered | COSMED Srl, Parvo Medics, KORR Medical Technologies, MGC Diagnostics, Vyaire Medical, Maastricht Instruments, GE Healthcare, Microlife Corporation, Pacific Medico, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Indirect Calorimeter Market Shifts & Advancements
Sensor miniaturization and cloud-native software architectures are dismantling the traditional boundary between laboratory-grade metabolic carts and point-of-care diagnostic devices, forcing incumbents to defend installed bases through service contracts rather than hardware lock-in.
Wireless capnography modules with integrated paramagnetic oxygen sensing are converging with tablet-based data visualization platforms. Sports medicine clinics and performance centers adopt these configurations within 12-18 month replacement cycles, bypassing capital committee approvals required for full metabolic carts. This convergence is compressing the addressable market for standalone portable calorimeters while expanding the total volume of metabolic assessments performed outside hospital walls.
The EU Medical Device Regulation's software classification rules now capture algorithmic breath-by-breath analysis as standalone medical devices. Manufacturers must submit clinical performance data for pattern-recognition features previously treated as accessory functions. German and French notified bodies interpret these requirements most strictly, while Dutch regulators permit modular certification approaches that segment hardware and software validation.
Health system purchasing cooperatives in the United States now bundle indirect calorimetry with ventilator and patient monitor contracts, displacing standalone RFP processes. IDN procurement teams negotiate enterprise pricing across 15-50 hospital sites, extracting 20-35% volume discounts unavailable to individual facilities. This concentration is most visible in the Southeast and Midwest, where Catholic health networks and for-profit chains dominate acute care bed capacity.
Global Indirect Calorimeter Market Segmentation
Indirect calorimeter purchasing patterns fragment sharply across clinical, research, and commercial settings. Each segment demands distinct sensor precision, software integration depth, and regulatory compliance profiles that reshape manufacturer R&D allocation.
Product Type:
Supply concentration for precision gas sensors and integrated software stacks creates divergent margin structures across hardware categories.
- Metabolic Cart:Stationary systems integrate paramagnetic oxygen analyzers, capnography modules, and ventilator synchronization interfaces for ICU deployment. University hospitals in Germany anchor procurement volume, driven by bariatric surgery protocol mandates and critical care nutritional support guidelines. FDA 510(k) clearance timelines compress competitive windows for new entrants targeting US health systems.
- Portable Calorimeter:Battery-operated units with wireless data transmission enable point-of-care metabolic testing outside traditional laboratory infrastructure. Sports clinics in the United States and wellness centers in Japan drive replacement cycles averaging 18 months, bypassing capital committee approvals required for full metabolic carts. Component miniaturization from Asian contract manufacturers accelerates price erosion in this tier.
- Respiratory Gas Analyzer:Modular oxygen and carbon dioxide measurement units designed for integration with third-party ventilation systems.
- Bench-top Indirect Calorimeter:Laboratory-grade systems prioritizing measurement precision over throughput for controlled research environments.
Today's leader: Metabolic Cart. Tomorrow's challenger: Portable Calorimeter.
Application:
End-use requirements stratify around measurement frequency, environmental control, and real-time data demands.
- Critical Care:Ventilated patient monitoring demands continuous respiratory quotient calculation with sub-one-percent error margins for nutritional support dosing. ICU departments in university hospitals now embed indirect calorimetry into standard care pathways, with procurement committees weighting total cost of ownership against diagnostic accuracy guarantees.
- Sports Science:Athlete performance testing prioritizes breath-by-breath temporal resolution over absolute precision, enabling adoption of simplified sensor configurations. Performance centers in Australia and the United States upgrade equipment within compressed replacement cycles, creating recurring revenue streams for manufacturers with cloud-native software architectures.
- Nutritional Research:Controlled dietary intervention studies require validated measurement protocols with extensive calibration documentation.
- Weight Management:Commercial bariatric programs utilize simplified metabolic screening for patient engagement and protocol adherence.
- Metabolic Studies:Academic research applications spanning diabetes, obesity, and endocrine disorder investigation.
Critical Care commands current procurement volume. Sports Science exhibits the steepest expansion trajectory as performance optimization permeates amateur and professional athletics.
End User:
Customer sophistication and purchasing authority determine pricing tolerance and service contract attachment rates.
- Healthcare Facilities:Hospital systems and acute care networks negotiate enterprise pricing across 15-50 sites, extracting volume discounts unavailable to individual facilities. IDN procurement teams in the US Southeast and Midwest bundle indirect calorimetry with ventilator contracts, displacing standalone RFP processes.
- Research Institutes:University laboratories and government research centers prioritize measurement precision and publication-grade validation data.
- Fitness Centers:Commercial gyms deploy simplified metabolic screening for member retention and personalized training program development.
- Sports Clinics:Specialized athletic medicine practices balance equipment portability against diagnostic credibility for professional team contracts.
- Wellness Centers:Preventive health facilities in North America leverage simplified operator interfaces to extend metabolic testing to non-technical staff.
Healthcare Facilities dominate capital expenditure. Wellness Centers are climbing the fastest as consumer-facing metabolic health gains cultural traction.
Technology:
Sensor architecture choices lock manufacturers into distinct supply chain configurations and calibration service models.
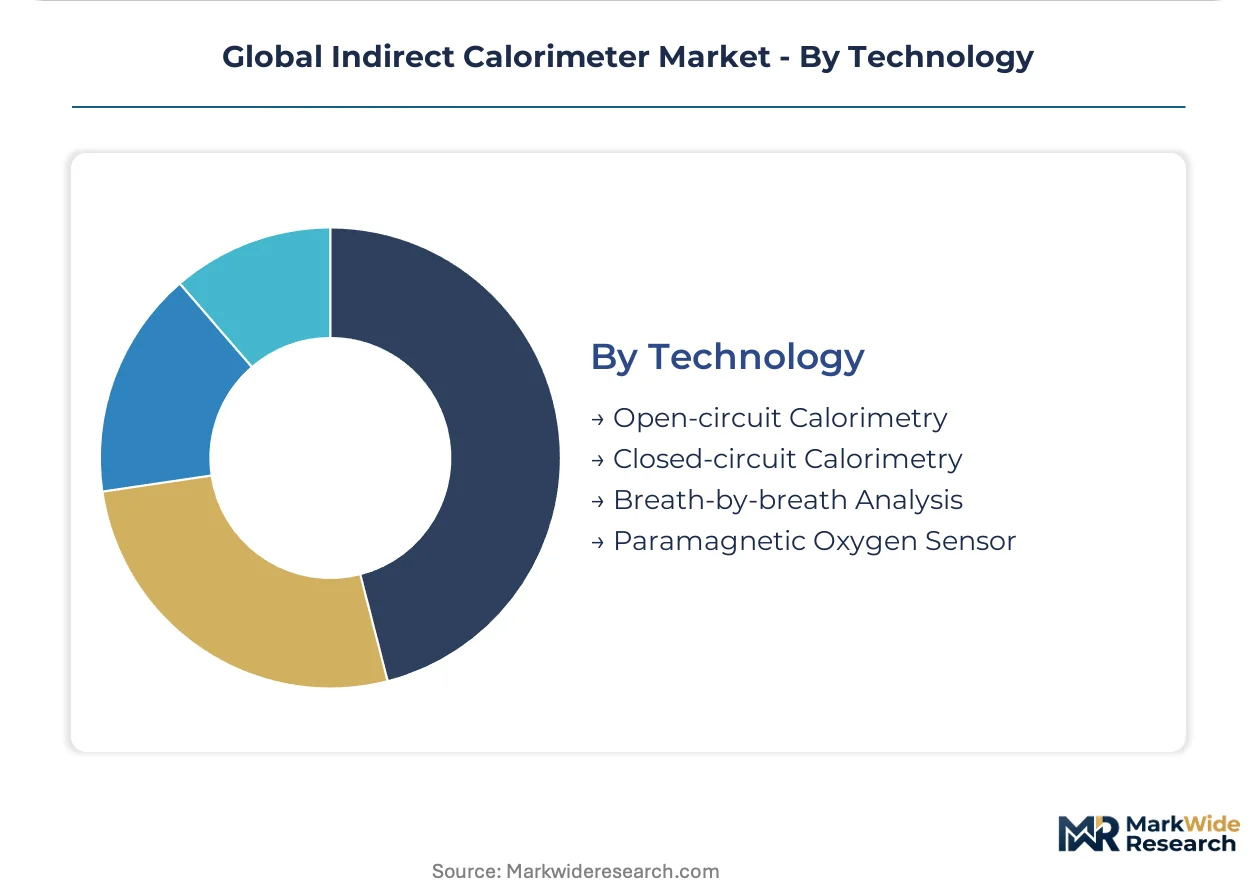
- Open-circuit Calorimetry:Continuous gas exchange measurement under ambient atmospheric conditions dominates research institute adoption. German and Swiss component suppliers control precision oxygen sensor availability, creating single-source vulnerability for metabolic cart assembly.
- Breath-by-breath Analysis:Real-time respiratory pattern capture enables metabolic trajectory prediction through emerging machine learning integration. EU MDR software classification rules now capture algorithmic analysis as standalone medical devices, extending validation timelines for pattern-recognition features.
- Closed-circuit Calorimetry:Controlled environmental chamber systems for specialized applications requiring atmospheric isolation.
- Paramagnetic Oxygen Sensor:Precision oxygen measurement technology utilizing magnetic susceptibility differential for reference-grade accuracy.
Open-circuit Calorimetry holds installed base dominance. Breath-by-breath Analysis is gaining share fastest through AI convergence and sports medicine adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized biomedical engineering talent clusters in Germany and Switzerland anchor precision sensor manufacturing for metabolic monitoring equipment. Clinical research networks in university hospitals drive protocol standardization across national health systems. Regulatory divergence between FDA clearance pathways and EU MDR requirements fragments product launch sequencing.
United States
Critical care protocol expansion in university-affiliated hospital systems drives metabolic cart procurement for ventilated patient nutritional support. The FDA's 510(k) clearance framework provides predictable regulatory timelines for respiratory diagnostic devices seeking market entry. IDN purchasing cooperatives in the Southeast and Midwest bundle indirect calorimetry with ventilator contracts, extracting volume discounts across 15-50 hospital sites.
Germany
University hospitals anchor European clinical research networks mandating indirect calorimetry for bariatric surgery and ICU nutritional protocols. The EU Medical Device Regulation imposes stricter clinical evidence requirements for software-integrated gas analyzers, extending recertification timelines. Precision oxygen sensor suppliers in Baden-Württemberg and Bavaria control component availability for metabolic cart assembly.
Japan
Wellness centers and sports clinics drive portable calorimeter replacement cycles averaging 18 months for metabolic health screening. The PMDA maintains distinct approval pathways that delay market entry for foreign manufacturers of respiratory diagnostic equipment. Tokyo and Osaka metropolitan areas concentrate demand for simplified operator interfaces in consumer-facing metabolic testing.
China
Contract manufacturers produce commodity-grade portable calorimeters at 40-60% below European production costs, pressuring mid-tier global pricing. The NMPA governs medical device registration with evolving standards for software-integrated diagnostic equipment. Yangtze River Delta industrial clusters supply miniaturized sensor components for wireless capnography modules.
Australia
Sports medicine clinics and athlete performance centers adopt breath-by-breath analysis systems with compressed equipment replacement cycles. The TGA regulates medical device inclusion with alignment to international standards for respiratory gas analysis. Sydney and Melbourne anchor procurement volume for cloud-native metabolic monitoring platforms in professional athletics.
Global Indirect Calorimeter Market Competitive Landscape
Top-tier vendors anchor the premium metabolic cart segment, while mid-tier specialists and Asian contract manufacturers populate portable and commodity-grade tiers. The vendor base stratifies across three archetypes: precision sensor-integrated system builders, software-centric wellness platform providers, and component-specialist contract assemblers. Dominant competitive moves include M&A targeting breath-by-breath algorithm capabilities and strategic partnerships bundling hardware with EMR integration services.
Among Italian and European precision manufacturers, COSMED Srl and Maastricht Instruments exemplify the integrated-system archetype with manufacturing bases anchoring regional hospital procurement. Parvo Medics occupies a position within the North American specialist tier. KORR Medical Technologies represents the wellness-channel simplification strategy, while Vyaire Medical and GE Healthcare sit within diversified medical technology conglomerates leveraging cross-product bundling.
| Leading Market Players |
|---|
| COSMED Srl |
| Parvo Medics |
| KORR Medical Technologies |
| MGC Diagnostics |
| Vyaire Medical |
| Maastricht Instruments |
| GE Healthcare |
| Microlife Corporation |
| Pacific Medico |
| Others |
Supply & Pricing Matrix
Zirconium oxide fuel cell maturation is compressing calibration service revenue while concentrating sensor sourcing decisions among three German and Swiss component specialists. This technology transition simultaneously reduces total cost of ownership for hospital buyers and tightens supply-side pricing power among precision oxygen sensor manufacturers.
Pricing Analysis
The bundled-vs-unbundled service split separates metabolic cart vendors defending margin through multi-year service contracts from portable device manufacturers competing on hardware cost alone. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status and software integration depth. Cost compression in the portable tier is intensifying because Asian contract manufacturers now produce commodity-grade units at substantially lower production costs. Wellness centers and sports clinics exhibit highest price sensitivity, while university hospitals in Germany prioritize measurement accuracy guarantees over procurement cost.
Supply Chain Analysis
Workforce-availability constraints in Baden-Württemberg and Bavaria limit expansion capacity for precision paramagnetic sensor production. Supply concentrates in Germany, Switzerland, and China, with the latter dominating miniaturized wireless component assembly. Component sourcing draws from specialized oxygen sensor foundries, capnography module assemblers, and tablet-based visualization platform developers. Single-source vulnerability runs through the precision oxygen sensor tier where three suppliers control global availability. Distribution runs through hospital procurement committees, IDN purchasing cooperatives, and direct-to-clinic channels for portable devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on zirconium oxide fuel cell adoption reducing field service intensity, while premium-tier consolidation around FDA-cleared metabolic carts with integrated software ecosystems commands pricing power.
For Market Incumbents: Cement technology leadership in breath-by-breath AI integration to defend against software-centric wellness platform entrants. Deepen backward integration into paramagnetic sensor supply through exclusive partnerships with Baden-Württemberg component specialists. Expand service contract attachment rates among IDN purchasing cooperatives to lock out standalone portable device competitors.
For New Entrants and Emerging Players: FDA 510(k) pathway clarity in the United States opens a window for streamlined metabolic cart entry targeting mid-tier health systems bypassed by incumbent enterprise pricing. Target home-based metabolic monitoring for post-acute bariatric surgery follow-up as the most penetrable white-space segment. Pursue cloud-native software architectures enabling rapid EMR integration as the primary go-to-market angle.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier portable device manufacturers facing margin compression from Asian contract manufacturing competition. Long-term viability favors precision sensor-integrated system builders with captive hospital procurement relationships and recurring service revenue. Watch reimbursement code expansion for indirect calorimetry in critical care as the inflection signal determining hospital capital budget prioritization.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Parallel technical file reviews in Dutch and German notified bodies compress EU market entry timelines for software-integrated devices. |
| Hospital System Partnership | IDN bundling of indirect calorimetry with ventilator contracts extracts volume discounts across 15-50 sites in the US Southeast and Midwest. |
| Software Companion Development | Machine learning algorithms for real-time metabolic trajectory prediction differentiate sports science offerings from commodity hardware. |
| Reimbursement Strategy | Coverage code expansion for critical care nutritional monitoring determines whether metabolic carts secure priority in hospital capital budgets. |
| Backward Integration | Captive supply of zirconium oxide fuel cells reduces calibration frequency and service cost burden in high-throughput clinical settings. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital procurement managers, biomedical engineers, GPO contracts managers, and sports medicine clinic directors with secondary validation against FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up equipment shipment tracking and top-down health system expenditure analysis were triangulated against manufacturer revenue disclosures.
Historical reference periods anchored the forecast window through verified installed base counts and replacement cycle analysis across the projection horizon. Segmentation modeling captured product type, application, end user, technology, and regional regulatory cluster dimensions. CAGRs were derived from fitted growth curves calibrated to protocol adoption rates and health system capital expenditure patterns. Forecast inputs incorporated zirconium oxide fuel cell penetration trajectories and EU MDR recertification timeline impacts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under paramagnetic sensor supply disruption or reimbursement code rejection scenarios. Projections reflect documented assumptions regarding critical care protocol expansion and wellness center channel development. Material deviation in FDA clearance timelines or IDN bundling contract structures warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Animal Operating Table Market
Medical Equipment
Blood Banking Equipment Market
Medical Equipment
Cryochambers Market
Medical Equipment
Durable Medical Equipment Rental Market
Medical Equipment
Radiotherapy Motion Management Market
Medical Equipment
Global Mortuary Equipment Market
Medical Equipment
RFID Blood Refrigerators and Freezers Market
Medical Equipment
Medical Device and Equipment Tags Market
Medical Equipment
Medical Equipment Maintenance Market
Medical Equipment
Global Embryo Incubator Market
Medical Equipment
Global Operating Table Mattresses Market
Medical Equipment
Global Plasma Sterilizers Market
Medical Equipment
US ECG Equipment Market
Medical Equipment
ECG Equipment Market
Medical Equipment
Medical Filter Market
Medical Equipment
Medical Pediatric Bed Market