
 Europe Dental Implants Market | 2026-2036
Europe Dental Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Dental Implants Market Intelligence
Subscription-based maintenance and monitoring packages for implant systems is expanding as a recurring revenue layer that shifts unit economics toward lifetime patient value. Institut Straumann AG leverages its digital dentistry ecosystem to anchor premium positioning across Northern Europe. Nobel Biocare Services AG competes through specialized training academies that lock in clinician loyalty. Dentsply Sirona Inc. extends its footprint by controlling CAD/CAM workflow integration from scan to final restoration.
Dental implants are titanium or zirconia screw-like fixtures surgically placed into the jawbone, typically measuring 3-6 mm in diameter and 7-16 mm in length, designed to osseointegrate and support prosthetic crowns or dentures. Endosteal implants dominate procedure volumes due to established surgical protocols and broad bone-type compatibility, while zirconia variants are gaining share among patients with titanium sensitivity concerns. Titanium remains the margin pool leader given decades of clinical data and favorable reimbursement coding, though polymer and alloy research is opening niche applications in temporary anchorage devices.
The EU Medical Device Regulation (MDR) and CE marking framework now require enhanced clinical evidence and post-market surveillance for implantable devices, elevating compliance costs but also screening out lower-tier suppliers. Germany's national reimbursement body, the G-BA, alongside France's HAS, shapes demand through procedural tariff settings and quality indicator programs. Stakeholders must monitor how MDR transition timelines and national health technology assessments converge to determine which material platforms and end-user channels retain sustainable economics.
Market Dynamics
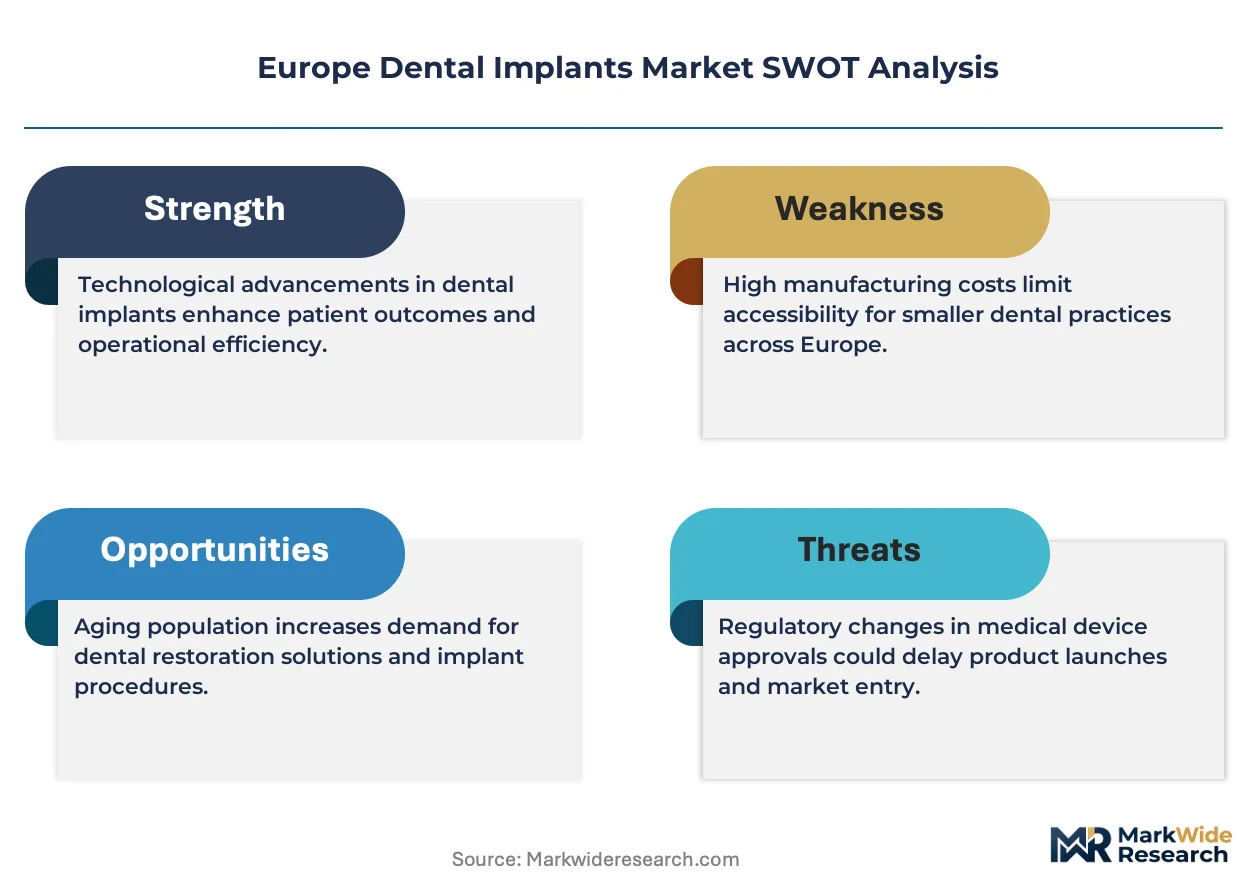
The EU Medical Device Regulation (MDR) is forcing a wholesale recertification of legacy implant portfolios, compressing supplier margins while elevating documentation burdens that favor incumbents with established clinical evidence libraries.
Growth Catalysts
- Aging demographics:Germany's 65-plus population density drives procedural volume expansion in private clinics across Bavaria and North Rhine-Westphalia.
- MDR transition timelines:Enhanced post-market surveillance requirements under the EU MDR are consolidating demand toward suppliers with robust quality management systems.
- Zirconia biocompatibility:Titanium-sensitive patient cohorts in France and Italy are accelerating material substitution toward ceramic implant platforms.
Market Restraints
- Titanium supply concentration:Sponge and alloy production clusters in Eastern Europe create input cost volatility for manufacturers dependent on regional smelters.
- CE marking friction:Extended notified body capacity constraints under MDR Article 120 transition provisions delay new product launches by 18-24 months.
- Removable denture substitution:Cost-conscious patients in Southern Europe continue selecting acrylic prosthetics over fixed implant solutions.
Strategic Opportunities
- Poland and Czech Republic:Underpenetrated implant density relative to Western Europe offers expansion corridors for specialist clinic networks.
- Digital workflow convergence:Intraoral scanning combined with chairside milling is compressing restoration turnaround times for same-day protocols.
- Subscription monitoring models:Per-implant annual maintenance packages are shifting revenue recognition toward recurring service streams.
Industry Challenges
- Prosthodontist training pipelines:Extended fellowship durations in Germany and France constrain specialist throughput for complex full-arch reconstructions.
- Legacy CAD/CAM integration:Siloed software architectures between implant planning and restoration design systems force manual data translation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Dental Implants Market |
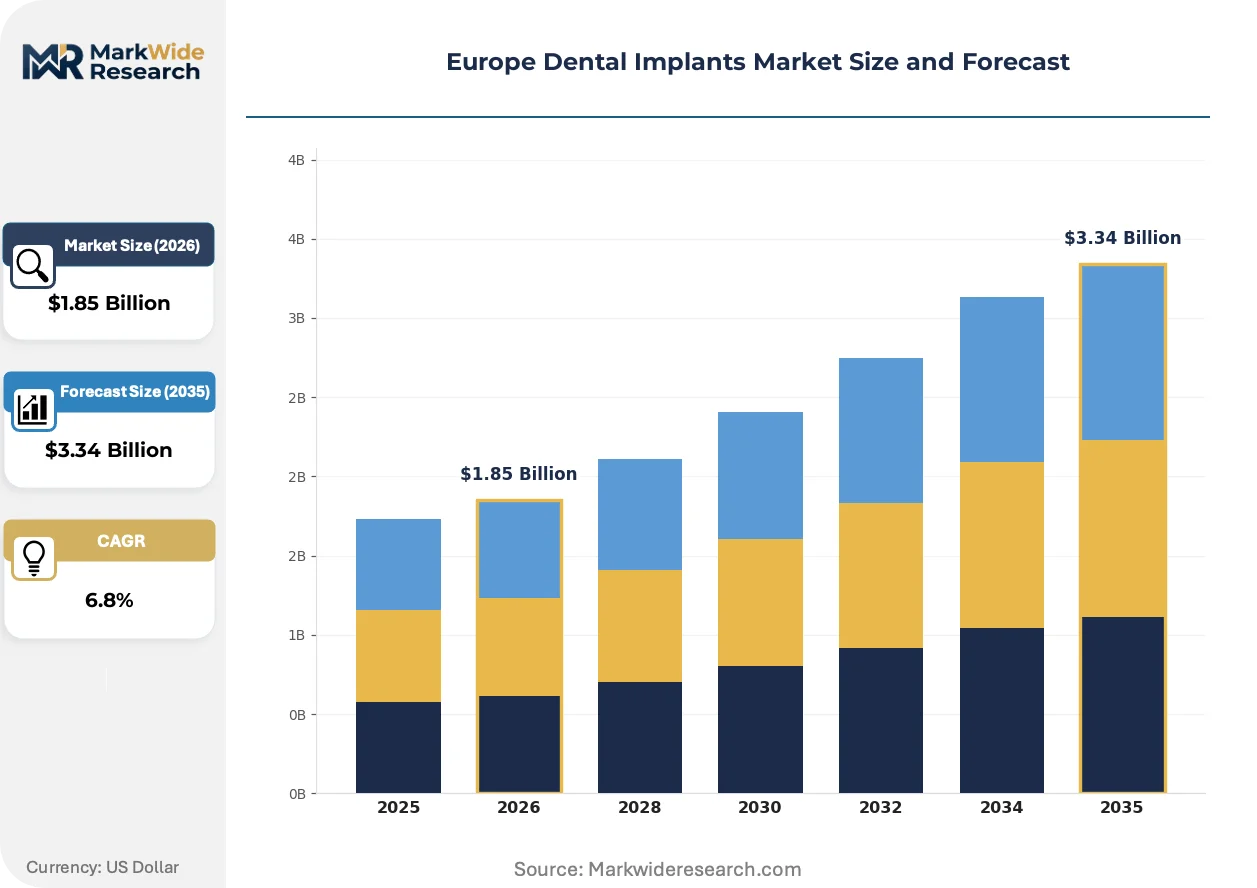
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endosteal Implants, Subperiosteal Implants, zygomatic Implants, Mini Implants Material: Titanium, Zirconia, Polymer, Alloy End User: Dental Clinics, Hospitals, Research Institutes, Dental Laboratories Application: Single Tooth Replacement, Multiple Tooth Replacement, Implant-Retained Dentures, Bone Augmentation |
| Companies Covered | Nobel Biocare Services AG, Osstem Implant Co., Institut Straumann AG, MIS Implants Technologies, BioHorizons Implant Systems, Dentsply Sirona Inc., ZimVie Inc., CAMLOG Biotechnologies GmbH, Envista Holdings Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Dental Implants Market Strategic Shifts & Innovations
Digital dentistry ecosystems are compressing the traditional lab-centric model, with chairside production and cloud-based treatment planning displacing conventional multi-visit protocols across Northern European markets.
Guided surgery software is modularizing implant placement workflows, enabling general practitioners with limited surgical training to execute preplanned osteotomies using 3D-printed drill guides. Adoption concentrates in Dutch and Belgian group practices seeking to capture specialist margin pools. This technology is modularizing the historical division between surgical and restorative phases, collapsing procedure timelines from months to single-visit interventions.
The EU MDR's enhanced clinical evidence requirements for Class III implantable devices are elevating post-market surveillance obligations beyond legacy Medical Device Directive standards. Manufacturers must now maintain systematic literature reviews and periodic safety update reports across their entire titanium and zirconia portfolios. German notified bodies are applying the strictest interpretation of biocompatibility documentation, creating compliance divergence within the single market.
After-sales service unbundling is separating hardware procurement from ongoing maintenance contracts, with French and Swiss clinics negotiating multi-year monitoring agreements independent of initial implant purchases. Specialist practices in Zurich and Geneva are pioneering this bifurcation, treating implants as subscription-enabled platforms rather than discrete capital equipment. This shift is most visible in premium private segments where patient lifetime value calculations dominate acquisition economics.
Europe Dental Implants Market Segmentation
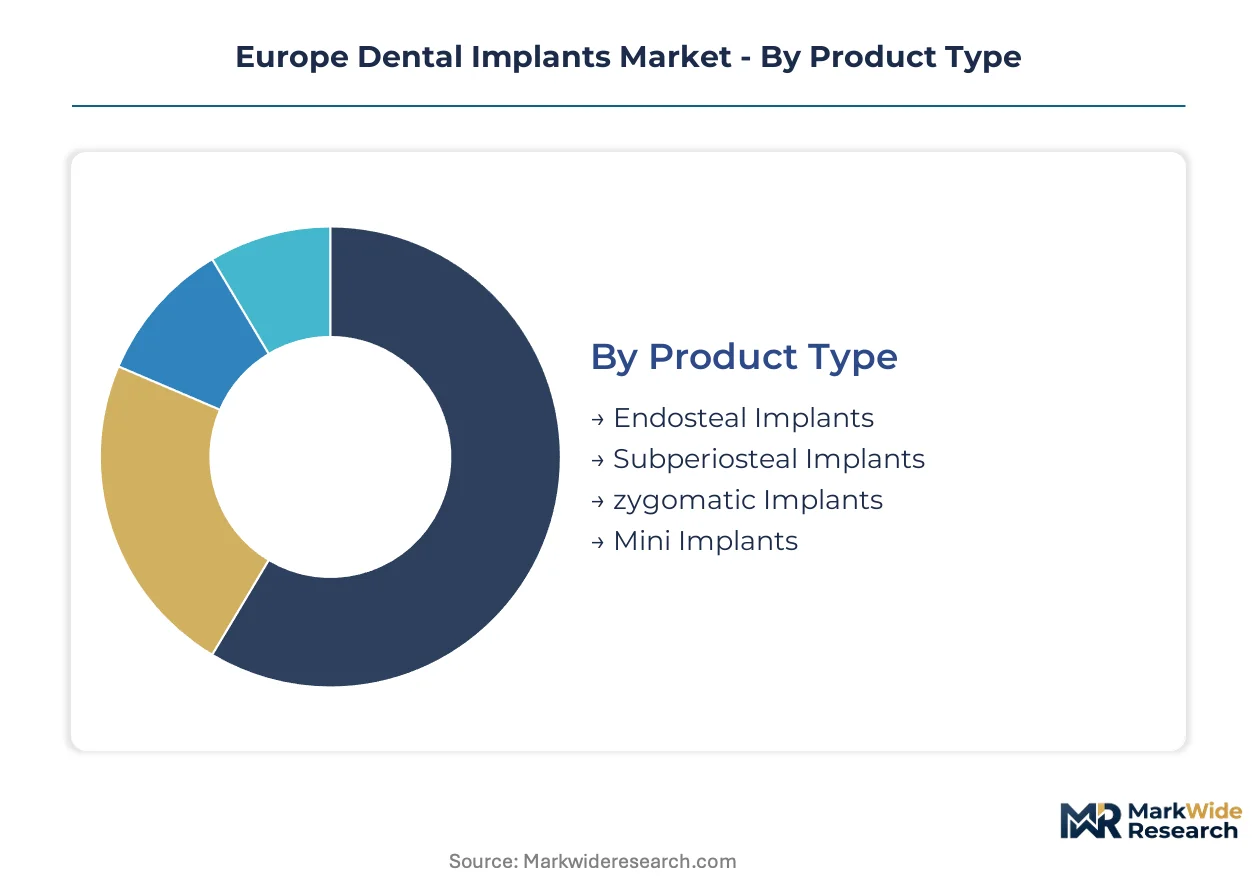
Material selection and surgical approach determine reimbursement pathways and patient eligibility across European markets. Product architecture directly influences which clinical settings can deliver profitable care.
Product Type:
Capital intensity concentrates in surgical navigation systems and 3D imaging infrastructure required for complex anatomical placements.
- Endosteal Implants:Screw-type fixtures placed directly into alveolar bone, typically 3-6 mm in diameter with threaded or cylindrical designs. Demand clusters in German private practices serving aging cohorts in Bavaria and North Rhine-Westphalia, where bone density supports conventional osteotomy protocols. The EU MDR's biocompatibility documentation requirements favor established titanium platforms with decades of clinical evidence.
- Zygomatic Implants:Extended-length fixtures anchoring into the zygomatic bone for maxillary atrophy cases, requiring specialized training and hospital-grade anesthesia. French oral surgery centers in Paris and Lyon report rising volumes among edentulous patients with severe resorption who reject grafting timelines. CE marking delays under MDR Article 120 constrain new entrant supply.
- Subperiosteal Implants:Custom frameworks resting on bone surface for patients with insufficient vertical bone height.
- Mini Implants:Narrow-diameter temporary anchorage devices for orthodontic applications and overdenture stabilization.
Most installed capacity flows through Endosteal Implants. Expansion is steepest in Zygomatic Implants.
Material:
Raw material sourcing shapes margin structures, with Eastern European titanium sponge clusters creating regional cost advantages.
- Titanium:Commercially pure grades 1-4 and Ti-6Al-4V alloy dominate surgical implant portfolios due to established osseointegration kinetics and favorable G-BA reimbursement coding in Germany. German notified bodies apply strictest MDR biocompatibility interpretation, elevating documentation costs for new alloy variants. Poland's emerging clinic networks source titanium systems from Western European distributors facing input cost volatility.
- Zirconia:Yttria-stabilized tetragonal polycrystalline ceramic platforms attract titanium-sensitive patients in France and Italy, where metal-free aesthetics command premium pricing. Milan and Rome aesthetic dentistry practices report substitution rates climbing fastest among female patients aged 45-65 seeking gingival tissue compatibility.
- Polymer:Resorbable and non-resorbable polymers for temporary anchorage and guided tissue regeneration.
- Alloy:Cobalt-chrome and novel compositions for niche load-bearing applications.
Installed base tilts toward Titanium. Zirconia gains share fastest in aesthetic-focused segments.
End User:
Workflow integration requirements separate capital-intensive digital adopters from labor-intensive conventional operators.
- Dental Clinics:Private specialist and group practices across Germany, France, and Switzerland concentrate procedure volume, with Dutch and Belgian group practices adopting guided surgery software fastest. Chairside milling investments in Zurich and Geneva clinics compress restoration turnaround to same-day protocols. Subscription-based maintenance contracts are unbundling from hardware procurement in premium segments.
- Hospitals:Academic medical centers and maxillofacial surgery departments handle complex zygomatic placements and medically compromised patients. French public hospitals in Paris cluster full-arch reconstructions requiring general anesthesia and overnight admission. MDR post-market surveillance obligations elevate compliance staffing.
- Research Institutes:University dental schools and biomaterials laboratories conducting clinical trials and device development.
- Dental Laboratories:Independent and in-house labs producing custom abutments and prosthetic frameworks.
Procedure volume concentrates in Dental Clinics. Digital workflow adoption climbs fastest in Hospital-affiliated training centers.
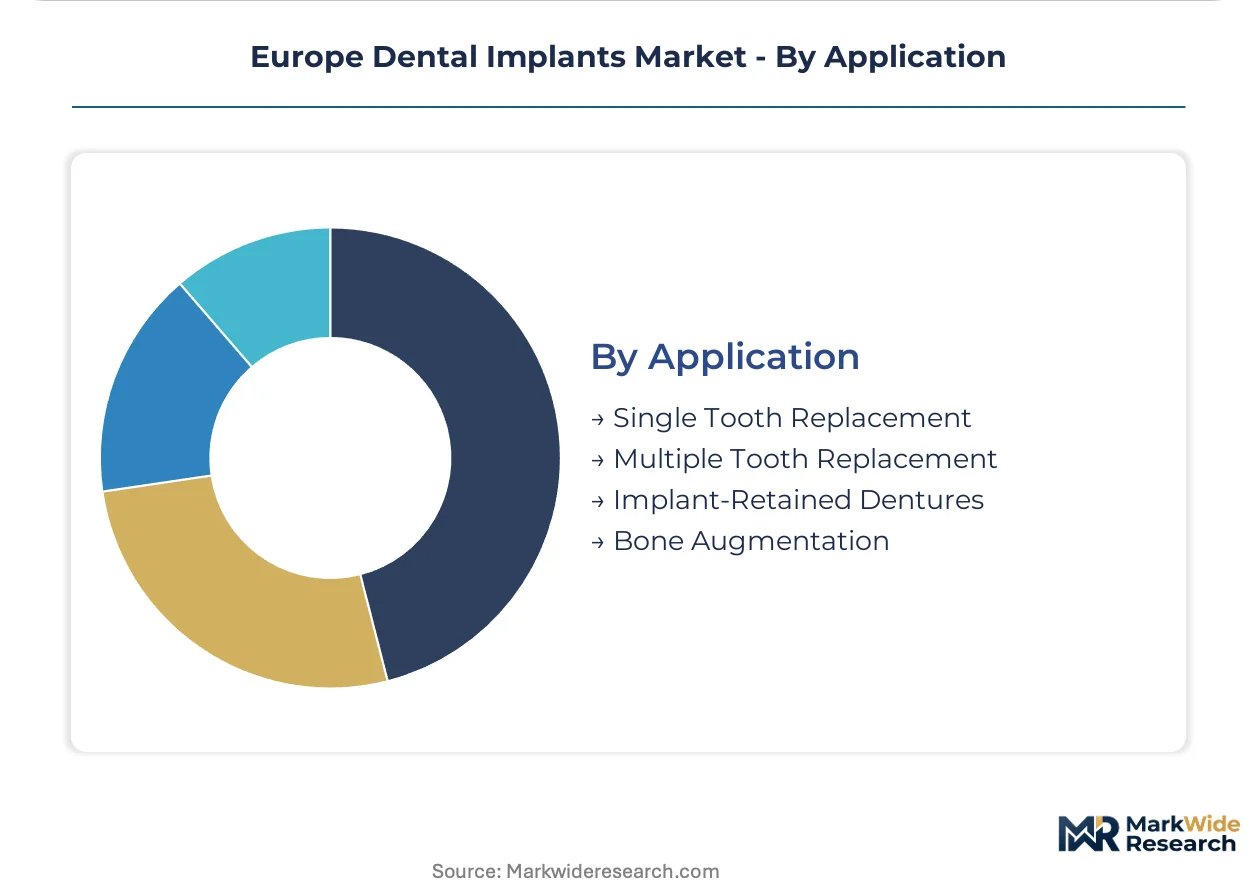
Application:
Case complexity determines reimbursement tier and required specialist credentialing across national health systems.
- Single Tooth Replacement:Anterior and posterior crown-supported implants represent the volume base, with German statutory insurance covering partial reimbursement for medically necessary extractions. Bavarian private practices bundle implant placement with immediate provisionalization using intraoral scanning and chairside milling. France's HAS quality indicators reward practices with documented survival rates.
- Implant-Retained Dentures:Full-arch overdentures on 2-4 implants serve cost-conscious edentulous patients in Southern Europe where fixed solutions remain unaffordable. Spanish and Portuguese clinics report acrylic prosthetic substitution limiting implant penetration despite superior functional outcomes.
- Multiple Tooth Replacement:Fixed partial prostheses bridging edentulous spans with implant support.
- Bone Augmentation:Grafting procedures preceding or concurrent with implant placement for atrophic ridges.
Single Tooth Replacement carries the heaviest installed procedure base. Implant-Retained Dentures expand most quickly in price-sensitive markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's implant procedure density outpaces France by a factor of nearly two, yet both markets operate under divergent reimbursement architectures that shape clinician economics and patient access patterns across Northern Europe.
Germany
Bavarian and North Rhine-Westphalian private clinics drive procedural volume through dense specialist networks and clear G-BA tariff structures. The EU MDR's biocompatibility documentation requirements elevate compliance costs that favor established titanium portfolios with decades of clinical evidence. Frankfurt and Munich cluster digital dentistry adoption, with chairside milling investments compressing restoration timelines toward same-day protocols.
France
Paris and Lyon oral surgery centers report rising zygomatic implant volumes among edentulous patients rejecting grafting timelines. HAS quality indicator programs reward practices with documented survival rates, steering demand toward premium material platforms. The French market's metal-free aesthetic preference accelerates zirconia substitution fastest among female patients aged 45-65 in Milan-influenced Rome corridor spillover.
Italy
Milan and Rome aesthetic dentistry practices command premium pricing for zirconia platforms targeting titanium-sensitive cohorts. ANSM post-market surveillance obligations align with EU MDR transition timelines, extending notified body review periods for new ceramic alloy variants. Northern Italian clinic networks leverage proximity to Swiss digital workflow suppliers for integrated CAD/CAM restoration pipelines.
Switzerland
Zurich and Geneva specialist practices pioneer subscription-based maintenance contracts unbundled from hardware procurement, treating implants as recurring-revenue platforms. Swissmedic applies stringent interpretation of implantable device biocompatibility standards, creating regulatory divergence within adjacent EU markets. Lake Geneva corridor clinics concentrate full-arch reconstruction capacity requiring hospital-grade anesthesia infrastructure.
Poland
Warsaw and Krakow emerging clinic networks source titanium systems from Western European distributors facing Eastern European sponge supply volatility. Underpenetrated implant density relative to German benchmarks offers expansion corridors for specialist training academies. Polish reimbursement clarity lags Western European standards, constraining procedure volume despite favorable demographic tailwinds.
Europe Dental Implants Market Key Industry Players
Top-tier vendors anchor premium digital ecosystems, while mid-scale specialists compete through material differentiation and regional training networks. The vendor base stratifies across three tiers: integrated platform providers controlling end-to-end workflows, component specialists dominating specific surgical or restorative niches, and regional distributors serving price-sensitive Southern European markets. Two dominant competitive moves reshape positioning: MDR-driven consolidation of legacy portfolios through notified body recertification partnerships, and backward integration into titanium alloy sourcing to offset Eastern European input cost volatility.
Within the integrated platform tier, Institut Straumann AG, Nobel Biocare Services AG, and Dentsply Sirona Inc. exemplify divergent strategic architectures. The Swiss-based entity anchors Northern European positioning through digital dentistry ecosystem control. The Swedish-German hybrid occupies specialist loyalty through clinician training academy investments. The American-German conglomerate extends reach via CAD/CAM workflow integration from intraoral scanning through final restoration fabrication.
| Leading Market Players |
|---|
| Nobel Biocare Services AG |
| Osstem Implant Co. |
| Institut Straumann AG |
| MIS Implants Technologies |
| BioHorizons Implant Systems |
| Dentsply Sirona Inc. |
| ZimVie Inc. |
| CAMLOG Biotechnologies GmbH |
| Envista Holdings Corporation |
| Others |
Cost & Logistics Intelligence
Titanium sponge price indices from Eastern European smelters cascade through implant manufacturing tiers, compressing margins for distributors while premium zirconia platforms maintain pricing power through Swiss and German clinic networks.
Pricing Analysis
Capacity additions in Polish and Czech manufacturing zones are reshaping price floors for standard titanium implant systems, forcing Western European incumbents to differentiate through CE marking tier and after-sales service bundling. Three-tier pricing structure across premium, standard, and economy levels separates Straumann-grade digital ecosystems from mid-market titanium portfolios and Eastern European imports. Cost compression in economy tiers is intensifying because MDR recertification costs fall disproportionately on smaller suppliers. Price-sensitive buyers cluster in Southern European public procurement, while Swiss private clinics demonstrate lowest sensitivity due to subscription-based maintenance contracts.
Supply Chain Analysis
Freight cost volatility from Eastern European titanium sponge clusters to German machining centers has elevated landed costs for alloy-dependent manufacturers. Supply concentrates in Ukraine, Kazakhstan, and Russian-origin feedstock channels now drawing from alternative Central Asian sources. Raw material dependencies center on titanium sponge, yttria-stabilized zirconia powder, and precision-machined abutment blanks. Single-source vulnerability pervades yttria supply chains concentrated in Chinese rare earth processing. Distribution runs through specialist dental distributors in Düsseldorf and Paris, with direct-to-clinic digital platforms gaining share in Nordic markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe dental implants function as a stable compounder anchored by irreversible demographic aging and procedure volume expansion in private German and French clinics.
For Market Incumbents: Acquire digital workflow software assets to lock in clinician loyalty before MDR transition consolidates demand toward integrated platform providers. Defensive priorities center on backward integration into titanium alloy sourcing to offset Eastern European input cost volatility, alongside CE marking recertification partnerships that screen out lower-tier competitors. Threat vectors include zirconia substitution accelerating among titanium-sensitive patient cohorts and Polish clinic networks sourcing directly from Asian manufacturers.
For New Entrants and Emerging Players: Teledentistry-enabled remote treatment planning offers low-friction entry into Dutch and Belgian group practices seeking guided surgery solutions without specialist overhead. White-space targets include underpenetrated Warsaw and Krakow clinic networks, plus zygomatic implant niches in French oral surgery centers constrained by legacy CE marking delays. Go-to-market positioning should emphasize chairside milling compatibility and per-implant subscription economics rather than hardware-centric procurement.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale zirconia specialists possessing ANSM-aligned quality systems and Milan-Rome corridor aesthetic clinic relationships. Long-term viability over a multi-year horizon favors platforms with recurring revenue attachment rates above hardware-only peers. Acquisition target archetype: ceramic implant manufacturers with established biocompatibility documentation libraries. Signal to watch: G-BA reimbursement tariff adjustments for metal-free restorations as indicator of structural demand shift.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Recertification Partnership | Notified body alliances with TÜV SÜD or DEKRA accelerate legacy portfolio compliance and exclude non-compliant rivals. |
| Digital Workflow Integration | Chairside milling investments in Zurich and Geneva clinics compress restoration timelines toward same-day protocols. |
| Zirconia Platform Expansion | Yttria-stabilized ceramic systems capture titanium-sensitive demand in Milan-influenced aesthetic dentistry corridors. |
| Subscription Maintenance Unbundling | Swiss clinic networks treat implants as recurring-revenue platforms independent of initial hardware procurement. |
| Specialist Training Academy Investment | Clinician loyalty lock-in through Paris and Lyon surgical certification programs steers long-term purchasing decisions. |
Research Approach
Multiple input streams — oral surgeon interviews, GPO procurement database analysis, and notified body regulatory filings — were reconciled to construct procedure volume and pricing estimates across the analysis window. Primary discussions with implant surgeons, clinic network procurement directors, biomedical engineers, and dental laboratory technicians informed demand-side assumptions. Secondary validation drew from EUDAMED device registrations, G-BA tariff documentation, HAS quality indicator reports, and customs trade data for titanium sponge imports. Bottom-up implant procedure counts by country and material platform were cross-referenced against top-down manufacturer revenue disclosures.
Historical volume trajectories were cross-referenced against expert panel assessments to anchor growth assumptions across the projection horizon. Segmentation modeling incorporated material platform, surgical approach complexity, end-user channel type, and national reimbursement framework as core dimensions. CAGRs were derived from curve-fitting procedures against demographic projections and procedure penetration benchmarks. Forecast inputs included specialist density ratios, MDR transition timeline compliance rates, and digital workflow adoption curves in Northern European clinic networks.
The model assumes a particular technology adoption path; alternative pathways for chairside milling and guided surgery would alter the outlook if general practitioner adoption outpaces specialist capacity constraints. Forecasts reflect underlying assumptions about G-BA reimbursement stability and Eastern European titanium supply continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Laboratories Market
Dental Devices
3D Printed Clear Dental Aligners Market
Dental Devices
Prophy Dental Handpiece Market
Dental Devices
Global Orthodontic Product Market
Dental Devices
Asia-Pacific Dental Aligners Market
Dental Devices
Periodontal Scalers and Curettes Market
Dental Devices
Dental Chair Market
Dental Devices
Dental Composite Resin Filling Market
Dental Devices
Dental Splints Market
Dental Devices
Global Restorative Dentistry Market
Dental Devices
Lights for Dental Healthcare Market
Dental Devices
Sleep Apnea Oral Appliances Market
Dental Devices
Chile Dental Market
Dental Devices
Global Endodontics Market
Dental Devices
Dental Apex Locator Market
Dental Devices
Guided Biofilm Therapy Market