
 Endodontics and Orthodontics Market | 2026-2036
Endodontics and Orthodontics Market Size, Share, and Industry Trends Forecast 2026-2036
Endodontics and Orthodontics Market Analysis
China is reshaping endodontic instrument manufacturing through large-scale titanium alloy processing zones in Jiangsu province. Dentsply Sirona leverages integrated digital workflows spanning cone beam imaging to chairside milling across European orthodontic practices. Straumann anchors premium implant-anchored orthodontics through its Basel-centered R&D and manufacturing footprint. Envista competes in value-tier clear aligner segments through its Ormco subsidiary's Spark system positioning against premium alternatives.
Endodontics and orthodontics encompass the diagnosis, prevention, and correction of dental pulp diseases and malocclusions through instruments, appliances, and biomaterials engineered to precise ISO 3630 and ADA specification tolerances. Orthodontic appliances employ nickel-titanium shape-memory alloys and medical-grade polymers to deliver calibrated biomechanical forces over 12-36 month treatment protocols. Endodontic instruments command mature margin pools with limited product differentiation, while digital imaging and 3D printing segments capture accelerating value as orthodontic practices adopt intraoral scanning and same-day aligner fabrication workflows. Dental cements face pricing compression from generic bioceramic alternatives even as cone beam CT installations expand across dental clinics seeking comprehensive treatment planning capabilities.
FDA 510(k) clearances govern orthodontic appliance market entry in the United States, while the EU Medical Device Regulation imposes strengthened clinical evidence requirements on custom-manufactured aligner systems. China's NMPA oversees endodontic file biocompatibility testing under GB/T 16886 standards, creating divergent compliance burdens for multinational suppliers. Stakeholders must monitor how FDA draft guidance on artificial intelligence-enabled orthodontic treatment planning software reshapes competitive barriers for digital workflow providers.
Market Dynamics
Digital workflow adoption is compressing orthodontic treatment timelines while titanium alloy processing concentration in Jiangsu province is reshaping endodontic instrument cost structures.
Growth Catalysts
- EU MDR pathway acceleration:Strengthened clinical evidence requirements for custom-manufactured aligner systems are filtering out marginal competitors and consolidating market access for compliant manufacturers.
- Nickel-titanium rotary instrumentation:Shape-memory alloy innovations in endodontic files are reducing chair time per procedure and expanding clinical throughput capacity in high-volume dental clinics.
- Suburban North American clinic expansion:Evolving reimbursement frameworks are enabling dental practices to add orthodontic service lines without dedicated hospital affiliations.
Market Restraints
- Raw material supply concentration:Premium nickel-titanium wire and medical-grade polymer feedstocks face sourcing bottlenecks from limited certified suppliers in East Asian processing zones.
- FDA 510(k) pathway friction:Artificial intelligence-enabled orthodontic treatment planning software faces evolving draft guidance that extends premarket review timelines for digital workflow providers.
- Bioceramic cement substitution:Generic alternatives to proprietary dental cements are compressing margin pools in restorative adjacencies that fund orthodontic equipment investments.
Strategic Opportunities
- Same-day aligner fabrication:Intraoral scanning paired with chairside 3D printing is hybridizing clinical workflows and capturing value previously lost to external dental laboratories.
- Costa Rica and Mexico manufacturing:FDA-registered clear aligner production facilities are establishing nearshore supply bases with tariff advantages and logistics proximity to US distribution networks.
- Implant-anchored orthodontics:Premium orthodontic appliances integrated with temporary anchorage devices are opening treatment protocols for complex malocclusion cases previously requiring orthognathic surgery.
Industry Challenges
- ISO 3630 and ADA specification compliance:Endodontic instrument manufacturers face precision tolerance verification bottlenecks that extend quality assurance cycles before commercial release.
- Digital workflow integration:Cone beam CT to chairside milling connectivity requires interoperability investments that strain capital allocation in independent dental practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endodontics and Orthodontics Market |
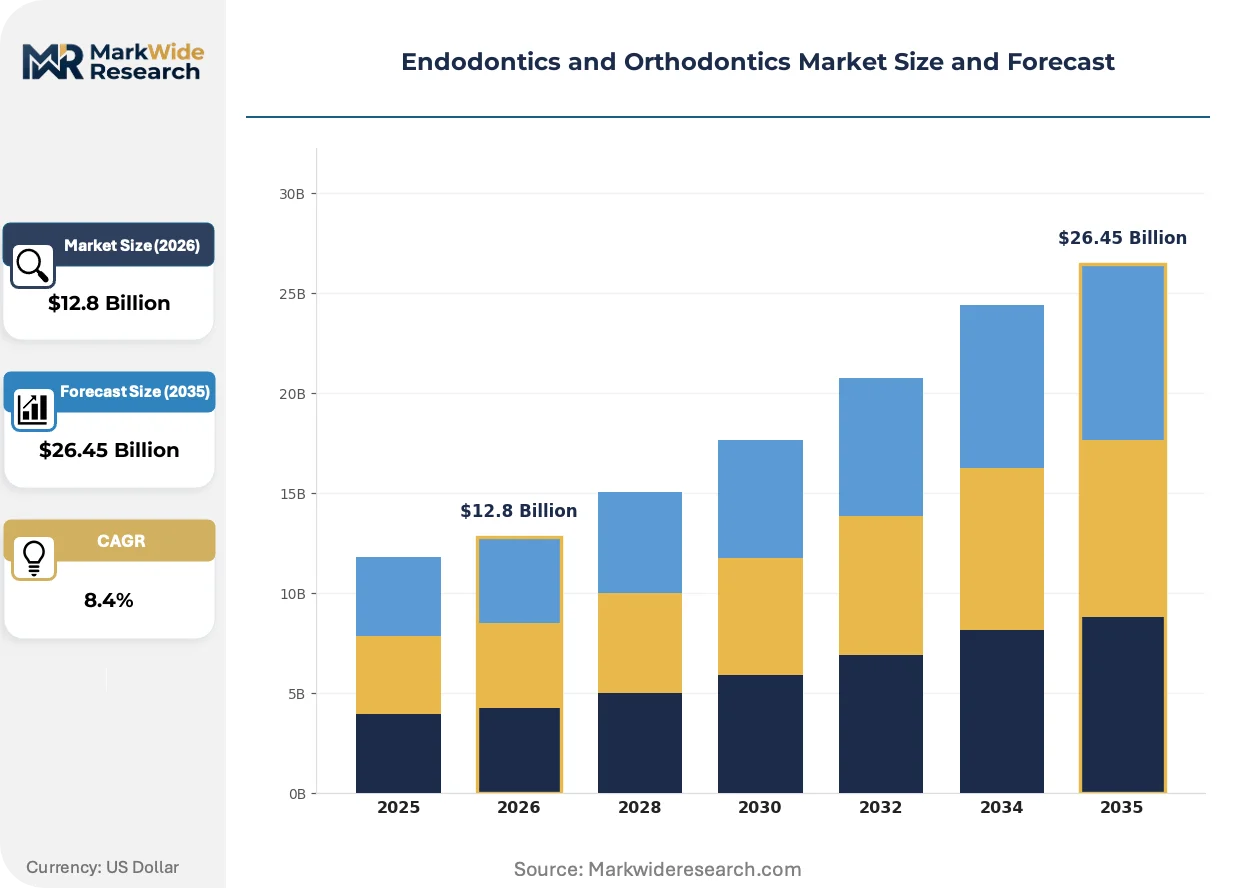
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endodontic Instruments, Orthodontic Appliances, Dental Cements, Endodontic Filling Materials Application: Root Canal Treatment, Teeth Alignment, Dental Restoration, Preventive Care End User: Dentists, Dental Clinics, Hospitals, Orthodontic Practices Technology: 3D Printing, Digital Imaging, Laser Therapy, Cone Beam CT |
| Companies Covered | Align Technology, Dentsply Sirona, Envista, 3M Oral Care, Ivoclar Vivadent, Septodont, Straumann, Ormco, Ultradent Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endodontics and Orthodontics Market Emerging Trajectories
Biomechanical force delivery systems and regulatory evidence frameworks are converging to reshape how orthodontic appliances and endodontic instruments reach clinical deployment.
Shape-memory alloy engineering is hybridizing endodontic and orthodontic applications through next-generation nickel-titanium formulations that combine superelasticity with enhanced fatigue resistance. High-volume dental service organizations are adopting these materials at accelerated procurement cycles. This metallurgical convergence is compressing the traditional separation between rotary instrumentation and fixed appliance wire supply chains.
China's NMPA biocompatibility testing requirements under GB/T 16886 standards are creating divergent compliance architectures for multinational suppliers seeking market access. Manufacturers must maintain parallel testing protocols or accept extended registration timelines. Endodontic file suppliers with Jiangsu province processing relationships are navigating this friction through localized certification partnerships.
Direct-to-consumer aligner screening platforms are fragmenting traditional orthodontic patient acquisition channels. General dentistry practices are responding by unbundling initial consultation and diagnostic imaging from treatment delivery. This channel disintermediation is most visible in suburban North American markets where reimbursement evolution has already enabled independent orthodontic service lines.
Endodontics and Orthodontics Market Segmentation
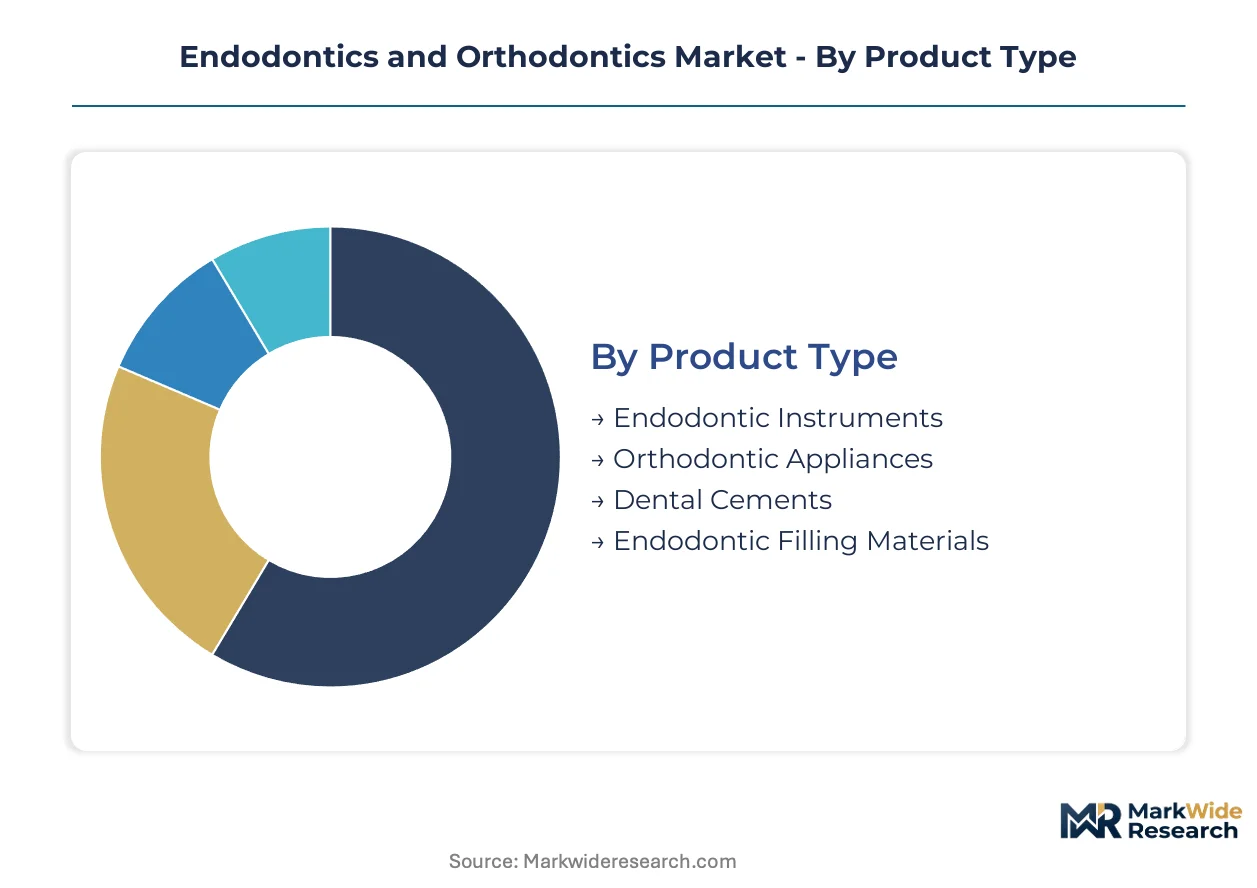
Endodontics and orthodontics segmentation reveals divergent margin structures between mature instrumentation categories and emerging digital workflows. Understanding these divisions helps stakeholders allocate capital across hardware manufacturing, software integration, and service delivery models.
Product Type:
Mature product categories dominate revenue concentration while digital-enabled segments command premium expansion rates.
- Endodontic Instruments:Nickel-titanium rotary files and hand instruments manufactured to ISO 3630 tolerances form the procedural backbone of root canal therapy. Demand concentrates in high-volume dental service organizations across Germany and the United States where chair-time efficiency drives procurement decisions. Raw material sourcing from Jiangsu province processing zones creates cost structure advantages for suppliers with established East Asian supply relationships.
- Orthodontic Appliances:Fixed appliances employing nickel-titanium archwires and medical-grade polymers compete with removable clear aligner systems for malocclusion correction. Suburban North American clinics are expanding fixed appliance service lines as reimbursement frameworks evolve to support independent orthodontic practice models.
- Dental Cements:Bioceramic and resin-based formulations face pricing compression from generic alternatives in restorative adjacencies.
- Endodontic Filling Materials:Gutta-percha and bioceramic sealants complete the obturation workflow with limited differentiation among suppliers.
Endodontic Instruments retains volume leadership; Orthodontic Appliances holds the steepest expansion curve.
Application:
Procedural complexity and reimbursement alignment determine application-level demand distribution across clinical settings.
- Root Canal Treatment:Endodontic therapy addressing pulpal necrosis and periapical pathology employs rotary instrumentation with nickel-titanium alloys to reduce procedural chair time. Demand concentrates in dental clinics across Japan and South Korea where aging demographics expand the addressable patient base for conservative tooth retention procedures.
- Teeth Alignment:Orthodontic correction of malocclusion spans traditional fixed appliances and clear aligner systems with treatment protocols extending 12-36 months. Direct-to-consumer screening platforms are fragmenting patient acquisition channels in suburban United States markets where general dentistry practices unbundle diagnostics from treatment delivery.
- Dental Restoration:Prosthetic rehabilitation following endodontic therapy links to cement and core material selection.
- Preventive Care:Early orthodontic intervention and pulp vitality preservation procedures occupy a smaller revenue share.
Root Canal Treatment anchors revenue stability; Teeth Alignment is climbing the fastest as digital workflows compress treatment timelines.
End User:
Capital intensity and regulatory compliance requirements stratify end-user segments by service integration depth.
- Dentists:General practitioners delivering primary endodontic and orthodontic services operate as the volume foundation for instrument and material suppliers. Solo and small-group practices across France and Italy face interoperability investments for cone beam CT to chairside milling connectivity that strains capital allocation.
- Dental Clinics:Multi-chair facilities and dental service organizations achieve procurement scale advantages with accelerated nickel-titanium alloy adoption cycles. Costa Rica and Mexico manufacturing investments by clear aligner producers target distribution efficiency to clinic networks in the United States.
- Hospitals:Academic medical centers and tertiary facilities handle complex cases requiring implant-anchored orthodontics.
- Orthodontic Practices:Dedicated specialists concentrate premium appliance delivery and same-day aligner fabrication adoption.
Dental Clinics capture volume concentration; Orthodontic Practices show the steepest technology adoption trajectory.
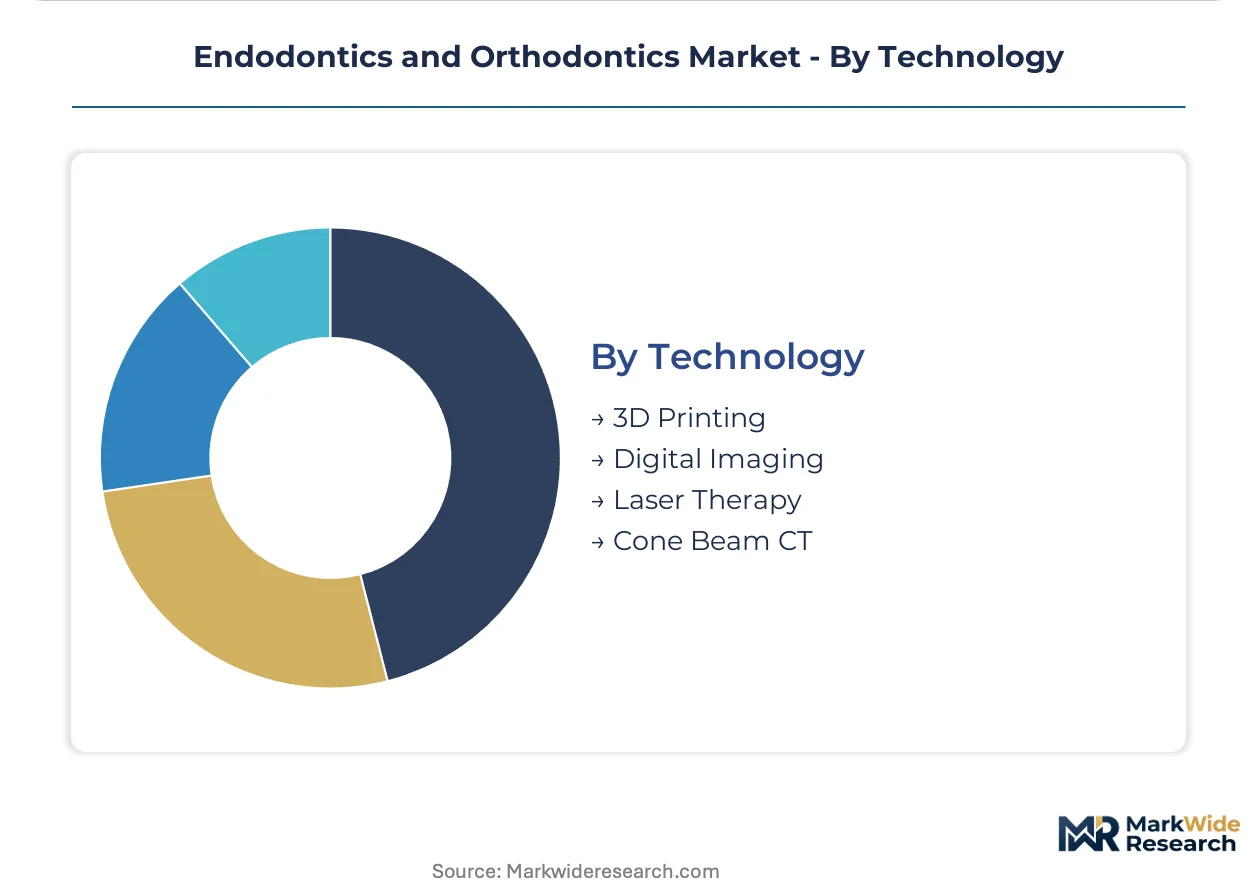
Technology:
Digital integration depth separates capital-intensive infrastructure investments from point-solution software deployments.
- 3D Printing:Chairside additive manufacturing enables same-day aligner fabrication and surgical guide production, hybridizing workflows that previously relied on external dental laboratories. Adoption concentrates in orthodontic practices across Switzerland and the Netherlands where premium positioning justifies equipment depreciation.
- Digital Imaging:Intraoral scanning and cone beam CT systems form the diagnostic backbone for treatment planning software. FDA draft guidance on artificial intelligence-enabled orthodontic planning is extending premarket review timelines for workflow providers targeting United States market entry.
- Laser Therapy:Soft tissue management and photobiomodulation applications occupy niche clinical adoption.
- Cone Beam CT:Three-dimensional radiographic imaging expands across dental clinics seeking comprehensive treatment planning capabilities.
Digital Imaging holds installed base dominance; 3D Printing is gaining share fastest as hardware costs decline and material biocompatibility standards mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearances govern orthodontic appliance market entry in the United States, while divergent regulatory frameworks across Germany, China, Japan, and Switzerland create layered compliance architectures for multinational suppliers.
United States
Suburban dental clinics are expanding orthodontic service lines as reimbursement frameworks evolve to support independent practice models. FDA draft guidance on artificial intelligence-enabled treatment planning software is extending premarket review timelines for digital workflow providers. Clear aligner manufacturing is concentrating in Costa Rica and Mexico following FDA facility registrations, establishing nearshore supply bases with logistics proximity to US distribution networks.
Germany
High-volume dental service organizations across Germany are accelerating procurement cycles for nickel-titanium rotary instrumentation. The EU Medical Device Regulation imposes strengthened clinical evidence requirements on custom-manufactured aligner systems, filtering out marginal competitors. Dentsply Sirona leverages integrated digital workflows spanning cone beam imaging to chairside milling across European orthodontic practices from its regional operational base.
China
Jiangsu province processing zones are reshaping endodontic instrument manufacturing through large-scale titanium alloy concentration. China's NMPA oversees endodontic file biocompatibility testing under GB/T 16886 standards, creating divergent compliance burdens for multinational suppliers seeking market access. Localized certification partnerships are enabling suppliers with established East Asian supply relationships to navigate extended registration timelines.
Japan
Aging demographics are expanding the addressable patient base for conservative tooth retention procedures across dental clinics in Japan and South Korea. METI standards govern medical device quality management systems, creating parallel certification requirements for imported orthodontic appliances. Tokyo and Osaka metropolitan clusters concentrate demand for digital imaging and cone beam CT installations seeking comprehensive treatment planning capabilities.
Switzerland
Premium orthodontic practices across Switzerland and the Netherlands are adopting chairside 3D printing for same-day aligner fabrication where premium positioning justifies equipment depreciation. Swissmedic regulates custom-manufactured dental devices with clinical evidence requirements that align with EU MDR frameworks. The Basel-centered R&D and manufacturing footprint anchors Straumann's implant-anchored orthodontics development for complex malocclusion cases.
Endodontics and Orthodontics Market Vendor Landscape
Capability concentration sits with integrated digital workflow providers; scale advantage sits with diversified dental conglomerates spanning multiple therapeutic categories. The market structures around three tiers: premium appliance specialists, value-tier aligner competitors, and mature instrumentation suppliers facing margin compression. Orthodontic appliance manufacturers compete through FDA 510(k) clearance velocity and EU MDR compliance certification, while endodontic instrument suppliers differentiate through Jiangsu province supply relationships and ISO 3630 tolerance verification. Dominant competitive moves include same-day fabrication workflow integration and nearshore manufacturing capacity expansion.
Within the premium-tier vector, Align Technology and Straumann occupy positions exemplifying integrated digital-to-clinical value capture. Envista competes through its Ormco subsidiary's Spark system positioning against premium alternatives in value-tier clear aligner segments. Dentsply Sirona represents the diversified conglomerate archetype spanning imaging, instrumentation, and workflow software across European and North American markets. These three anchors illustrate how competitive positioning stratifies between pure-play digital specialists, implant-anchored orthodontics developers, and multi-category dental equipment suppliers.
| Leading Market Players |
|---|
| Align Technology |
| Dentsply Sirona |
| Envista |
| 3M Oral Care |
| Ivoclar Vivadent |
| Septodont |
| Straumann |
| Ormco |
| Ultradent Products |
| Others |
Supply Flow & Price Mechanics
Jiangsu province's titanium alloy processing zones concentrate upstream supply for nickel-titanium rotary instruments, anchoring margin pools in endodontic file manufacturing while orthodontic appliance pricing fragments across premium clear aligner and value-tier fixed-wire tiers.
Pricing Analysis
Geographic price spreads separate Swiss and Dutch premium orthodontic practices from suburban North American clinics adopting value-tier alternatives. Three-tier pricing structure across premium, standard, and economy levels differentiates by ISO 3630 certification grade and after-sales calibration support. Cost compression in bioceramic cement categories is intensifying because generic substitution erodes restorative adjacency margins that cross-subsidize orthodontic equipment. Dental service organizations exhibit lowest price sensitivity; solo practitioners in France and Italy face highest capital constraint pressure.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for endodontic instrument suppliers. Raw material sourcing draws from Jiangsu province titanium alloy zones, Costa Rica FDA-registered clear aligner facilities, and Mexican nearshore production hubs. Single-source vulnerability concentrates in medical-grade polymer feedstocks from limited East Asian certified suppliers. Distribution runs through dental service organization procurement networks and independent clinic supply cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dental service organization consolidation across Germany and the United States is shifting buyer power toward volume aggregators, compressing margin capture for undifferentiated instrument suppliers.
For Market Incumbents: Harden ISO 3630 tolerance verification protocols to defend against Jiangsu province cost-advantaged entrants. Deepen backward integration into nickel-titanium wire supply through captive East Asian processing relationships. FDA 510(k) clearance velocity serves as the priority defensive lever against AI-enabled orthodontic planning software disruptors. For New Entrants and Emerging Players: Suburban North American orthodontic service lines present the most penetrable white-space target as reimbursement evolution enables independent practice models. Japan's aging demographic expansion for conservative tooth retention procedures offers secondary entry velocity. Partner with dental clinic networks on cone beam CT-to-chairside milling interoperability bundles to bypass incumbent imaging lock-in. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed dental service organizations consolidating suburban clinic networks across the United States. Five-to-ten year viability hinges on same-day aligner fabrication adoption curves and AI-enabled treatment planning software penetration. Watch FDA draft guidance finalization on orthodontic AI as the inflection signal for digital workflow provider valuations.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Compliance Certification | Strengthened clinical evidence requirements filter marginal aligner competitors from European market access. |
| Nearshore Manufacturing Expansion | Costa Rica and Mexico FDA registrations establish tariff-advantaged supply bases for US distribution. |
| Same-Day Aligner Fabrication Integration | Chairside 3D printing captures value previously lost to external dental laboratories in orthodontic practices. |
| Nickel-Titanium Alloy R&D Partnership | Shape-memory alloy innovations reduce chair time per endodontic procedure in high-volume clinics. |
| AI-Enabled Treatment Planning Development | FDA draft guidance trajectory will reshape competitive barriers for digital orthodontic workflow providers. |
Methodological Framework
A spread of perspectives from endodontic instrument procurement managers, orthodontic practice owners, dental service organization supply chain directors, and biomedical engineers converged on the working assumptions. Primary interviews combined with secondary validation from FDA 510(k) filings, EU MDR submission databases, hospital procurement records, and customs trade data. Bottom-up segment sizing triangulated against top-down macroeconomic indicators anchored the analysis.
Demand-supply-balance framing across product type, application, end user, and technology segmentation dimensions structured the analytical approach over the projection horizon. CAGRs derived from procedure volume elasticity models and equipment replacement cycle analysis. Industry-specific forecast inputs incorporated nickel-titanium alloy adoption curves and clear aligner manufacturing capacity expansion trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by AI-enabled orthodontic software entrants or accelerated Jiangsu province vertical integration would shift outcomes. Regulatory timeline acceleration at FDA or NMPA represents specific revision risk. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Surgical Dental Loupes and Camera Market
Dental Devices
North America Dental Lasers Market
Dental Devices
Dental Splints Market
Dental Devices
Dental Curing Lights Market
Dental Devices
Titanium Dental Implants Market
Dental Devices
Dental Needle Market
Dental Devices
Dental Contouring Market
Dental Devices
Digital Facebow Market
Dental Devices
Intraoral Dental Sensors Market
Dental Devices
Dental Crown Removal Market
Dental Devices
Dental Implants and Abutment Systems Market
Dental Devices
Digital Dental Cameras Market
Dental Devices
Dental Radiometer Market
Dental Devices
RFID-Enabled Dental Printing Market
Dental Devices
Dental Air Polishers Market
Dental Devices
Sleep Apnea Oral Appliances Market