
 United States Dental Implants Market | 2026-2036
United States Dental Implants Market Size, Share, and Industry Trends Forecast 2026-2036
United States Dental Implants Market Intelligence
Prosthetic component revenue is reconfiguring margin distribution across the United States dental implant value chain. Institut Straumann leverages its premium-brand positioning to command higher abutment and crown-connection pricing. Envista Holdings Corporation anchors its competitiveness through broad surgical instrumentation portfolios that lock in recurring consumable sales. Dentsply Sirona competes by integrating digital scanning workflows with its implant planning software, tightening clinician loyalty.
Dental implants are titanium or zirconia fixtures surgically embedded into the jawbone, typically measuring 3-6 mm in diameter and 7-16 mm in length, to serve as artificial roots for prosthetic tooth replacement. Endosteal designs dominate procedure volumes due to established osseointegration reliability and broad surgical training familiarity. Titanium retains the largest material share given decades of clinical documentation and favorable biomechanical properties, though zirconia posts faster growth among metal-allergy-sensitive patient populations. Surgical delivery mode generates the majority of revenue as flap elevation and bone-grading protocols remain standard, while immediate-load protocols expand among experienced practitioners with strong cone-beam computed tomography capabilities.
FDA 510(k) premarket notification requirements govern implant device safety and efficacy submissions, while OSHA bloodborne pathogen standards shape surgical suite operational protocols across dental practices. State dental boards in California, Texas, and New York impose continuing education mandates that influence specialist training depth and technology adoption timelines. Stakeholders must monitor evolving CMS reimbursement determinations for implant-supported prosthetics and state-level scope-of-practice debates that could reshape which provider types capture surgical procedure volumes.
Market Dynamics
Immediate-load protocols and cone-beam computed tomography integration are compressing treatment timelines and redistributing surgical volume toward high-throughput oral surgery centers equipped with advanced imaging infrastructure.
Growth Catalysts
- Aging Demographics:The 65-plus patient cohort in Florida, California, and Texas drives full-arch reconstruction demand as life expectancy extends and tooth retention expectations rise.
- FDA 510(k) Streamlining:Titanium-alloy implant clearances accelerate product cycles, reducing time-to-market for manufacturers with established predicate devices.
- Zirconia Biocompatibility:Metal-allergy-sensitive patients shift toward ceramic fixtures, expanding addressable populations previously excluded from titanium-based solutions.
Market Restraints
- Titanium Feedstock Concentration:Aerospace and medical-grade titanium supply concentrates among a limited supplier base, exposing implant manufacturers to price volatility and allocation constraints.
- Osseointegration Failure Rates:Smoking, diabetes, and osteoporosis populations experience elevated implant failure, restricting candidacy and requiring extensive preoperative screening protocols.
- CMS Reimbursement Gaps:Medicare excludes routine dental services, forcing elderly patients toward out-of-pocket payment or supplemental private coverage with variable implant prosthetic allowances.
Strategic Opportunities
- Underserved Rural Markets:Mississippi, Alabama, and Arkansas exhibit implant penetration gaps of 40-60% below national averages, presenting expansion targets for mobile surgical units and teledentistry-enabled planning.
- Same-Day Prosthetic Integration:Chairside milling systems combined with intraoral scanning enable single-visit definitive restorations, capturing premium pricing from time-sensitive professional patients.
- OSHA Compliance Automation:Bloodborne pathogen documentation and sterilization tracking software create recurring revenue streams for practice management vendors serving multi-location dental service organizations.
Industry Challenges
- CBCT Interpretation Expertise:Cone-beam computed tomography requires specialized radiographic training that general practitioners often lack, creating bottlenecks in treatment planning and surgical referral coordination.
- Prosthetic Component Interoperability:Proprietary connection geometries from major manufacturers lock clinicians into single-source ecosystems, complicating second-source procurement and repair workflows.
- State Scope-of-Practice Variability:Dental boards in New York, Texas, and California impose divergent continuing education mandates and surgical privilege definitions, fragmenting training standardization across multi-state practice groups.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Dental Implants Market |
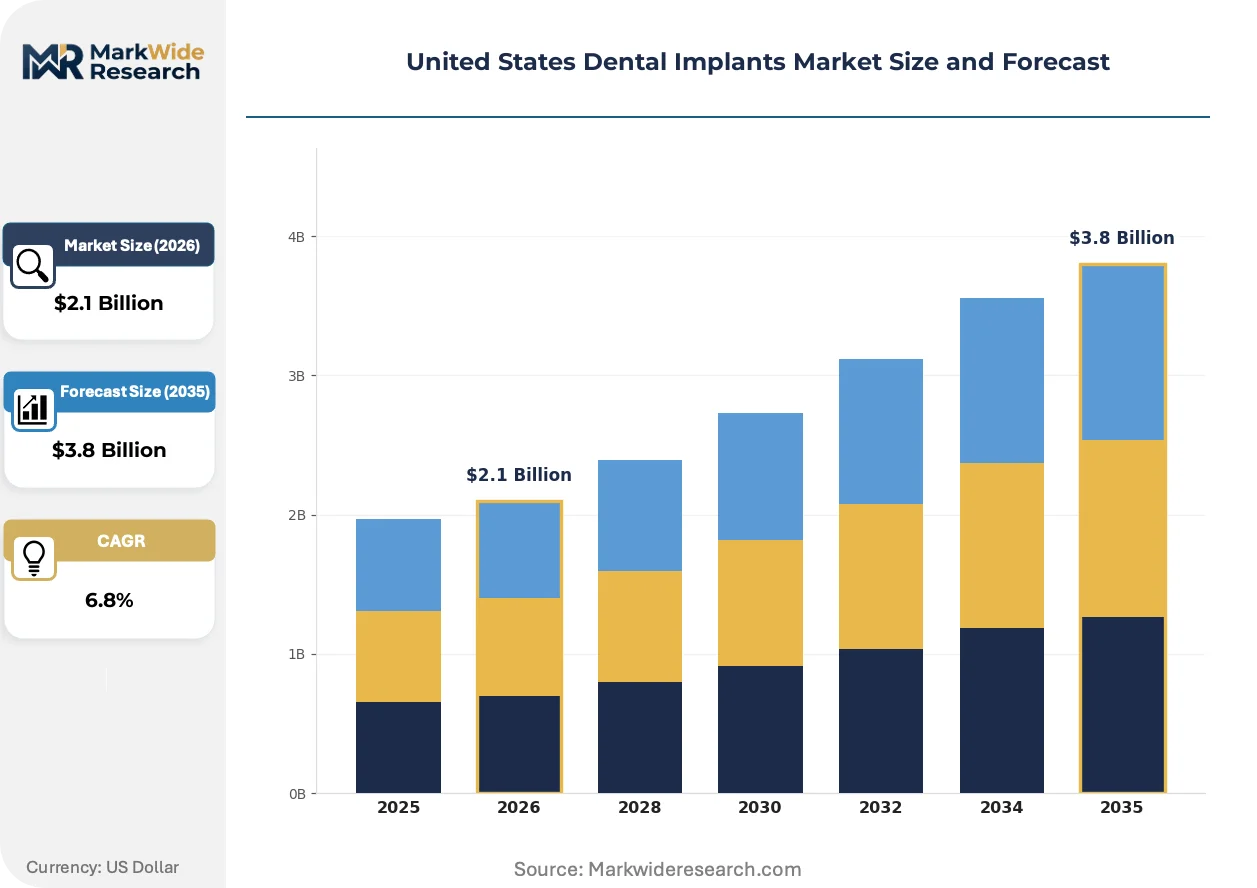
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endosteal, Subperiosteal, Intramucosal, Transosteal Material: Titanium, Zirconia, Stainless Steel, Polymer Delivery Mode: Surgical, Non-Surgical, Immediate Load, Delayed Load End User: Dentists, Oral Surgeons, Clinics, Dental Laboratories |
| Companies Covered | Institut Straumann, Envista Holdings Corporation, Dentsply Sirona, ZimVie, Henry Schein, Nobel Biocare Services AG, BioHorizons, Dentium, OSSTEM Implant, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Dental Implants Market Strategic Shifts & Innovations
Digital workflow integration and patient-specific manufacturing are collapsing the traditional laboratory-mediated implant restoration pipeline, compressing chair time and reordering value capture between clinicians and technology vendors.
Intraoral scanning hardware is digitizing impression capture and model transmission, replacing polyvinyl siloxane and alginate workflows in high-volume practices. Oral surgeons and prosthodontists with established digital infrastructure achieve 40-50% faster turnaround from scan to surgical guide fabrication. This compression is digitizing the traditional dental laboratory intermediary, forcing independent technicians toward design-only service models or direct-to-patient aligner manufacturing.
FDA 510(k) premarket notification requirements for computer-aided design and manufacturing software modules are tightening validation standards for implant planning algorithms. Manufacturers must demonstrate geometric accuracy and biocompatibility of patient-specific surgical guides. Small software vendors lacking quality system infrastructure face exclusion, concentrating innovation among established device companies with integrated regulatory affairs capabilities.
Subscription-based surgical guide procurement is displacing capital-intensive in-house milling investments among solo practitioners and small group practices. Dental service organizations negotiate enterprise pricing with design centers, while independent dentists access per-case guide fabrication through cloud-based planning portals. This shift concentrates most visibly in metropolitan California and Texas markets where practice consolidation has advanced furthest.
United States Dental Implants Market Segmentation
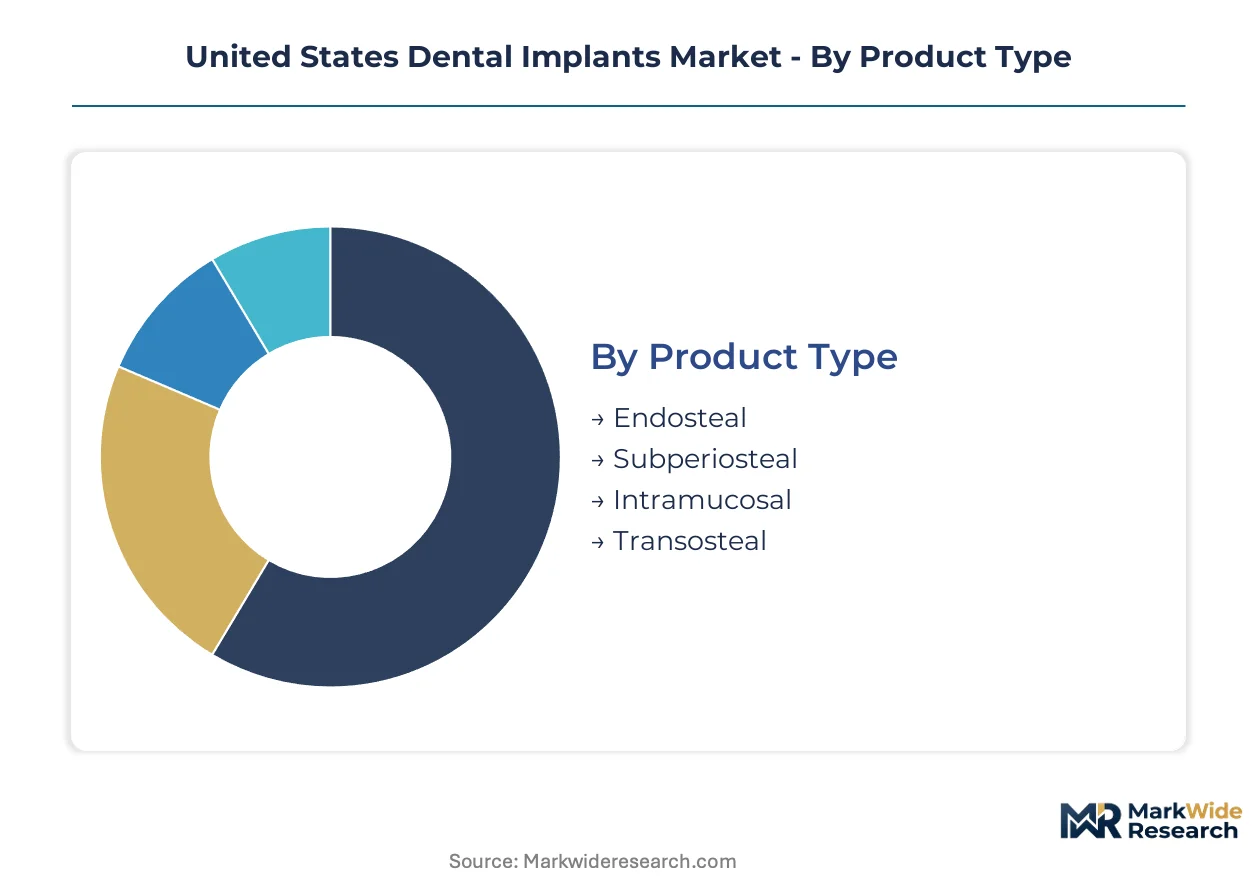
Segmentation in the United States dental implants market exposes divergent margin profiles and service intensity requirements across product, material, delivery, and end-user dimensions. Manufacturers calibrate inventory depth and field support teams based on these structural differences.
Product Type:
After-sales service intensity varies sharply by implant design complexity, with multi-component systems demanding sustained technical support versus single-fixture alternatives.
- Endosteal:Screw-shaped or cylindrical fixtures placed directly into the jawbone, typically 3-6 mm in diameter with threaded or press-fit surfaces. Demand concentrates among oral surgeons in Florida and California performing full-arch reconstructions, driven by aging patient expectations for permanent tooth replacement.
- Subperiosteal:Custom metal frameworks resting atop the jawbone beneath the gum tissue, requiring extensive preoperative imaging and laboratory coordination. These address severe bone resorption cases in Texas metropolitan markets where CBCT-equipped surgical centers can execute complex custom fabrication workflows.
- Intramucosal:Attachments embedded within soft tissue rather than bone, serving specialized overdenture applications with reduced surgical invasiveness.
- Transosteal:Penetrating fixtures extending through the entire jawbone thickness, reserved for extreme atrophy cases requiring maximal stability.
By volume, Endosteal leads. By growth pace, Subperiosteal is expanding most quickly as complex reconstruction demand rises.
Material:
Cost tier stratification separates premium biocompatible ceramics from commodity metal alternatives, with reimbursement sensitivity shaping procurement patterns across patient populations.
- Titanium:Commercially pure or alloyed fixtures leveraging decades of osseointegration documentation and favorable strength-to-weight ratios. Demand clusters in high-volume California dental service organizations where standardization and supplier consolidation drive procurement economics.
- Zirconia:Yttria-stabilized tetragonal zirconia polycrystalline ceramics offering tooth-colored aesthetics and hypoallergenic properties. Growth accelerates among metal-sensitive patients in Florida aesthetic-focused practices where premium pricing tolerance supports ceramic fixture adoption.
- Stainless Steel:Lower-cost alternatives for temporary or provisional applications with limited long-term osseointegration requirements.
- Polymer:Emerging resorbable or permanent polymeric options targeting specific biocompatibility niches and cost-sensitive market segments.
Titanium captures the largest revenue share. Zirconia posts the steepest expansion trajectory as aesthetic and biocompatibility preferences intensify.
Delivery Mode:
Application urgency divides the market between scheduled staged procedures and accelerated same-day protocols, with capital equipment requirements determining practitioner accessibility.
- Surgical:Traditional flap elevation and osteotomy preparation under local or general anesthesia, requiring dedicated surgical suites and sterilization infrastructure. Dominates Mississippi and Alabama rural markets where immediate-load infrastructure remains underdeveloped.
- Non-Surgical:Mini-implant or transgingival approaches minimizing tissue disruption, expanding among general dentists in Texas seeking to expand service scope without full surgical certification.
- Immediate Load:Provisional prosthesis placement within 48 hours of implant insertion, demanding precise primary stability and advanced CBCT planning capabilities.
- Delayed Load:Conventional two-stage healing protocols allowing extended osseointegration before functional loading, standard for compromised bone quality cases.
Surgical delivery generates the highest absolute procedure volume. Immediate Load is gaining share fastest as imaging infrastructure penetrates metropolitan markets.
End User:
Customer type dictates purchasing authority and technical support expectations, with specialists commanding premium product configurations versus generalist volume procurement.
- Oral Surgeons:Maxillofacial specialists performing complex bone grafting and full-arch reconstructions, representing the most technically demanding customer segment with highest per-case product consumption.
- Dentists:General practitioners and prosthodontists handling single-tooth and straightforward multi-unit cases, driving standardized product volume through group purchasing organizations.
- Clinics:Federally qualified health centers and community health facilities serving Medicaid-eligible populations with constrained reimbursement environments.
- Dental Laboratories:Independent and corporate fabrication centers procuring components for outsourced restoration manufacturing, increasingly bypassed by chairside digital workflows.
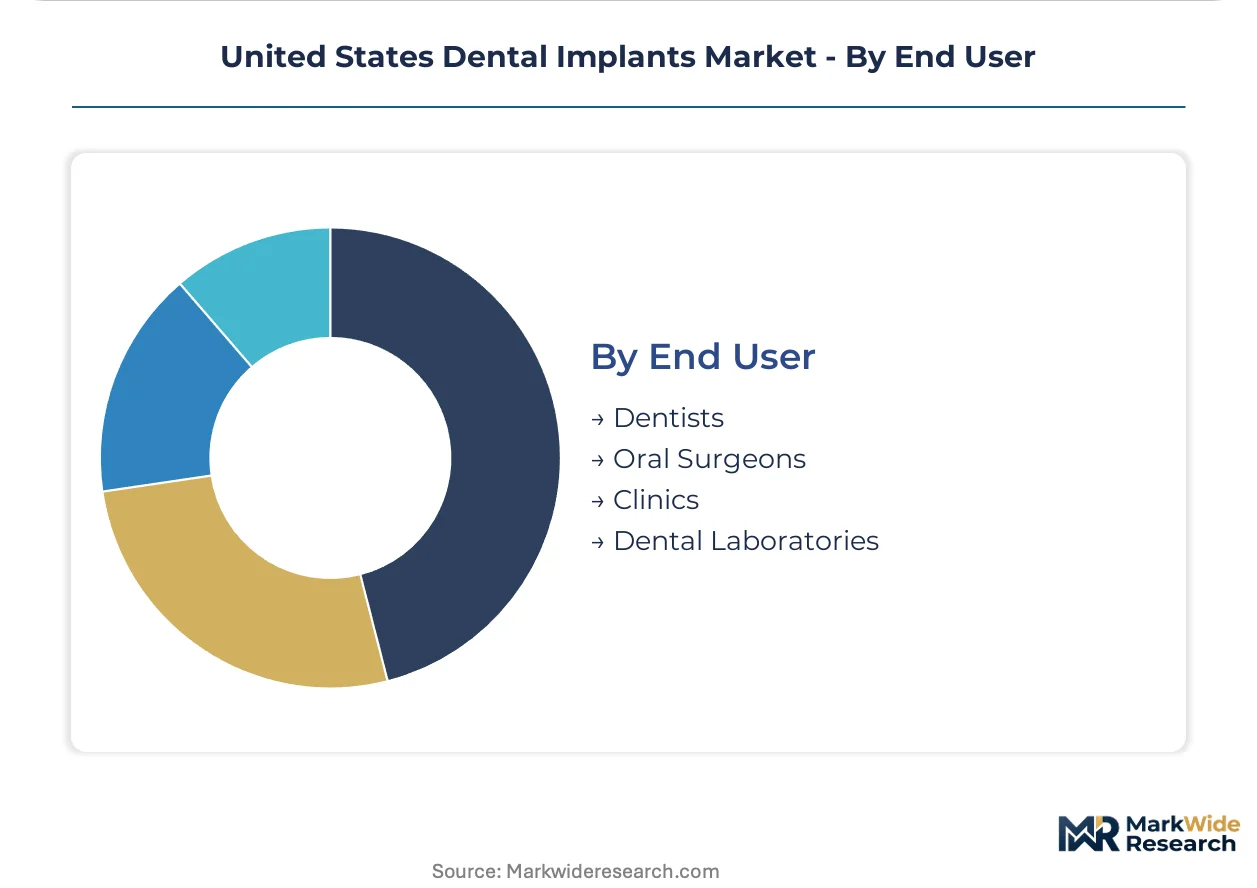
Dentists account for the largest procedure volume base. Oral Surgeons are climbing the fastest as scope-of-practice boundaries shift and complex case referrals concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Titanium-alloy supply chains and oral surgery center density concentrate implant procedure volumes in three coastal states, while rural markets exhibit substantial penetration gaps that mobile surgical units and teledentistry platforms now target.
California
Los Angeles and San Francisco metropolitan dental service organizations drive standardized procurement of titanium fixtures through consolidated group purchasing agreements. FDA 510(k) clearances for immediate-load protocols accelerate faster here due to proximity to regulatory consultants and predicate device archives. San Diego's oral surgery corridor specializes in full-arch reconstructions for aging coastal retirees with premium pricing tolerance.
Texas
Houston and Dallas-Fort Worth surgical centers equipped with cone-beam computed tomography infrastructure capture complex subperiosteal and bone-grafting cases from across the Southwest. State dental board continuing education mandates for radiographic interpretation deepen specialist training pipelines. Austin's emerging dental technology cluster attracts chairside milling and intraoral scanning vendors seeking proximity to high-volume group practices.
Florida
The 65-plus demographic concentration in Miami, Tampa, and Orlando generates disproportionate demand for zirconia fixtures among metal-allergy-sensitive aesthetic-focused patients. Medicare Advantage supplemental plans with variable implant prosthetic allowances create patchwork reimbursement landscapes across counties. Jacksonville's oral surgery networks serve as referral hubs for Georgia and Alabama patients seeking immediate-load capabilities unavailable locally.
New York
Manhattan prosthodontists and oral surgeons command premium pricing for same-day prosthetic integration using chairside milling systems. State scope-of-practice regulations impose stricter surgical privilege definitions than neighboring states, concentrating complex procedures within hospital-affiliated dental departments. Buffalo and Rochester markets exhibit lower penetration but higher growth potential as upstate dental boards expand teledentistry-enabled planning permissions.
Illinois
Chicago's dental laboratory infrastructure traditionally mediated restoration workflows, though digitization now compresses this intermediary role. Midwest implant distributors maintain deeper inventory positions here to serve satellite markets in Wisconsin and Indiana with limited local surgical capacity. Peoria and Springfield rural networks represent expansion targets for mobile CBCT-equipped surgical units addressing 40-60% penetration gaps below national averages.
United States Dental Implants Market Key Industry Players
Premium-brand specialists and diversified dental conglomerates split the market into distinct competitive spheres with divergent margin capture mechanisms. Three archetypes dominate: integrated digital workflow providers bundling software with hardware, component specialists commanding premium pricing on abutments and connection geometries, and broad-line distributors leveraging surgical instrumentation portfolios to lock in recurring consumable sales. Consolidation pressure intensifies as dental service organizations negotiate enterprise pricing and independent practitioners migrate toward subscription-based surgical guide procurement.
Within the premium-brand tier, Institut Straumann and Nobel Biocare Services AG exemplify positioning built on decades of clinical documentation and proprietary connection geometries that lock clinicians into single-source ecosystems. Envista Holdings Corporation and Dentsply Sirona represent the diversified conglomerate archetype, competing through breadth of surgical instrumentation and digital scanning integration rather than standalone implant pricing. ZimVie occupies a mid-market position between these poles, while Henry Schein's distribution dominance anchors the supply-chain vector through practice-level inventory management and multi-location dental service organization contracts.
| Leading Market Players |
|---|
| Institut Straumann |
| Envista Holdings Corporation |
| Dentsply Sirona |
| ZimVie |
| Henry Schein |
| Nobel Biocare Services AG |
| BioHorizons |
| Dentium |
| OSSTEM Implant |
| Others |
Cost & Logistics Intelligence
The Port of Long Beach container corridor governs inbound freight economics for titanium-alloy implant components, concentrating landed costs among West Coast distributors and amplifying price differentiation between CBCT-equipped surgical centers and rural general practices lacking volume leverage.
Pricing Analysis
FDA 510(k) premarket notification dictates the pricing tier structure across the United States dental implants market. Three-tier pricing separates premium zirconia fixtures from standard titanium-alloy systems and economy-grade provisional components, with certification grade and after-sales service bundling as primary differentiation drivers. Cost compression in the economy tier is intensifying as dental service organizations consolidate procurement through group purchasing organizations. Rural independent practitioners exhibit highest price sensitivity, while metropolitan oral surgery centers demonstrate lowest sensitivity due to immediate-load premium pricing capture.
Supply Chain Analysis
Export control restrictions on precision milling equipment and electron-beam melting systems constrain domestic manufacturing scale-up for patient-specific surgical guides. Supply concentrates in Switzerland for premium-brand fixtures, South Korea for mid-market titanium blanks, and China for surgical instrumentation components. The United States market draws from aerospace-grade titanium feedstock, yttria-stabilized zirconia powders, and cobalt-chrome abutment alloys. Single-source vulnerability concentrates in Swiss implant connection geometries. Distribution runs through Henry Schein and Patterson Dental's multi-location inventory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of CBCT-interpretation expertise among general practitioners concentrates surgical referral flows and creates asymmetric margin capture between imaging-equipped specialists and laboratory-dependent generalists.
For Market Incumbents: Entrench proprietary connection geometries through expanded surgical guide subscription offerings that lock clinicians into ecosystem-dependent workflows. Deepen backward integration into titanium feedstock processing to buffer aerospace allocation volatility. Prioritize FDA 510(k) predicate device archives as competitive moats against emerging ceramic fixture entrants. For New Entrants and Emerging Players: Establish a beachhead in Mississippi and Alabama rural markets where implant penetration gaps exceed 40% below national averages. Target mobile surgical unit partnerships as distribution channels bypassing established dental service organization procurement blocks. Lead with teledentistry-enabled planning software to circumvent capital-intensive CBCT infrastructure requirements. For Investors and Strategic Acquirers: Chairside milling system vendors with cloud-based surgical guide portals represent the most defensible acquisition archetype as subscription revenue displaces capital equipment sales. Long-term viability hinges on software recurring revenue multiples rather than hardware depreciation cycles. Watch for state dental board teledentistry permission expansions as inflection indicators for addressable market growth.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acceleration | Predicate device archives at FDA headquarters shorten titanium-alloy implant time-to-market for established manufacturers. |
| Subscription Surgical Guide Procurement | Cloud-based planning portals displace capital-intensive in-house milling among solo practitioners and small group practices. |
| Backward Integration into Titanium Processing | In-house feedstock conversion buffers implant manufacturers against aerospace allocation constraints and spot price volatility. |
| Teledentistry Platform Expansion | State dental board permission expansions in New York and Illinois enable remote treatment planning for underserved rural markets. |
| OSHA Compliance Automation | Bloodborne pathogen documentation software creates recurring revenue streams for practice management vendors serving multi-location dental service organizations. |
Research Approach
Operator-level perspectives from oral surgeons, prosthodontists, dental service organization procurement directors, and independent laboratory technicians anchored the qualitative base for this study. Primary interviews with CBCT equipment specialists and GPO contracts managers combined with secondary validation from FDA 510(k) clearance databases, CMS reimbursement determinations, and state dental board continuing education mandates. Bottom-up procedure volume estimates triangulated against top-down manufacturer shipment data.
Scenario-bracketing around immediate-load adoption curves and dental service organization consolidation pace shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material composition, delivery mode, and end-user category, with additional stratification by metropolitan versus rural practice density. CAGRs derived from logistic diffusion curves for digital workflow penetration and linear extrapolation of aging demographic demand. Forecast inputs incorporated cone-beam computed tomography equipment installation rates and state-level scope-of-practice regulatory trajectories.
Sensitivities concentrate around Medicare Advantage reimbursement determinations for implant-supported prosthetics and titanium feedstock allocation disruptions from aerospace demand spikes. Forecasts reflect assumptions regarding osseointegration protocol standardization and FDA software validation tightening for patient-specific surgical guides. Material shifts in CMS dental coverage expansion or state-level teledentistry permissions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Global Dental Crowns and Bridges Market
Dental Devices
Europe CBCT Dental Imaging Market
Dental Devices
Dental Impression System Market
Dental Devices
Acrylic Teeth Market
Dental Devices
Dental Chair Market
Dental Devices
Dental Apex Locator Market
Dental Devices
Digital Dental Cameras Market
Dental Devices
Nano Dentistry Market
Dental Devices
Dental Caries Market
Dental Devices
North America Dental Lab Market
Dental Devices
Asia Pacific Dental Market
Dental Devices
Global Dental Restorative Market
Dental Devices
Subperiosteal Dental Implants Market
Dental Devices
Dental CAD Market
Dental Devices
Europe Dental Aligners Market
Dental Devices
Intraoral Dental Sensors Market