
 Turkey Medical Tourism Market | 2026-2036
Turkey Medical Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Turkey Medical Tourism Market Analytics
Buyer concentration among European and Middle Eastern patients is shifting from dispersed individual bookings toward organized referral networks and employer-sponsored health travel programs. Acibadem Healthcare Group leverages its JCI-accredited multi-site network to capture recurring referral flows from Gulf state insurers. Memorial Healthcare Group anchors premium positioning through its integrated oncology and robotic surgery centers. Medicana Health Group competes on volume accessibility across Anatolian cities beyond Istanbul.
Turkey medical tourism encompasses cross-border patient travel for elective and therapeutic procedures, spanning surgical intervention, diagnostic services, and post-treatment rehabilitation within accredited healthcare facilities. The sector operates through ISO-certified clinical pathways, JCI hospital standards, and Ministry of Health licensing frameworks that govern sterilization protocols, physician credentialing, and medical device traceability. Cosmetic surgery and dental care command the largest treatment-type revenue pools due to price arbitrage against Western European benchmarks. All-inclusive packages generate superior margin capture by bundling accommodation, transfers, and follow-up care into single-price offerings. Private hospitals dominate facility-type throughput, while specialized clinics concentrate high-complexity niches such as fertility treatment and orthopedics.
Turkey's Ministry of Health enforces facility licensing and physician certification requirements that determine market access for international-facing providers. JCI accreditation and ISO 15189 laboratory standards shape patient trust and insurer reimbursement eligibility for outbound health travelers. Stakeholders must monitor evolving EU patient-mobility directives and Gulf Cooperation Council insurance portability rules that could redirect referral flows toward competing destinations.
Market Dynamics
European patient mobility directives and Gulf Cooperation Council insurance portability rules are redirecting referral flows toward organized health travel networks, compressing traditional individual booking channels into structured B2B procurement relationships.
Growth Catalysts
- JCI Accreditation Standards:Turkey's Ministry of Health licensing framework mandates sterilization protocols and physician credentialing that satisfy Gulf state insurer requirements, unlocking recurring referral flows from employer-sponsored health travel programs.
- Price Arbitrage in Cosmetic Surgery:Western European patients pursue hair transplantation and dental implants at facilities charging 60-70% below German and UK benchmarks, sustaining volume despite currency fluctuations.
- Istanbul Super-Specialty Clusters:Concentrated hospital infrastructure along the Bosphorus corridor integrates robotic surgery centers with dedicated recovery residences, reducing patient friction and extending average length of stay.
Market Restraints
- Input Cost Volatility in Medical Devices:Orthopedic implant and aesthetic material imports denominated in euros and dollars expose margin structures to lira depreciation, forcing frequent package repricing.
- Supply Concentration in Diagnostic Imaging:MRI and CT scanner maintenance contracts cluster with three multinational OEM service providers, creating single-source vulnerability for high-throughput facilities.
- EU Patient Mobility Directive Friction:Cross-border healthcare reimbursement claim processing delays under Directive 2011/24/EU deter price-sensitive patients from completing booking funnels.
Strategic Opportunities
- Anatolian City Expansion:Underpenetrated demand in Izmir, Antalya, and Bursa supports greenfield JCI-accredited facilities targeting domestic health travelers and Balkan inbound segments.
- Telemedicine Follow-Up Integration:Remote post-operative monitoring platforms converge with ISO 27001 data security standards, enabling extended care relationships beyond physical discharge.
- Wellness Tourism Bundling:Thermal spa and medical rehabilitation combinations in Afyon and Pamukkale attract extended-stay German retirees seeking covered physical therapy.
Industry Challenges
- Physician Credential Verification:Ministry of Health specialist certification recognition delays for foreign-trained surgeons constrain staffing flexibility during peak seasonal demand.
- Legacy PMS Integration:Hospital information systems at mid-tier Anatolian facilities require capital-intensive upgrades to interface with international insurer pre-authorization portals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turkey Medical Tourism Market |
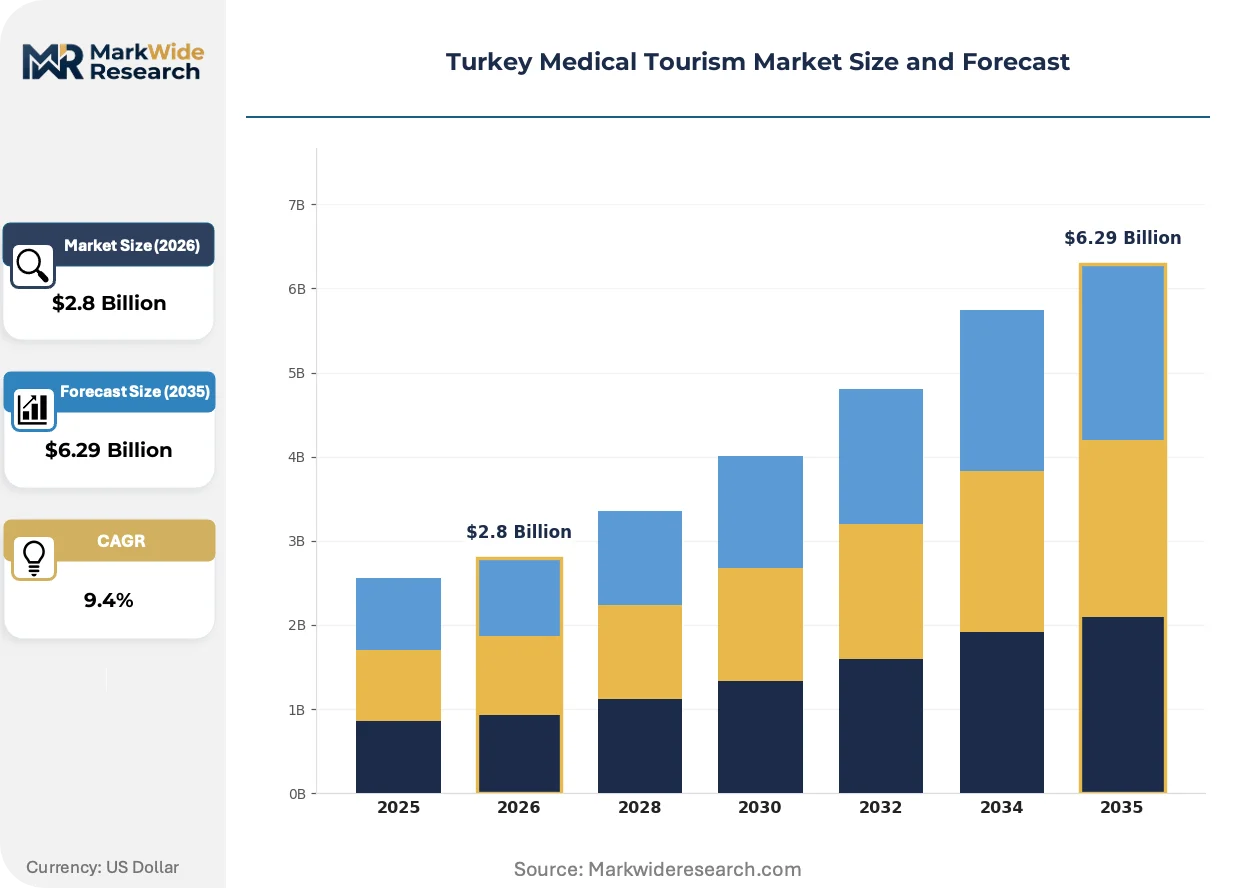
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Cosmetic Surgery, Dental Care, Orthopedic Surgery, Fertility Treatment Service Package: All-Inclusive Packages, Individual Treatments, Post-Operative Care, Transportation Services Patient Demographics: International Tourists, Domestic Patients, Age Group, Wellness Seekers Facility Type: Private Hospitals, Specialized Clinics, Medical Resorts, Rehabilitation Centers |
| Companies Covered | Acibadem Healthcare Group, Memorial Healthcare Group, Medicana Health Group, Florence Nightingale Hospitals, Medical Park Hospitals Group, Liv Hospital, Anadolu Medical Center, Remed Health, Euro Health Medical Tourism, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turkey Medical Tourism Market Evolving Landscape
Digital patient journey orchestration and robotic surgical platforms are compressing treatment timelines while elevating outcome transparency expectations among European and Gulf state buyers.
Robotic-assisted surgery systems are integrating into Istanbul oncology and orthopedic centers, enabling sub-millimeter precision for spinal fusion and prostate procedures. German and Dutch insurer panels now mandate robotic capability for high-complexity case referrals, forcing facility capex commitments. This technology is integrating pre-operative planning software with intraoperative navigation, compressing average hospitalization from five days to under 48 hours for select procedures.
Turkey's Ministry of Health enforces ISO 15189 laboratory standards and medical device traceability requirements that determine international insurer eligibility. The 2023 update to sterilization protocol audits introduced unannounced inspection cycles, accelerating compliance investments across Anatolian provinces. Private hospital groups in Ankara and Izmir have responded by centralizing pathology services to capture economies of scale in accreditation maintenance.
Employer-sponsored health travel programs are displacing individual direct bookings as the dominant procurement channel for UK and Gulf corporate policyholders. Human resources departments negotiate annual case quotas with JCI-accredited networks, unbundling traditional travel agency intermediaries. This concentration is most visible among London-based financial services firms and Riyadh construction conglomerates seeking predictable cost caps for elective procedures.
Turkey Medical Tourism Market Segmentation
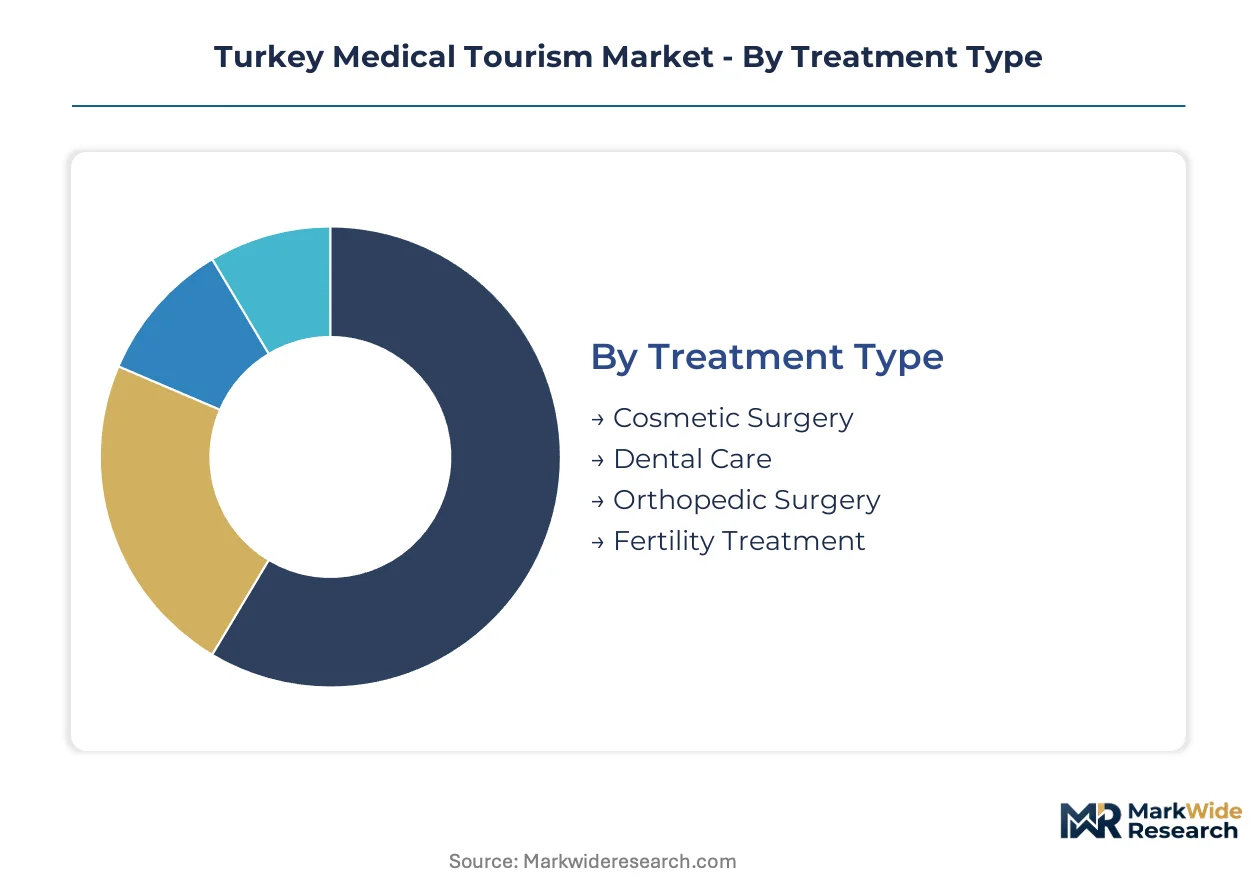
Medical tourism in Turkey fragments across treatment complexity, service bundling, patient origin, and facility infrastructure. Each dimension shapes procurement patterns, margin structures, and insurer accreditation requirements differently.
Treatment Type:
Volume concentrates in high-frequency, standardized procedures while premium pricing attaches to complex interventions requiring extended recovery.
- Cosmetic Surgery:Hair transplantation, rhinoplasty, and liposuction dominate inbound volume from Western Europe. German and UK patients drive demand through price arbitrage against domestic benchmarks, with Istanbul facilities capturing recurring flows via JCI-accredited surgical suites.
- Dental Care:Implantology and full-mouth reconstruction generate superior margin capture through same-day CAD/CAM milling capabilities. Antalya and Izmir clinics attract extended-stay retirees seeking bundled dental and thermal wellness combinations.
- Orthopedic Surgery:Robotic-assisted joint replacement concentrates in Ankara and Istanbul super-specialty centers. Gulf state insurer panels mandate specific implant traceability standards.
- Fertility Treatment:IVF and genetic screening services cluster in private hospital reproductive medicine departments. Domestic patients combine with inbound demand from Balkan and Central Asian markets.
Mature deployment sits with Cosmetic Surgery. Newer deployment is concentrated in Fertility Treatment.
Service Package:
Procurement patterns diverge between structured corporate programs and individual direct bookings, with bundling intensity determining margin capture.
- All-Inclusive Packages:Single-price offerings integrate accommodation, transfers, surgery, and follow-up care. Employer-sponsored health travel programs from London financial services firms and Riyadh construction conglomerates negotiate annual case quotas exclusively through this format.
- Individual Treatments:Unbundled procedure pricing attracts price-sensitive European patients booking directly through clinic portals. Currency volatility in lira-denominated quotes creates frequent repricing cycles.
- Post-Operative Care:Extended recovery residence packages attach to orthopedic and cosmetic procedures. Dedicated facilities along the Bosphorus corridor reduce patient friction.
- Transportation Services:Medical concierge and air ambulance coordination serve high-complexity cases from Gulf Cooperation Council markets.
Corporate procurement gravitates toward All-Inclusive Packages. Direct consumer booking persists through Individual Treatments.
Patient Demographics:
Origin and motivation shape average spend, length of stay, and referral channel economics.
- International Tourists:European and Middle Eastern patients seeking elective procedures generate highest per-case revenue. German retirees and UK cosmetic surgery seekers dominate volume.
- Domestic Patients:Anatolian city residents travel to Istanbul and Ankara for procedures unavailable in provincial facilities. Public insurance portability limitations constrain this segment.
- Age Group:Working-age patients concentrate in cosmetic and fertility treatments. Retiree segments drive orthopedic and dental demand with extended recovery stays.
- Wellness Seekers:Thermal spa and medical rehabilitation combinations in Afyon and Pamukkale attract German and Austrian extended-stay visitors.
International Tourists anchor premium positioning. Domestic Patients represent expanding volume as provincial infrastructure matures.
Facility Type:
Accreditation tier and capital intensity determine insurer panel eligibility and case complexity handling.
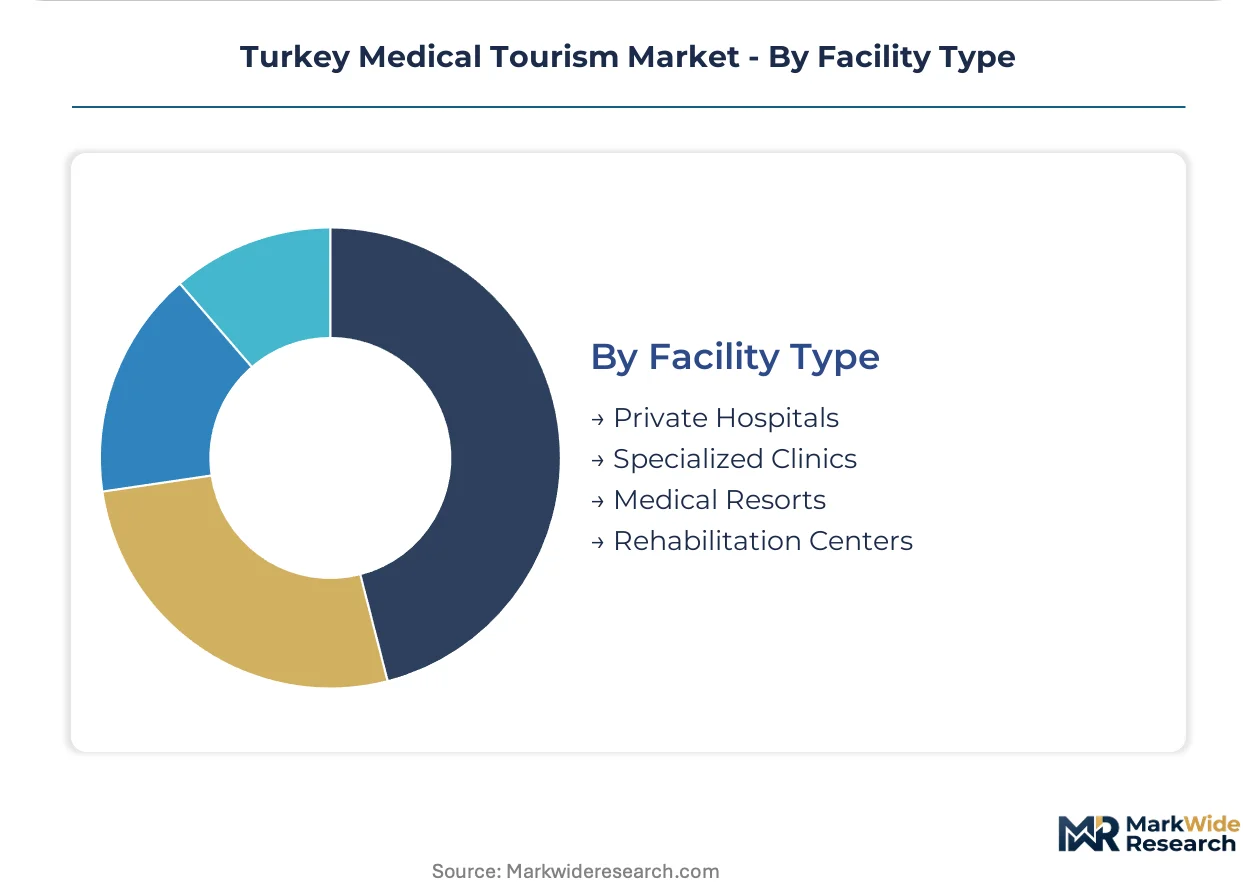
- Private Hospitals:JCI-accredited multi-site networks capture recurring referral flows from Gulf state insurers. Robotic surgery capability and integrated pathology services differentiate premium positioning.
- Specialized Clinics:High-complexity niches such as fertility treatment and hair transplantation concentrate in dedicated facilities. ISO 15189 laboratory standards govern eligibility for international patient acceptance.
- Medical Resorts:Thermal spa and rehabilitation combinations in Aegean and Central Anatolian regions serve extended-stay German retirees.
- Rehabilitation Centers:Post-operative physical therapy facilities cluster near super-specialty hospital infrastructure in Istanbul and Ankara.
Private Hospitals dominate throughput volume. Specialized Clinics are gaining share fastest in high-margin niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European patients concentrate demand for cosmetic and dental procedures in Turkey's accredited facilities, while Gulf state insurer networks redirect referral flows through structured procurement channels rather than individual bookings.
Istanbul
Hair transplantation and rhinoplasty patients from Germany and the UK drive volume into JCI-accredited surgical suites along the Bosphorus corridor. Turkey's Ministry of Health licensing framework mandates sterilization protocols that satisfy Gulf state requirements. Super-specialty hospital clusters integrate robotic surgery centers with dedicated recovery residences, reducing patient friction and extending average length of stay.
Ankara
Orthopedic and oncology cases from Central Asian and Balkan markets concentrate in capital-based facilities with advanced diagnostic imaging capabilities. The Ministry of Health enforces ISO 15189 laboratory standards that determine international insurer eligibility. Robotic-assisted joint replacement centers anchor premium positioning through sub-millimeter precision capabilities for spinal fusion procedures.
Antalya
Extended-stay German retirees seeking dental implants and thermal wellness combinations sustain year-round demand in Mediterranean coastal facilities. EU patient mobility directives create reimbursement friction that structured employer-sponsored programs circumvent through direct insurer negotiations. CAD/CAM milling capabilities enable same-day full-mouth reconstruction for bundled dental and spa packages.
Izmir
Fertility treatment and reproductive medicine patients from Balkan and Middle Eastern markets access ISO-certified laboratory services in Aegean coastal clinics. Unannounced sterilization protocol audits introduced in 2023 accelerate compliance investments across provincial facilities. Private hospital groups centralize pathology services to capture economies of scale in accreditation maintenance.
Bursa
Underpenetrated demand from domestic health travelers and emerging Balkan inbound segments supports greenfield JCI-accredited facility development. Public insurance portability limitations constrain domestic segment growth as provincial infrastructure matures. Thermal spa and medical rehabilitation combinations attract extended-stay visitors seeking covered physical therapy beyond Istanbul's saturated market.
Turkey Medical Tourism Market Competitive Landscape
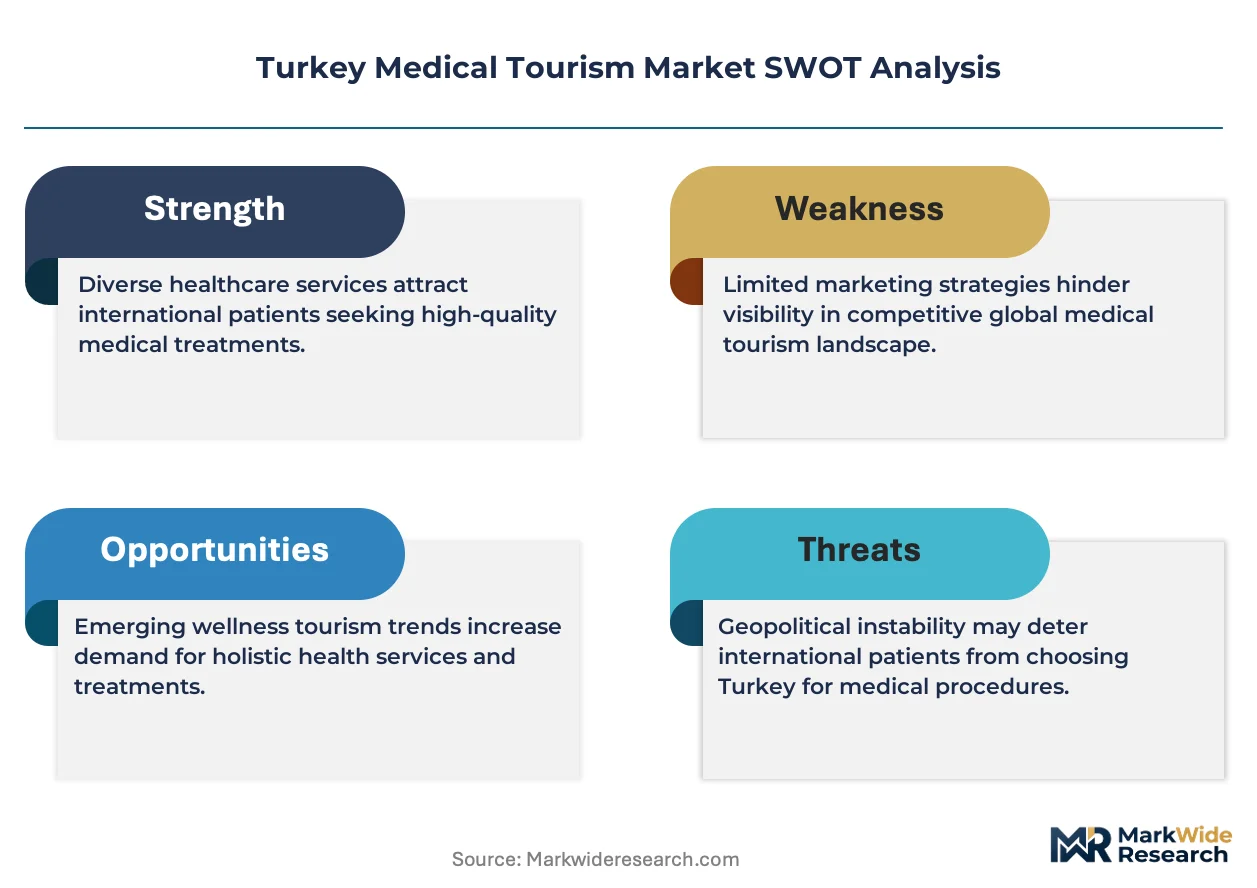
Istanbul-based hospital groups anchor the premium tier; Anatolian city specialists hold volume accessibility positions. The vendor base concentrates around three multi-site networks with JCI accreditation, while mid-tier provincial facilities fragment across uncoordinated individual booking channels. Strategic archetypes include integrated super-specialty anchors, Anatolian volume players, and niche high-complexity clinics. Competitive moves center on robotic surgery capability acquisition and telemedicine follow-up platform integration.
Within the integrated network tier, Acibadem Healthcare Group and Memorial Healthcare Group exemplify multi-site JCI-accredited positioning, while Medicana Health Group occupies a volume-accessibility archetype across Anatolian cities beyond Istanbul. These three entities represent contrasting strategic postures: super-specialty premium anchoring, robotic surgery capability leadership, and geographic reach expansion into underpenetrated provincial demand.
| Leading Market Players |
|---|
| Acibadem Healthcare Group |
| Memorial Healthcare Group |
| Medicana Health Group |
| Florence Nightingale Hospitals |
| Medical Park Hospitals Group |
| Liv Hospital |
| Anadolu Medical Center |
| Remed Health |
| Euro Health Medical Tourism |
| Others |
Value Network & Pricing Analysis
Orthopedic implant and aesthetic material imports denominated in euros and dollars feed through JCI-accredited hospital networks into tiered service packages, with lira depreciation forcing frequent repricing cycles across premium surgical suites and volume-accessible Anatolian facilities.
Pricing Analysis
High-frequency cosmetic and dental procedures capture volume through 60-70% discounts against German benchmarks, while robotic-assisted orthopedic and oncology interventions command premium positioning. Price differentiation hinges on JCI accreditation status and bundled recovery residence inclusion. Cost compression in mid-tier facilities intensifies because euro-denominated device imports erode lira-based margins. Individual direct-booking patients from Western Europe exhibit highest price sensitivity; employer-sponsored Gulf state programs show lowest sensitivity due to annual case quota negotiations.
Supply Chain Analysis
Robotic surgical platform supply rests on German and American precision engineering manufacturers, with maintenance contracts clustering among three multinational OEM service providers. Diagnostic imaging equipment draws from Japanese and South Korean producers, while aesthetic materials and orthopedic implants source from Swiss and American suppliers. Single-source vulnerability in MRI and CT scanner servicing creates operational risk for high-throughput Istanbul facilities. Distribution runs through JCI-accredited hospital procurement departments and direct insurer network agreements, bypassing traditional travel agency intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Turkey's Ministry of Health licensing framework and unannounced sterilization audit protocols erect a cost-of-compliance barrier that favors capital-rich incumbents with centralized pathology services and multi-site accreditation maintenance capabilities.
For Market Incumbents: To counter input cost volatility in euro-denominated medical devices, deepen backward integration into captive supply agreements with implant manufacturers and expand robotic surgery capability acquisition to satisfy German and Dutch insurer panel mandates for high-complexity referrals. For New Entrants and Emerging Players: Balkan inbound health travelers seeking fertility treatment and reproductive medicine represent the most penetrable buyer archetype, accessible through ISO 15189-certified laboratory investments in Izmir and Bursa greenfield developments with telemedicine follow-up integration. For Investors and Strategic Acquirers: Employer-sponsored health travel program adoption by London financial services firms is the leading indicator that structured B2B procurement channels will displace individual bookings, signaling long-term viability for JCI-accredited networks with integrated super-specialty clusters and extended recovery infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Surgery Capability Acquisition | German and Dutch insurer panels now mandate robotic systems for high-complexity orthopedic and oncology case referrals. |
| Telemedicine Follow-Up Platform Integration | ISO 27001-compliant remote monitoring extends patient relationships beyond physical discharge and reduces readmission liability. |
| JCI Accreditation Maintenance Investment | Unannounced Ministry of Health sterilization audits require continuous compliance spending that smaller competitors cannot sustain. |
| Anatolian City Greenfield Development | Underpenetrated demand in Izmir, Antalya, and Bursa supports volume accessibility positioning away from saturated Istanbul clusters. |
| Employer-Sponsored Program Direct Negotiation | Human resources departments at Riyadh construction conglomerates and London financial services firms seek predictable cost caps through annual case quotas. |
Research Methodology
Independent corroboration across hospital procurement managers, international patient coordinators, Gulf state insurer network directors, and Ministry of Health licensing officials underwrites the qualitative findings, with secondary validation drawing from JCI accreditation databases, ISO certification registries, and EU patient mobility directive implementation reports. Bottom-up facility capacity assessments and top-down inbound patient flow estimates were reconciled through cross-referencing.
Comparable historical reference periods anchored the projection framework across the analysis window, with segmentation modeling across treatment type, service package bundling intensity, patient origin geography, and facility accreditation tier. CAGRs were derived from procedure volume trajectories and average revenue per case trends, incorporating lira volatility assumptions and Gulf Cooperation Council insurance portability rule evolution as industry-specific forecast inputs.
Revisions become necessary when Ministry of Health regulatory enforcement intensity shifts, EU patient mobility directive reimbursement processing timelines change, or Gulf state employer-sponsored program procurement concentration accelerates beyond current trajectory assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Tourism
Fertility Tourism Market
Medical Tourism
Barbados Healthcare and Medical Tourism Market
Medical Tourism
Spain Medical Tourism Market
Medical Tourism
Europe Dental Tourism Market
Medical Tourism
India Medical Tourism Market
Medical Tourism
Japan Medical Tourism Market
Medical Tourism
North America Outbound Medical Tourism Services Market
Medical Tourism
Outbound Medical Tourism Services Market
Medical Tourism
GCC Countries Medical Tourism Market
Medical Tourism
UK Medical Tourism Market
Medical Tourism
Medical Tourism Market
Medical Tourism
China Medical Tourism Market
Medical Tourism
Italy Medical Tourism Market
Medical Tourism
France Medical Tourism Market
Medical Tourism
Thailand Medical Tourism Market
Medical Tourism
South Korea Medical Tourism Market