
 Outsourced Testing Services Market | 2026-2036
Outsourced Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Outsourced Testing Services Market Analytics
ISO 17025-grade certification is bifurcating the competitive landscape into accredited laboratories and commodity test shops. Accenture leverages its cloud engineering backbone to embed continuous validation into client DevOps pipelines. Tata Consultancy Services anchors large-scale financial services testing through captive centers in Mumbai and Chennai. Cognizant Technology Solutions differentiates via healthcare payer-specific compliance frameworks that map directly to HIPAA security rule controls.
Outsourced testing services encompass independent verification of software functionality, performance thresholds, security posture, and user experience against specified requirements using scripted test cases, automated toolchains, and human exploratory methods. These services reduce time-to-market for enterprise applications by detecting defects prior to production deployment while shifting fixed QA labor costs to variable expenditure. Functional testing occupies the largest revenue pool among service types as legacy system modernization drives regression demand across banking and insurance verticals. Security testing represents the fastest-expanding category as GDPR breach-notification mandates and SEC cybersecurity disclosure rules compel proactive penetration testing. Automated testing methodology captures disproportionate investment as CI/CD adoption forces script-based validation into every code commit.
FDA 21 CFR Part 11 and EMA Annex 11 shape demand in life sciences by mandating electronic record integrity and audit trail validation for software used in clinical trials. India's CDSCO and BIS laboratories enforce parallel bioequivalence and electromagnetic compatibility standards that local CROs must navigate for domestic market access. Stakeholders should monitor how EU AI Act conformity assessment requirements extend testing obligations to algorithmic decision systems in financial and healthcare deployments.
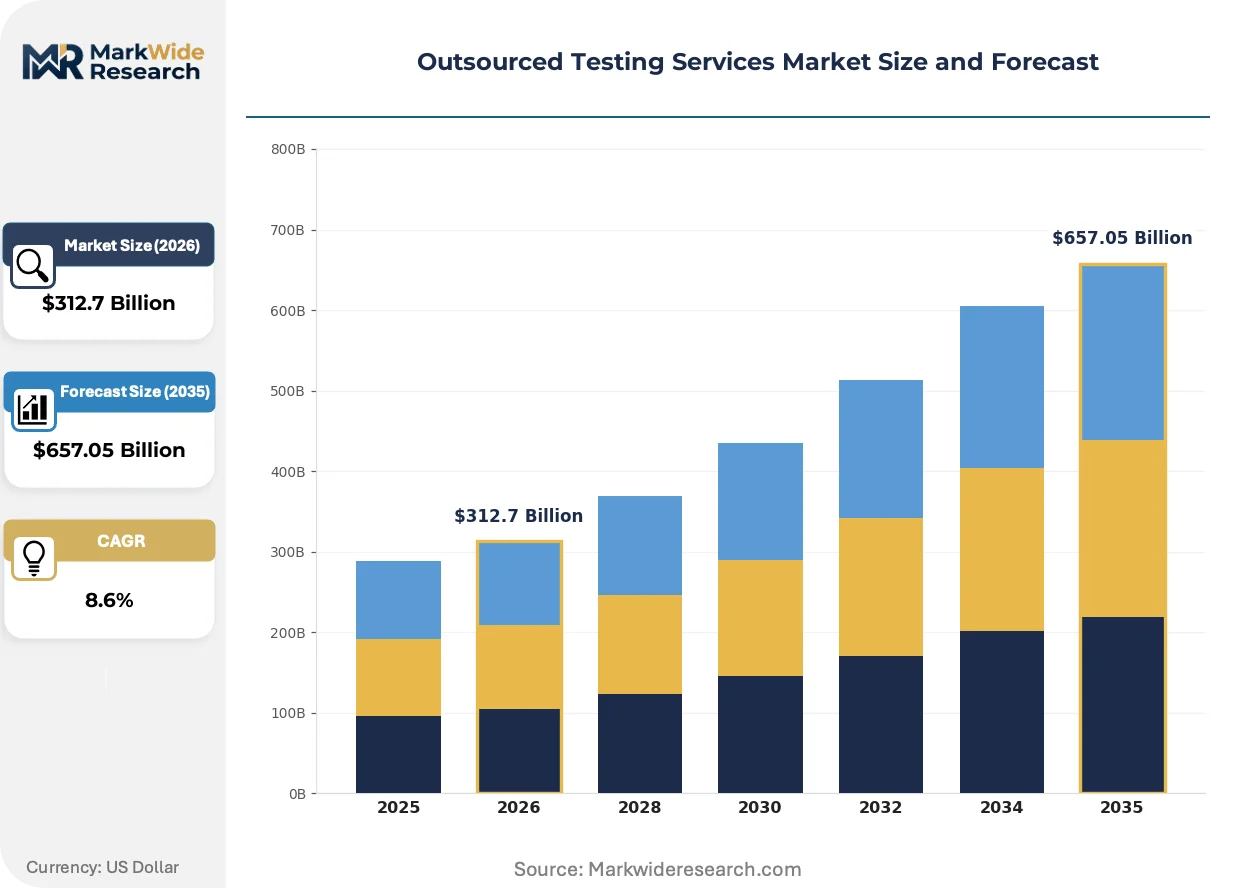
Market Dynamics
CI/CD pipeline adoption is fragmenting testing workflows into continuous micro-validations, forcing service providers to embed automation engineers directly within client sprint teams rather than operate as external batch processors.
Growth Catalysts
- EMA ICH Q14 Method-Validation Mandates:Pharmaceutical manufacturers in Germany now route complex bioanalytical assays to contract research organizations as European guidelines tighten validation requirements for analytical procedures.
- GDPR Breach-Notification Enforcement:European data protection authorities now impose 72-hour disclosure deadlines, compelling financial services firms to commission proactive penetration testing and security posture validation.
- Bengaluru-Hyderabad Corridor Scale:Indian CROs absorb Western regulatory submissions at volume, creating cost arbitrage for FDA 21 CFR Part 11 compliance documentation and clinical trial software validation.
Market Restraints
- ISO 17025 Accreditation Cost Barriers:Laboratory certification expenses bifurcate the competitive landscape, excluding commodity test shops from pharmaceutical and life sciences contracts.
- Specialized Talent Scarcity:DevOps automation engineers with GxP validation expertise command premium compensation, compressing margins for mid-tier service providers.
- Hybrid Cloud Complexity:Multi-cloud deployments fragment testing environments, requiring providers to maintain parallel validation stacks across AWS, Azure, and private infrastructure.
Strategic Opportunities
- EU AI Act Conformity Assessment:Algorithmic decision systems in financial and healthcare deployments will require expanded testing obligations, creating new service lines for bias detection and explainability validation.
- Medical Device Cybersecurity:FDA guidance on premarket submission of cybersecurity documentation opens specialized penetration testing demand for connected diagnostic equipment.
- Blockchain Smart Contract Verification:Decentralized finance protocols require formal verification of code correctness, extending testing services into cryptographic proof validation.
Industry Challenges
- Legacy System Integration Friction:Mainframe environments in banking and insurance resist automated test injection, forcing hybrid manual-scripted approaches that elongate delivery timelines.
- Cross-Border Data Residency:Testing teams in India face restrictions on accessing European patient data for validation, complicating clinical trial software quality assurance workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outsourced Testing Services Market |
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $657.05 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Functional Testing, Performance Testing, Security Testing, Usability Testing End User: IT Services, Financial Institutions, Healthcare Providers, eCommerce Testing Methodology: Automated Testing, Manual Testing, Continuous Testing, Agile Testing Deployment Model: Cloud-Based, On-Premises, Hybrid, Remote Testing |
| Companies Covered | Accenture, IBM Corporation, Capgemini, Tata Consultancy Services (TCS), Infosys Limited, Wipro Limited, Cognizant Technology Solutions, Tech Mahindra, Qualitest Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outsourced Testing Services Market Evolving Landscape
Artificial intelligence is rewriting test generation and execution protocols, compressing the traditional linear QA lifecycle into adaptive, self-healing validation loops that anticipate failure modes rather than react to them.
Model-based test generation is decomposing scripted manual test case libraries into autonomous, requirement-derived validation scenarios. Pharmaceutical manufacturers adopting FDA 21 CFR Part 11 compliant platforms now deploy AI-generated edge case suites that map directly to risk-based validation protocols. This capability is compressing method transfer timelines between sponsor organizations and contract laboratories.
EMA Annex 11 electronic record integrity mandates now require audit trail validation for all software used in clinical trial data capture. European life sciences firms must demonstrate complete data lineage from source system to regulatory submission, forcing CROs to implement blockchain-anchored verification logs. German pharmaceutical manufacturers lead compliance investment, routing complex bioanalytical work to accredited laboratories with validated computerized systems.
Subscription-based testing platforms are displacing per-project contracting in mid-market enterprise software. Banking and insurance verticals now procure continuous validation as a utility service, embedding quality assurance costs into annual software maintenance budgets. This shift concentrates vendor selection authority within procurement functions rather than distributed engineering teams, favoring providers with standardized platform architectures.
Outsourced Testing Services Market Segmentation
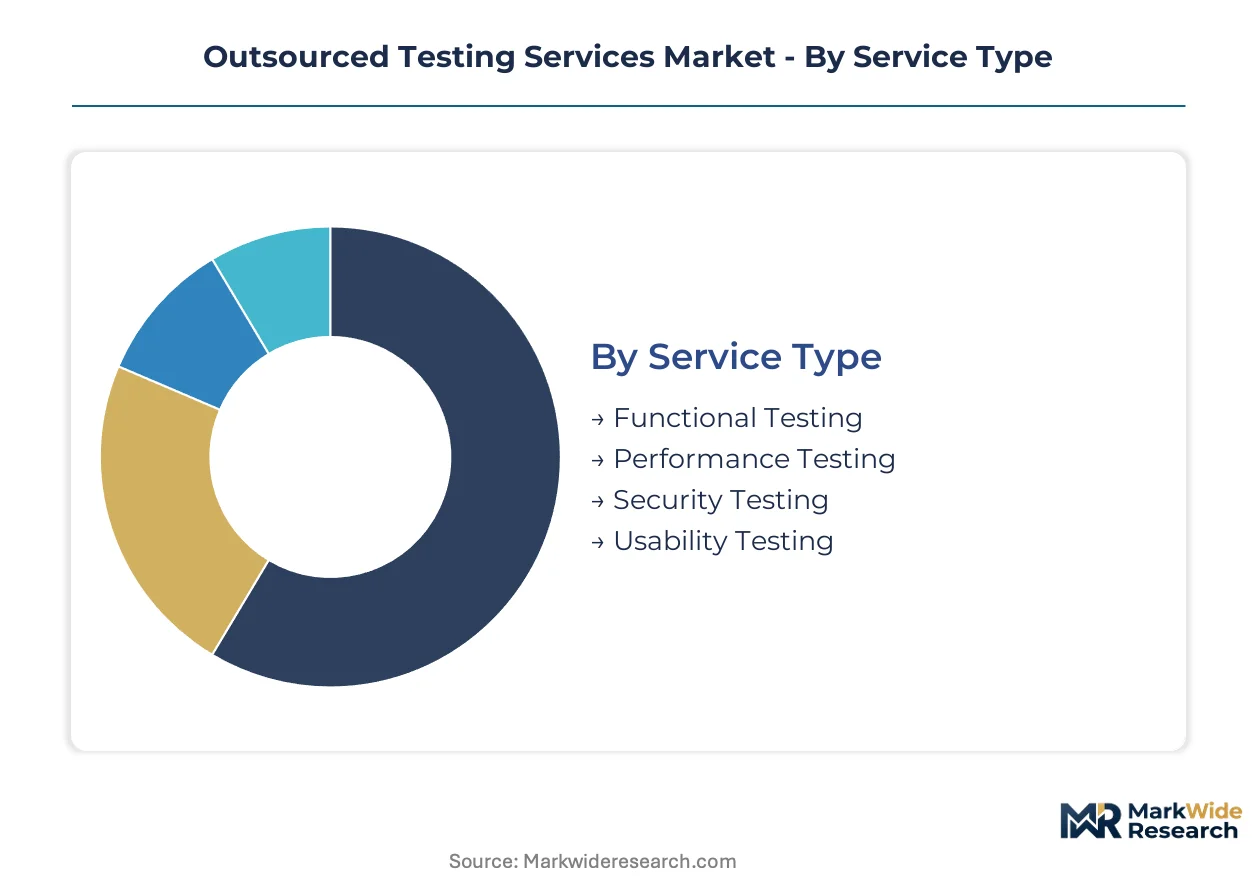
Testing service providers configure delivery models around client DevOps maturity and regulatory exposure. Segment boundaries blur as automation platforms absorb discrete service types into continuous pipelines. Understanding margin concentration across methodology and deployment choices determines vendor positioning strategy.
Service Type:
Functional testing commands the deepest margin pools due to legacy system regression demand across banking modernization programs.
- Functional Testing:Validates software behavior against specified requirements using scripted test cases and automated toolchains. Demand concentrates in North American banking and insurance verticals where core system modernization drives exhaustive regression suites. ISO 17025-grade laboratories capture premium pricing for validated environments.
- Security Testing:Proactive penetration testing and vulnerability assessment against frameworks like GDPR breach-notification mandates and SEC cybersecurity disclosure rules. European financial services firms commission continuous posture validation under 72-hour disclosure deadlines. This segment is expanding most quickly as regulatory enforcement tightens.
- Performance Testing:Load and stress validation for application scalability under transaction volume spikes.
- Usability Testing:Human-centered evaluation of interface design and user experience workflows.
The dominant share belongs to Functional Testing, while Security Testing is closing the gap fastest.
End User:
Volume concentration tracks digital transformation intensity and regulatory scrutiny severity across verticals.
- Financial Institutions:Banking and insurance carriers commission exhaustive validation for core banking platforms and claims processing systems. European institutions absorb GDPR compliance costs into testing budgets. Indian captive centers in Mumbai and Chennai process large-scale financial services validation at scale.
- Healthcare Providers:HIPAA security rule controls and FDA 21 CFR Part 11 mandates shape testing protocols for electronic health records and clinical trial software. German pharmaceutical manufacturers route bioanalytical assays to accredited contract laboratories under EMA ICH Q14 guidelines.
- IT Services:Software vendors and systems integrators embed quality assurance into product development lifecycles.
- eCommerce:Retail platforms prioritize checkout flow validation and payment gateway security testing.
Financial Institutions retain the largest procurement volumes, though Healthcare Providers are scaling fastest under life sciences digitization.
Testing Methodology:
Automation penetration determines cost structure and delivery velocity for service providers.
- Automated Testing:Script-based validation integrated into CI/CD pipelines executes with every code commit. DevOps adoption forces automation engineers into client sprint teams rather than external batch processing. Cloud engineering backbones enable continuous validation embedding.
- Continuous Testing:Micro-validation workflows triggered by pipeline events compress defect detection timelines. Fragmented testing environments across multi-cloud deployments require parallel validation stacks. This methodology is gaining share fastest as release frequency accelerates.
- Manual Testing:Human exploratory methods for edge case discovery and user experience evaluation.
- Agile Testing:Iterative validation aligned with sprint cycles and incremental feature delivery.
Automated Testing holds the installed base advantage, yet Continuous Testing demonstrates the steepest expansion trajectory.
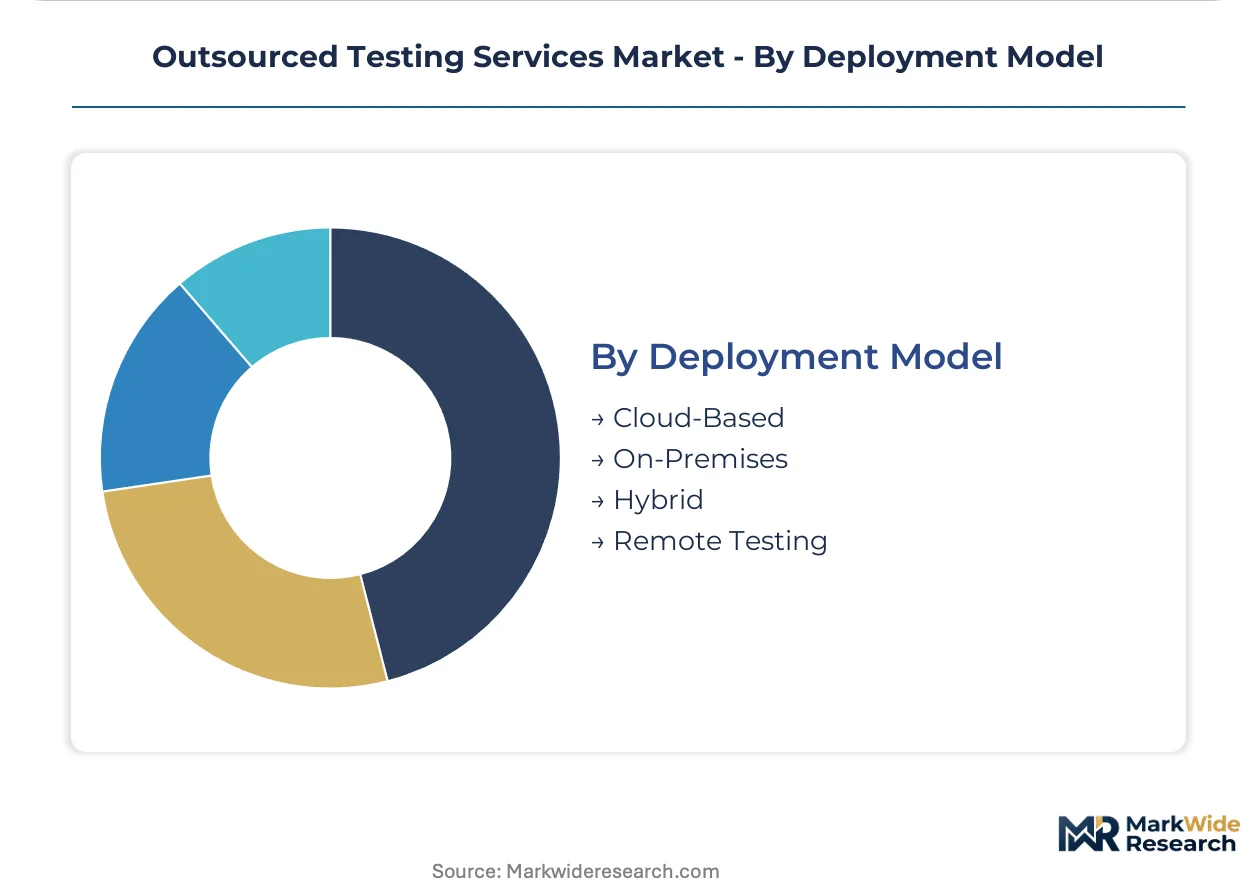
Deployment Model:
Cloud infrastructure economics are displacing capital-intensive on-premises validation environments.
- Cloud-Based:Elastic testing infrastructure provisioned across AWS, Azure, and Google Cloud platforms. Subscription-based platforms displace per-project contracting in mid-market enterprise software. Quality assurance costs embed into annual software maintenance budgets.
- Hybrid:Mixed environments combining public cloud burst capacity with on-premises secure enclaves for sensitive data. Cross-border data residency restrictions complicate clinical trial software validation for Indian testing teams accessing European patient records. Hybrid architectures are proliferating fastest under sovereignty requirements.
- On-Premises:Dedicated testing infrastructure within client data centers for maximum data control.
- Remote Testing:Distributed execution models leveraging global talent pools and follow-the-sun delivery.
Cloud-Based deployments lead current procurement, while Hybrid models are scaling most rapidly under data sovereignty pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Testing service exports flow predominantly from India toward Western pharmaceutical and financial services clients, while Germany and the United States remain net importers of specialized bioanalytical and security validation capabilities.
Germany
Pharmaceutical manufacturers in Baden-Württemberg and Bavaria route complex bioanalytical assays to contract laboratories under tightening EMA ICH Q14 guidelines. The country's national pharmaceutical regulator enforces method-validation requirements that accredited CROs must satisfy for clinical trial software deployment. Berlin-Brandenburg hosts specialized penetration testing firms serving Mittelstand industrial clients.
United States
FDA 21 CFR Part 11 mandates drive demand for electronic record integrity validation across life sciences software deployments. The SEC's cybersecurity disclosure rules compel financial institutions in New York and Chicago to commission continuous security posture assessments. Greater Boston concentrates bioanalytical CROs supporting pharmaceutical sponsors with GxP-compliant computerized systems.
India
The Bengaluru-Hyderabad corridor absorbs Western regulatory submissions at scale, creating cost arbitrage for FDA compliance documentation and clinical trial validation. CDSCO and BIS laboratories enforce parallel bioequivalence standards that local CROs navigate for domestic market access. Mumbai and Chennai captive centers process large-scale financial services testing for global banking clients.
United Kingdom
GDPR breach-notification enforcement compels London-based financial services firms to maintain 72-hour disclosure capabilities through proactive penetration testing. The Information Commissioner's Office mandates shape security testing procurement across insurance and fintech verticals. The Thames Valley corridor hosts specialized CROs serving European pharmaceutical sponsors with EMA-aligned validation protocols.
Switzerland
Swissmedic requirements for clinical trial software validation sustain demand for ISO 17025-grade laboratory services in Basel and Zurich. The country's pharmaceutical cluster generates specialized bioanalytical outsourcing for method transfer and computerized system validation. Geneva-based CROs serve as intermediaries for EMA regulatory submissions from emerging market sponsors.
Outsourced Testing Services Market Competitive Landscape
Concentration sits with diversified IT services conglomerates that embed testing capabilities within broader digital transformation offerings. The vendor base stratifies across three tiers: global consultancies with cloud engineering backbones, India-headquartered scale players with captive delivery centers, and specialized quality engineering boutiques. Strategic moves center on automation platform development and vertical-specific compliance framework acquisition.
Among diversified technology consultancies, Accenture exemplifies the cloud-native validation archetype through continuous testing integration into client DevOps pipelines. Tata Consultancy Services anchors the scale-driven tier with Mumbai and Chennai captive centers processing financial services validation at volume. Cognizant Technology Solutions occupies a healthcare-specialized position, mapping testing protocols directly to HIPAA security rule controls and FDA 21 CFR Part 11 requirements.
| Leading Market Players |
|---|
| Accenture |
| IBM Corporation |
| Capgemini |
| Tata Consultancy Services (TCS) |
| Infosys Limited |
| Wipro Limited |
| Cognizant Technology Solutions |
| Tech Mahindra |
| Qualitest Group |
| Others |
Value Network & Pricing Analysis
Subscription-based capacity reservation contracts now lock pharmaceutical manufacturers into multi-year testing service agreements, securing ISO 17025-grade laboratory access while flattening quarterly expenditure volatility for FDA 21 CFR Part 11 compliance documentation. German sponsors negotiating EMA ICH Q14 bioanalytical method transfers pay premium rates for validated computerized systems that compress regulatory submission timelines.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium, standard, and economy service levels. Premium tiers capture ISO 17025-accredited laboratories with GxP validation expertise, while commodity test shops compete on per-project rates for non-regulated software testing. Price differentiation hinges on certification grade and vertical specialization, with DevOps automation engineers commanding substantial premiums. Cost compression in mid-tier functional testing intensifies as Indian captive centers scale financial services validation. Healthcare providers exhibit lowest price sensitivity due to HIPAA security rule mandates and FDA enforcement exposure.
Supply Chain Analysis
Port congestion along the Nhava Sheva-Mundra corridor elevates inbound logistics costs for testing equipment imports into India's Bengaluru-Hyderabad corridor. Supply concentrates in India, Germany, and the United States, with Mumbai and Chennai captive centers processing large-scale financial services validation. Raw material dependencies include validated software licenses, automated testing toolchains, and cloud infrastructure provisioning. Single-source vulnerability persists for GxP-qualified engineers with FDA submission experience. Distribution runs through direct enterprise sales teams and cloud-native platform marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as pharmaceutical manufacturers consolidate vendor panels around accredited laboratories capable of EMA ICH Q14 and FDA 21 CFR Part 11 dual compliance, compressing margins for non-specialized providers.
For Market Incumbents: Fortify competitive moats by deepening GxP validation expertise and embedding automation engineers directly within client sprint teams rather than operating as external batch processors. Accenture's cloud engineering backbone and Cognizant's healthcare payer-specific compliance frameworks demonstrate defensible positioning against emerging AI-native testing platforms. ISO 17025 accreditation investment remains the priority lever for pharmaceutical contract capture. For New Entrants and Emerging Players: Lead with EU AI Act conformity assessment services targeting algorithmic decision systems in financial and healthcare deployments, where regulatory testing obligations remain nascent. Blockchain smart contract verification for decentralized finance protocols offers underpenetrated white space with limited incumbent specialization. Partner with existing cloud engineering backbones rather than building proprietary infrastructure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription-based testing platforms displacing per-project contracting in mid-market enterprise software. Long-term viability favors providers with standardized architectures embedding quality assurance into annual software maintenance budgets. Monitor FDA cybersecurity guidance expansion for connected diagnostic equipment as inflection signal for medical device testing demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding continuous validation into client DevOps pipelines compresses defect detection timelines for CI/CD adoption. |
| Acquisition of Specialist Firm | GxP validation boutiques with FDA 21 CFR Part 11 expertise command premium multiples from pharmaceutical sponsors. |
| Geographic Expansion | Captive centers in Mumbai and Chennai capture cost arbitrage for Western regulatory submission documentation. |
| Strategic Partnership | Cloud engineering alliances enable elastic testing infrastructure across AWS, Azure, and Google Cloud platforms. |
| Product Launch | AI-generated edge case suites map directly to EMA ICH Q14 risk-based validation protocols for method transfer acceleration. |
Research Methodology
Operator-level perspectives from quality engineering directors, regulatory affairs leads at pharmaceutical sponsors, CRO laboratory managers, and DevOps platform engineers anchored the qualitative base. Primary interviews combined with secondary validation from FDA 21 CFR Part 11 guidance documents, EMA ICH Q14 implementation frameworks, CDSCO bioequivalence standards, and SEC cybersecurity disclosure filings. Bottom-up service provider revenue estimates triangulated against top-down vertical spending allocations across banking, insurance, and life sciences segments.
Sensitivity analysis tested forecast robustness across automation penetration scenarios and regulatory enforcement intensity variations over the projection horizon. Segmentation dimensions modeled include service type, end-user vertical, testing methodology, and deployment model complexity. CAGRs derived from regression analysis of historical contract value growth and forward-looking pipeline visibility from regulatory submission trends. Cloud infrastructure economics and AI test generation adoption curves informed methodology-specific growth assumptions.
Forecasts assume regulatory continuity in FDA, EMA, and CDSCO enforcement regimes; material policy shifts would require re-modeling. Cross-border data residency restrictions and ISO 17025 accreditation cost inflation represent specific risk factors that could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Influenza Home Testing Market
Testing Services
Global Newborn Screening Market
Testing Services
Global IVD Regulatory Affairs Outsourcing Market
Testing Services
Special Coagulation Tests Market
Testing Services
Sickle Cell Anemia Testing and Screening Market
Testing Services
Global Bilirubin Colorimeter Assay Market
Testing Services
Europe Antimicrobial Susceptibility Testing Market
Testing Services
Allergy Skin Test Market
Testing Services
Infusion Toxicology Services Market
Testing Services
Arthropod-Borne Viral Infections Testing Market
Testing Services
Global Enzyme Linked Immunosorbent Assay (ELISA) Testing Market
Testing Services
Global at-Home Drug of Abuse (DOA) Testing Market
Testing Services
At-Home Celiac Testing Market
Testing Services
Pharmaceutical Analytical Testing Market
Testing Services
Syphilis Testing Market
Testing Services
Fertility and Pregnancy Rapid Test Kits Market