
 Global Dental Hygiene Devices Market | 2026-2036
Global Dental Hygiene Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dental Hygiene Devices Market Foresight
Aftermarket service revenue for precision scaler tips and brush head replenishment is fragmenting across regional distributor networks and direct-to-practice digital channels. Dentsply Sirona leverages its installed base of chairside equipment to capture recurring consumable sales. Procter & Gamble sustains dominant shelf presence in mass retail through proprietary oscillating-rotating patents. Danaher anchors professional-grade water flosser distribution through its KaVo dental platform network.
Dental hygiene devices encompass powered and manual instruments engineered to remove biofilm, calculus, and surface stains from tooth structures, with sonic and ultrasonic systems typically operating at frequencies between 20,000 and 40,000 Hz to disrupt bacterial adhesion through cavitation and acoustic microstreaming. These instruments serve preventive dentistry, periodontal maintenance, and cosmetic oral care across clinical and consumer settings. Electric toothbrushes command the largest revenue pool due to premium pricing and replacement brush head economics, while water flossers represent the fastest-expanding category as consumers shift from string floss to pressurized irrigation for interdental cleaning. Dental scalers retain concentrated margin capture within professional channels where FDA 510(k) and CE marking requirements limit new entrant access.
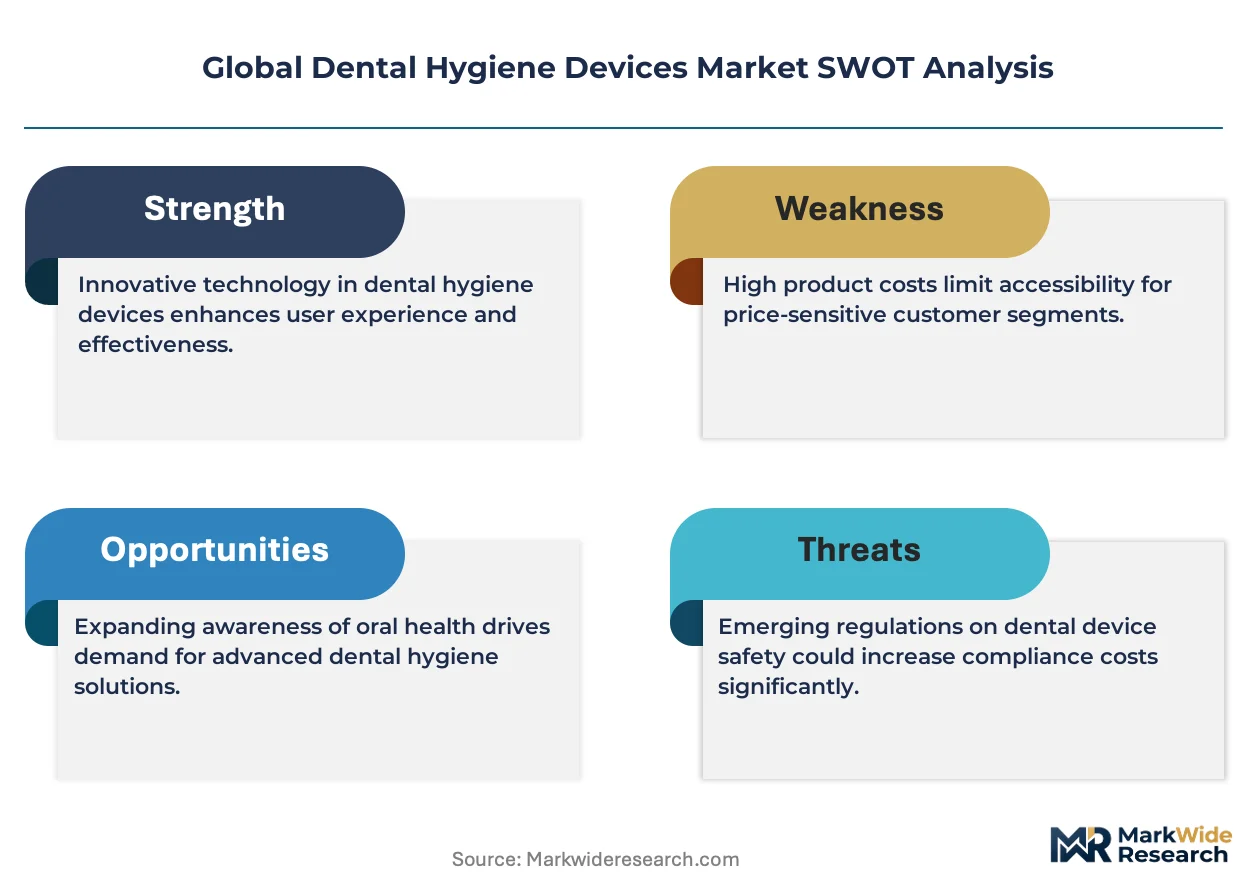
The FDA's 510(k) premarket notification framework governs powered dental device safety and efficacy claims in the United States, while the EU Medical Device Regulation (MDR) reclassifies certain powered scalers and irrigators to higher risk tiers with expanded clinical evidence requirements. Japan's Ministry of Health, Labour and Welfare (MHLW) enforces Pharmaceutical and Medical Device Act standards that delay foreign product entry but reward localized quality certification. Stakeholders must monitor regulatory divergence between FDA predicate device pathways and MDR technical documentation demands when allocating R&D and registration budgets across priority markets.
Market Dynamics
The aftermarket service revenue model for precision scaler tips and brush head replenishment is fragmenting across regional distributor networks and direct-to-practice digital channels, compressing traditional margin structures while opening new channel economics.
Growth Catalysts
- Preventive care protocol expansion:Dental clinics across Germany, Japan, and Brazil are upgrading equipment fleets to capture recurring patient volume through scheduled hygiene appointments.
- FDA 510(k) pathway efficiency:The premarket notification framework for powered dental scalers and water flossers accelerates product commercialization timelines versus full PMA review.
- Urban private dental chain consolidation:China's tier-one cities are witnessing equipment fleet standardization as private chains centralize procurement.
Market Restraints
- Titanium alloy input volatility:Precision scaler tip manufacturing depends on aerospace-grade titanium supply subject to spot price fluctuations and export quota restrictions.
- EU MDR technical documentation burden:The Medical Device Regulation reclassification of powered irrigators to higher risk tiers demands expanded clinical evidence, lengthening registration timelines.
- String floss substitution persistence:Traditional interdental cleaning maintains cost advantage and consumer habit stickiness in price-sensitive demographics.
Strategic Opportunities
- Subscription-based consumable models:Direct-to-practice digital channels enable automated brush head and tip replenishment with predictive inventory algorithms.
- AI-powered plaque detection integration:Smartphone-connected oral cameras using machine learning are converging with electric toothbrush ecosystems to deliver real-time brushing feedback.
- Japan MHLW localized certification:The Pharmaceutical and Medical Device Act rewards foreign manufacturers who invest in domestic quality certification infrastructure.
Industry Challenges
- EU MDR notified body capacity constraints:Certification backlogs for Class IIa and IIb powered devices are extending time-to-market by twelve to eighteen months.
- Legacy scaler tip compatibility standards:Proprietary connector geometries across installed equipment bases complicate aftermarket tip sourcing for multi-brand dental practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dental Hygiene Devices Market |
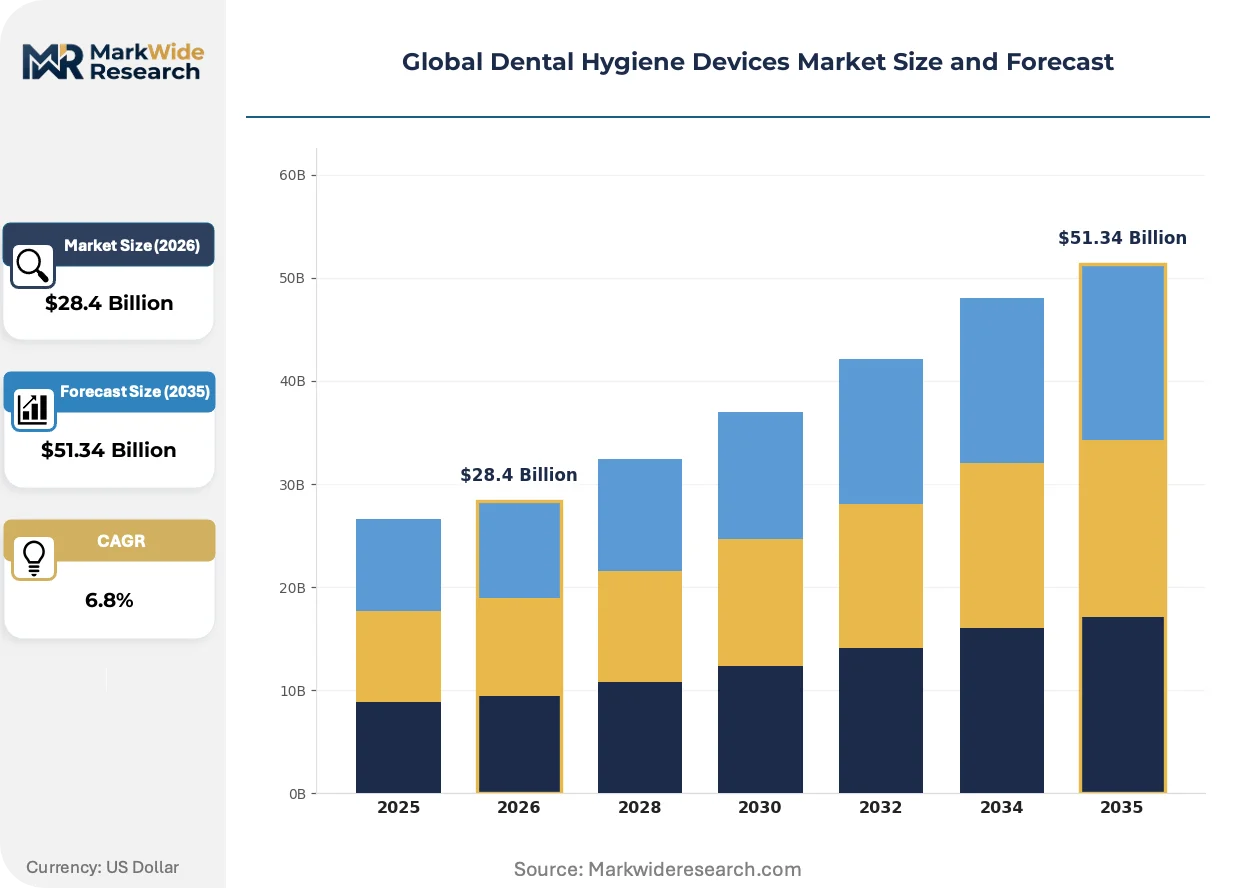
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $51.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Toothbrushes, Manual Toothbrushes, Water Flossers, Dental Scalers, Interdental Brushes Technology: Sonic, Ultrasonic, Oscillating-Rotating, Pulsating, Manual Application: Plaque Removal, Gum Care, Whitening, Breath Freshening, Tartar Control End User: Dental Clinics, Orthodontists, Dental Laboratories, Home Care Users |
| Companies Covered | Colgate-Palmolive Company, Procter & Gamble, Dentsply Sirona, 3M, Danaher, Koninklijke Philips, GlaxoSmithKline, Ivoclar Vivadent, BIOLASE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dental Hygiene Devices Market Shifts & Advancements
Smartphone-connected oral care ecosystems are collapsing the boundary between professional diagnostic capability and consumer self-monitoring, redistributing value capture from clinical settings toward app-integrated hardware platforms.
Photonic disinfection technology using blue light-emitting diode arrays is collapsing bacterial biofilm disruption efficacy into handheld consumer form factors previously restricted to clinical ultraviolet systems. Early adopters in South Korea's aesthetic dentistry segment are integrating these devices with whitening protocols. The compression of professional-grade antimicrobial performance into sub-hundred-dollar retail price points is collapsing the historical segmentation between clinical and consumer oral hygiene tiers.
The EU Medical Device Regulation's expanded clinical evidence requirements for powered irrigators are forcing manufacturers to retrofit predicate device portfolios with new biocompatibility and electrical safety documentation. German notified bodies are prioritizing technical file reviews for devices with existing CE certificates under the Medical Devices Directive. The reclassification pressure is concentrating professional-grade water flosser development resources toward Class IIb compliance investments.
After-sales service unbundling is separating equipment warranty coverage from consumable replenishment contracts in dental practice procurement. Brazilian private dental chains are negotiating direct tip sourcing agreements that bypass traditional distributor markups. The disintermediation is most visible in São Paulo and Rio de Janeiro metropolitan clusters where group purchasing organizations aggregate demand across fifty-plus location networks.
Global Dental Hygiene Devices Market Segmentation
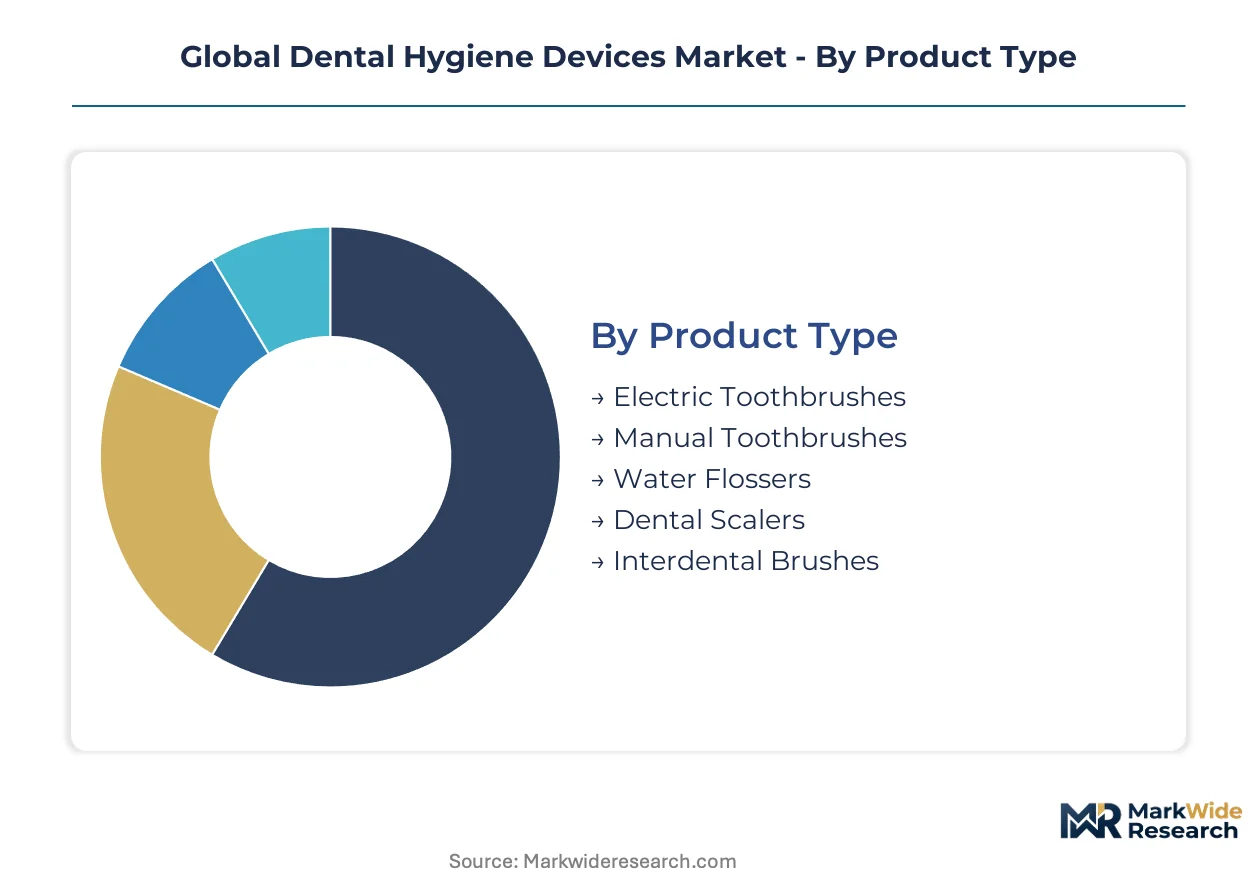
Segmentation in dental hygiene devices reveals divergent margin structures and channel economics. Product type determines whether revenue concentrates in recurring consumables or capital equipment replacement cycles. Technology and application dimensions further stratify pricing power between professional and consumer tiers.
Product Type:
Electric toothbrushes and water flossers anchor opposite ends of the use-case spectrum, from daily preventive routines to targeted interdental irrigation.
- Electric Toothbrushes:These devices incorporate rechargeable power systems with oscillating-rotating or sonic mechanisms operating at 20,000-40,000 Hz. Demand clusters in China's tier-one cities where private dental chains bundle them with preventive care packages. Brush head replenishment economics sustain manufacturer margins long past initial hardware sale.
- Water Flossers:Pressurized pulsating water streams deliver interdental cleaning at 10-100 psi operating pressure. German dental clinics are upgrading to professional-grade units as part of expanded periodontal maintenance protocols. The shift from string floss accelerates category expansion fastest among urban demographics.
- Manual Toothbrushes:Polymer-bristle designs dominate volume in price-sensitive emerging markets and institutional procurement.
- Dental Scalers:Titanium-alloy precision tips on powered handpieces serve calculus removal in clinical settings. FDA 510(k) clearance requirements limit competitive entry.
- Interdental Brushes:Wire-core nylon bristle configurations target orthodontic patients and periodontal maintenance cases.
The dominant share belongs to electric toothbrushes, while water flossers are climbing the fastest as consumers abandon traditional string floss.
Technology:
Cost tier stratification separates premium powered systems from basic mechanical alternatives, with frequency and motion patterns determining clinical efficacy claims.
- Sonic:Acoustic energy at 20,000-40,000 Hz generates cavitation and acoustic microstreaming for biofilm disruption. Japanese MHLW certification standards reward localized quality infrastructure investment. Sonic systems command premium positioning in professional and consumer channels alike.
- Ultrasonic:Piezoelectric transducers deliver frequencies above 20,000 Hz for calculus removal in clinical scaler applications. EU MDR reclassification to Class IIb elevates technical documentation burdens for new entrants. German notified bodies prioritize legacy device portfolio reviews.
- Oscillating-Rotating:Mechanical brush head rotation combined with pulsation dominates mass retail shelf presence through proprietary patent protection.
- Pulsating:Water jet pressure modulation without sonic frequency characterizes entry-level water flosser architectures.
- Manual:Pure mechanical action without power assistance retains volume leadership in institutional and developing market procurement.
Sonic technology captures the premium tier, with ultrasonic systems facing steepest regulatory headwinds in European registration timelines.
Application:
Customer type and clinical indication create divergent performance requirements and reimbursement pathways across preventive versus therapeutic positioning.
- Plaque Removal:Daily biofilm disruption represents the foundational use case spanning electric toothbrushes and water flossers. Brazil's private dental chains are standardizing equipment fleets around plaque-focused preventive protocols. Scheduled hygiene appointments generate recurring revenue for clinic operators.
- Gum Care:Periodontal maintenance applications demand precision pressure control and soft-tissue compatibility. Japanese aesthetic dentistry clinics integrate these protocols with whitening services. Gum care specialization supports premium pricing in professional channels.
- Whitening:Surface stain removal and bleaching acceleration drive consumer upgrade cycles and attachment sales.
- Breath Freshening:Volatile sulfur compound reduction targets social and professional confidence positioning in mass retail.
- Tartar Control:Calculus prevention and removal concentrates in clinical scaler applications with professional-only distribution.
Plaque removal holds the installed base majority, though gum care applications are gaining share fastest as periodontal disease awareness rises.
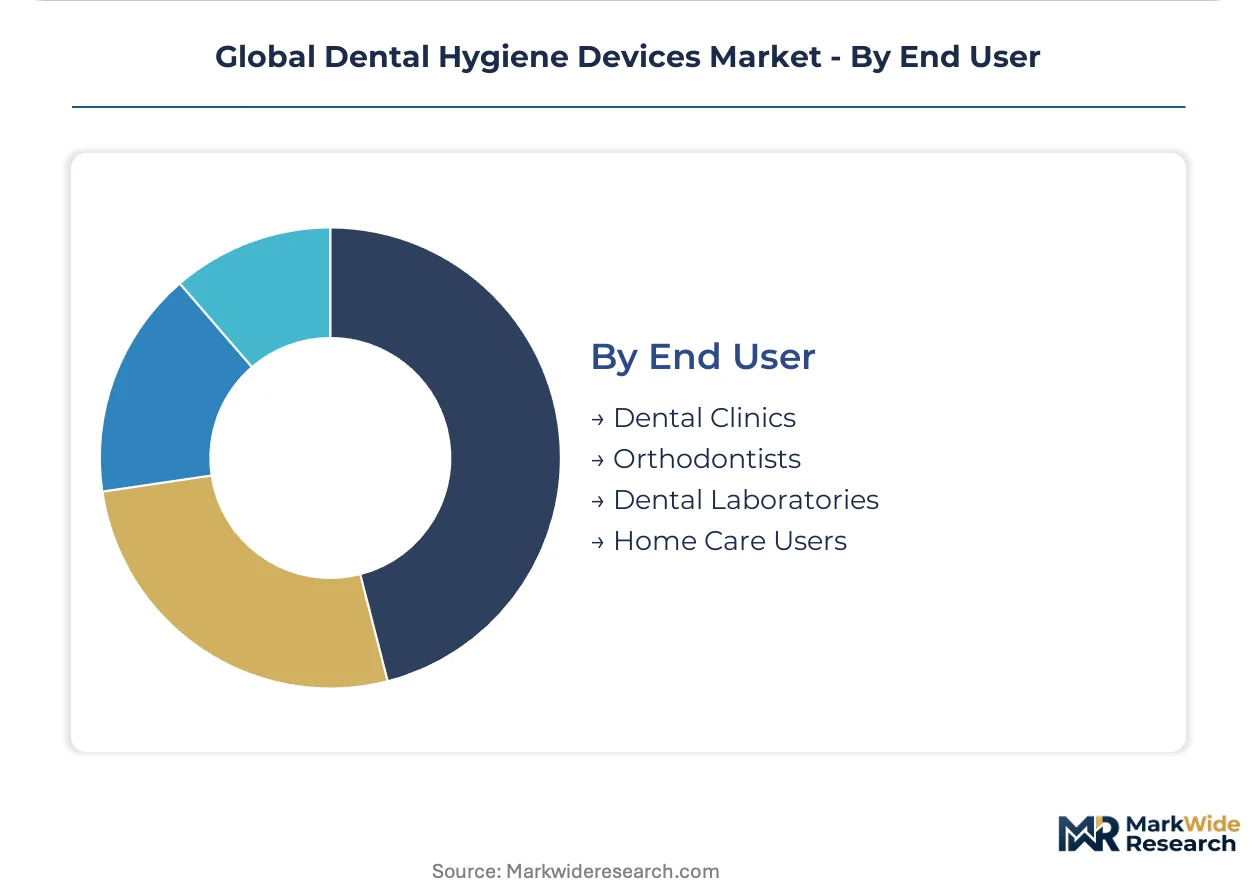
End User:
Volume concentration and margin capture diverge sharply between institutional procurement standardization and fragmented consumer self-selection.
- Dental Clinics:Professional settings demand FDA 510(k) or CE-marked devices with validated efficacy claims. China's tier-one private chains centralize procurement across fifty-plus location networks. Aftermarket tip and brush head replenishment contracts sustain long-term supplier relationships.
- Orthodontists:Specialized practices require interdental cleaning compatibility with fixed appliances and aligner systems. Brazilian group purchasing organizations aggregate orthodontic practice demand in São Paulo and Rio de Janeiro metropolitan clusters. Precision tip geometries must match proprietary equipment connectors.
- Dental Laboratories:Fabrication and finishing operations utilize specialized cleaning equipment for prosthetic and appliance production.
- Home Care Users:Consumer self-purchase dominates electric toothbrush and water flosser volume through retail and direct-to-consumer digital channels.
Home care users generate the volume base, while dental clinics concentrate value capture through equipment standardization and consumable lock-in.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: clinical-grade scaler systems dominate procurement in Germany and Japan, while China's urban consumers drive electric toothbrush volume through retail channels and Brazil's private chains standardize water flosser fleets for preventive protocols.
United States
FDA 510(k) premarket notifications for powered scalers and irrigators accelerate commercialization timelines versus full PMA review. The regulatory pathway rewards predicate device strategies for established manufacturers. Metropolitan dental clusters in Texas and Florida are consolidating procurement through group purchasing organizations that negotiate direct consumable contracts.
Germany
EU MDR reclassification of powered irrigators to Class IIb elevates technical documentation burdens, concentrating development resources among notified body-preferred applicants. German dental clinics are expanding preventive care protocols with scheduled hygiene appointments. The Baden-Württemberg and Bavaria industrial corridors host precision scaler tip manufacturing subject to aerospace-grade titanium input volatility.
China
Private dental chains in Shanghai, Beijing, and Shenzhen are centralizing equipment procurement across fifty-plus location networks. NMPA regulatory pathways for powered dental devices reward localized quality certification infrastructure. Tier-one city consumers are upgrading from manual to sonic electric toothbrushes through e-commerce direct-to-consumer channels.
Japan
MHLW Pharmaceutical and Medical Device Act standards delay foreign product entry but reward domestic quality certification investment. Aesthetic dentistry clinics in Tokyo and Osaka are integrating gum care protocols with whitening services. Sonic technology systems command premium positioning through localized JIS standards compliance.
Brazil
ANVISA regulatory frameworks govern powered dental device safety claims with emphasis on biocompatibility documentation. São Paulo and Rio de Janeiro metropolitan clusters are witnessing after-sales service unbundling as group purchasing organizations aggregate demand. Private dental chains are negotiating direct tip sourcing agreements that bypass traditional distributor markups.
Global Dental Hygiene Devices Market Competitive Landscape
Capability concentration sits with professional-grade equipment specialists; scale advantage sits with mass-market consumer goods conglomerates. The market structure tiered between FDA 510(k) cleared clinical device manufacturers and retail-channel electric toothbrush producers. Three archetypes dominate: installed-base platform owners capturing recurring consumable revenue, proprietary technology patent holders defending shelf presence, and precision component specialists serving aftermarket tip replenishment. Consolidation pressure is accelerating through strategic partnerships between equipment manufacturers and digital health platforms, alongside backward integration into titanium alloy supply chains.
Within the installed-base platform tier, Dentsply Sirona and Danaher occupy positions leveraging chairside equipment ecosystems to capture recurring scaler tip and brush head sales. Procter & Gamble exemplifies the mass-market archetype through proprietary oscillating-rotating patent protection and dominant retail shelf presence. Colgate-Palmolive sits within the oral care portfolio diversification vector, spanning professional and consumer channels.
| Leading Market Players |
|---|
| Colgate-Palmolive Company |
| Procter & Gamble |
| Dentsply Sirona |
| 3M |
| Danaher |
| Koninklijke Philips |
| GlaxoSmithKline |
| Ivoclar Vivadent |
| BIOLASE |
| Others |
Supply & Pricing Matrix
Baden-Württemberg's precision scaler tip manufacturing clusters anchor aerospace-grade titanium processing capacity that feeds downstream pricing power to German dental equipment producers facing input volatility. This geographic concentration of specialized metallurgy infrastructure creates asymmetric cost pass-through dynamics where raw material spot fluctuations transmit unevenly across consumer versus professional product tiers.
Pricing Analysis
Long-term consumable replenishment contracts dominate professional channel economics, with spot purchasing confined to emergency tip replacement and small-practice procurement. Price differentiation hinges on FDA 510(k) certification tier and bundled after-sales service coverage, with cleared clinical devices commanding substantial premiums over consumer retail equivalents. Cost compression in mass-market electric toothbrushes intensifies as private-label entrants replicate sonic frequency architectures. Home care users exhibit highest price sensitivity, while dental clinic procurement committees prioritize equipment standardization and tip compatibility over unit cost minimization.
Supply Chain Analysis
Export control regimes governing aerospace-grade titanium alloys constrain raw material flows from US and EU suppliers to precision manufacturing hubs in Germany and Japan. Finished device assembly concentrates in China, Germany, and the United States, with component sourcing drawing from Taiwanese electronics for power systems and Swiss micromotors for premium handpieces. Single-source vulnerability in titanium alloy supply creates exposure to spot price spikes and quota restrictions. Distribution runs through regional distributor networks for professional equipment, while consumer products bypass intermediaries via direct-to-practice digital channels and mass retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as smartphone-connected oral cameras with AI plaque detection threaten to displace standalone electric toothbrush hardware value capture. String floss habit persistence and low-cost manual alternatives continue pressuring water flosser penetration in price-sensitive demographics.
For Market Incumbents: Entrench installed-base lock-in through proprietary scaler tip connector geometries and predictive replenishment algorithms that automate inventory management for multi-location dental chains. Counter AI-powered diagnostic substitutes by integrating real-time brushing feedback into existing sonic platform ecosystems. Backward integration into titanium alloy supply hedges input cost volatility threatening margin compression in precision tip manufacturing.
For New Entrants and Emerging Players: Brazil's São Paulo and Rio de Janeiro metropolitan clusters present underpenetrated white space where group purchasing organization aggregation is disintermediating traditional distributor markups. Target orthodontic specialist practices requiring interdental cleaning compatibility with fixed appliances, a segment underserved by mass-market product architectures. Pursue direct-to-practice digital channels with subscription-based consumable models that bypass incumbent distributor relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue platform play because brush head and scaler tip replenishment economics sustain manufacturer margins years past initial hardware installation. Acquisition targets should display installed base density in tier-one Chinese cities or Japanese aesthetic dentistry clinics where premium positioning endures. Monitor EU MDR notified body capacity constraints as inflection indicator—certification backlogs extending beyond eighteen months will concentrate market share among legacy predicate device holders with existing technical documentation.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR Class IIb reclassification demands expanded clinical evidence for powered irrigators entering German notified body review queues. |
| Hospital System Partnership | China's private dental chains centralize procurement across fifty-plus location networks, rewarding suppliers with fleet standardization agreements. |
| Software Companion Development | Smartphone-connected oral cameras using machine learning converge with electric toothbrush ecosystems to defend against standalone diagnostic substitutes. |
| Backward Integration into Titanium Supply | Aerospace-grade alloy input volatility threatens precision scaler tip margins; captive supply secures cost predictability for German manufacturing. |
| Reimbursement Strategy | Japan's MHLW rewards localized quality certification with preferential positioning in aesthetic dentistry clinic procurement decisions. |
Research Methodology
Desk research of FDA 510(k) premarket notification databases, EU MDR technical documentation guidance, and NMPA regulatory pathways preceded structured interviews with dental clinic procurement managers, biomedical engineers, GPO contracts specialists, and aftermarket service heads. Secondary validation drew from hospital procurement databases, customs trade records for titanium alloy flows, and dental equipment distributor financial disclosures. Bottom-up equipment installation counts and top-down market size estimates were triangulated to reconcile volume and value figures.
Assumptions held fixed across the modeling period include regulatory pathway timelines for predicate device clearances, titanium alloy spot price bands, and private dental chain consolidation rates in China's tier-one cities. Variables included NMPA localization requirements, EU notified body capacity expansion, and AI-powered diagnostic technology adoption curves. CAGRs were derived from segment-level growth rate reconciliation across product type, technology tier, application, and end-user dimensions. Forecast inputs incorporated brush head replenishment frequency data and water flosser household penetration assumptions.
Practitioners should monitor EU MDR notified body backlog duration, titanium export quota announcements, and AI diagnostic platform funding rounds for early signals of forecast deviation. Material shifts in regulatory pathway efficiency, aerospace alloy supply availability, or consumer substitution patterns would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
North America Dental Lab Market
Dental Devices
Spain Dental Devices Market
Dental Devices
Dental Fittings Market
Dental Devices
Dental Laboratories Market
Dental Devices
United Kingdom Dental Devices Market
Dental Devices
Dental Sealants Market
Dental Devices
Dental 3D Printing Market
Dental Devices
Dental Air Polishers Market
Dental Devices
Prophy Dental Handpiece Market
Dental Devices
Chile Dental Market
Dental Devices
China Dental Devices Market
Dental Devices
Global Dental Burs Market
Dental Devices
Europe CBCT Dental Imaging Market
Dental Devices
United States Dental Implants Market
Dental Devices
Sleep Apnea Oral Appliances Market
Dental Devices
Dental Curing Lights Market