
 US Mechanical Ventilator Market | 2026-2036
US Mechanical Ventilator Market Size, Share, and Industry Trends Forecast 2026-2036
US Mechanical Ventilator Market Intelligence
Hospital group purchasing organizations are reshaping how mechanical ventilators flow into acute care networks across the United States. Medtronic leverages its broad critical care portfolio to sustain long-term contracts with integrated delivery networks. GE Healthcare anchors its position through deep installed-base relationships and service revenue streams in large health systems.
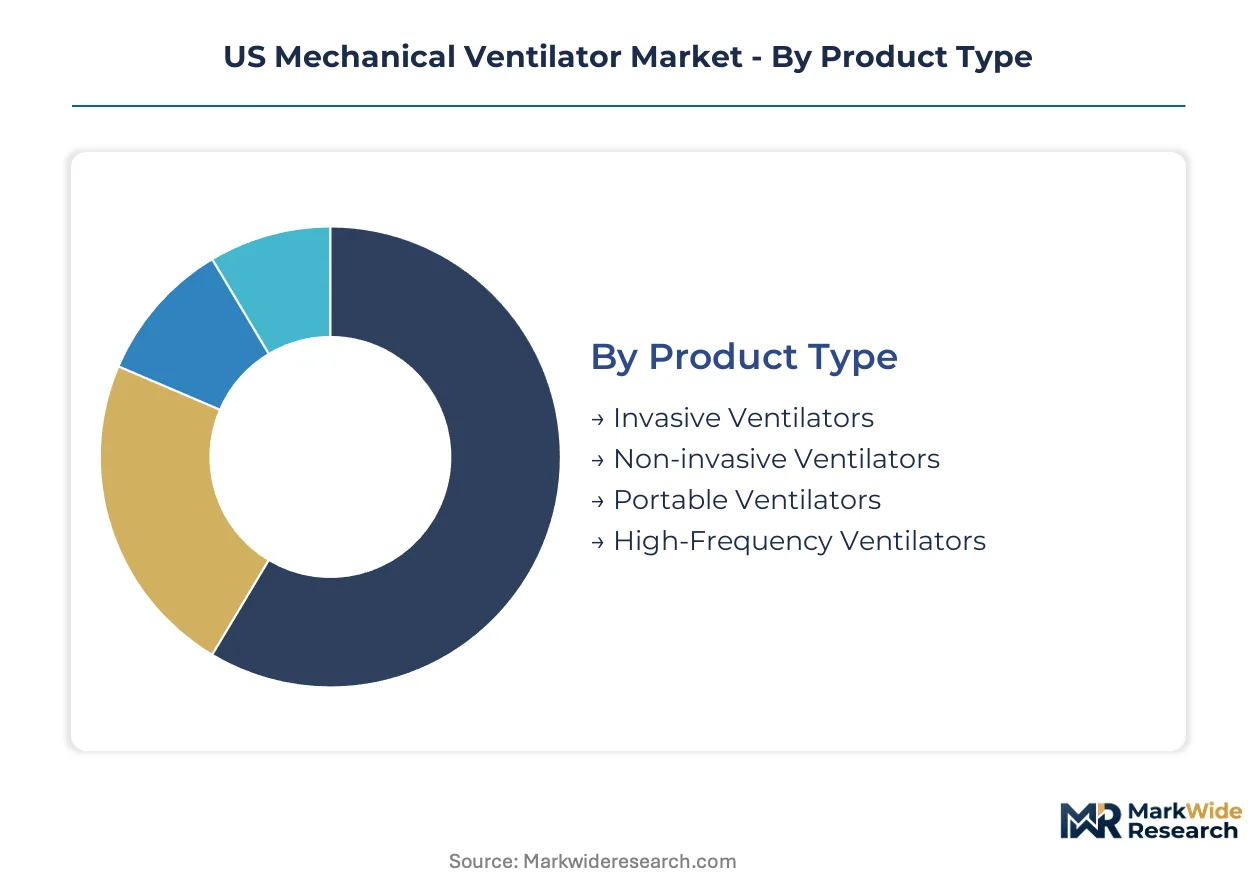
A mechanical ventilator is an electrically powered life-support device that delivers breathable air into and out of a patient's lungs through an endotracheal tube or mask interface, typically operating at pressure ranges of 5–40 cm H₂O and incorporating microprocessor-controlled feedback loops for tidal volume and respiratory rate management. Its primary purpose is to provide or assist pulmonary ventilation in patients with respiratory failure, acute lung injury, or compromised airway reflexes. Invasive ventilators command the dominant revenue share within product type categories due to their essential role in intensive care settings and higher per-unit pricing. Portable ventilators represent the fastest-expanding segment as post-acute care shifts toward home-based respiratory management and emergency transport protocols.
FDA 510(k) clearance pathways and ISO 80601-2-80 electrical safety standards govern device authorization and clinical deployment across US hospitals. CMS reimbursement coding under DRG classifications directly shapes hospital capital allocation for ventilator fleet modernization. Stakeholders must monitor evolving FDA guidance on software-as-a-medical-device frameworks as artificial intelligence-enabled ventilation modes advance toward commercialization.
Market Dynamics
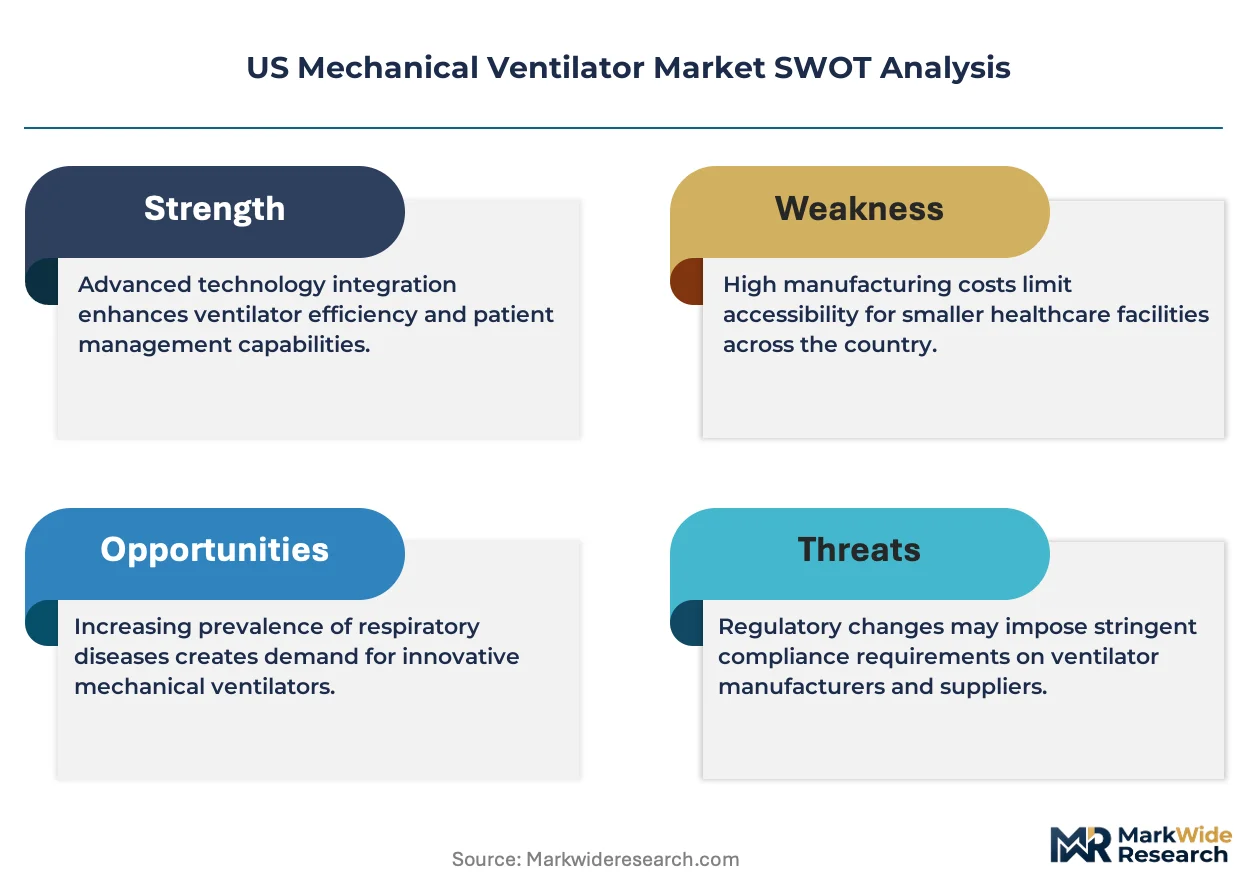
Hospital group purchasing organizations are consolidating procurement authority across integrated delivery networks, forcing manufacturers to restructure pricing and service bundling to retain access to high-volume acute care contracts.
Growth Catalysts
- ISO 80601-2-80 electrical safety standards:Updated international requirements for critical care ventilators are accelerating fleet replacement cycles in tertiary hospitals seeking compliance certification.
- Post-acute care migration:Texas and Florida health systems are expanding home-based respiratory management programs, creating pull-through demand for portable ventilator configurations.
- Academic medical centers:Complex respiratory failure case volumes at institutions like Mayo Clinic and Cleveland Clinic are driving investment in multi-mode ventilation platforms with advanced monitoring capabilities.
Market Restraints
- Semiconductor supply concentration:Microprocessor and sensor component sourcing remains concentrated among Asian foundries, exposing US manufacturers to extended lead times during demand surges.
- FDA 510(k) pathway friction:Premarket notification requirements for software-as-a-medical-device submissions are extending validation timelines by 8-14 months for AI-enabled ventilation modes.
- Capital equipment substitution:High-frequency oscillatory ventilation systems and extracorporeal membrane oxygenation are capturing select acute respiratory distress syndrome cases previously managed with conventional mechanical ventilation.
Strategic Opportunities
- Southeast medical corridor expansion:Nashville and Atlanta hospital construction pipelines are creating greenfield procurement opportunities without incumbent equipment lock-in.
- CMS DRG reimbursement alignment:Updated diagnosis-related group classifications for respiratory failure are creating capital allocation incentives for ventilator fleet modernization.
- Cloud-native ventilation analytics:Convergence of edge computing and predictive algorithms is enabling remote patient monitoring services that extend manufacturer relationships beyond hardware sales.
Industry Challenges
- Bioengineering talent scarcity:Respiratory therapy device specialists with ISO 13485 quality system expertise command premium compensation, constraining R&D team scaling.
- Legacy health record integration:Epic and Cerner electronic medical record systems require custom HL7 interface development, complicating deployment timelines and elevating implementation costs.
- Service technician certification:Manufacturer-authorized repair training programs face capacity constraints, limiting aftermarket service expansion in rural hospital markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Mechanical Ventilator Market |
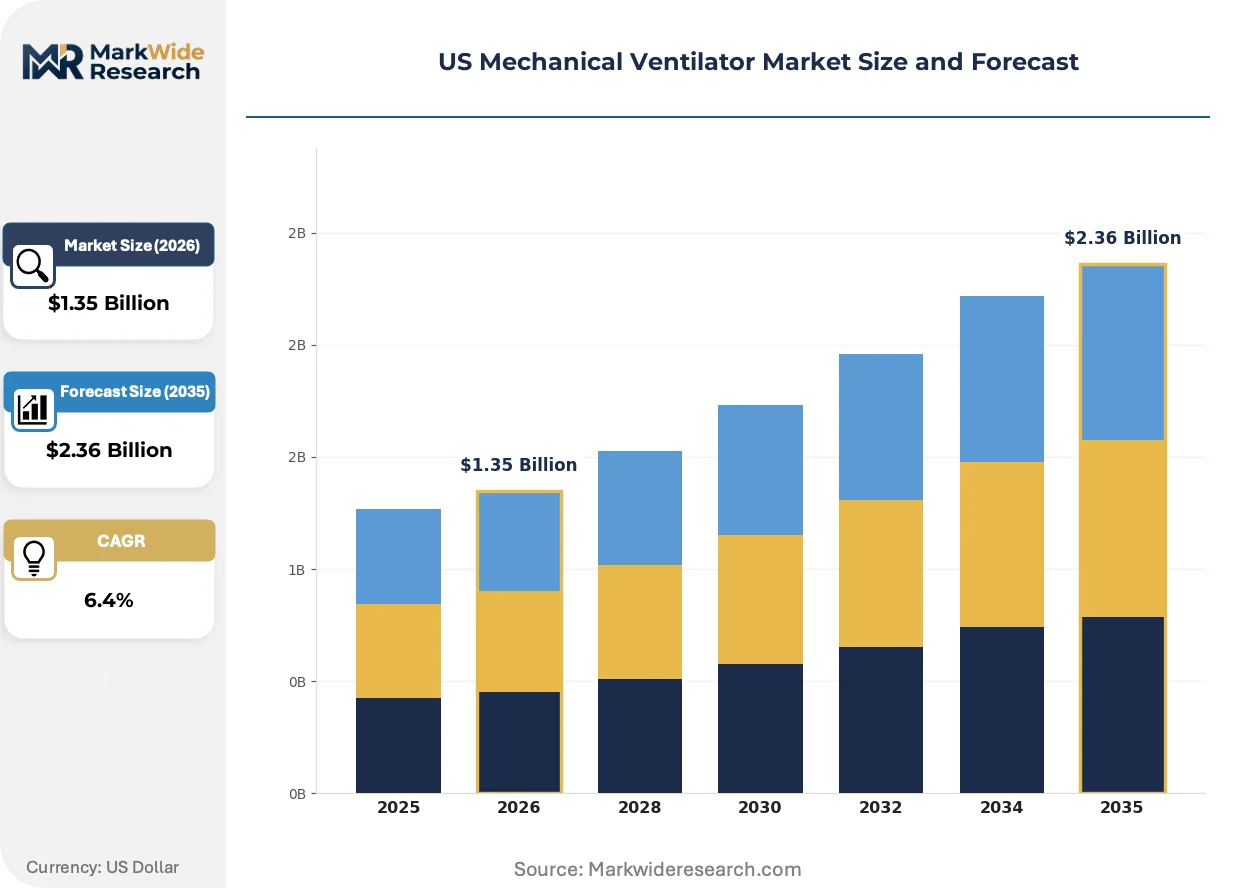
| Market Size in 2026 | $1.35 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Invasive Ventilators, Non-invasive Ventilators, Portable Ventilators, High-Frequency Ventilators End User: Hospitals, Home Care Providers, ASCs, Long-term Care Facilities Technology: Microprocessor-based, Pneumatic, Electronic, Software-Driven Application: Critical Care, Emergency Care, Transport, Anesthesia |
| Companies Covered | Medtronic, GE Healthcare, Getinge AB, Drägerwerk AG & Co. KGaA, Koninklijke Philips N.V., Hamilton Medical, Vyaire Medical Inc., ResMed Inc., Smiths Group plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Mechanical Ventilator Market Strategic Shifts & Innovations
Artificial intelligence is penetrating ventilation control systems, shifting competitive advantage toward software-enabled clinical decision support rather than hardware performance specifications alone.
Adaptive pressure support algorithms are hybridizing conventional volume-control ventilation with real-time respiratory mechanics feedback. Academic medical centers in the Northeast are piloting these systems for weaning protocol optimization. This convergence is compressing differentiation between premium and mid-tier hardware platforms as software becomes the primary value driver.
FDA guidance on predetermined change control plans is reshaping how manufacturers validate machine learning-enabled ventilation modes. The agency's framework requires locked algorithm architectures with documented performance boundaries. Device sponsors are responding by segregating AI-enabled features into modular software components that can be updated without full 510(k) resubmission.
Group purchasing organization consolidation is concentrating buyer power among three dominant intermediaries serving over sixty percent of US hospital beds. Traditional distributor relationships are being displaced by direct manufacturer contracting with integrated delivery networks. This restructuring is most visible in the Texas Medical Center and Pacific Northwest health systems where multi-hospital alliances negotiate enterprise-wide ventilator standardization.
US Mechanical Ventilator Market Segmentation
Mechanical ventilator procurement patterns diverge sharply across clinical settings and technological architectures. Hospital capital committees, home care agencies, and ambulatory surgical centers each impose distinct performance specifications and price sensitivity thresholds that reshape manufacturer positioning strategies.
Product Type:
Cost tier differentiation separates intensive care platforms from transportable units and emergency alternatives.
- Invasive Ventilators:These systems deliver breathable air through endotracheal tubes or tracheostomy interfaces, operating at pressure ranges of 5–40 cm H₂O with microprocessor-controlled feedback loops for tidal volume management. Academic medical centers in the Northeast and Texas Medical Center corridor are standardizing on multi-mode platforms with advanced monitoring capabilities to manage complex respiratory failure cases.
- Portable Ventilators:Battery-powered units weighing under 10 pounds enable post-acute respiratory management outside institutional walls. Florida and Texas health systems expanding home-based care programs are driving procurement volume for configurations with integrated oxygen conservation and remote telemetry.
- Non-invasive Ventilators:Mask-delivered positive pressure systems for patients with intact airway reflexes.
- High-Frequency Ventilators:Oscillatory platforms delivering small tidal volumes at rapid rates for acute lung injury.
Invasive Ventilators commands the established base. The steepest expansion runs through Portable Ventilators.
End User:
Customer type determines service bundling requirements, training intensity, and capital deployment cycles.
- Hospitals:Integrated delivery networks and academic medical centers account for the dominant share of critical care unit procurement. Southeast hospital construction pipelines in Nashville and Atlanta are creating greenfield opportunities without incumbent equipment lock-in, while established systems prioritize fleet modernization for ISO 80601-2-80 compliance.
- Home Care Providers:Post-acute respiratory management agencies serve patients transitioning from intensive care to community settings. Texas and Florida Medicaid waiver programs are expanding reimbursement for home ventilator services, pulling demand toward lightweight, caregiver-friendly configurations.
- ASCs:Ambulatory surgical centers require compact anesthesia-capable units for procedural sedation.
- Long-term Care Facilities:Skilled nursing facilities manage stable ventilator-dependent residents.
Hospitals command the established base. The steepest expansion runs through Home Care Providers.
Technology:
Functional architecture separates legacy pneumatic systems from software-enabled adaptive platforms.
- Microprocessor-based:Digital control systems with real-time respiratory mechanics feedback dominate current ICU installations. FDA 510(k) clearance pathways for algorithm updates are extending validation timelines, prompting manufacturers to segregate AI-enabled features into modular software components.
- Software-Driven:Cloud-native platforms with predictive analytics and remote monitoring capabilities are emerging as the next competitive frontier. Convergence of edge computing and machine learning is enabling ventilation-as-a-service business models that extend manufacturer relationships beyond hardware sales.
- Pneumatic:Compressed gas-powered systems for emergency backup and field deployment.
- Electronic:Analog control circuits in legacy installed base requiring replacement.
Microprocessor-based command the established base. The steepest expansion runs through Software-Driven.
Application:
Clinical use case dictates performance specifications, regulatory pathway, and reimbursement coding.
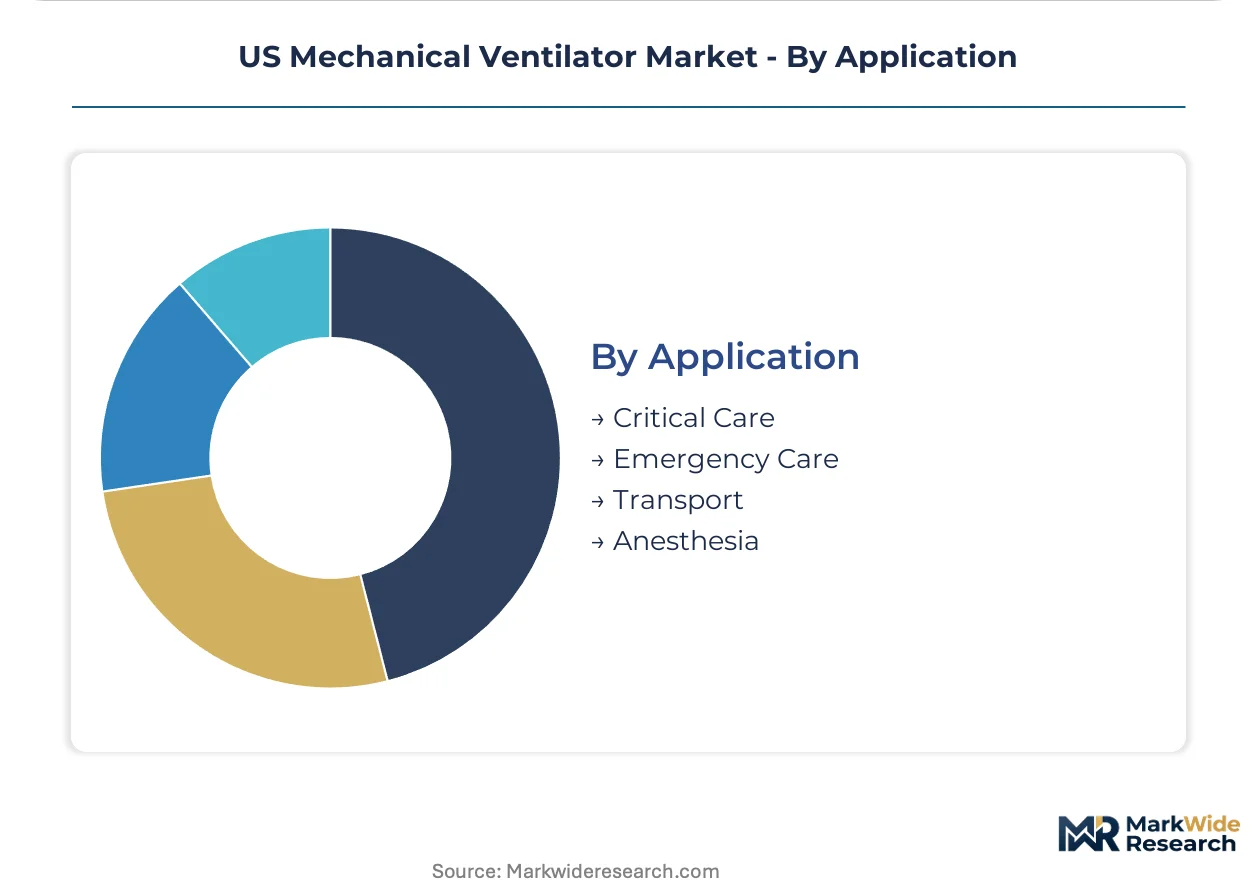
- Critical Care:Multi-mode ventilation platforms for intensive care units managing acute respiratory distress syndrome and post-surgical respiratory failure. CMS DRG reimbursement classifications for respiratory failure are creating capital allocation incentives for fleet modernization across tertiary hospitals.
- Emergency Care:Rapid-deployment systems for emergency departments and trauma bays.
- Transport:Ruggedized units for inter-facility transfer and aeromedical evacuation.
- Anesthesia:Integrated workstations for operating room ventilation and gas delivery.
Critical Care commands the established base. The steepest expansion runs through Emergency Care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways and CMS DRG reimbursement classifications are steering hospital capital allocation toward ventilator fleet modernization across distinct US medical corridors. State-level Medicaid waiver programs and hospital construction pipelines are creating divergent procurement environments.
Southeast Medical Corridor
Nashville and Atlanta hospital construction pipelines are generating greenfield procurement opportunities without incumbent equipment lock-in. Tennessee and Georgia Medicaid agencies are expanding reimbursement for home ventilator services under post-acute care waivers. Academic medical centers in the Research Triangle are piloting AI-enabled ventilation modes for weaning protocol optimization.
Texas Medical Center
The Houston-based Texas Medical Center anchors the nation's largest concentration of tertiary respiratory care capacity. Texas Medicaid waiver programs are pulling demand toward portable ventilator configurations for home-based respiratory management. Dallas-Fort Worth health systems are negotiating enterprise-wide ventilator standardization through integrated delivery network contracts.
Florida Peninsula
Florida's aging demographic profile is intensifying demand for post-acute respiratory services across the I-4 corridor. The state's Agency for Health Care Administration is expanding Medicaid coverage for home ventilator-dependent patients. Tampa and Orlando hospital systems are building dedicated respiratory step-down units to manage chronic ventilator weaning.
Northeast Academic Belt
Mayo Clinic and Cleveland Clinic networks are driving investment in multi-mode ventilation platforms with advanced monitoring capabilities. Massachusetts and New York hospital systems face accelerated replacement cycles to meet updated ISO 80601-2-80 electrical safety standards. Boston's Longwood Medical Area is emerging as a testbed for cloud-native ventilation analytics and remote patient monitoring services.
Pacific Northwest
Seattle and Portland health systems are standardizing on software-driven platforms with predictive analytics capabilities. Washington State's Health Care Authority is revising Medicaid reimbursement codes to align with CMS DRG classifications for respiratory failure. The region's integrated delivery networks are consolidating procurement authority through group purchasing organization affiliation.
US Mechanical Ventilator Market Key Industry Players
On the supply side, the industry is consolidating around three dominant intermediaries serving over sixty percent of US hospital beds. Diversified medical technology conglomerates anchor the critical care segment through long-term service contracts and installed-base relationships. Specialists in portable and home care configurations occupy distinct competitive territory. Manufacturers are restructuring pricing and service bundling to retain access to high-volume acute care contracts, while simultaneously developing cloud-native ventilation analytics to extend relationships beyond hardware sales.
Within the diversified conglomerate tier, Medtronic and GE Healthcare exemplify positioning through broad critical care portfolios and deep health system relationships. Among European-based specialists, Drägerwerk AG & Co. KGaA and Getinge AB occupy positions anchored by intensive care platform expertise and regulatory compliance capabilities. ResMed Inc. represents the portable and home care archetype, with its corporate identity signaling specialization in post-acute respiratory management outside institutional walls.
| Leading Market Players |
|---|
| Medtronic |
| GE Healthcare |
| Getinge AB |
| Drägerwerk AG & Co. KGaA |
| Koninklijke Philips N.V. |
| Hamilton Medical |
| Vyaire Medical Inc. |
| ResMed Inc. |
| Smiths Group plc |
| Others |
Cost & Logistics Intelligence
Taiwanese foundry capacity for microprocessor and sensor components directly shapes pricing power across US mechanical ventilator tiers, with semiconductor allocation constraints compressing margins on mid-range platforms while insulating premium ICU systems.
Pricing Analysis
Certification level creates the primary spread between ventilator tiers, with FDA 510(k) cleared platforms and ISO 80601-2-80 compliant systems commanding premium positioning against legacy pneumatic alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects bundled service intensity and software capability depth. Cost compression in standard-tier units is intensifying because group purchasing organization consolidation concentrates buyer leverage across integrated delivery networks. Academic medical centers exhibit lowest price sensitivity due to clinical outcome prioritization, while rural hospitals and long-term care facilities face acute capital constraint pressure.
Supply Chain Analysis
Microprocessor feedstock draws from Taiwan, South Korea, and China, with sensor arrays and precision valves sourcing from Germany and Japan. Critical dependencies include semiconductor wafers, medical-grade aluminum enclosures, and silicone diaphragm components. Single-source vulnerability in advanced ASIC fabrication exposes manufacturers to allocation disruption during demand surges. Distribution runs through manufacturer-direct contracting with integrated delivery networks, displacing traditional distributor relationships in high-volume hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA software-as-a-medical-device guidance is accelerating AI-enabled ventilation mode commercialization, creating a high-growth disruption window for adaptive algorithm platforms.
For Market Incumbents: Build installed-base data moats through cloud-native ventilation analytics that embed predictive weaning protocols into hospital workflows. Deepen service revenue streams by certifying proprietary technician networks for legacy fleet maintenance. Counter portable ventilator substitution by integrating remote patient monitoring capabilities into critical care platform subscriptions.
For New Entrants and Emerging Players: Pursue Southeast medical corridor greenfield procurement where Nashville and Atlanta construction pipelines lack incumbent equipment lock-in. Target home care provider segments in Texas and Florida where Medicaid waiver expansion is reimbursing lightweight portable configurations. Deploy direct-to-provider digital sales channels that bypass consolidated group purchasing organization intermediaries.
For Investors and Strategic Acquirers: Long-term, this sits as a software-medical-device convergence play because AI-enabled ventilation modes are shifting value capture from hardware specifications to algorithm performance. Prioritize acquisition targets with locked algorithm architectures and predetermined change control plans already mapped to FDA guidance. Monitor CMS DRG reimbursement recalibration for respiratory failure as the signal for accelerated hospital capital deployment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-a-Medical-Device Submission | Accelerates AI-enabled ventilation mode commercialization under predetermined change control plans. |
| Hospital System Partnership | Locks in multi-year fleet standardization contracts across Texas Medical Center integrated delivery networks. |
| Software Companion Development | Extends manufacturer relationships beyond hardware through cloud-native ventilation analytics and remote monitoring. |
| CE Marking Pathway | Opens parallel commercialization channels for portable configurations in European post-acute care markets. |
| Reimbursement Strategy | Aligns product positioning with CMS DRG classifications and state Medicaid waiver program expansions. |
Research Approach
Cross-validation between hospital procurement databases and GPO contract archives anchors the qualitative findings on pricing dynamics and vendor selection criteria. Primary interviews with biomedical engineers, respiratory therapists, GPO contracts managers, and hospital purchasing committees were combined with secondary validation through FDA 510(k) filings, CMS Medicare reimbursement data, and ISO standards documentation. Bottom-up unit shipment modeling and top-down hospital capital expenditure triangulation were applied across the analysis window.
Calibration against historical replacement cycle patterns and regulatory compliance deadlines shaped the analytical framework. Segmentation dimensions modeled include product type, end user category, technology architecture, and clinical application setting. CAGRs were derived from weighted average growth assumptions across these segments. Forecast inputs incorporated ISO 80601-2-80 adoption timelines and AI-enabled feature penetration curves in academic medical centers.
Sensitivities concentrate around FDA guidance evolution on machine learning-enabled devices and semiconductor supply allocation volatility. Forecasts reflect assumptions on hospital construction pipeline completion and Medicaid waiver program expansion rates. Cross-checking against hospital capital budget surveys and GPO contract renewal schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Meniscal Rasps Market
Medical Devices
Healthcare Additive Manufacturing Market
Medical Devices
Veterinary Respiratory Ventilators Market
Medical Devices
Male Artificial Urinary Sphincter Market
Medical Devices
Intraocular Lens (IOL) Market
Medical Devices
Spain Aesthetic Devices Market
Medical Devices
Single-Use Assemblies Market
Medical Devices
Wearable Medical Device Connectivity and Cybersecurity Test Systems Market
Medical Devices
Ultra-Large Volume Wearable Injectors Market
Medical Devices
Unilateral Biportal Endoscopy Market
Medical Devices
China Anesthesia Devices Market
Medical Devices
Transradial Closure Devices Market
Medical Devices
Next-Generation Neurofeedback Device Market
Medical Devices
Arteriosclerosis Detector Market
Medical Devices
China Minimally Invasive Surgery Devices Market
Medical Devices
Asia-Pacific Medical Device Market