
 Prophylaxis Pastes Market | 2026-2036
Prophylaxis Pastes Market Size, Share, and Industry Trends Forecast 2026-2036
Prophylaxis Pastes Market Analytics
ISO 13485 certification for medical device quality management is bifurcating the competitive landscape between qualified manufacturers and commodity suppliers. Dentsply Sirona leverages its integrated dental platform to sustain recurring paste sales through proprietary delivery systems. Ultradent Products Inc. specializes in clinician-centric formulations that dominate the North American professional channel. VOCO GmbH anchors its position with German-engineered abrasive technologies that compete on consistency rather than price.
Prophylaxis pastes are abrasive slurries containing pumice, perlite, or synthetic silica particles suspended in glycerin or water-based carriers, designed for mechanical removal of extrinsic stains and biofilm during professional dental cleaning. Fluoride paste formulations retain the largest volume share in general dentistry due to reimbursement alignment, while whitening paste variants within cosmetic dentistry command the strongest margin pools as patients self-fund aesthetic procedures. Sachet packaging is gaining traction in dental clinics seeking single-use infection control compliance, though tube formats still lead in hospitals where multi-patient protocols dominate procurement.
The FDA oversees prophylaxis paste classification as Class I medical devices, while the EU MDR requires updated technical documentation and clinical evaluation for abrasive dental products placed on the European market. Japan's PMDA enforces JIS-compliant biocompatibility testing that limits import pathways for non-certified manufacturers. Stakeholders must monitor evolving fluoride concentration limits under EFSA and state-level dental board guidelines, as regulatory divergence between jurisdictions will determine which formulation portfolios can scale without reformulation costs.
Market Dynamics
ISO 13485 certification requirements are bifurcating the competitive landscape, forcing manufacturers to choose between medical device quality compliance and commodity positioning as regulatory scrutiny intensifies across major markets.
Growth Catalysts
- Preventive Care Expansion:Dental clinics in the United States, Germany, and Japan are expanding prophylaxis protocols as reimbursement frameworks increasingly favor early intervention over restorative procedures.
- FDA Device Reclassification:The FDA's updated medical device classification for abrasive dental preparations is elevating formulation standards and accelerating professional-grade product adoption.
- Enamel-Safe Polishing Demand:Cosmetic dentistry applications are commanding premium positioning for non-abrasive polishing agents as patients prioritize aesthetic outcomes alongside oral health.
Market Restraints
- Glycerin Input Volatility:Fluctuating glycerin prices, driven by biodiesel co-production cycles, compress margin predictability for water-based and glycerin-suspended paste formulations.
- Pumice Supply Concentration:Natural pumice sourcing concentrates in Mediterranean volcanic regions, exposing manufacturers to geopolitical disruption and quality inconsistency risks.
- EU MDR Compliance Burden:The EU MDR requires updated technical documentation and clinical evaluation for abrasive dental products, creating substantial reformulation costs for European market access.
Strategic Opportunities
- Single-Use Sachet Adoption:Dental clinics are shifting toward sachet packaging formats to meet single-use infection control compliance, opening premium positioning for sterile-dispensing system manufacturers.
- Whitening Paste Premiumization:Patient self-funding of aesthetic procedures is expanding margin pools for whitening paste variants within cosmetic dentistry channels.
- Japan PMDA Certification Pathway:JIS-compliant biocompatibility testing requirements limit import competition, creating protected market access for certified manufacturers willing to navigate PMDA protocols.
Industry Challenges
- Fluoride Concentration Divergence:EFSA and state-level dental board guidelines are evolving on fluoride limits, forcing portfolio fragmentation to serve jurisdiction-specific formulation requirements.
- Legacy Tube-to-Sachet Conversion:Hospitals with multi-patient procurement protocols resist packaging format shifts, requiring dual-format inventory management and complicating supply chain optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prophylaxis Pastes Market |
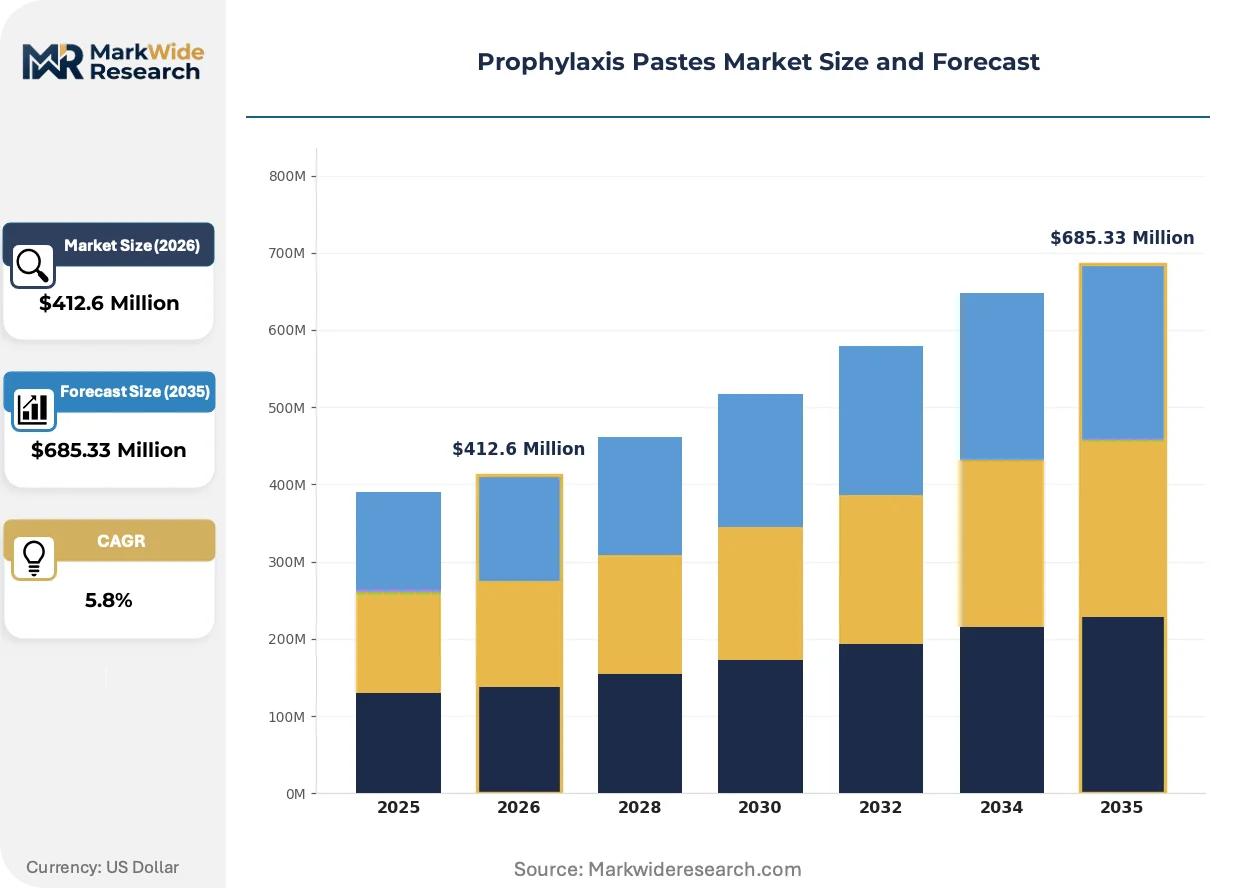
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluoride Paste, Non-Fluoride Paste, Herbal Paste, Whitening Paste Application: Pediatric Care, Geriatric Care, General Dentistry, Cosmetic Dentistry Packaging Type: Tube, Bottle, Sachet, Jar End User: Dental Clinics, Hospitals, Home Care, Research Laboratories |
| Companies Covered | 3M, Dentsply Sirona, VOCO GmbH, Keystone Industries, Ultradent Products Inc., Young Dental, Kerr Corporation, Premier Dental, Ivoclar Vivadent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prophylaxis Pastes Market Evolving Landscape
Synthetic silica abrasive technologies are reshaping formulation chemistry as manufacturers seek alternatives to natural pumice, while regulatory convergence around biocompatibility testing is accelerating certification-driven competitive sorting.
Perlite-based polishing agents are fragmenting the traditional pumice-dominated abrasive landscape. German-engineered perlite technologies offer controlled particle geometry that dental professionals increasingly prefer for consistent stain removal. This fragmentation is compressing commodity pumice suppliers into price-competitive general dentistry segments while elevating precision-engineered alternatives in cosmetic applications.
The EU MDR's expanded clinical evaluation requirements for abrasive dental products are forcing reformulation investments across European portfolios. Manufacturers must now generate biocompatibility documentation that previously satisfied notified body review without additional testing. Cosmetic dentistry paste variants face the steepest compliance burden, as their higher abrasive indices trigger more stringent safety substantiation demands.
Self-funded aesthetic procedures are compressing traditional reimbursement-driven procurement cycles in dental clinics. Patients directly purchasing whitening treatments are bypassing institutional purchasing committees, shifting influence toward chairside clinician preference. This behavioral shift is most visible in United States metropolitan markets where cosmetic dentistry volume concentrates and practice management software enables transparent procedure pricing.
Prophylaxis Pastes Market Segmentation
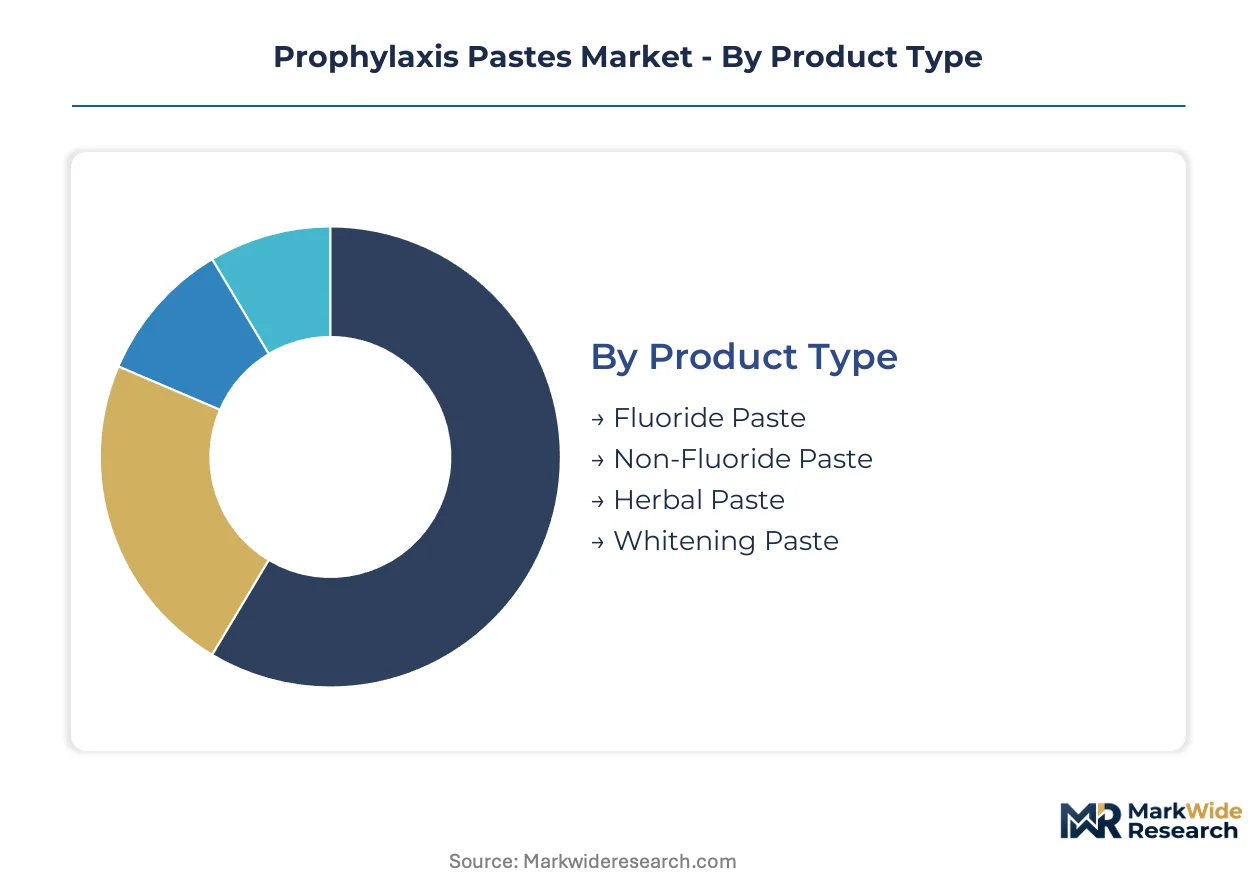
Prophylaxis paste formulation diversity reflects divergent regulatory pathways across FDA, EU MDR, and PMDA jurisdictions. Segmentation strategy determines which portfolios scale without reformulation costs versus which require geography-specific manufacturing.
Product Type:
Domestic production dominates fluoride and non-fluoride pastes serving institutional procurement in the United States, Germany, and Japan. Export-led manufacturing concentrates in whitening and herbal variants targeting cosmetic dentistry channels with weaker reimbursement alignment.
- Fluoride Paste:Contains sodium fluoride or stannous fluoride in glycerin-suspended abrasive bases, formulated to 900-1500 ppm fluoride concentration per FDA dental monograph standards. General dentistry procurement in United States dental clinics drives volume concentration, constrained by state-level dental board fluoride limit divergence that fragments interstate distribution.
- Whitening Paste:Incorporates higher-index synthetic silica or perlite abrasives with hydrogen peroxide precursors for extrinsic stain oxidation. Patient self-funding in United States metropolitan cosmetic dentistry practices concentrates demand, with premium positioning supported by chairside procedure bundling.
- Non-Fluoride Paste:Glycerin-based formulations without fluoride salts, positioned for pediatric sensitivity protocols and fluoride-averse patient segments. German dental clinics favor these for preventive care expansion under statutory insurance frameworks.
- Herbal Paste:Plant-derived antimicrobial extracts in water-based carriers, targeting home care and alternative medicine channels. Japanese import pathways face PMDA JIS biocompatibility testing barriers that limit non-certified manufacturer access.
Fluoride paste commands the established base. The steepest expansion runs through whitening paste.
Application:
Cost tier stratification separates reimbursement-aligned institutional segments from patient-funded aesthetic procedures. Volume concentration tracks preventive care protocol expansion while margin pools concentrate in self-pay channels.
- General Dentistry:Routine prophylaxis protocols in institutional settings, dominated by fluoride paste procurement through group purchasing organizations. United States dental clinics drive volume through expanded preventive care reimbursement.
- Cosmetic Dentistry:Aesthetic polishing and whitening procedures with direct patient payment, bypassing traditional procurement committees. United States metropolitan markets concentrate volume where practice management software enables transparent chairside pricing.
- Pediatric Care:Low-abrasivity formulations with flavor-optimized carriers for compliance in children. German statutory insurance coverage supports volume concentration.
- Geriatric Care:Reduced-abrasion pastes for enamel-compromised patients, often paired with desensitizing agents. Japan's aging demographic drives demand concentration in Tokyo and Osaka dental clinics.
General dentistry absorbs the highest absolute volume. Cosmetic dentistry captures the fastest margin expansion.
Packaging Type:
Supply concentration in Mediterranean pumice regions and German perlite engineering shapes packaging format economics. Infection control protocol divergence between clinic and hospital settings drives format fragmentation.
- Sachet:Single-use foil or polymer pouches delivering pre-measured paste doses, eliminating cross-contamination risk. United States dental clinics adopt fastest for OSHA-aligned infection control compliance.
- Tube:Collapsible aluminum or laminate tubes for multi-dose dispensing, dominant in hospital central supply where multi-patient protocols govern procurement. German hospital networks resist format conversion due to legacy inventory systems.
- Jar:Wide-mouth containers for bulk chairside dispensing, concentrated in high-volume cosmetic dentistry practices. Japanese dental clinics favor these for perlite-based polishing agent access.
- Bottle:Pump-dispense containers for liquid prophylaxis preparations, niche positioning in research laboratory and specialized home care channels.
Tube packaging retains the volume base. Sachet adoption climbs fastest through clinic channel conversion.
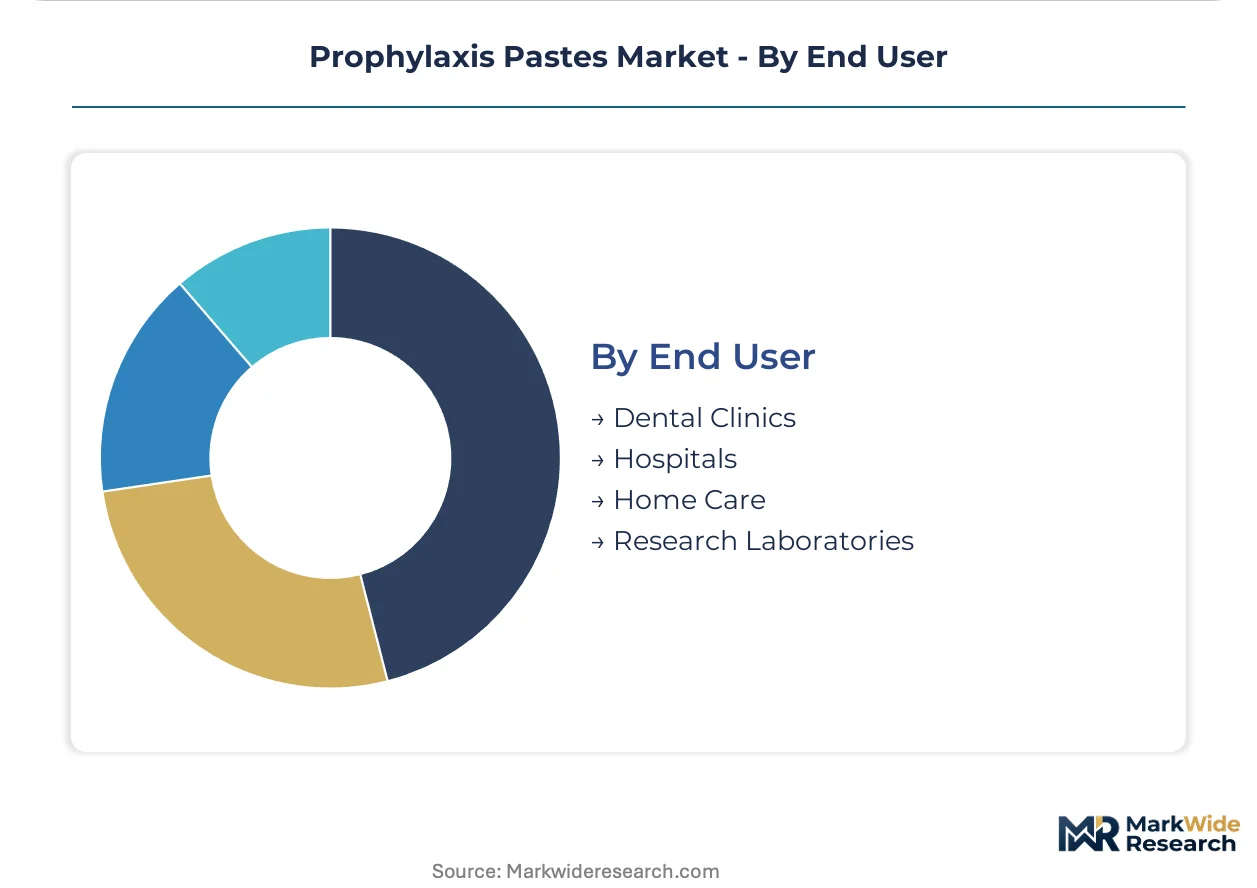
End User:
Customer type determines procurement influence structures, from institutional purchasing committees to individual clinician preference. Channel concentration varies sharply between reimbursement-driven and self-funded decision pathways.
- Dental Clinics:Independent and group practices where chairside clinician preference dominates paste selection. United States metropolitan cosmetic dentistry concentrates whitening paste demand.
- Hospitals:Central supply departments with multi-patient infection control protocols and group purchasing organization contracts. German hospital networks anchor fluoride paste volume through statutory framework alignment.
- Home Care:Direct-to-consumer retail and e-commerce channels for maintenance polishing between professional cleanings. Japanese consumers drive herbal paste interest through pharmacy retail.
- Research Laboratories:Academic and commercial R&D facilities evaluating abrasive technologies and biocompatibility profiles. ISO 13485 certification requirements limit supplier qualification.
Dental clinics anchor the revenue base. Home care emerges as the fastest-climbing channel through direct-to-consumer whitening product expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European dental supply chain connectivity, while the Los Angeles-Long Beach port complex underwrites Pacific Rim prophylaxis paste import volumes into North American clinical networks.
United States
Metropolitan cosmetic dentistry practices in Los Angeles and New York City drive whitening paste premiumization through self-funded patient procedures. The FDA's Class I medical device classification for abrasive dental preparations tightens formulation standards for interstate distribution. Texas dental clinic chains anchor volume procurement through group purchasing organization contracts aligned with expanded preventive care reimbursement.
Germany
Statutory insurance frameworks in Bavaria and North Rhine-Westphalia support preventive care protocol expansion across dental clinic networks. The EU MDR mandates updated technical documentation and clinical evaluation for abrasive dental products entering European markets. The Rhine-Ruhr industrial corridor concentrates perlite-based polishing agent engineering from specialized chemical manufacturers.
Japan
Tokyo and Osaka dental clinics concentrate geriatric care demand as the national demographic ages rapidly. The PMDA enforces JIS-compliant biocompatibility testing that limits import pathways for non-certified manufacturers. The Kansai region anchors domestic production of herbal paste variants targeting pharmacy retail channels.
China
Shanghai and Beijing dental clinic networks expand cosmetic dentistry capacity to serve affluent urban patient segments. The NMPA oversees medical device registration for imported abrasive dental preparations with extended review timelines. The Yangtze River Delta concentrates contract manufacturing for export-oriented fluoride paste formulations.
Prophylaxis Pastes Market Competitive Landscape
Listed leaders compete with private specialists across certification compliance, where ISO 13485 quality management bifurcation separates qualified manufacturers from commodity suppliers. The competitive structure concentrates around three strategic tiers: integrated dental platform operators, clinician-centric formulation specialists, and regional abrasive technology engineers. Dominant competitive moves include proprietary delivery system integration and single-use packaging format conversion to capture infection control compliance demand.
Within the integrated platform tier, Dentsply Sirona and 3M occupy positions that leverage recurring paste sales through captive distribution infrastructure. Among German-engineered specialists, VOCO GmbH exemplifies consistency-driven competitive positioning. Ultradent Products Inc. represents the North American professional channel focus archetype. These three anchors illustrate how geographic origin and organizational structure map to distinct competitive vectors without overlapping strategic territory.
| Leading Market Players |
|---|
| 3M |
| Dentsply Sirona |
| VOCO GmbH |
| Keystone Industries |
| Ultradent Products Inc. |
| Young Dental |
| Kerr Corporation |
| Premier Dental |
| Ivoclar Vivadent |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Mediterranean pumice extractors and German perlite processors lock in both abrasive supply access and price visibility for prophylaxis paste manufacturers navigating glycerin input volatility from biodiesel co-production cycles.
Pricing Analysis
Volume-discount tiering structures separate institutional procurement through group purchasing organizations from chairside clinician purchases in cosmetic dentistry practices. Three-tier pricing stratifies across ISO 13485-certified premium formulations, standard fluoride pastes, and economy-grade pumice-based alternatives. Pricing pressure stems from glycerin cost compression in water-based formulations as biodiesel output fluctuates. Hospital central supply departments exhibit highest price sensitivity due to multi-year contract lock-ins, while metropolitan cosmetic dentistry practices show lowest sensitivity where patients self-fund aesthetic procedures.
Supply Chain Analysis
Mediterranean volcanic belt transit underwrites natural pumice supply for abrasive base production, with concentrated extraction in Italy, Turkey, and Greece. German-engineered perlite alternatives draw from domestic industrial mineral processing, reducing geographic dependency. Raw material inputs hinge on glycerin from biodiesel refining, synthetic silica from chemical manufacturers, and fluoride salts from phosphate mining operations. Single-source vulnerability concentrates in Mediterranean pumice regions exposed to geopolitical disruption. Distribution runs through dental supply distributors serving clinic networks, with direct manufacturer relationships dominating hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
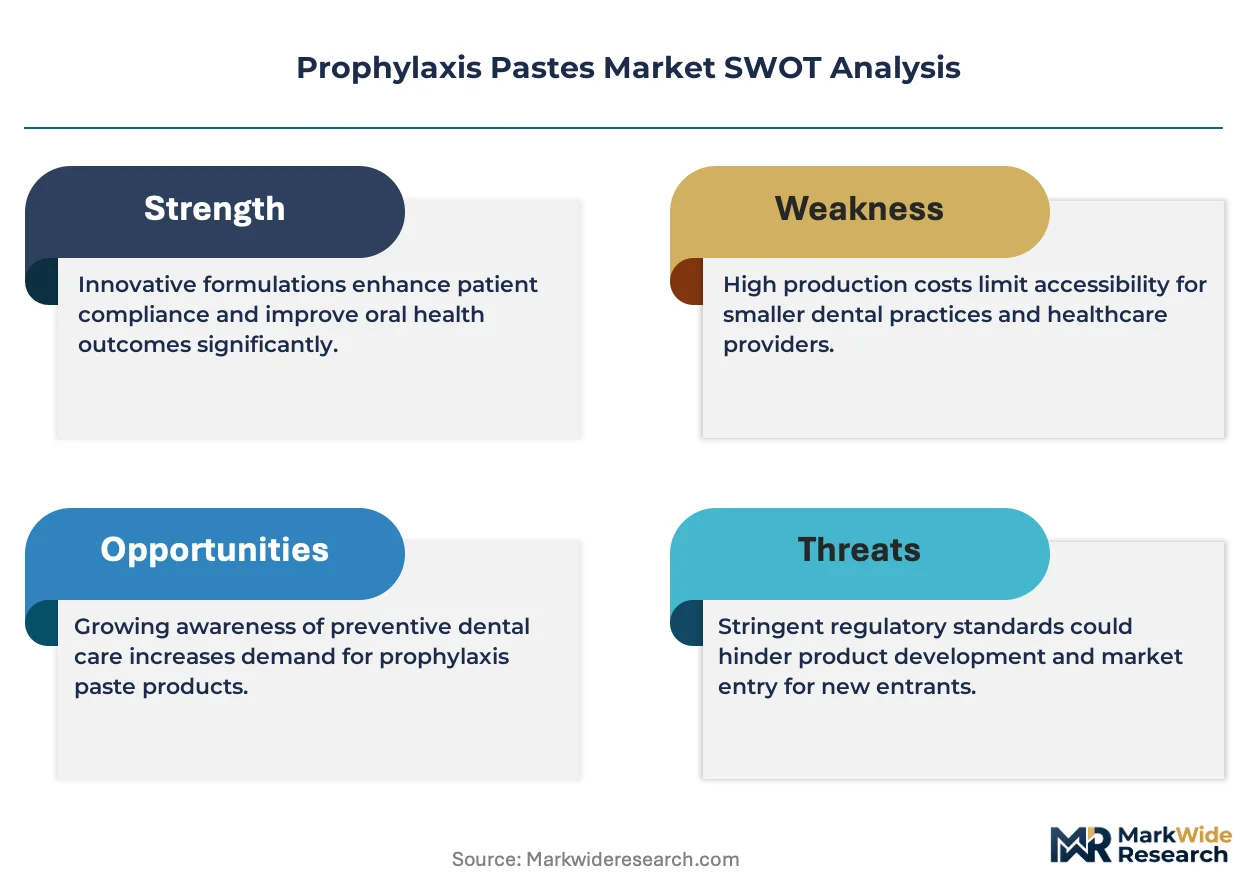
The prophylaxis pastes market functions as a defensive-moat story where ISO 13485 certification creates regulatory entrenchment that locks out commodity suppliers and protects incumbent margin structures through reformulation cost barriers.
For Market Incumbents: Fortify market position through backward integration into synthetic silica production to offset Mediterranean pumice supply concentration risks, while accelerating single-use sachet format conversion to capture infection control compliance demand from United States dental clinics. Channel control through proprietary delivery system integration represents the critical lever against emerging perlite-based formulation specialists. For New Entrants and Emerging Players: Differentiate on JIS-compliant biocompatibility certification to access Japan's protected geriatric care market, where PMDA testing requirements limit import competition. The most penetrable white-space target sits in herbal paste variants for Japanese pharmacy retail channels, with direct-to-consumer e-commerce serving as the viable go-to-market angle bypassing institutional procurement committees. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap ISO 13485-certified manufacturers with established European notified body relationships, as EU MDR compliance burdens intensify competitive sorting. Long-term viability over a multi-year window favors targets with dual-format packaging capabilities bridging clinic sachet adoption and hospital tube persistence. The signal to watch is fluoride concentration guideline divergence between EFSA and state-level dental boards forcing portfolio fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Creates regulatory barrier against commodity suppliers in EU MDR and PMDA jurisdictions. |
| Single-Use Sachet Manufacturing Scale-Up | Captures OSHA-aligned infection control demand from United States dental clinic networks. |
| Synthetic Silica Backward Integration | Reduces dependency on Mediterranean pumice supply concentration and quality inconsistency. |
| Japan PMDA JIS Compliance Pathway | Unlocks protected market access in aging demographic concentrated in Tokyo and Osaka. |
| Whitening Paste Premium Positioning | Exploits patient self-funding in metropolitan cosmetic dentistry bypassing reimbursement constraints. |
Research Methodology
The analysis maps fluoride paste, whitening paste, non-fluoride, and herbal formulation sub-sectors, each validated through dental clinic procurement managers, hospital central supply directors, GPO contract specialists, and abrasive technology R&D leads. Primary interviews with these stakeholders combined trade data from customs records, FDA medical device registration databases, and EU MDR notified body filings. Secondary validation drew from dental industry association reports, statutory insurance framework documentation, and SEC filings of listed dental supply manufacturers. Bottom-up paste volume modeling triangulated against top-down market sizing from reimbursement data and procedure volume estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including formulation chemistry, application setting, packaging format, and end-user procurement structure. CAGRs derived from procedure volume growth trajectories, reimbursement framework evolution, and patient self-funding penetration in cosmetic channels. Industry-specific forecast inputs incorporated fluoride concentration regulatory divergence scenarios and glycerin price cycle assumptions from biodiesel co-production economics.
The analysis sits within stated boundaries; outcomes outside sustained preventive care reimbursement expansion or stable Mediterranean pumice supply access would require recalibration. Forecasts reflect documented assumptions on regulatory convergence timelines and patient payment behavior shifts. Practitioners should keep alternative scenarios live as EU MDR enforcement intensity and Japan's PMDA import pathway requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Dam Market
Dental Devices
Dental Implant Motors Market
Dental Devices
Surgical Dental Loupes and Camera Market
Dental Devices
Periodontal Scalers and Curettes Market
Dental Devices
Intraoral Dental Scanner Market
Dental Devices
Dental Diamond Burs Market
Dental Devices
Dental Orthodontic Wax Market
Dental Devices
Dental Handpieces Market
Dental Devices
Dental Chair Market
Dental Devices
Global Dental Microscope Market
Dental Devices
Dental Suction Systems Market
Dental Devices
Nano Dentistry Market
Dental Devices
Dental Composite Resin Filling Market
Dental Devices
Dental Needle Market
Dental Devices
Malocclusion Market
Dental Devices
Netherlands Dental Devices Market