
 United Kingdom Dental Devices Market | 2026-2036
United Kingdom Dental Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Dental Devices Market Analytics
Hospital procurement frameworks is tilting toward consolidated supplier agreements across NHS trusts and private chains. Dentsply Sirona leverages its integrated CAD/CAM workflow to anchor large-format clinic deployments. Straumann Group specializes in premium implantology systems that occupy the consultant-grade segment. Henry Schein competes through distribution density, controlling last-mile logistics to independent practices nationwide.
United Kingdom dental devices comprise instruments, materials, and equipment engineered to ISO 13485 quality management standards for diagnosis, treatment, and restoration of oral conditions. These products must achieve UKCA marking conformity following Great Britain's regulatory separation from EU CE marking frameworks. Dental implants command the highest value per procedure within product type segmentation, while digital imaging and CAD/CAM systems represent the fastest-expanding technology category as practices retire analog workflows. General dentistry generates the largest procedure volume among applications, though cosmetic dentistry carries superior margin profiles due to private-pay dynamics.
The Medicines and Healthcare products Regulatory Agency enforces post-market surveillance for implantable dental devices, elevating documentation burdens for manufacturers seeking UKCA certification. The General Dental Council regulates clinical practice standards, indirectly shaping equipment specifications through training curriculum requirements. Stakeholders must monitor divergence between UKCA and EU MDR technical documentation demands, as dual-compliance costs will influence supplier selection and pricing structures.
Market Dynamics
Digital dentistry adoption is compressing equipment replacement cycles across United Kingdom practices as NHS trusts and private chains accelerate CAD/CAM procurement timelines. The Medicines and Healthcare products Regulatory Agency's UKCA marking requirements are restructuring supplier qualification processes.
Growth Catalysts
- UKCA Regulatory Harmonization:The Medicines and Healthcare products Regulatory Agency's post-market surveillance rules for implantable devices are elevating documentation standards that favor established manufacturers with regulatory infrastructure.
- Cosmetic Procedure Volume:Private-pay cosmetic dentistry in England's south-east corridor is expanding chairside digital workflow investments as specialist practices cluster around London and Manchester.
- Consolidated Procurement Frameworks:NHS trust purchasing alliances are standardizing equipment specifications across hospital networks, creating volume commitments that stabilize manufacturer revenue visibility.
Market Restraints
- Dual-Compliance Cost Burden:Divergence between UKCA and EU MDR technical documentation demands is inflating certification expenses for manufacturers serving both markets.
- Specialist Workforce Density:Consultant-grade implantology capacity concentrates in London, Manchester, and Birmingham, limiting addressable market expansion into secondary cities.
- Capital Equipment Intensity:Chairside milling units and intraoral scanners require substantial upfront investment that constrains independent practice upgrade velocity.
Strategic Opportunities
- Scotland and Wales Penetration:Specialist dental device distribution remains underdeveloped outside England's core corridor, presenting channel expansion potential.
- Tele-diagnostics Integration:Remote consultation platforms are converging with intraoral scanning data, enabling pre-appointment treatment planning that compresses chair time.
- General Dental Council Curriculum Alignment:Training mandate updates for digital workflow competency are creating captive demand cycles tied to educational procurement.
Industry Challenges
- CAD/CAM Technician Scarcity:Digital design expertise lags equipment installation rates, creating bottlenecks in same-day restoration delivery.
- Legacy Analog Integration:Hybrid practices managing both digital and conventional workflows face inventory duplication and staff training fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Dental Devices Market |
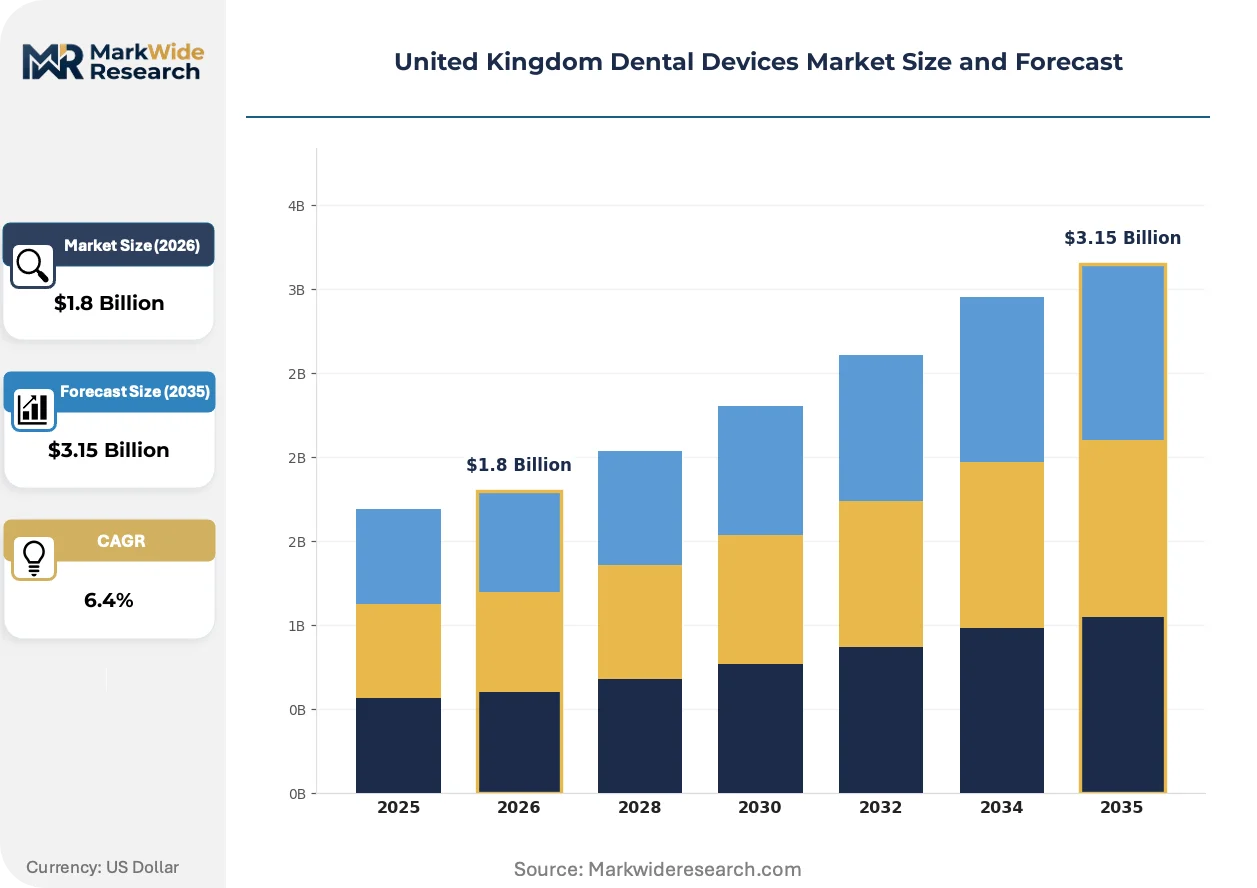
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dental Implants, Orthodontic Devices, Dental Instruments, Restoration Materials Application: Cosmetic Dentistry, General Dentistry, Oral Surgery, Periodontics End User: Dental Clinics, Hospitals, Research Laboratories, Dental Schools Technology: 3D Printing, Laser Dentistry, CAD/CAM Systems, Digital Imaging |
| Companies Covered | Envista Holdings Corporation, Carestream Dental, Dentsply Sirona, A-Dec Inc, Planmeca Oy, Straumann Group, GC Corporation, Henry Schein, 3M Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Dental Devices Market Evolving Landscape
Workflow digitization is restructuring competitive positioning across United Kingdom dental practices as equipment specifications become procurement decision criteria. Three developments are compressing technology adoption timelines.
Intraoral scanning systems are capturing digital impressions that eliminate physical mold production. Specialist practices in London and Manchester are deploying these units at replacement cycles of four to five years versus the previous decade for analog equipment. The technology is migrating from diagnostic adjunct to primary impression capture, collapsing laboratory turnaround times and enabling same-day restoration delivery.
The Medicines and Healthcare products Regulatory Agency's tightened post-market surveillance for implantable dental devices is extending documentation retention periods. Manufacturers must now maintain clinical performance records across device lifecycles. Implantology system suppliers face the steepest compliance burden as they restructure quality management systems to satisfy UKCA certification demands.
Independent practices are consolidating purchasing through dental service organizations to access volume pricing on capital equipment. These buying cooperatives are displacing traditional distributor relationships in secondary English cities. The concentration is most visible in the Midlands where practice group formation is accelerating equipment standardization across affiliated clinics.
United Kingdom Dental Devices Market Segmentation
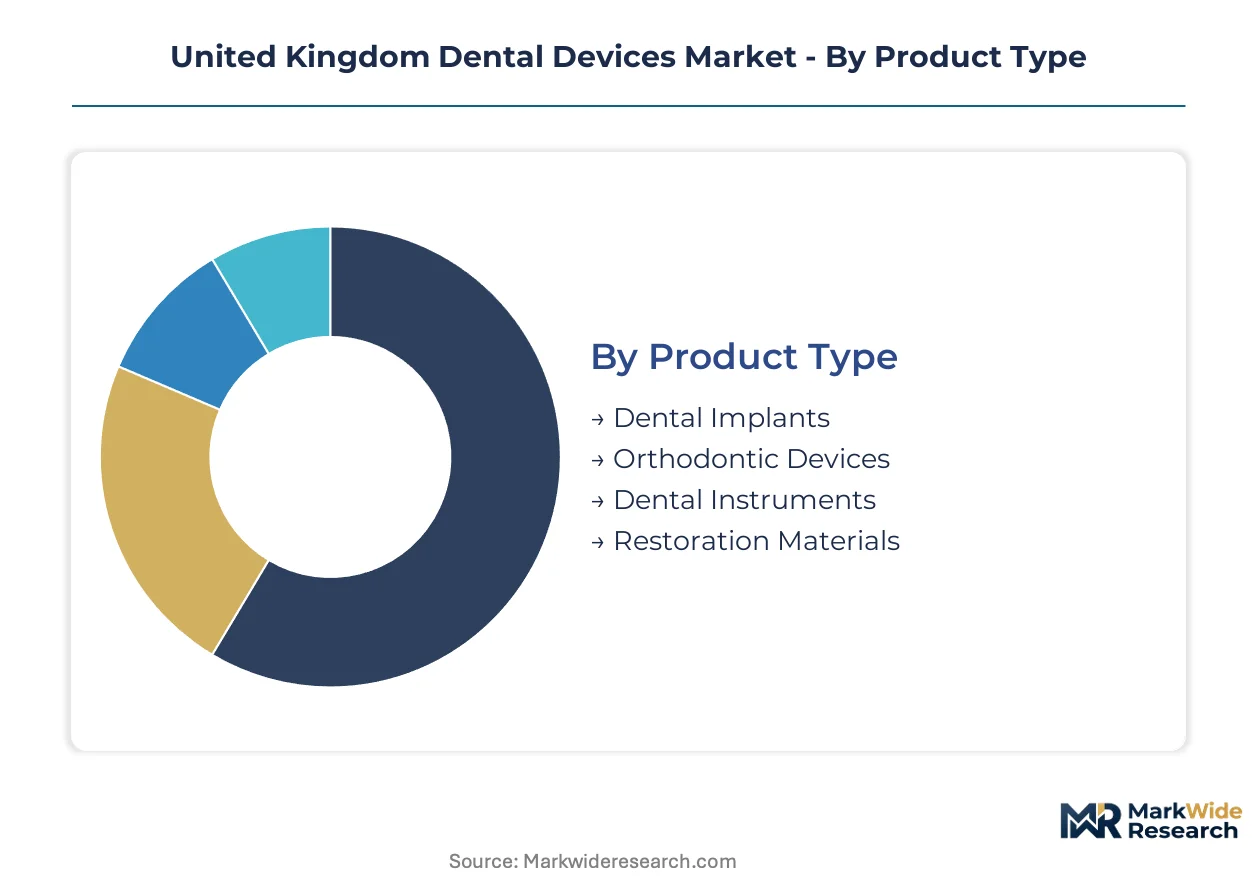
Segmentation in United Kingdom dental devices reveals how procurement patterns diverge between NHS hospital networks and private specialist practices. Understanding these divides exposes where margin capture concentrates and where volume commitments stabilize manufacturer revenue.
Product Type:
Cost tier separation across product categories determines which manufacturers anchor premium positioning versus commodity supply relationships.
- Dental Implants:Titanium and zirconium-based fixtures engineered for osseointegration carry the highest per-procedure value in United Kingdom dentistry. Consultant-grade implantology in London and Manchester drives demand for premium surface-treated systems as MHRA post-market surveillance extends documentation retention across device lifecycles.
- Restoration Materials:Ceramic composites and hybrid resins formulated for chairside milling applications are climbing the fastest as practices retire analog impression workflows. Specialist clinics in England's south-east corridor are standardizing on lithium disilicate blocks for same-day crown delivery.
- Orthodontic Devices:Clear aligner systems and fixed bracket assemblies serve adolescent and adult correction protocols across NHS and private channels.
- Dental Instruments:Handpieces, scalers, and diagnostic tools represent high-frequency replacement purchases with shorter procurement cycles than capital equipment.
Dental implants hold installed capacity. Restoration materials is rotating up the share rankings.
Application:
Margin structure across dental applications separates private-pay cosmetic procedures from reimbursed general dentistry volume.
- Cosmetic Dentistry:Veneer placement, whitening systems, and aesthetic alignment procedures command superior pricing power through direct patient payment. Practices clustering around London's Harley Street district are investing in digital smile design software to compress treatment planning cycles.
- General Dentistry:Routine examination, prophylaxis, and basic restoration generates the largest procedure volume across United Kingdom practices. NHS contract frameworks in England standardize equipment specifications across affiliated clinics, creating predictable replacement demand for core instrumentation.
- Oral Surgery:Extraction and bone grafting procedures require specialized handpieces and regenerative material portfolios.
- Periodontics:Gum tissue management and implant site preparation concentrates in specialist referral practices with advanced surgical capabilities.
General dentistry holds installed capacity. Cosmetic dentistry is rotating up the share rankings.
End User:
Customer type concentration shapes whether procurement flows through consolidated frameworks or fragmented independent channels.
- Dental Clinics:Independent practices and corporate chains account for the majority of United Kingdom device procurement as patient volumes shift from hospital settings. Dental service organizations in the Midlands are consolidating purchasing to access volume pricing on intraoral scanners and milling units.
- Hospitals:NHS trust networks operate through centralized procurement alliances that standardize implantology and surgical equipment across regional networks. These frameworks favor suppliers with regulatory infrastructure to satisfy MHRA UKCA documentation demands.
- Research Laboratories:Academic and commercial R&D facilities drive early-stage adoption of novel biomaterials and manufacturing processes.
- Dental Schools:Training institutions create captive demand cycles tied to General Dental Council curriculum updates for digital workflow competency.
Dental clinics hold installed capacity. Hospitals is rotating up the share rankings.
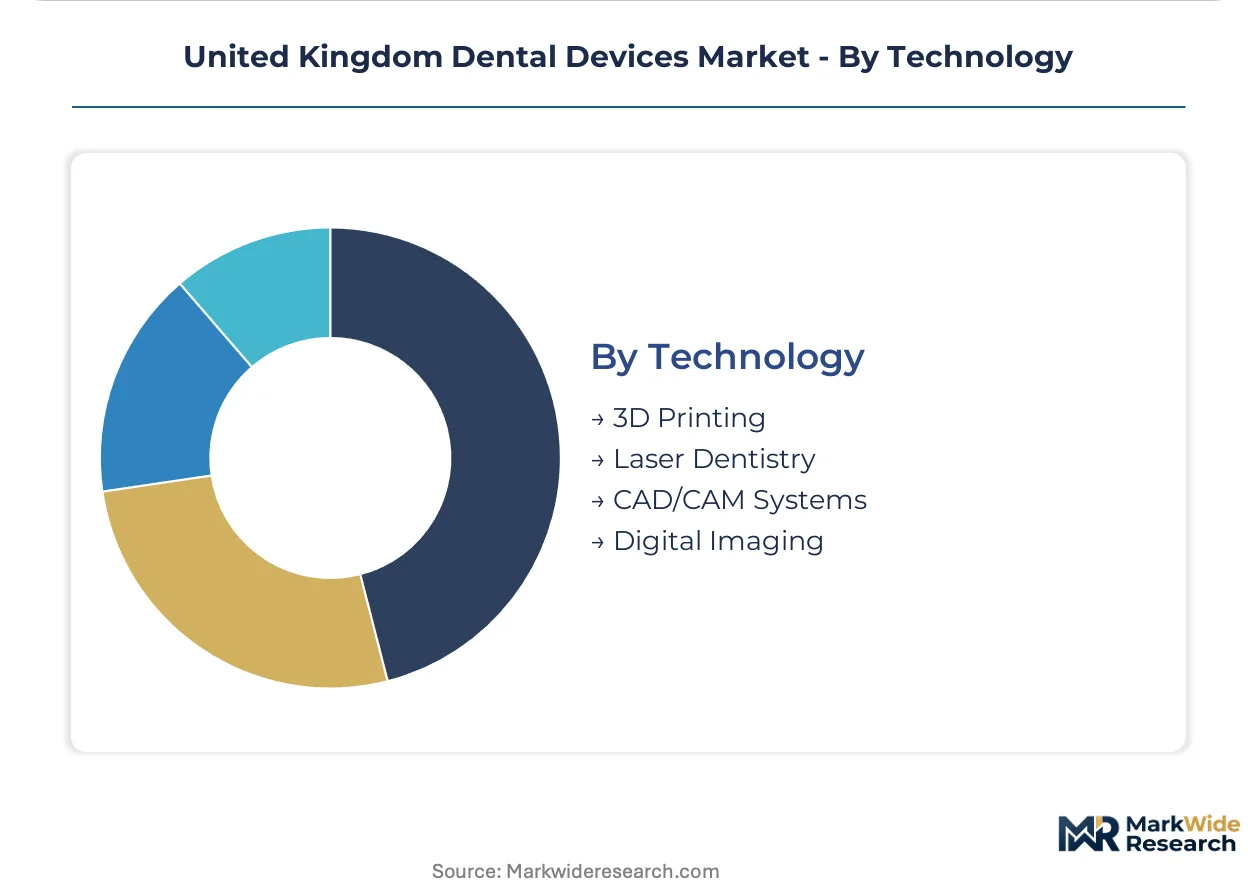
Technology:
Technology maturity curves determine replacement cycle compression and which vendors capture upgrade revenue.
- CAD/CAM Systems:Chairside milling units and design software are displacing laboratory-dependent workflows as replacement cycles compress from ten years to four-to-five years. Private chains in Manchester are deploying integrated systems to enable same-day restoration delivery.
- Digital Imaging:CBCT scanners and intraoral radiography systems are expanding from diagnostic adjunct to treatment planning standard across United Kingdom specialist practices. Equipment specifications are becoming procurement decision criteria as practices retire analog impression methods.
- 3D Printing:Photopolymer and metal powder bed systems are penetrating dental laboratories for surgical guide and model production.
- Laser Dentistry:Soft and hard tissue lasers occupy niche applications in periodontal and cosmetic procedures with slower adoption velocity than scanning technologies.
CAD/CAM systems hold installed capacity. Digital imaging is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The East Coast Main Line rail corridor underwrites England's dominance in United Kingdom dental device distribution, connecting London's specialist clusters to manufacturing and logistics hubs in the Midlands and North.
London and Southeast England
Harley Street cosmetic practices and NHS hospital trusts drive demand for premium implantology systems and CAD/CAM workflows. The Medicines and Healthcare products Regulatory Agency's UKCA marking requirements filter supplier eligibility for implantable devices entering this high-value corridor. Specialist clinics cluster around London's medical district, concentrating procurement volumes for chairside milling units.
Midlands
Dental service organizations in Birmingham and Leicester are consolidating independent practices into purchasing cooperatives. NHS procurement alliances standardize equipment specifications across West Midlands hospital networks. Manufacturing logistics hubs near Derby and Nottingham supply distribution channels radiating into secondary cities.
North England
Manchester's specialist implantology market anchors demand for consultant-grade systems in the northwest. Private chains accelerate CAD/CAM procurement timelines as they compete with London practices for cosmetic dentistry revenue. Leeds and Sheffield host regional distribution centers serving Yorkshire's mixed NHS-private practice base.
Scotland
NHS Scotland's centralized health boards create uniform procurement frameworks distinct from England's trust-based system. Edinburgh and Glasgow concentrate specialist dental services, though device distribution infrastructure remains less developed than England's core corridor. Scottish dental schools generate curriculum-driven demand for training equipment aligned with General Dental Council competency standards.
Wales
Welsh health boards operate consolidated equipment purchasing that favors suppliers with established UKCA regulatory infrastructure. Cardiff hosts the primary specialist cluster, with limited penetration of premium digital workflows into rural practices. Distribution channel development lags England's density, presenting expansion opportunities for logistics networks.
United Kingdom Dental Devices Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in materials and instrument supply. The United Kingdom market structures around three tiers: multinational conglomerates with full CAD/CAM workflows, regional distributors controlling last-mile logistics, and niche biomaterial suppliers. Consolidation pressures intensify as NHS procurement alliances and dental service organizations concentrate purchasing power. Competitive moves center on regulatory infrastructure investment for UKCA compliance and distribution network densification into secondary cities.
Within the integrated platform tier, Dentsply Sirona and Straumann Group exemplify archetypes competing through workflow completeness versus premium implantology specialization. Henry Schein occupies the distribution density position, anchoring independent practice supply relationships nationwide. Envista Holdings Corporation represents the diversified dental technology conglomerate structure, sitting within portfolios spanning imaging, implants, and consumables.
| Leading Market Players |
|---|
| Envista Holdings Corporation |
| Carestream Dental |
| Dentsply Sirona |
| A-Dec Inc |
| Planmeca Oy |
| Straumann Group |
| GC Corporation |
| Henry Schein |
| 3M Company |
| Others |
Value Network & Pricing Analysis
German and Swiss precision-component manufacturing concentrates upstream supply for high-value dental implants and CAD/CAM systems, anchoring margin pools in downstream specialist practices across London and Manchester. This upstream concentration creates tiered pricing power that separates consultant-grade implantology from commodity instrumentation in NHS procurement frameworks.
Pricing Analysis
Volume-discount tiering structures dominate procurement across NHS trust alliances and dental service organizations, compressing margins for independent distributors. Three-tier pricing structure across premium, standard, and economy levels separates MHRA-certified implant systems from uncertified imports and basic handpiece replacements. Pricing pressure stems from consolidated purchasing power in the Midlands and North England, where buying cooperatives displace traditional distributor relationships. NHS hospital networks exhibit highest price sensitivity due to fixed contract frameworks, while Harley Street cosmetic practices demonstrate lowest sensitivity for same-day restoration capabilities.
Supply Chain Analysis
Export-control regimes limiting flows of dual-use laser and precision-milling technologies constrain chairside CAD/CAM system availability from German and Swiss suppliers. Component manufacturing concentrates in Germany, Switzerland, and the United States for titanium implant fixtures, ceramic milling blocks, and intraoral scanner optics. Raw material dependencies include medical-grade titanium alloys, zirconium oxide powders, and photopolymer resins for 3D-printed surgical guides. Single-source vulnerability runs through Swiss precision-motor suppliers for chairside milling spindles. Distribution runs through Henry Schein's national logistics network and regional dental service organization warehouses serving affiliated practice chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive outcomes as integrated CAD/CAM workflows displace standalone equipment purchases, rewarding ecosystem orchestrators over component vendors. Interoperability between intraoral scanners, design software, and chairside mills is becoming the primary procurement criterion for specialist practices.
For Market Incumbents: Build regulatory-documentation moats by expanding UKCA technical file capabilities ahead of EU MDR divergence. Dentsply Sirona and Straumann Group should deepen backward integration into ceramic-block manufacturing to capture restoration-material margins. Channel control through exclusive distributor agreements in Scotland and Wales defends against dental service organization consolidation. Threat from clear-aligner entrants with direct-to-consumer scanning requires software-companion investments.
For New Entrants and Emerging Players: Welsh health board procurement and Scottish NHS centralized purchasing represent underpenetrated channels with less established supplier relationships than England's core corridor. Target mid-tier independent practices in Leeds and Sheffield with subscription-based CAD/CAM access models that bypass capital-intensity barriers. White-space exists in tele-diagnostics platforms integrating intraoral scan data with remote treatment planning. Go-to-market through General Dental Council-accredited training institutions creates curriculum-driven demand cycles.
For Investors and Strategic Acquirers: Capital is best deployed toward biomaterial specialists with UKCA certification infrastructure and ceramic-composite IP. Long-term viability across the analysis window favors suppliers with regulatory separation from EU MDR compliance costs. Acquisition archetype: niche milling-block manufacturers with lithium-disilicate formulations and established MHRA quality-system relationships. Signal to watch is NHS trust procurement alliance consolidation velocity in the West Midlands.
| Strategic Initiative | Industry Significance |
|---|---|
| UKCA Certification Infrastructure Investment | MHRA post-market surveillance rules favor manufacturers with established documentation systems over EU-dependent competitors. |
| Backward Integration into Ceramic Manufacturing | Lithium-disilicate block production captures restoration-material margins as chairside milling accelerates. |
| Dental Service Organization Partnership | Consolidated purchasing in the Midlands creates volume commitments that stabilize manufacturer revenue visibility. |
| Software Companion Development | Digital smile design platforms differentiate cosmetic practices competing for private-pay revenue in London. |
| Scotland and Wales Distribution Expansion | Underdeveloped specialist-device infrastructure outside England's core corridor presents channel growth potential. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of MHRA device registrations, NHS procurement databases, and General Dental Council curriculum documentation. Primary interviews engaged implantology consultants, hospital purchasing committee members, biomedical engineers at NHS trusts, and procurement directors at dental service organizations. Secondary validation drew from UKCA certification records, GPO contract disclosures, and customs import data for dental equipment. Bottom-up practice-level equipment counts triangulate against top-down manufacturer shipment estimates.
Forecast inputs include procedure-volume projections across cosmetic and general dentistry segments, replacement-cycle compression for digital versus analog equipment, and regulatory-compliance cost trajectories. Modeled dimensions span product type, application, end-user category, and technology maturity tier. CAGRs derive from equipment-installation base growth, procedure-volume elasticity, and average-selling-price trends. Industry-specific inputs incorporate NHS contract framework renewal schedules and private-practice consolidation rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by clear-aligner direct-to-consumer entrants or tele-diagnostics platforms would shift outcomes. Material shifts in UKCA-EU MDR regulatory divergence, NHS procurement centralization policy, or ceramic-biomaterial supply constraints would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
RFID-Enabled Dental Printing Market
Dental Devices
CBCT Dental Imaging Market
Dental Devices
Dental Hand Tools Market
Dental Devices
Dental Splints Market
Dental Devices
Dental Crown Removal Market
Dental Devices
Chile Dental Market
Dental Devices
Teeth Whitening Pen Market
Dental Devices
Global Digital Dentistry Market
Dental Devices
Global Dental Lasers Market
Dental Devices
Europe CBCT Dental Imaging Market
Dental Devices
Dental Suction Mirror Market
Dental Devices
Plaque Disclosing Aids Market
Dental Devices
United States Dental Implants Market
Dental Devices
Dental 3D Scanners Market
Dental Devices
Dental Inlays and Onlays Market
Dental Devices
Dental CAD/CAM Market