
 Dental Sealants Market | 2026-2036
Dental Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Sealants Market Outlook
ISO 4049 certification for polymer-based restorative materials is redrawing competitive boundaries among dental sealant suppliers. 3M leverages its materials science heritage to sustain formulation leadership in resin-based systems. Dentsply Sirona anchors its position through integrated digital dentistry workflows that bundle sealants with diagnostic platforms. GC Corporation differentiates via glass ionomer chemistry expertise that spans both professional and public health channels.
Dental sealants are thin, protective coatings—typically composed of resin monomers like bis-GMA or urethane dimethacrylate with photoinitiator systems—that polymerize under visible light to form a micromechanically bonded barrier over occlusal surfaces. Their primary function is to seal pits and fissures against acid demineralization, reducing caries incidence in permanent and primary molars. Resin-based formulations command the dominant share of clinical preference due to superior retention rates and fluoride recharge compatibility, while glass ionomer alternatives occupy a growing niche in moisture-tolerant applications and community health settings where technique sensitivity must be minimized. Pediatric dentistry generates the fastest volume expansion as early intervention protocols gain institutional backing, though general dentistry retains the largest absolute procedure count.
FDA 510(k) clearance requirements govern sealant biocompatibility and mechanical performance thresholds for US market access, while CE marking under the EU Medical Device Regulation shapes European commercialization pathways and post-market surveillance obligations. ISO 10993 biological evaluation standards further constrain which monomer systems and filler compositions manufacturers can deploy across major markets. Stakeholders must monitor evolving regulatory distinctions between professional-use and over-the-counter preventive products, as classification shifts would reshape channel economics and competitive positioning.
Market Dynamics
School-based sealant programs in the United States are consolidating procurement volumes while ISO 4049 certification requirements fragment supplier tiers into certified and non-certified camps, reshaping competitive access to institutional channels.
Growth Catalysts
- Medicaid expansion for pediatric preventive services:State-level reimbursement mandates in the US are embedding sealants into standard early intervention protocols, driving procedure volume in community health settings.
- Bis-GMA formulation advances:Photoinitiator system refinements are extending working time and improving micromechanical bond strength, reducing technique sensitivity for general practitioners.
- Fluoride recharge compatibility:Resin-based systems that enable sustained ion release are gaining preference in public health programs seeking dual-function preventive materials.
Market Restraints
- Monomer raw material concentration:Specialty urethane dimethacrylate supply chains cluster with German and Japanese chemical suppliers, creating input vulnerability for formulators.
- FDA 510(k) clearance timelines:Biocompatibility testing under ISO 10993 standards extends product launch cycles by 18-24 months for novel filler compositions.
- Glass ionomer substitution in moisture-tolerant niches:Hydrophilic chemistry alternatives are capturing share in community settings where isolation control is inconsistent.
Strategic Opportunities
- Rural US school district penetration:Underresourced districts in Appalachia and the Mississippi Delta present volume expansion potential for mobile preventive dentistry programs.
- Digital workflow bundling:Integration of sealant placement with intraoral scanning and CAD/CAM systems creates stickier supplier-dentist relationships.
- EU Medical Device Regulation post-market surveillance:MDR-compliant manufacturers can leverage clinical data requirements as a barrier against lower-tier competitors.
Industry Challenges
- Photopolymerization technique standardization:Variability in curing light intensity and exposure protocols across dental schools creates inconsistent clinical outcomes and retention rate disputes.
- ISO 4049 certification backlog:Testing laboratory capacity constraints are delaying competitive repositioning for reformulated resin systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Sealants Market |
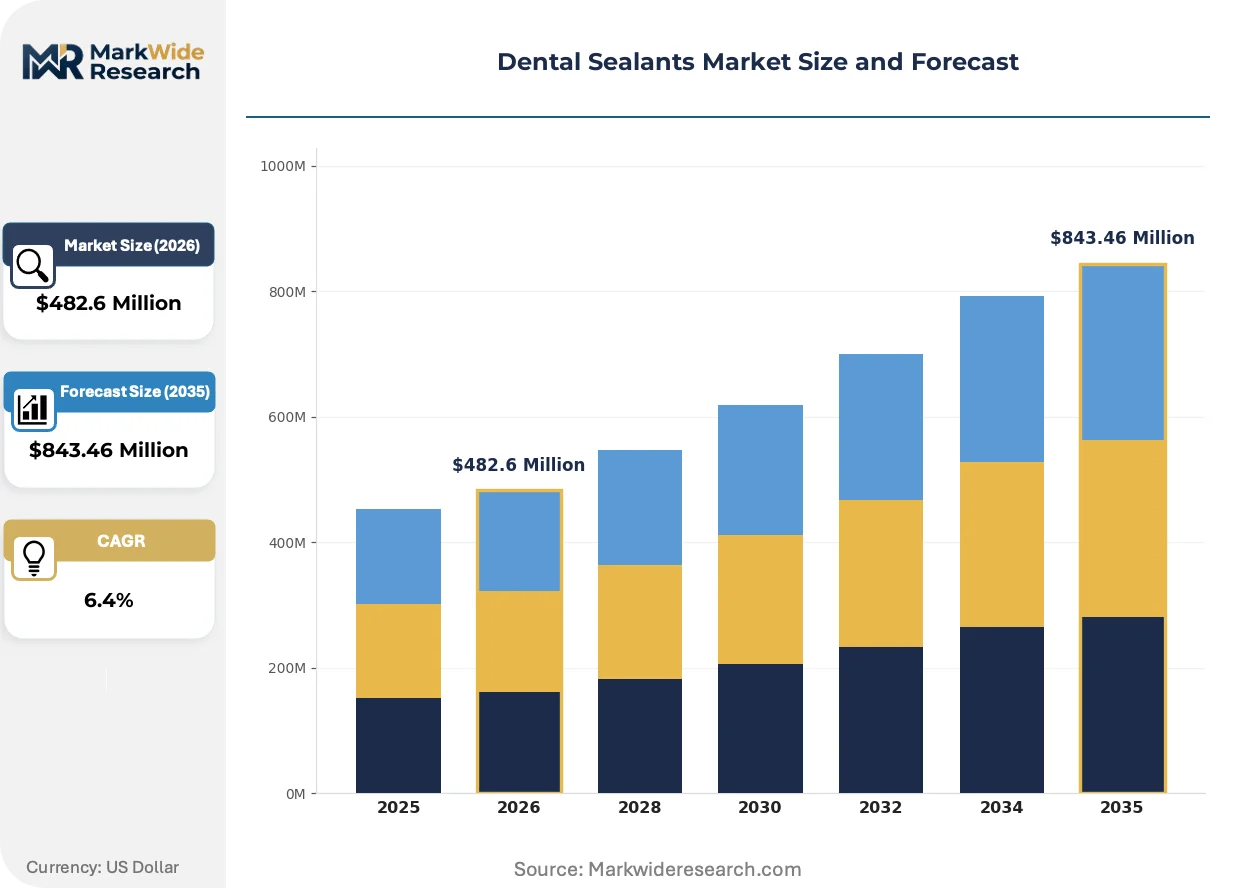
| Market Size in 2026 | $482.6 Million |
| Market Size in 2035 | $843.46 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Ionomer, Resin-based, Composite, Other Application: Pediatric Dentistry, Preventive Care, Orthodontics, General Dentistry End User: Dental Clinics, Hospitals, Research Institutions, Academic/Training Centers Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | 3M, Dentsply Sirona, Ivoclar Vivadent, GC Corporation, Kuraray Noritake Dental, Ultradent Products, SDI Limited, Pulpdent Corporation, BISCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Sealants Market Strategic Shifts
Material science convergence with digital dentistry workflows is redefining how sealants are specified, placed, and reimbursed, shifting value capture from standalone products to integrated preventive protocols.
Nano-hybrid filler technologies are fragmenting the traditional resin-glass ionomer dichotomy by delivering moisture tolerance approaching glass ionomer chemistries while retaining bis-GMA retention rates. Pediatric dental groups in the US Pacific Northwest are piloting these systems for school-based applications where field conditions compromise isolation. The result is fragmenting procurement categories as buyers reject legacy material classifications.
EU Medical Device Regulation post-market surveillance requirements are compelling manufacturers to maintain clinical performance registries for cleared sealant formulations. German dental associations are coordinating multi-practice outcome studies to satisfy MDR Article 83 obligations. French and Italian suppliers with limited clinical infrastructure face disproportionate compliance burdens relative to integrated multinationals.
Group purchasing organizations are consolidating dental supply procurement for multi-site practices and dental service organizations, compressing price negotiation cycles from annual to quarterly. DSOs in Texas and Florida are unbundling sealant purchases from broader consumable contracts to extract volume discounts. This concentration is most visible in Sun Belt states where practice consolidation has outpaced regulatory scrutiny of anticompetitive purchasing arrangements.
Dental Sealants Market Segmentation
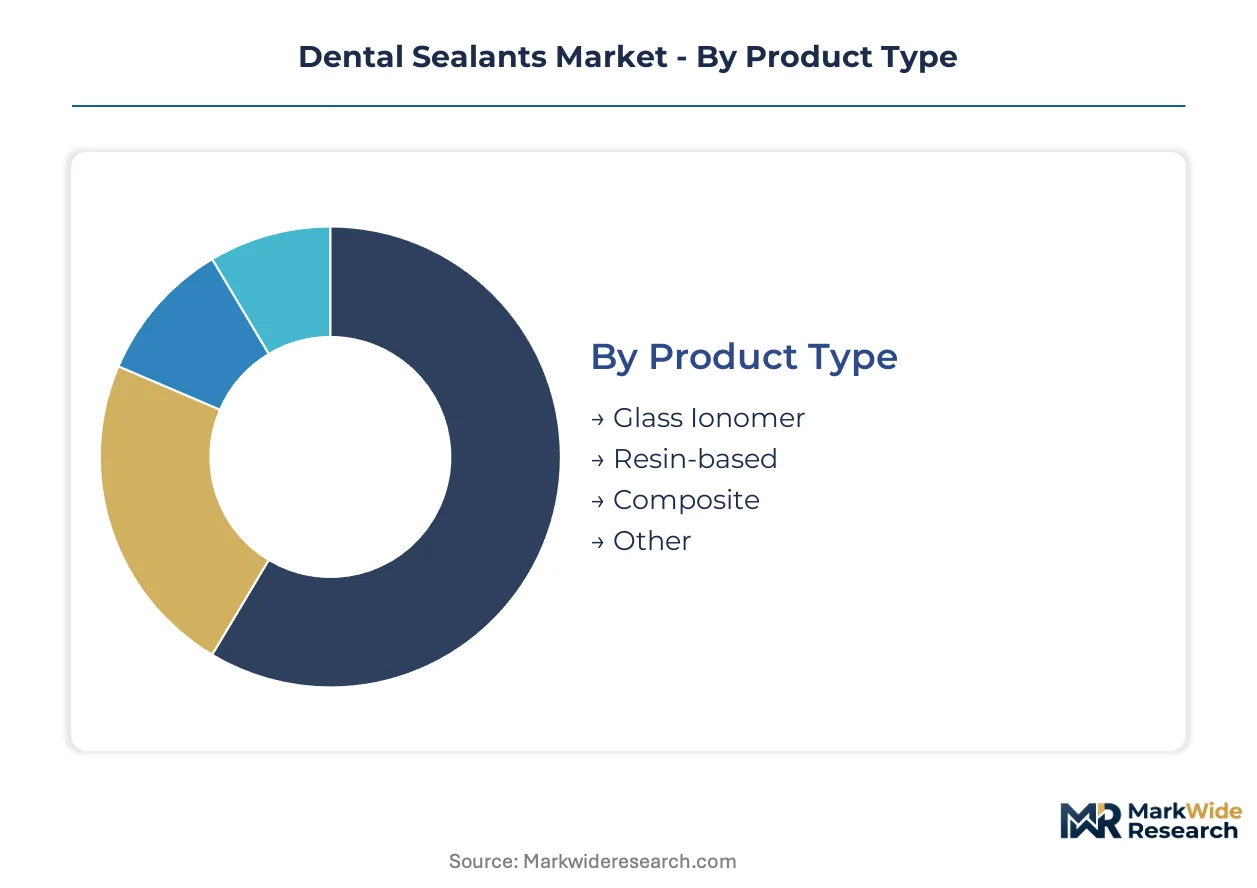
Dental sealant segmentation reveals distinct margin architectures across material chemistry, clinical setting, and procurement channel. Category boundaries are blurring as nano-hybrid formulations and digital workflow integration reshape how buyers evaluate value.
Product Type:
Resin-based systems command premium pricing in private practice channels while glass ionomer alternatives capture volume in public health tenders where moisture tolerance outweighs retention benchmarks.
- Resin-based:Bis-GMA and urethane dimethacrylate formulations polymerize under visible light to form micromechanically bonded barriers. Demand concentrates in US private practices where FDA 510(k) cleared photoinitiator systems justify reimbursement premiums through documented retention rates. Working time refinements are reducing technique sensitivity for general practitioners.
- Glass Ionomer:Hydrophilic polyalkenoate cement chemistry releases fluoride ions through acid-base reaction setting. School-based programs in Appalachia and the Mississippi Delta specify these materials where rubber dam isolation is impractical and field conditions compromise moisture control.
- Composite:Nano-filled restorative hybrids with sealant-adjacent indications serve dual-function roles in resource-constrained settings.
- Other:Experimental bioactive formulations and resin-modified glass ionomer intermediates occupy pre-commercial niches.
Resin-based holds installed capacity. Glass ionomer is rotating up the share rankings.
Application:
Procedure volume distributes unevenly across dental specialties, with pediatric protocols driving the steepest expansion trajectory as early intervention gains institutional backing.
- Pediatric Dentistry:Permanent and primary molar sealing in patients aged 6-14 dominates procedure growth. Medicaid expansion in Texas and Florida has embedded sealants into standard early intervention protocols, accelerating community health deployment.
- General Dentistry:Adult prophylaxis and maintenance procedures retain the largest absolute procedure count across US private practices. Retention rate disputes and photopolymerization technique variability create outcome inconsistency that constrains pricing power.
- Preventive Care:Public health screenings and mobile dentistry units in rural US districts concentrate procurement through consolidated tender processes.
- Orthodontics:Banding and bracket placement adjunct procedures represent a specialized niche with distinct adhesive compatibility requirements.
General Dentistry anchors absolute volume. Pediatric Dentistry is climbing the fastest.
End User:
Site-of-care economics fragment procurement patterns, with dental service organizations extracting volume discounts that independent practices cannot match.
- Dental Clinics:Multi-site DSOs in Sun Belt states unbundle sealant purchases from broader consumable contracts to drive quarterly price renegotiation cycles. Group purchasing organization concentration compresses supplier margins.
- Hospitals:Operating room and emergency department applications for trauma-related sealing represent a low-volume, high-specification segment.
- Academic/Training Centers:Dental schools in the US Pacific Northwest pilot nano-hybrid systems for technique standardization studies, creating reference site influence over graduate practice patterns.
- Research Institutions:Biocompatibility testing under ISO 10993 standards and novel filler composition studies occupy pre-market validation roles.
Dental Clinics hold installed capacity. Academic/Training Centers is rotating up the share rankings.
Distribution Channel:
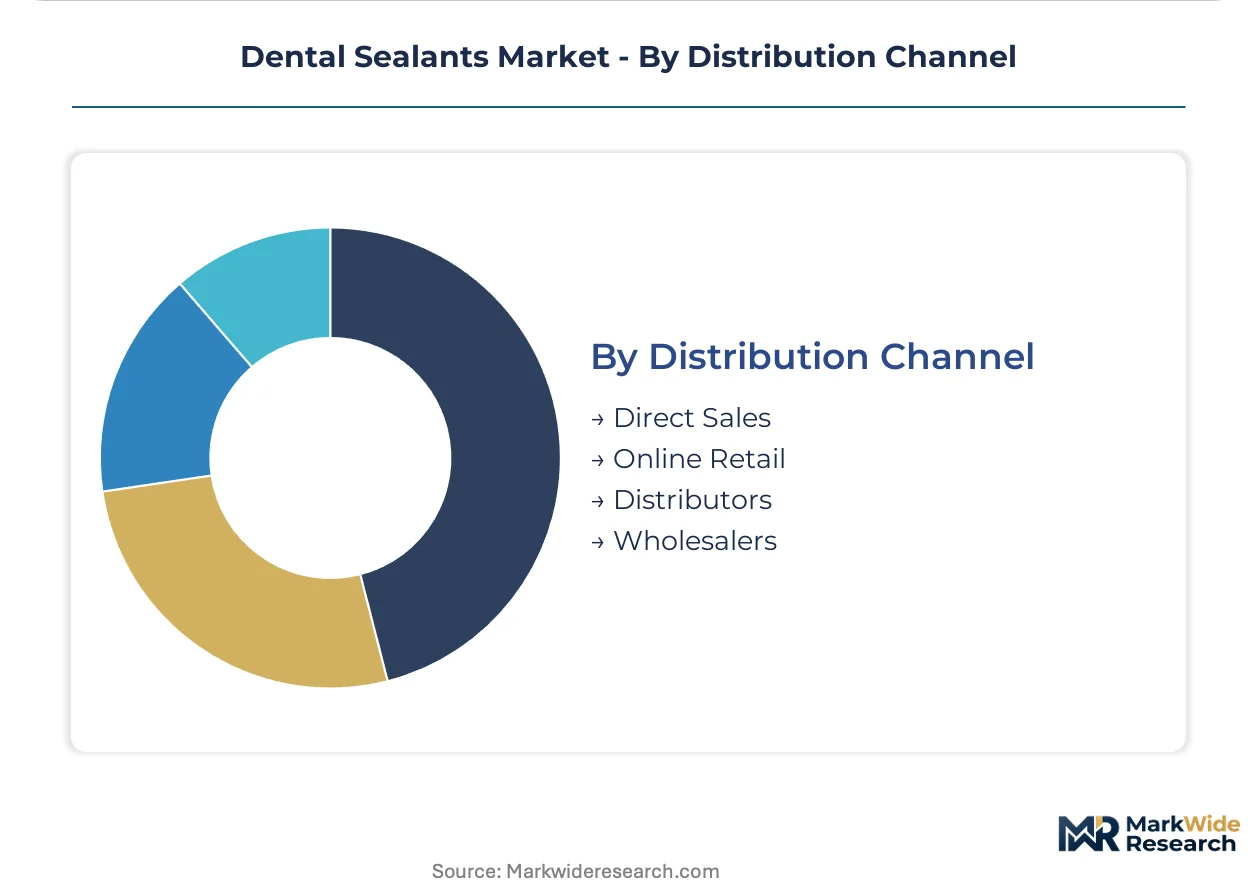
Channel selection reflects practice scale and inventory management sophistication, with direct relationships increasingly reserved for high-volume institutional accounts.
- Distributors:Henry Schein and Patterson Dental regional networks dominate mid-market practice supply, bundling sealants with chairside consumables and equipment service contracts.
- Direct Sales:3M and Dentsply Sirona field organizations serve DSO accounts with customized formulation and digital workflow integration packages.
- Online Retail:E-commerce penetration concentrates in solo practitioner and rural settings where distributor call frequency is insufficient.
- Wholesalers:Secondary distribution tiers serve cash-constrained practices with extended payment terms and generic alternatives.
Distributors hold installed capacity. Direct Sales is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical logistics infrastructure underwrites European supply security for specialty monomers, while the US Interstate highway network enables mobile dentistry units to reach rural school districts.
United States
School-based sealant programs in Texas and Florida drive pediatric procedure volume through Medicaid expansion mandates. FDA 510(k) clearance requirements govern biocompatibility testing timelines for novel resin formulations. The Mississippi Delta and Appalachian regions concentrate mobile preventive dentistry deployment where rubber dam isolation is impractical.
Germany
EU Medical Device Regulation post-market surveillance obligations compel manufacturers to maintain clinical performance registries for cleared formulations. German dental associations coordinate multi-practice outcome studies to satisfy MDR Article 83 requirements. The Rhine-Ruhr industrial corridor anchors specialty urethane dimethacrylate production for European formulators.
Japan
Glass ionomer chemistry expertise sustains export competitiveness across moisture-tolerant applications in Southeast Asian public health programs. PMDA consultation procedures shape pre-market validation pathways for novel photoinitiator systems. The Osaka-Kobe manufacturing cluster concentrates precision chemical synthesis for dental monomers.
India
CDSCO medical device registration requirements are tightening import standards for foreign sealant manufacturers seeking market access. State-level dental college networks in Maharashtra and Karnataka generate graduate practitioner demand that shapes regional procurement patterns. The Delhi-NCR corridor concentrates distributor logistics for northern Indian dental supply chains.
Brazil
ANVISA medical device regulations govern import licensing for resin-based preventive materials in Latin America's largest dental market. Public health dentistry programs in São Paulo state specify glass ionomer alternatives for community settings with inconsistent moisture control. The São Paulo metropolitan area anchors regional distribution for Mercosur dental supply networks.
Dental Sealants Market Competitive Environment
Listed leaders compete with private specialists across formulation chemistry and digital workflow integration. The market structure consolidates around multinational materials science conglomerates with dental divisions, while mid-tier regional formulators occupy price-sensitive public health channels. Strategic archetypes include integrated digital dentistry platforms, specialty chemical formulators, and regional distributors with private-label capabilities. Dominant competitive moves encompass ISO 4049 certification acquisition and school-based program procurement consolidation.
Within the integrated platform tier, 3M and Dentsply Sirona exemplify multinational scale advantages in digital workflow bundling. GC Corporation represents specialized glass ionomer chemistry expertise that spans professional and public health channels. These three anchors demonstrate how materials science heritage and regulatory compliance infrastructure create sustainable competitive positioning across divergent end-use segments.
| Leading Market Players |
|---|
| 3M |
| Dentsply Sirona |
| Ivoclar Vivadent |
| GC Corporation |
| Kuraray Noritake Dental |
| Ultradent Products |
| SDI Limited |
| Pulpdent Corporation |
| BISCO |
| Others |
Value Chain & Pricing Dynamics
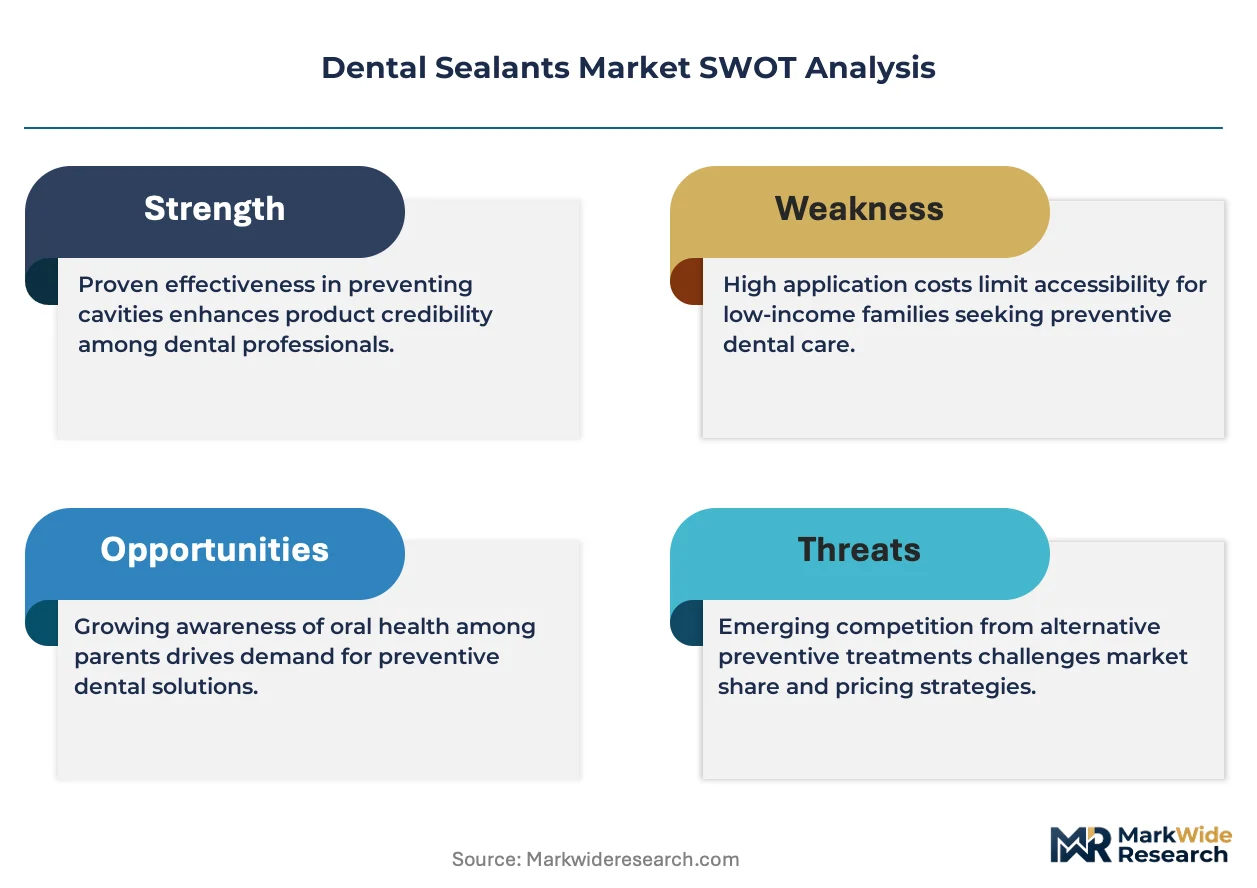
ISO 4049 certification backlog at testing laboratories concentrates bargaining power among certified suppliers, creating tiered price floors that separate institutional procurement channels from cash-constrained rural practices. Scale economies in bis-GMA photoinitiator production anchor cost structures for resin-based systems, while glass ionomer alternatives face volatile polyalkenoate cement input costs.
Pricing Analysis
Certification level creates the primary spread between premium FDA 510(k)-cleared formulations and economy-tier alternatives lacking ISO 10993 documentation. Three-tier pricing structure across premium, standard, and economy levels tracks retention rate benchmarks and fluoride recharge compatibility. Pricing pressure stems from group purchasing organization consolidation in Sun Belt dental service organizations. Public health programs in Appalachia and the Mississippi Delta exhibit highest price sensitivity, while integrated DSOs prioritize digital workflow bundling over unit cost.
Supply Chain Analysis
Strategic stockpiling of specialty urethane dimethacrylate monomers dominates inventory strategy among German and Japanese chemical suppliers serving formulators. Manufacturing gravity centers on the Rhine-Ruhr corridor, Osaka-Kobe cluster, and US Gulf Coast petrochemical hubs. Raw material dependencies encompass photoinitiator systems, nano-hybrid fillers, and polyalkenoate cement precursors. Single-source vulnerability concentrates in German specialty chemical suppliers for urethane dimethacrylate. Distribution runs through Henry Schein and Patterson Dental regional networks for mid-market practices, with direct field organizations serving high-volume DSO accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nano-hybrid filler convergence with digital dentistry workflows signals high-growth disruption, with EU Medical Device Regulation clinical data requirements creating compliance moats that reshape competitive access.
For Market Incumbents: Compound ISO 4049 certification advantages by accelerating testing laboratory partnerships to clear reformulated resin backlogs. Deepen backward integration into photoinitiator systems to offset German and Japanese chemical supplier concentration. Glass ionomer substitution in moisture-tolerant community settings threatens resin-based volume leadership. For New Entrants and Emerging Players: Anchor in rural US school district mobile dentistry programs where rubber dam isolation constraints favor glass ionomer chemistry expertise. Target underresourced districts in Appalachia and the Mississippi Delta with moisture-tolerant formulations. Pursue state-level Medicaid procurement tender qualification as the primary go-to-market pathway. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors manufacturers with MDR-compliant clinical performance registries and digital workflow bundling capabilities. Long-term viability rests on navigating ISO 10993 biocompatibility testing infrastructure and school-based program procurement consolidation. Watch FDA classification shifts between professional-use and over-the-counter preventive products as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 4049 Certification Acquisition | Testing laboratory partnerships unlock institutional procurement channels for reformulated resin systems. |
| Digital Workflow Bundling | Intraoral scanning integration with sealant placement creates sticky supplier-dentist relationships in DSO accounts. |
| Backward Integration into Photoinitiators | In-house production of specialty monomers reduces dependency on German and Japanese chemical suppliers. |
| MDR Clinical Performance Registry | EU Medical Device Regulation Article 83 compliance creates data barriers against lower-tier competitors. |
| Mobile Preventive Dentistry Partnership | Rural school district penetration in Texas and Florida captures Medicaid expansion volume. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with dental materials scientists, pediatric dentistry group administrators, GPO contracts managers, and FDA regulatory consultants; and secondary validation through FDA 510(k) filings, ISO certification registries, Medicaid state plan amendment documents, and Henry Schein procurement disclosures. Bottom-up procedure volume modeling triangulated against top-down materials consumption estimates.
Across the projection horizon, the analytical framework segmented by material chemistry, clinical setting, and procurement channel, with additional modeling of reimbursement pathway variation. CAGRs derived from trend extrapolation of school-based program penetration rates and DSO consolidation trajectories. Forecast inputs encompassed photopolymerization technique standardization adoption curves and nano-hybrid filler clinical trial outcomes.
Material uncertainties — regulatory reclassification of preventive products, photoinitiator system supply disruptions, and ISO 4049 testing laboratory capacity constraints — sit outside the modeled envelope. Forecasts reflect assumptions about Medicaid reimbursement stability and DSO consolidation velocity. Practitioners should keep alternative scenarios live as EU MDR enforcement intensity and FDA 510(k) clearance timeline variability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Global Dental Laboratory Welders Market
Dental Devices
Global Dental Obturators Market
Dental Devices
Dental Inlays and Onlays Market
Dental Devices
Saudi Arabia Dental Devices Market
Dental Devices
Periodontal Scalers and Curettes Market
Dental Devices
Global Dental Burs Market
Dental Devices
India Dental Devices Market
Dental Devices
Dental Air Abrasion Market
Dental Devices
Digital Facebow Market
Dental Devices
Global Veterinary Dentistry Instruments and Equipment Market
Dental Devices
Netherlands Dental Devices Market
Dental Devices
Dental Veneers Market
Dental Devices
UAE Dental Devices Market
Dental Devices
Dental Healing Caps Market
Dental Devices
Turkey CAD/CAM Dental Devices Market
Dental Devices
Malocclusion Market