
 Dental Composite Resin Filling Market | 2026-2036
Dental Composite Resin Filling Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Composite Resin Filling Market Insights
Dental supply distribution through group purchasing organizations is reshaping how composite resins reach end users. 3M Company leverages its direct-to-clinic digital platform to sustain premium positioning across North American practices. Dentsply Sirona Inc. anchors its portfolio through integrated CAD/CAM workflows that bundle restorative materials with chairside systems. Ivoclar Vivadent Inc. differentiates via specialized shade-matching technologies that target high-aesthetic anterior segments.
Dental composite resin filling consists of a bis-GMA or urethane dimethacrylate resin matrix loaded with silica or glass filler particles, typically containing 60-80% by weight inorganic filler to achieve compressive strengths of 250-400 MPa and polymerize under 450-470 nm blue light for direct intracoronal restoration. Nanohybrid formulations now lead product type demand due to their balance of polishability and mechanical durability, while cosmetic dentistry applications represent the fastest-expanding segment as patient-funded aesthetic procedures outpace reimbursement-dependent categories. Packable composites occupy a mature niche in posterior bulk-fill protocols where speed competes with incremental layering techniques.
FDA 510(k) clearance pathways and CE marking under the EU MDR govern biocompatibility validation and clinical performance claims for dental composites entering their respective markets. ISO 4049 standards for polymer-based restorative materials establish baseline mechanical testing protocols that manufacturers must satisfy for international market access. Stakeholders should monitor evolving regulatory divergence between FDA and EU MDR requirements as dual-compliance costs could reshape competitive positioning among mid-tier suppliers.
Market Dynamics
Group purchasing organizations now control material flow to dental clinics across North America and Europe, compressing distributor margins while elevating manufacturers with direct digital platforms. This procurement consolidation forces composite resin suppliers to build clinical loyalty through chairside workflow integration rather than traditional sales relationships.
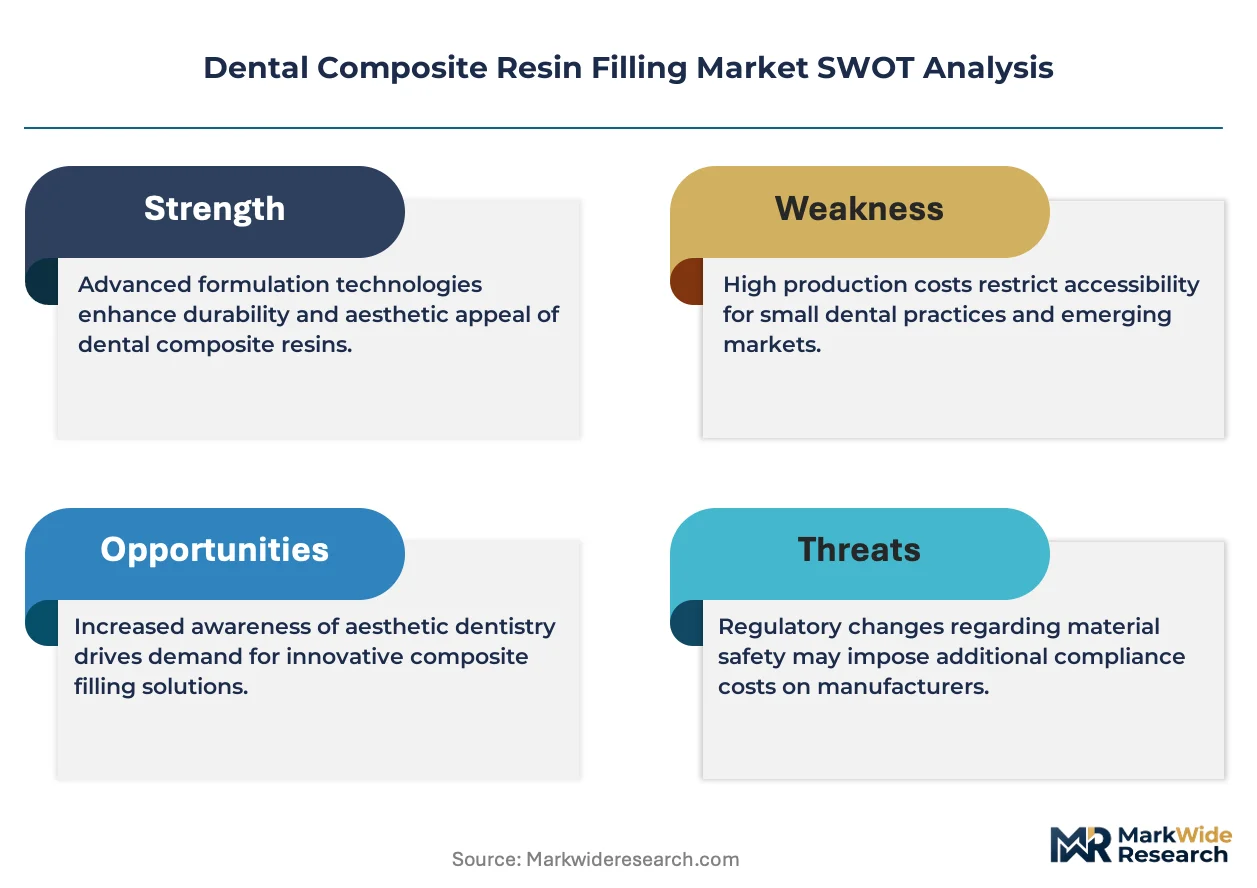
Growth Catalysts
- FDA 510(k) pathway streamlining:Expedited biocompatibility validation for nanohybrid formulations accelerates product cycles for posterior restoration applications in United States dental clinics.
- Patient-funded aesthetic procedures:Cosmetic dentistry segments in Germany and China bypass reimbursement constraints, creating premium demand for shade-matched anterior composites.
- Blue-light polymerization efficiency:450-470 nm curing protocols reduce chair time, driving replacement of older chemically-cured systems in high-volume practices.
Market Restraints
- Silica filler cost volatility:Inorganic particle supply concentrates among specialty chemical processors, exposing formulators to raw material price swings that compress blended margin structures.
- EU MDR clinical data requirements:Expanded biocompatibility documentation demands extend CE marking timelines, freezing mid-tier suppliers from European market entry.
- Amalgam substitution ceiling:Remaining posterior applications in price-sensitive clinics resist composite conversion where mercury-based alternatives retain durability advantages.
Strategic Opportunities
- India's dental infrastructure expansion:Private clinic chains in Mumbai and Delhi upgrade to nanohybrid protocols, creating first-mover positioning for quality-certified suppliers.
- CAD/CAM material convergence:Chairside milling systems require compatible composite blocks, opening workflow-integrated supply contracts with equipment manufacturers.
- Brazil's ANVISA harmonization:Regulatory alignment with ISO 4049 standards reduces dual-testing burdens for exporters targeting Latin American aesthetic dentistry growth.
Industry Challenges
- Shade-matching technician scarcity:Anterior restoration quality depends on specialized colorimetry skills that dental schools graduate insufficiently.
- Bulk-fill validation protocols:Packable composite claims require incremental layering evidence, extending R&D timelines against speed-focused competitor positioning.
- Legacy distributor relationship unwinding:Direct-to-clinic platform investments strain capital allocation while GPO contracts demand price concessions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Composite Resin Filling Market |
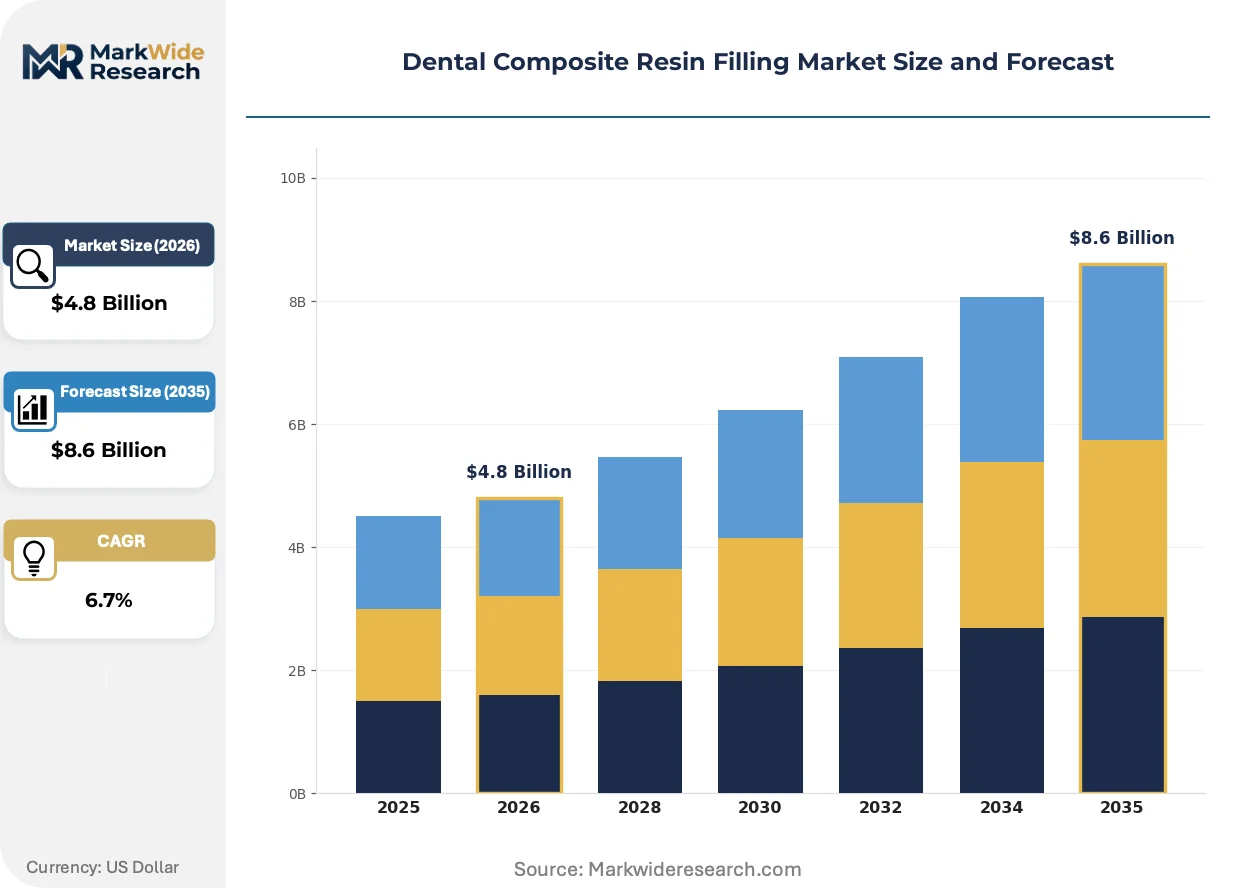
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microhybrid, Nanohybrid, Microfilled, Packable Application: Anterior Restorations, Posterior Restorations, Cosmetic Dentistry, Preventive Dentistry End User: Dental Clinics, Hospitals, Dental Laboratories, Research Institutions Delivery Mode: Bulk Packages, Syringe Delivery, Pre-loaded Cartridges, Online Distribution |
| Companies Covered | 3M Company, Dentsply Sirona Inc., Ivoclar Vivadent Inc., Envista Holdings Corporation, Coltene Holding AG, GC Corporation, Kerr Corporation, VOCO GmbH, Kuraray Noritake Dental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Composite Resin Filling Market Trends and Innovations
Workflow digitization now penetrates every stage of restorative dentistry, from intraoral scanning through material selection to polymerization monitoring. This integration pressure forces composite resin suppliers to embed their products within closed-loop clinical systems rather than competing as standalone commodities.
Nanohybrid filler architectures combine sub-micron silica particles with prepolymerized resin fillers to achieve both surface gloss and occlusal wear resistance. Large dental clinic chains in the United States deploy these materials for same-day posterior restorations, compressing appointment scheduling. Conventional microhybrid composites are rendering obsolete in premium practice segments where patient retention depends on single-visit outcomes.
EU MDR biocompatibility testing expansions now mandate extended cytotoxicity and sensitization studies for all polymer-based restorative materials entering European markets. Manufacturers must maintain technical files with clinical performance data, elevating compliance costs that disadvantage smaller formulators. Nanohybrid product lines face the steepest documentation burdens given their complex multi-phase compositions.
Clinic procurement teams now consolidate supplier relationships through multi-year GPO contracts that bundle composite resins with bonding agents and curing equipment. This purchasing concentration displaces independent distributor networks in Germany and France, where hospital-affiliated dental centers negotiate enterprise pricing. Direct manufacturer platforms capture preference where technical training and shade-matching support accompany material supply.
Dental Composite Resin Filling Market Segmentation
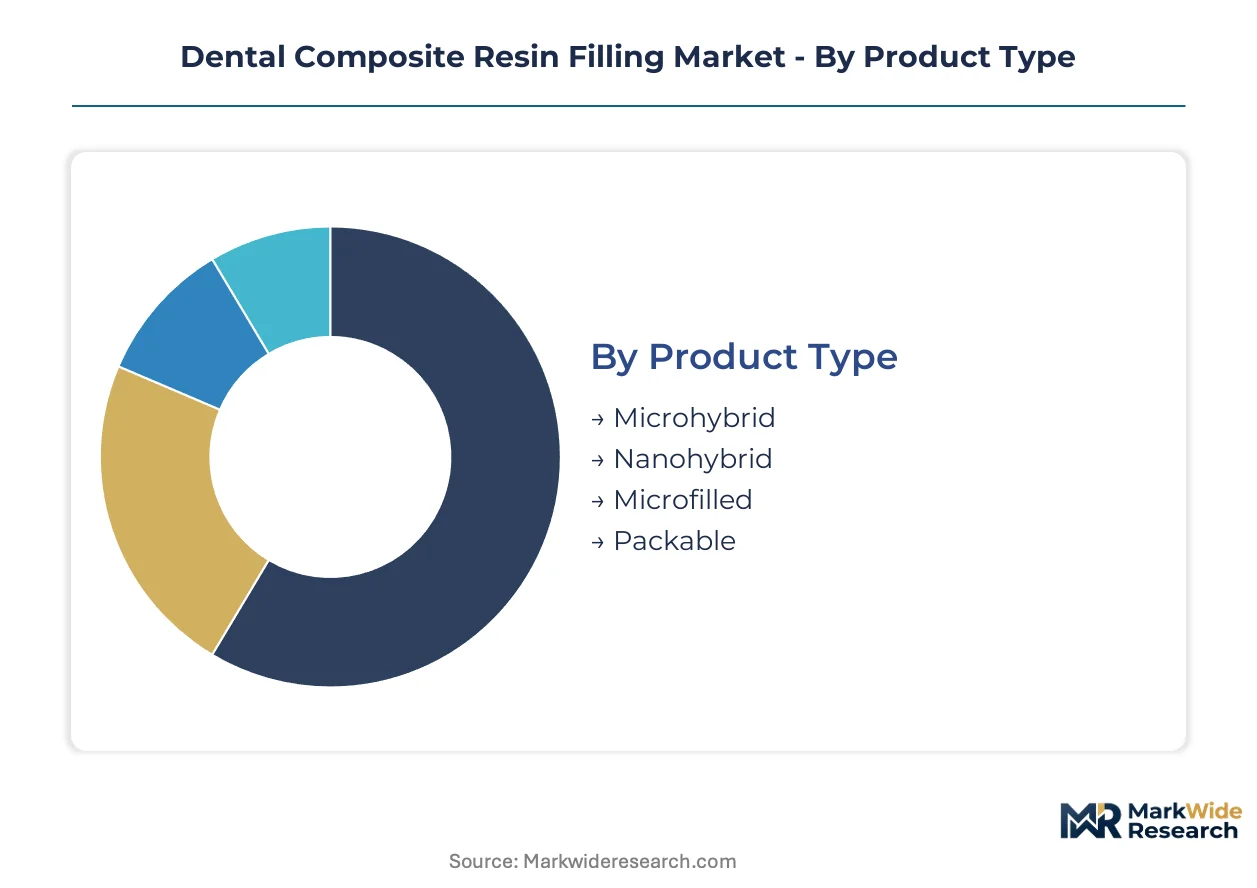
Composite resin segmentation determines material selection protocols across restorative workflows. Clinicians match filler architecture to cavity classification, curing constraints, and aesthetic demands. Procurement teams negotiate supply contracts around these technical boundaries.
Product Type:
Cost tier stratification separates premium nanohybrid formulations from economy microfilled alternatives.
- Nanohybrid:Sub-micron silica particles combined with prepolymerized resin fillers deliver polishability and occlusal wear resistance. United States dental clinic chains deploy these for same-day posterior restorations where patient retention hinges on single-visit outcomes.
- Microhybrid:Conventional 0.4-1.0 micron glass and silica filler loading achieves compressive strengths of 300-350 MPa. German university hospitals specify these for load-bearing posterior applications where incremental layering protocols remain standard.
- Microfilled:0.04 micron colloidal silica particles enable surface gloss for anterior aesthetics.
- Packable:High-viscosity formulations with 70-80% filler loading suit bulk-fill posterior techniques.
Microhybrid commands the established base. The steepest expansion runs through nanohybrid.
Application:
Clinical indication drives material specification through distinct functional requirements.
- Cosmetic Dentistry:Shade-matched anterior restorations bypass reimbursement constraints as patient-funded procedures. Chinese private clinics in Shanghai and Beijing upgrade to premium nanohybrid protocols for veneer and diastema closure cases.
- Posterior Restorations:High-stress occlusal surfaces demand 400+ MPa compressive resistance. Packable and nanohybrid formulations displace amalgam in United States Medicaid expansion clinics where mercury handling regulations tighten.
- Anterior Restorations:Translucency and fluorescence matching dominate material selection.
- Preventive Dentistry:Pit and fissure sealants utilize flowable composite derivatives.
Posterior restorations command the established base. The steepest expansion runs through cosmetic dentistry.
End User:
Customer type determines procurement channel and technical support requirements.
- Dental Clinics:Independent and chain-affiliated practices generate volume demand through direct-to-clinic platforms. Group purchasing organizations in North America consolidate multi-year contracts bundling composite resins with curing lights and bonding systems.
- Dental Laboratories:Indirect restoration fabrication requires compatible composite blocks for CAD/CAM milling. Ivoclar Vivadent and Dentsply Sirona supply workflow-integrated material systems to European lab networks.
- Hospitals:Hospital-affiliated dental centers negotiate enterprise pricing.
- Research Institutions:Biocompatibility validation and filler innovation studies drive specialized procurement.
Dental clinics command the established base. The steepest expansion runs through dental laboratories.
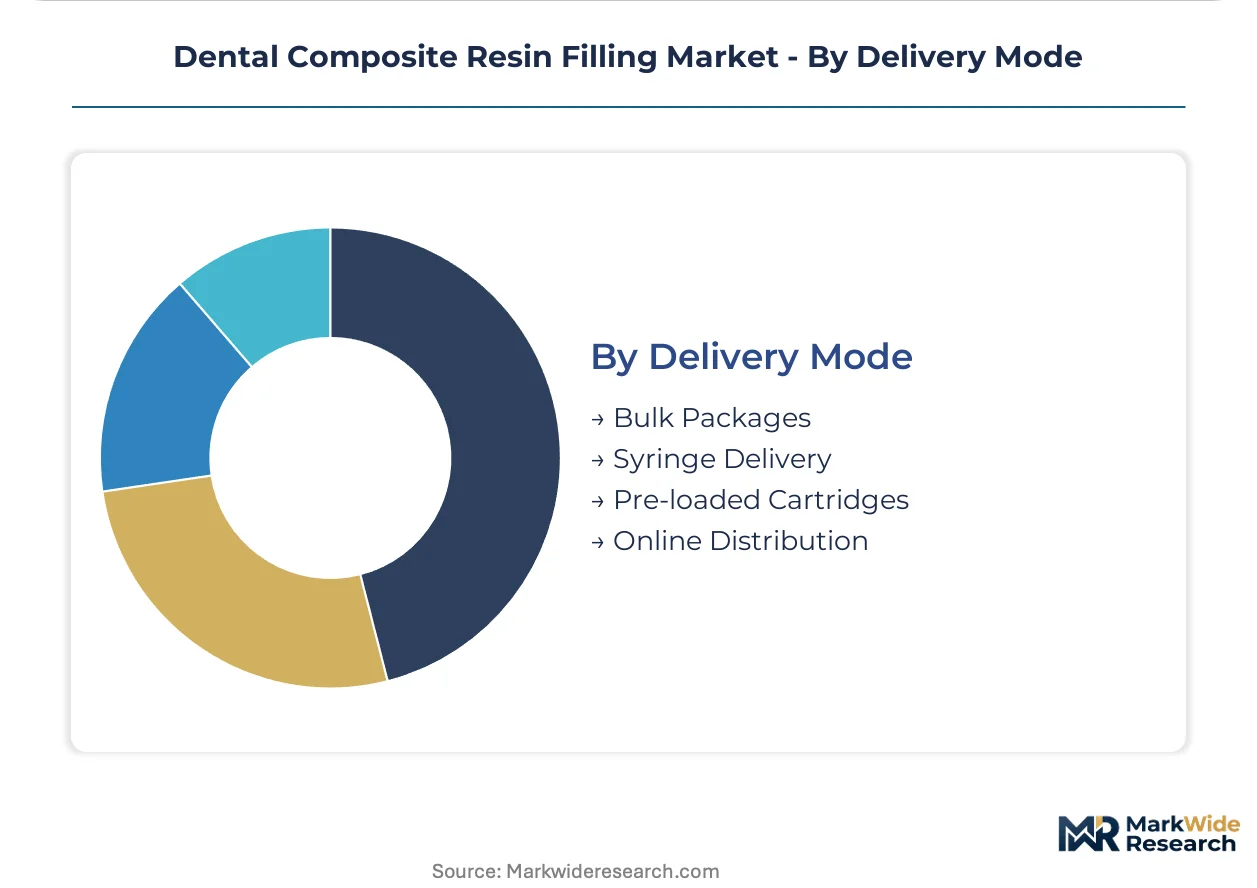
Delivery Mode:
Packaging configuration shapes inventory management and chairside efficiency.
- Syringe Delivery:Unit-dose hand dispensers with 4-5g composite reservoirs enable precise incremental placement. United States high-volume practices prefer 20-packs with color-coded shade caps for streamlined operatory stocking.
- Pre-loaded Cartridges:Single-patient applicators eliminate cross-contamination risks. German infection control protocols mandate these for hospital dental departments under EU MDR hygiene requirements.
- Bulk Packages:50-100g jars serve high-throughput clinics.
- Online Distribution:Direct manufacturer platforms bypass distributor networks.
Syringe delivery commands the established base. The steepest expansion runs through pre-loaded cartridges.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways in the United States anchor the dominant geography, while CE marking under EU MDR governs European market entry. Regulatory divergence between these jurisdictions shapes manufacturer compliance strategies and competitive positioning across key national markets.
United States
Dental clinic chains in Texas and Florida deploy nanohybrid composites for same-day posterior restorations. FDA streamlines biocompatibility validation for nanohybrid formulations, accelerating product cycles. Group purchasing organizations in the Midwest consolidate multi-year contracts bundling resins with curing equipment.
Germany
University hospitals in Bavaria specify microhybrid composites for load-bearing posterior applications. EU MDR mandates expanded biocompatibility documentation, extending CE marking timelines. Berlin-Brandenburg hospital-affiliated dental centers negotiate enterprise pricing for integrated CAD/CAM workflows.
China
Private clinics in Shanghai and Beijing upgrade to premium nanohybrid protocols for veneer cases. NMPA aligns with ISO 4049 standards for polymer-based restorative materials. Pearl River Delta manufacturing clusters supply silica filler particles to domestic formulators.
Brazil
São Paulo clinic chains drive aesthetic dentistry demand for shade-matched anterior composites. ANVISA harmonizes with ISO 4049 standards, reducing dual-testing burdens for exporters. Southeast regional distributors consolidate procurement relationships with multi-material suppliers.
India
Mumbai and Delhi private clinic chains upgrade to nanohybrid protocols, creating first-mover opportunities. CDSCO strengthens biocompatibility testing requirements for imported dental materials. Maharashtra dental infrastructure expansion concentrates demand in urban metro corridors.
Dental Composite Resin Filling Market Competitive Landscape
Integrated equipment manufacturers and specialized material formulators split the market into distinct strategic tiers. Consolidation pressure runs through group purchasing organization procurement, compressing distributor margins while elevating direct-platform suppliers. Three archetypes dominate: workflow-integrated systems providers, premium aesthetic specialists, and scale-driven commodity suppliers. Competitive moves center on CAD/CAM workflow bundling and chairside digital platform deployment.
Within the workflow-integrated tier, 3M Company and Dentsply Sirona Inc. exemplify archetype positioning through direct-to-clinic platform strategies. Ivoclar Vivadent Inc. occupies a specialist position targeting high-aesthetic anterior segments. These three entities represent the dominant competitive anchors without exhausting the field.
| Leading Market Players |
|---|
| 3M Company |
| Dentsply Sirona Inc. |
| Ivoclar Vivadent Inc. |
| Envista Holdings Corporation |
| Coltene Holding AG |
| GC Corporation |
| Kerr Corporation |
| VOCO GmbH |
| Kuraray Noritake Dental |
| Others |
Pricing and Supply Chain Analysis
Silica filler cost volatility concentrates among specialty chemical processors in Germany and China, compressing blended margin structures for formulators while simultaneously widening spreads between nanohybrid premium tiers and microfilled economy alternatives. This single-source dependency on inorganic particle supply shapes procurement consolidation through group purchasing organizations that demand volume-tiered contracting.
Pricing Analysis
Customization-premium spreads separate shade-matched nanohybrid formulations from standard microhybrid alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 4049 certification grades and filler architecture complexity. Cost compression in economy tiers intensifies because GPO contracts demand price concessions for high-volume clinic chains. Price sensitivity concentrates among Medicaid expansion clinics in the United States, while German private aesthetic practices exhibit minimal elasticity for anterior restoration materials.
Supply Chain Analysis
Export-control regimes on sub-micron silica particle technology limit technology transfer to emerging formulators in India and Brazil. Raw material sourcing draws from German specialty chemical processors, Chinese glass manufacturing clusters, and Japanese prepolymerized resin suppliers. Single-source vulnerability concentrates in high-purity silica filler supply. Distribution runs through group purchasing organization contracts that bundle composite resins with curing equipment and bonding agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dental composite resin supply is shifting toward platform-economics dynamics where CAD/CAM workflow interoperability determines supplier lock-in. Chairside system integration now functions as the primary ecosystem control point.
For Market Incumbents: Entrench platform dominance through backward integration into silica filler production and exclusive CAD/CAM block supply contracts with equipment manufacturers. Defend against emerging nanohybrid specialists by accelerating FDA 510(k) clearance cycles for next-generation formulations. Channel control through direct-to-clinic digital platforms represents the critical defensive lever. For New Entrants and Emerging Players: Build out specialized shade-matching services for anterior aesthetic segments where technician scarcity creates service-layer differentiation. India's private clinic chains in Mumbai and Delhi offer the most penetrable geography given infrastructure expansion timing. Target workflow-agnostic material supply as the go-to-market angle, positioning compatibility across multiple chairside systems. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors workflow-integrated platform providers over standalone commodity formulators. Long-term viability across the projection horizon hinges on CAD/CAM ecosystem positioning rather than material innovation alone. Acquisition targets should demonstrate hospital-affiliated dental center contracts or GPO bundling relationships. Watch FDA-EU MDR regulatory divergence as the signal for compliance-cost-driven consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CAD/CAM Workflow Integration | Locks composite resin supply into chairside milling system ecosystems. |
| Backward Integration into Silica Fillers | Captures margin compression from specialty chemical processor concentration. |
| Direct-to-Clinic Platform Deployment | Bypasses distributor networks displaced by GPO procurement consolidation. |
| EU MDR Technical File Expansion | Elevates compliance barriers that freeze mid-tier European competitors. |
| Shade-Matching Technology Acquisition | Addresses technician scarcity constraining anterior restoration quality. |
Research Methodology
Initial hypotheses were tested against primary input from dental clinic procurement managers, GPO contracts specialists, biomedical materials engineers, and regulatory affairs leads at composite resin manufacturers and refined through secondary validation. Sources included FDA 510(k) clearance databases, EU MDR technical file registries, ISO 4049 certification records, and hospital procurement system data. Bottom-up demand modeling from clinic-level procedure volumes was triangulated against top-down manufacturer shipment data.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled included filler architecture tier, clinical application indication, end-user procurement channel, and regional regulatory cluster. CAGRs were derived from procedure volume trajectories and material substitution rates. Forecast inputs incorporated nanohybrid adoption curves in posterior restorations and patient-funded aesthetic procedure growth patterns.
Stress conditions across silica filler price volatility, EU MDR documentation timeline extensions, and GPO contract renewal cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory harmonization and clinic infrastructure expansion timing. Material shifts in FDA-EU MDR divergence severity or amalgam substitution regulatory mandates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Global Dental Bone Graft Substitutes Market
Dental Devices
Dental Radiometer Market
Dental Devices
Dental Floss Market
Dental Devices
Dental Veneers Market
Dental Devices
RFID-Enabled Dental Printing Market
Dental Devices
Global Endodontics Market
Dental Devices
Dental Dam Market
Dental Devices
Global Dental Microscope Market
Dental Devices
Dental Composite Filling Market
Dental Devices
Dental Laboratory Handpiece Market
Dental Devices
Dental Handpieces Market
Dental Devices
North America Dental Lasers Market
Dental Devices
Dental CAD Market
Dental Devices
Dental Calipers Market
Dental Devices
Global Dental Labs Market
Dental Devices
3D Printing Dental Device Market