
 Decorative Concrete Market | 2026-2036
Decorative Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
Decorative Concrete Market Analysis
Specialty distributor networks is narrowing as large building material retailers consolidate shelf space for premium decorative concrete systems. Sika AG leverages its admixture-coating integration to sustain technical specification control across major commercial flooring projects. BASF SE anchors its position through polymer-modified overlay chemistry that dominates high-traffic architectural installations. LafargeHolcim Ltd competes via captive cement supply and ready-mix distribution density in North American metropolitan corridors.
Decorative concrete encompasses cementitious surfaces enhanced through chemical staining, mechanical polishing, stamped patterning, or polymer-modified overlay systems to achieve architectural aesthetics while retaining structural load-bearing capacity; these systems typically incorporate Portland cement blends with supplementary cementitious materials at 15-35% replacement levels, finished with lithium silicate densifiers or acrylic sealers to achieve specified gloss units and abrasion resistance. Polished concrete and stamped concrete command the largest installed bases, though decorative overlays represent the fastest-expanding margin pool due to renovation-driven demand and shorter project cycles. Residential flooring and commercial flooring together absorb the majority of specification volume, with technology differentiation clustering around concrete admixtures and coatings where formulation IP creates pricing power.
EPA oversight of volatile organic compound emissions from concrete sealers and coatings shapes product formulation requirements, while OSHA silica exposure limits during grinding and polishing operations influence contractor equipment investment and job site protocols. The EU Green Deal's embodied carbon benchmarks are filtering into procurement specifications for large commercial developments, effectively restricting high-clinker decorative mixes from certain public projects. Stakeholders must monitor how tightening chemical disclosure frameworks across multiple jurisdictions reshape permissible binder chemistries and sealer compositions.
Market Dynamics
Large building material retailers are consolidating shelf space for premium decorative concrete systems, compressing specialty distributor networks and forcing manufacturers to secure direct specification relationships with commercial flooring contractors.
Growth Catalysts
- Sun Belt Metropolitan Concentration:Residential flooring demand clusters in United States metropolitan corridors where new construction and renovation activity outpaces national averages, pulling decorative overlay and polished concrete specifications.
- EU Green Deal Embodied Carbon Thresholds:Low-clinker formulation requirements are accelerating specification shifts toward supplementary cementitious material blends in European commercial developments.
- Polymer-Modified Overlay Chemistry:Renovation-driven demand for shorter project cycles is expanding the fastest-growing margin pool across commercial flooring applications.
Market Restraints
- Silica Exposure Compliance Costs:OSHA grinding and polishing limits force contractor equipment investment in dust collection systems and job site protocol restructuring.
- Volatile Organic Compound Formulation Constraints:EPA sealer and coating emission standards restrict permissible solvent chemistries and extend product development timelines.
- Ready-Mix Distribution Density Requirements:Captive cement supply advantages concentrate competitive positioning in North American metropolitan corridors with established ready-mix networks.
Strategic Opportunities
- Chemical Disclosure Framework Convergence:Tightening multi-jurisdictional binder chemistry rules create first-mover advantage for manufacturers with pre-validated low-clinker formulations.
- Residential Premium Aesthetic Specification:Homeowner demand for architectural finishes in flooring applications remains underpenetrated relative to commercial verticals.
- Admixture-Coating Integration Control:Technical specification authority across major commercial projects favors suppliers with integrated formulation portfolios.
Industry Challenges
- Skilled Polishing and Stamping Labor Scarcity:Mechanical polishing and stamped patterning techniques require specialized contractor expertise that outstrips current training pipeline output.
- Lithium Silicate Densifier Specification Complexity:Achieving specified gloss units and abrasion resistance demands precise application protocols that vary across substrate conditions.
- Multi-Jurisdictional Sealer Compliance:Acrylic sealer formulations must navigate diverging chemical disclosure requirements across state and national boundaries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decorative Concrete Market |
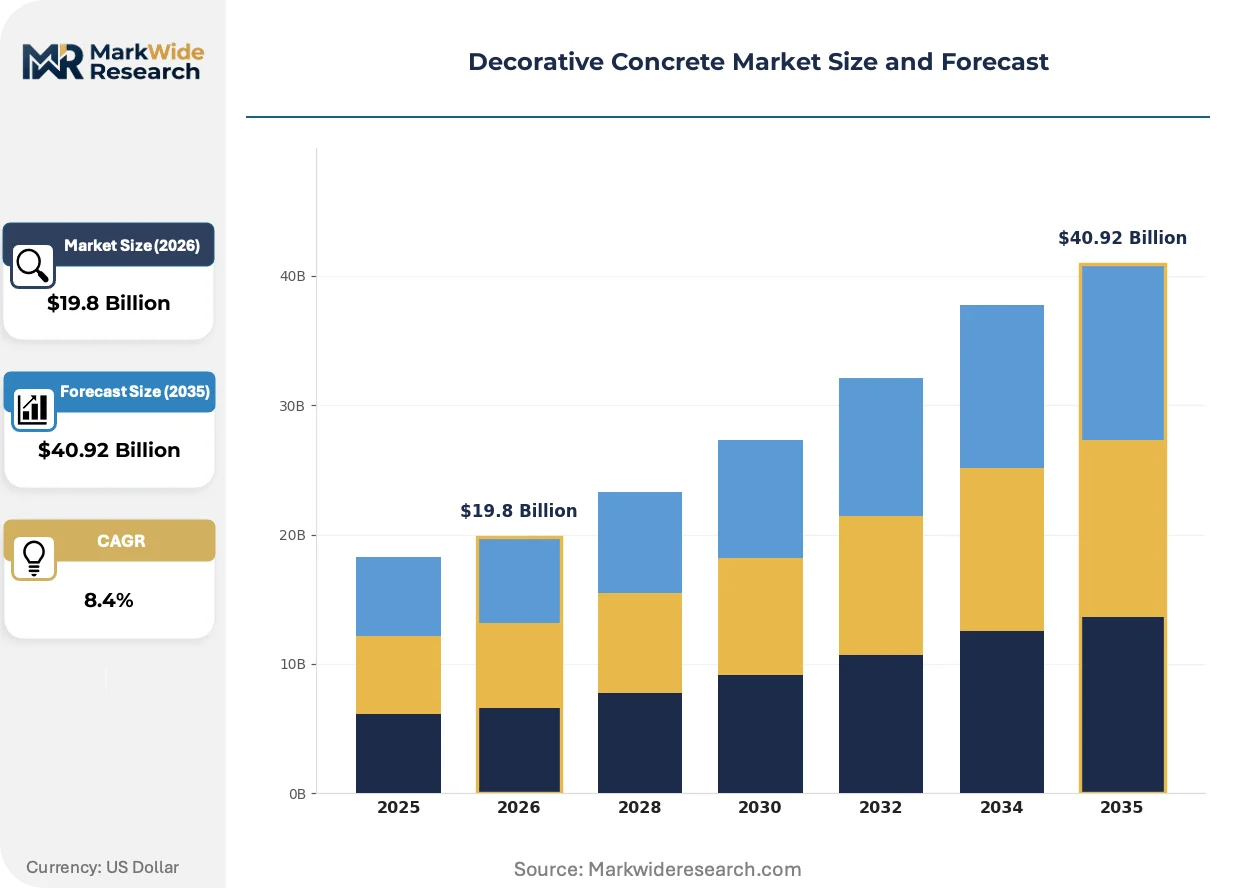
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $40.92 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stained Concrete, Polished Concrete, Decorative Overlay, Stamped Concrete Application: Residential Flooring, Commercial Flooring, Patios, Driveways Technology: Concrete Admixtures, Coatings, Dyes, Sealers End User: Homeowners, Contractors, Architects, Designers |
| Companies Covered | Sika AG, BASF SE, LafargeHolcim Ltd, RPM International Inc., The Sherwin-Williams Company, CEMEX S.A.B. de C.V., PPG Industries, Inc., HeidelbergCement AG, Ultratech Cement Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decorative Concrete Market Emerging Trajectories
Digital specification tools and embodied carbon tracking are compressing traditional material selection cycles while elevating transparency requirements across decorative concrete supply chains.
Sensor-integrated curing monitoring systems are digitizing quality assurance protocols for polished concrete installations. Commercial flooring contractors in high-traffic architectural segments are adopting these systems to document densifier penetration rates and gloss achievement in real time. The technology is digitizing specification compliance verification, reducing callback disputes and compressing project closeout timelines.
REACH chemical authorization expansions are restricting chromate-based curing compounds and certain acrylic monomers used in decorative sealers. European manufacturers are reformulating overlay systems to maintain performance benchmarks under tightened substance restrictions. High-traffic commercial installations in Germany and France face the most immediate specification recalibration as existing product registrations expire.
Building information modeling integration is reshaping how architects specify decorative concrete finishes during early design phases. Commercial flooring contractors now receive substrate condition data and performance requirement parameters before bidding, replacing traditional post-award material selection. This shift is most visible in United States commercial developments where general contractors mandate digital handoff protocols.
Decorative Concrete Market Segmentation
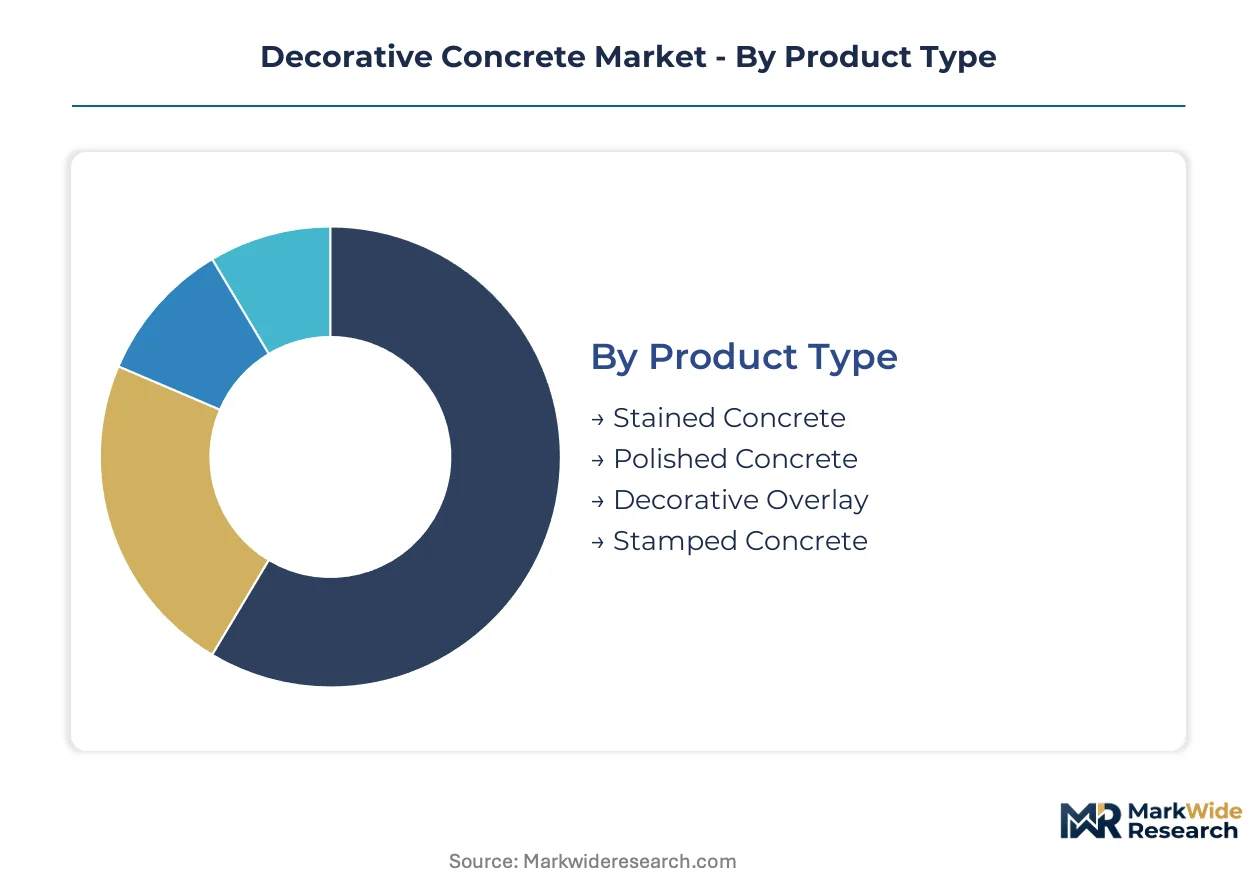
Segmentation in decorative concrete reveals how specification authority flows through distinct technical and channel pathways. Product chemistry, application environment, and procurement actor type each create separate margin structures and competitive moats.
Product Type:
Cost tier differentiation separates commodity surface treatments from premium architectural systems requiring specialized contractor certification and extended warranty terms.
- Polished Concrete:Mechanical grinding with progressive diamond abrasives achieves specified gloss units through lithium silicate densifier penetration. Demand concentrates in United States commercial flooring for retail and warehouse environments where abrasion resistance requirements exceed 3,000 Taber cycles.
- Decorative Overlay:Polymer-modified cementitious systems at 3-25mm thickness rehabilitate existing substrates without demolition. Renovation demand in Sun Belt metropolitan areas is accelerating specification for shorter project cycles in hospitality and multi-family residential conversions.
- Stained Concrete:Reactive acid or water-based colorants penetrate cementitious surfaces to produce variegated earth-tone finishes. Residential flooring applications in custom home construction dominate volume.
- Stamped Concrete:Elastomeric mats imprint fresh concrete with stone, brick, or wood grain patterns. Driveway and patio installations in suburban United States developments absorb majority share.
Polished concrete holds installed capacity. Decorative overlay is rotating up the share rankings.
Application:
Volume concentration follows construction cycle intensity, with commercial verticals demanding performance documentation that residential specifications rarely require.
- Commercial Flooring:High-traffic architectural installations specify polymer-modified overlays and polished systems with documented abrasion resistance and slip coefficient compliance. EU Green Deal embodied carbon thresholds are filtering into procurement specifications for large developments in Germany and France.
- Residential Flooring:Premium aesthetic finishes in custom homes drive stained and polished concrete specifications. United States Sun Belt metropolitan corridors concentrate demand where new construction and renovation activity outpaces national benchmarks.
- Patios:Stamped and stained systems dominate outdoor living space extensions. Contractor-installed volume tracks single-family housing permit issuance in suburban markets.
- Driveways:Stamped concrete with integral color and release agent finishing commands this segment. Curb appeal investment in resale markets sustains replacement cycle demand.
Commercial flooring commands specification authority. Residential flooring is climbing the fastest.
Technology:
Margin capture concentrates in formulation IP where admixture-coating integration creates technical specification control across major projects.
- Concrete Admixtures:Chemical additives modify workability, set time, and hardened properties of cementitious mixes. Low-clinker formulation requirements under EU Green Deal benchmarks are accelerating specification shifts toward supplementary cementitious material blends.
- Coatings:Polymer-modified systems provide decorative color, texture, and protective film formation. EPA volatile organic compound emission standards restrict permissible solvent chemistries and extend product development timelines.
- Dyes:Penetrating colorants achieve consistent hue across cementitious surfaces. Water-based formulations are displacing solvent carriers under tightening chemical disclosure frameworks.
- Sealers:Acrylic, polyurethane, or epoxy film-forming systems protect decorative finishes. Multi-jurisdictional compliance requirements across state and national boundaries complicate formulation standardization.
Concrete admixtures anchor technical differentiation. Coatings are expanding most quickly.
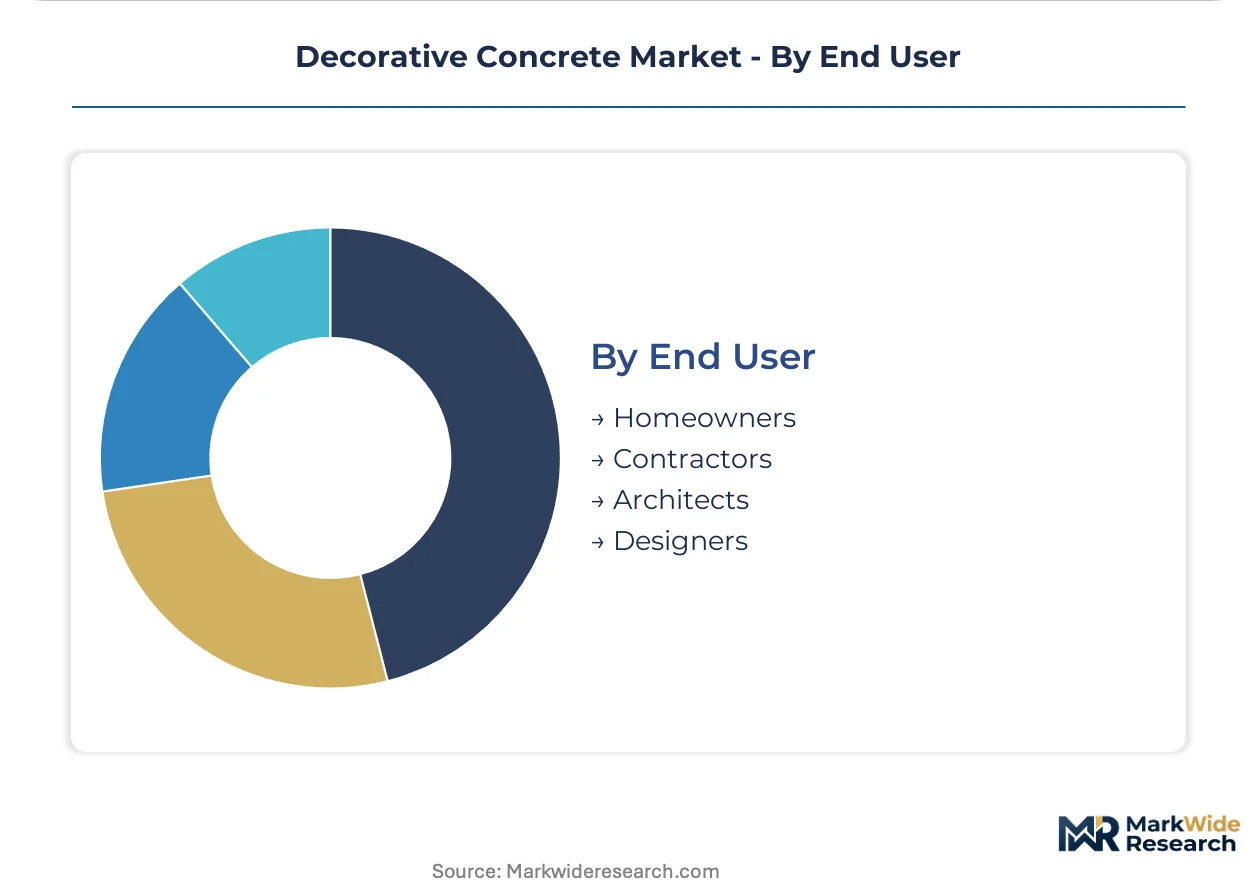
End User:
Customer type determines specification pathway complexity, from direct homeowner aesthetic preference to architect-driven performance documentation.
- Contractors:Commercial flooring specialists and residential flatwork installers control material selection through established distributor relationships. OSHA silica exposure limits during grinding and polishing operations influence equipment investment and job site protocol restructuring.
- Architects:Specification authority in commercial and institutional projects demands performance documentation and embodied carbon tracking. Building information modeling integration is reshaping how decorative concrete finishes enter early design phases.
- Homeowners:Direct procurement of residential flooring and outdoor living surfaces follows aesthetic preference and referral networks. Premium finish demand remains underpenetrated relative to commercial verticals.
- Designers:Interior design professionals influence material selection in high-end residential and hospitality projects. Color and texture specification authority competes with architect-driven performance requirements.
Contractors control channel volume. Architects are gaining specification influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate Highway System underwrites United States distribution density for decorative concrete systems. European rail freight corridors move low-clinker formulations across borders. Gulf Coast petrochemical infrastructure supplies polymer modifiers for overlay chemistry.
United States
Sun Belt metropolitan corridors concentrate residential flooring and commercial overlay demand where construction cycles outpace national benchmarks. EPA volatile organic compound emission standards restrict sealer chemistries and extend product development timelines. Dallas-Fort Worth and Phoenix anchor specification volume for polished concrete in retail and warehouse environments.
Germany
High-traffic commercial installations drive polymer-modified overlay specifications with documented abrasion resistance. REACH chemical authorization expansions restrict chromate-based curing compounds and certain acrylic monomers. The Rhine-Ruhr metropolitan region faces immediate specification recalibration as existing product registrations expire.
France
Architectural flooring in hospitality and multi-family conversions accelerates renovation-driven demand. EU Green Deal embodied carbon thresholds filter into procurement specifications for large commercial developments. The Île-de-France region concentrates specification authority where building information modeling integration reshapes early design phases.
China
Urban renewal projects and commercial real estate upgrades expand decorative overlay installations. GB standards and dual carbon goals pressure manufacturers toward supplementary cementitious material blends. The Yangtze River Delta anchors production capacity for lithium silicate densifiers and acrylic sealer formulations.
United Arab Emirates
Megaproject developments and luxury hospitality construction specify premium architectural concrete finishes. MOHAP chemical disclosure requirements complicate multi-jurisdictional sealer compliance for imported systems. Dubai's commercial corridor concentrates high-gloss polished concrete demand in retail and entertainment venues.
Decorative Concrete Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in formulation chemistry. The vendor base clusters around three strategic archetypes: multinational building material conglomerates with captive cement supply, specialty chemical manufacturers with admixture-coating integration, and regional ready-mix distributors with metropolitan density. Consolidation pressures concentrate around large building material retailers compressing specialty distributor networks. Dominant competitive moves include securing direct specification relationships with commercial flooring contractors and accelerating low-clinker formulation validation under tightening chemical disclosure frameworks.
Within the multinational conglomerate tier, Sika AG, BASF SE, and LafargeHolcim Ltd represent distinct positioning archetypes. Sika AG exemplifies admixture-coating integration control across major commercial projects. BASF SE anchors the specialty chemical vector through polymer-modified overlay chemistry dominance. LafargeHolcim Ltd occupies the captive supply position via ready-mix distribution density in North American metropolitan corridors.
| Leading Market Players |
|---|
| Sika AG |
| BASF SE |
| LafargeHolcim Ltd |
| RPM International Inc. |
| The Sherwin-Williams Company |
| CEMEX S.A.B. de C.V. |
| PPG Industries, Inc. |
| HeidelbergCement AG |
| Ultratech Cement Ltd |
| Others |
Supply Flow & Price Mechanics
Gulf Coast petrochemical infrastructure feeds polymer modifier production for decorative overlay systems, anchoring margin capture in downstream formulation chemistry rather than commodity cement supply. Large building material retailers compress specialty distributor networks, forcing manufacturers to absorb channel consolidation costs or secure direct contractor relationships.
Pricing Analysis
Volume-discount tiering structures separate certified contractor pricing from retail homeowner purchases across decorative concrete systems. Three-tier pricing stratification across premium architectural, standard commercial, and economy residential levels reflects certification requirements and warranty terms. Cost compression in economy tiers intensifies as captive cement suppliers leverage ready-mix density for price leverage. Commercial flooring contractors exhibit lowest price sensitivity due to specification-locked projects, while residential homeowners drive aggressive retail comparison shopping.
Supply Chain Analysis
Upstream feedstock concentration centers on Gulf Coast petrochemical complexes for acrylic monomers and polyurethane precursors, Chinese lithium silicate densifier production, and North American Portland cement manufacturing. Decorative overlay chemistry draws from epoxy resins, Portland cement blends, and supplementary cementitious materials. Single-source vulnerability sits with lithium silicate densifiers concentrated in Yangtze River Delta production. Distribution runs through building material retailers consolidating shelf space alongside direct specification channels to commercial flooring contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Decorative concrete represents a high-growth disruption as EU Green Deal embodied carbon thresholds force rapid formulation recalibration across European commercial developments. Low-clinker validation timelines compress competitive windows for unprepared manufacturers.
For Market Incumbents: Harden technical specification control through admixture-coating integration investments that lock out component-only competitors. Accelerate low-clinker formulation certification under REACH chemical authorization expansions before product registration expirations eliminate non-compliant systems from German and French procurement lists. Captive cement supply advantages must extend into polymer-modified overlay chemistry to defend margin pools.
For New Entrants and Emerging Players: Establish a beachhead in residential flooring applications where premium aesthetic demand remains underpenetrated relative to commercial verticals. Sun Belt metropolitan corridors offer concentrated construction cycle exposure without ready-mix distribution density requirements that disadvantage new entrants elsewhere. Digital specification tools provide a go-to-market angle for bypassing consolidated retailer channels.
For Investors and Strategic Acquirers: Capital is best deployed toward specialty chemical manufacturers with validated low-clinker portfolios and established contractor specification relationships. Long-term viability hinges on regulatory compliance moats rather than commodity scale. Watch EU Green Deal procurement specification adoption rates as the inflection signal for competitive repositioning velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Low-Clinker Formulation Validation | REACH chemical authorization deadlines in Germany and France force rapid product recertification cycles. |
| Admixture-Coating Integration Investment | Sika AG's technical specification control across major commercial projects demonstrates margin capture potential. |
| Direct Contractor Channel Development | Large building material retailer consolidation makes specialty distributor bypass essential for pricing authority. |
| Digital Specification Tool Deployment | Building information modeling integration in United States commercial developments reshapes early-phase material selection. |
| Sun Belt Metropolitan Density Expansion | Dallas-Fort Worth and Phoenix construction cycles outpace national benchmarks for polished concrete demand. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and industry association publications across the decorative concrete value chain. Primary interviews engaged commercial flooring contractors, ready-mix procurement managers, architectural specification leads, and polymer chemistry R&D directors. Secondary validation drew from EPA emission standard dockets, EU Green Deal procurement guidelines, REACH chemical authorization registries, and building material distributor financial disclosures. Bottom-up project pipeline analysis triangulates against top-down construction spending forecasts.
Forecast inputs incorporate product type segmentation across polished concrete, decorative overlay, stained concrete, and stamped concrete systems; application verticals spanning commercial flooring, residential flooring, patios, and driveways; technology differentiation in admixtures, coatings, dyes, and sealers; and end-user procurement pathways through contractors, architects, homeowners, and designers. CAGRs derive from regression analysis of historical specification volumes against construction cycle indicators and regulatory implementation timelines. Embodied carbon threshold adoption curves and silica exposure compliance cost trajectories inform scenario-weighted projections across the analysis window.
Macroeconomic conditions sit as an overlay; deviation in construction spending cycles, interest rate environments, or raw material commodity prices would shift the trajectory. Forecasts reflect assumptions about regulatory implementation pacing and contractor training pipeline output. Cross-checking against regional building permit issuance data and ready-mix shipment reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Rainscreen Cladding Market
Building & Construction Materials
Door Hinges Market
Building & Construction Materials
Air Barrier Market
Building & Construction Materials
Hydraulic Binder Market
Building & Construction Materials
Prefabricated Bathroom Modules Market
Building & Construction Materials
Autoclaved Aerated Concrete (AAC) Blocks Market
Building & Construction Materials
Glazed Tiles Market
Building & Construction Materials
Welded Wire Mesh Market
Building & Construction Materials
Plastic Fencing Market
Building & Construction Materials
Engineered Wood Market
Building & Construction Materials
Architectural Window Films Market
Building & Construction Materials
Concrete Protective Liners Market
Building & Construction Materials
Steel Roofing Market
Building & Construction Materials
South America Industrial Flooring Market
Building & Construction Materials
Vapor Barriers Market
Building & Construction Materials
Point Supported Glass Curtain Wall Market