
 Point Supported Glass Curtain Wall Market | 2026-2036
Point Supported Glass Curtain Wall Market Size, Share, and Industry Trends Forecast 2026-2036
Point Supported Glass Curtain Wall Market Insights
Chinese toughened glass producers is broadening export capacity for high-transparency facade panels. Yuanda China leverages integrated fabrication lines to anchor domestic project pipelines across Asia-Pacific. Permasteelisa North America competes on complex geometry delivery for museum and airport commissions. Arconic Corporation specializes in engineered metal hardware that sustains structural performance across seismic zones.
A point supported glass curtain wall employs mechanical spider fittings, tension cable nets, or bolted connectors to suspend glazing panels with minimal visible framing, typically achieving sightline reductions below 50 millimeters at connection nodes. The system transfers wind and dead loads through point-concentrated bearing rather than continuous perimeter support, enabling uninterrupted visual transparency for commercial atriums and transit terminals. Spider fittings and cable net systems command premium specification in airport and museum applications where span requirements exceed conventional stick-system limits. Laminated and insulated glass configurations are gaining share as thermal performance codes tighten across high-rise construction.
China's GB standards and the EU's CE marking framework govern structural silicone compatibility and impact resistance for point-fixed assemblies, with China's MEE enforcing embodied carbon disclosures on imported facade materials. The US FAA reviews glazing fragmentation criteria for airport terminal applications under federal aviation safety protocols. Stakeholders must monitor evolving energy code thresholds and local content requirements as procurement criteria shift toward lifecycle performance metrics.
Market Dynamics
Seismic performance mandates from China's GB standards and the EU's CE marking framework are compressing certification timelines for imported facade systems, forcing hardware suppliers to pre-validate laminated glass assemblies before project bidding.
Growth Catalysts
- Airport terminal modernization:The US FAA's glazing fragmentation criteria for aviation safety are mandating point-fixed systems in new transit hubs, elevating specification rates for spider fitting assemblies.
- REPowerEU building renovation targets:The EU Green Deal's energy performance standards are retrofitting commercial atriums with high-transparency curtain walls to maximize daylight harvesting.
- Tension cable net engineering advances:Improved stainless steel strand fatigue resistance is extending cable net spans beyond conventional stick-system limits in museum and exhibition hall applications.
Market Restraints
- Tempered glass input volatility:Float glass energy costs and silica sand supply disruptions are compressing margins for Chinese toughened panel exporters serving Middle East project pipelines.
- Structural silicone certification bottlenecks:Compatibility testing under China's GB 16776 and EU ETAG 002 standards extends lead times for imported facade systems by 8-14 months.
- Unitized curtain wall substitution:Pre-fabricated panelized systems are capturing mid-rise commercial specifications where sightline transparency is secondary to installation speed.
Strategic Opportunities
- Saudi giga-project pipeline:NEOM and Red Sea Project developments are architect-specifying cable net atriums for hospitality and cultural venues, creating premium hardware demand.
- Photovoltaic glass convergence:Building-integrated PV laminates are merging energy generation with point-fixed transparency, opening new specification channels for net-zero commercial towers.
- Performance-based procurement:Lifecycle cost modeling is displacing first-cost bidding in UAE commercial complexes, favoring suppliers with embodied carbon disclosure capabilities under China's MEE frameworks.
Industry Challenges
- Facade engineer talent scarcity:Specialized structural glass designers capable of cable net analysis and wind load simulation are concentrated in Milan, Dubai, and Shanghai, constraining project delivery capacity elsewhere.
- Seismic zone hardware validation:Japan's METI and California's OSHPD require jurisdiction-specific shake-table testing for spider fittings, fragmenting certification economies of scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Point Supported Glass Curtain Wall Market |
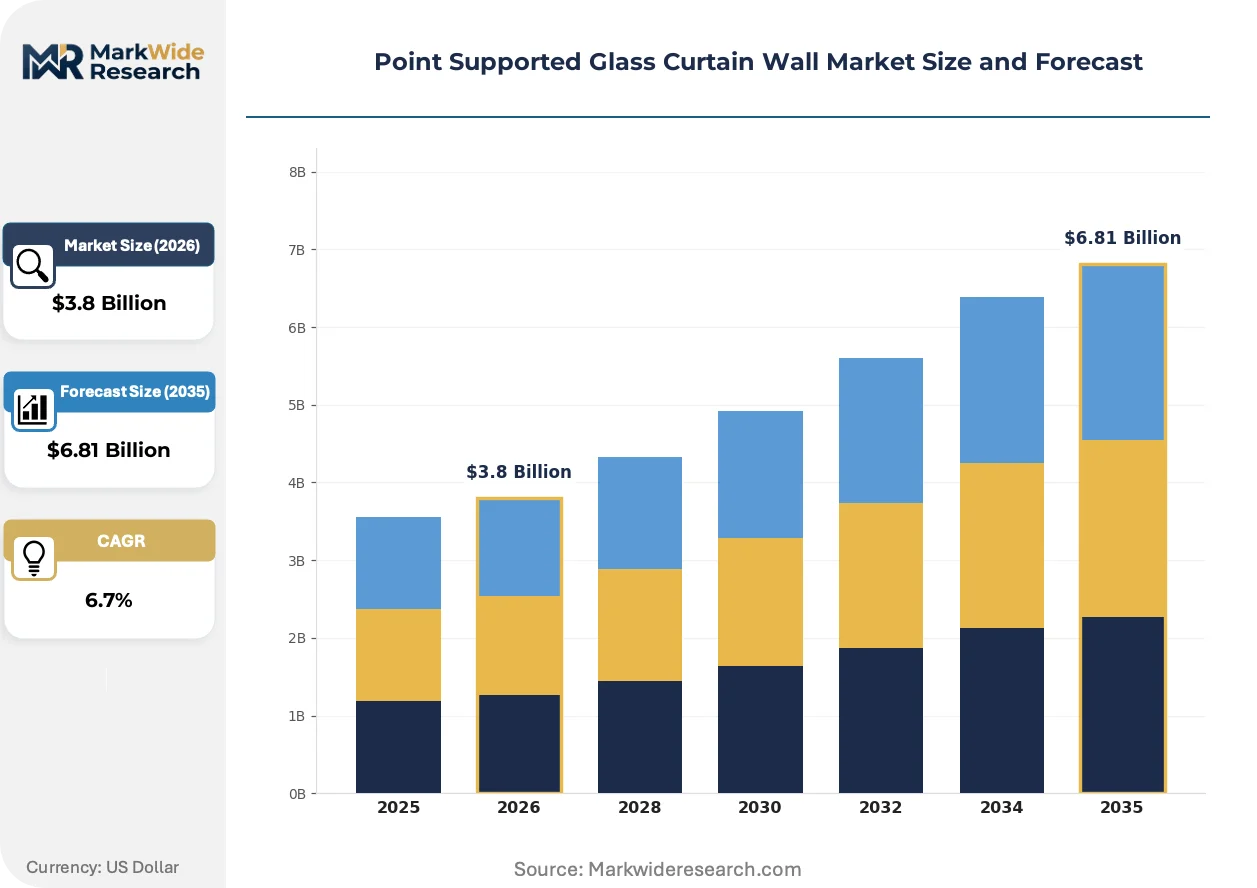
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spider Fittings, Bolted Glass, Cable Net Systems, Glass Fins Application: Commercial Complexes, Airports, Museums, Exhibition Centers End User: Architectural Firms, Construction Companies, Facade Consultants, Real Estate Developers Material: Toughened Glass, Laminated Glass, Insulated Glass, Tempered Glass |
| Companies Covered | Apogee Enterprises, YKK Corporation, Arconic Corporation, Enclos Corp., W&W Glass, Oldcastle BuildingEnvelope, Permasteelisa North America, Benson Curtain Wall & Glass, Yuanda China, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Point Supported Glass Curtain Wall Market Trends and Innovations
Digital fabrication and embodied carbon accounting are restructuring how point-fixed glazing systems are engineered, procured, and certified across high-rise and cultural building types.
Robotic glass edge grinding and CNC drilling of countersunk bolt holes is automating panel preparation for point-supported assemblies, reducing dimensional tolerance errors that previously required field adjustment. Airport terminal contractors in the UAE and museum developers in Qatar are specifying robot-fabricated panels to compress installation schedules on complex geometry facades. This automation is compressing the competitive advantage of traditional manual fabrication shops in lower-cost manufacturing regions.
The EU's CSRD disclosure requirements and China's MEE embodied carbon tracking are mandating Environmental Product Declarations for imported facade materials before public project eligibility. Structural silicone, laminated interlayers, and stainless steel hardware must now document cradle-to-gate carbon intensity. European commercial developers and Chinese state-owned contractors are pre-qualifying suppliers based on EPD availability, disadvantaging smaller fabricators without lifecycle assessment capabilities.
Design-build procurement is displacing traditional design-bid-award sequences in Middle East commercial and hospitality developments, concentrating specification authority with integrated facade contractors. Single-source responsibility for engineering, fabrication, and installation is compressing owner risk but narrowing access for specialized hardware suppliers without turnkey capability. This concentration is most visible in Dubai and Riyadh, where giga-project developers favor consolidated contracting to accelerate entitlement timelines.
Point Supported Glass Curtain Wall Market Segmentation
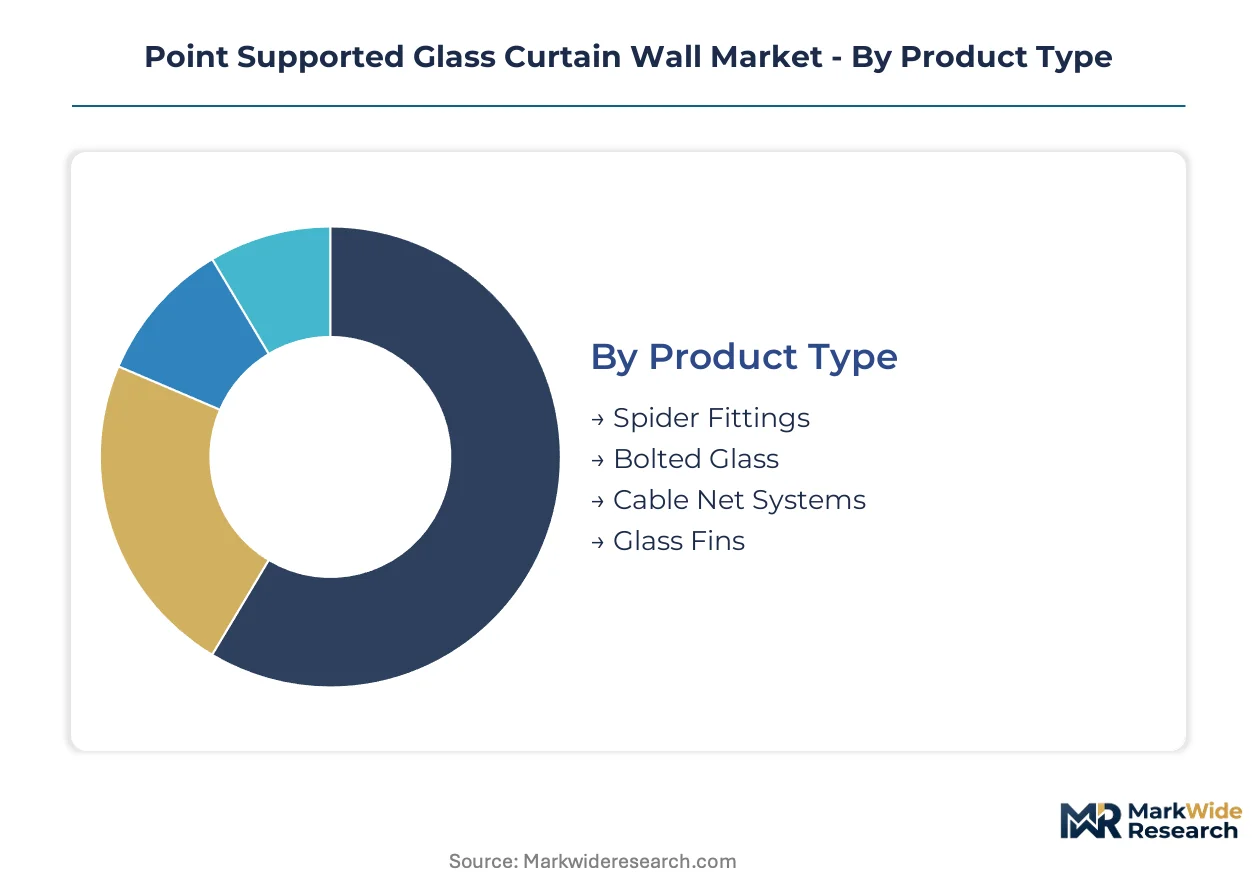
Point-supported glazing systems fragment across hardware topology, building typology, procurement channel, and glass composition. Each dimension shapes specification authority, margin structure, and certification burden differently across project pipelines.
Product Type:
Supply concentrates with stainless steel casting foundries in Italy and Germany that dominate spider fitting and cable net hardware production.
- Spider Fittings:Four-arm or two-arm stainless steel castings transfer point loads from glazing to structural supports through countersunk bolt assemblies. NEOM and Red Sea Project developments in Saudi Arabia are specifying custom-finished spider fittings for hospitality atriums, with procurement teams requiring mill-certificate traceability on 316-grade stainless.
- Cable Net Systems:Pre-tensioned stainless steel strand grids suspend glazing across spans exceeding conventional frame limits, with recent fatigue-resistance advances extending service life in high-wind zones. Museum and airport commissions in the UAE and Qatar are driving specification volume for cable net atriums where uninterrupted sightlines are architect-mandated.
- Bolted Glass:Countersunk stainless steel fittings penetrate laminated panels directly, eliminating perimeter frames entirely. China's domestic project pipelines favor bolted systems for mid-rise commercial retrofits under tightening GB seismic standards.
- Glass Fins:Vertical glass blades provide lateral stability to point-fixed facades, creating all-glass envelopes for exhibition halls. European museum developers specify low-iron glass fins to minimize visual distortion in daylight harvesting configurations.
Spider fittings absorb the bulk of installed capacity; cable net systems are expanding most quickly.
Application:
Cost tier differentiation separates prestige cultural commissions from volume commercial specifications.
- Commercial Complexes:Office and retail atriums in the Middle East specify point-fixed glazing for lobby transparency, with developer procurement teams prioritizing installation speed over custom engineering. Saudi giga-project pipelines are elevating architect-specified point glazing in Riyadh and Jeddah commercial towers.
- Airports:Terminal modernization programs under US FAA fragmentation criteria mandate point-fixed systems for passenger circulation zones. Dubai and Doha hub expansions are driving specification rates for cable net roof assemblies spanning departure halls.
- Museums:Daylight-dependent exhibition spaces require high-transparency envelopes with minimal structural interference. Qatar's cultural venue pipeline favors spider fitting assemblies for gallery perimeter glazing.
- Exhibition Centers:Temporary and permanent trade show facilities utilize point-fixed systems for flexible interior partitioning. Chinese state-owned contractors are integrating prefabricated point-supported modules into exhibition hall expansions.
Commercial complexes command the greatest installed base; airport terminals are climbing the fastest.
End User:
Procurement authority is concentrating with integrated design-build contractors across Middle East developments.
- Architectural Firms:Signature practices in Milan, Dubai, and Shanghai specify point-fixed systems for visual transparency in atrium and transit designs. Zaha Hadid Architects and Foster + Partners drive premium hardware specification through performance-based facade briefs.
- Construction Companies:Turnkey contractors in the UAE and Saudi Arabia are consolidating engineering, fabrication, and installation responsibility under single-source contracts. Consolidated procurement narrows access for specialized hardware suppliers without captive installation crews.
- Facade Consultants:Structural glass engineering specialists perform wind load simulation and seismic analysis for complex geometry projects. Talent scarcity concentrates in Milan, Dubai, and Shanghai, constraining project delivery capacity elsewhere.
- Real Estate Developers:Gulf sovereign wealth-backed developers pre-qualify suppliers based on embodied carbon disclosure under China's MEE frameworks. Lifecycle cost modeling is displacing first-cost bidding in UAE commercial complexes.
Construction companies capture the greatest procurement volume; facade consultants are gaining specification influence fastest.
Material:
Margin structure varies with thermal performance certification and carbon disclosure requirements.
- Toughened Glass:Heat-strengthened panels provide impact resistance for point-fixed applications with minimal framing. Chinese producers are broadening export capacity for high-transparency facade panels serving Middle East project pipelines.
- Laminated Glass:PVB or ionoplast interlayers retain post-breakage integrity for safety-critical applications. EU CSRD disclosure requirements now mandate Environmental Product Declarations for laminated interlayers in public project eligibility.
- Insulated Glass:Double or triple glazing configurations meet tightening energy codes for high-rise construction. REPowerEU building renovation targets are retrofitting commercial atriums with insulated point-fixed units.
- Tempered Glass:Fully tempered panels offer higher surface compression for wind load resistance. Float glass energy costs and silica sand supply disruptions are compressing margins for Chinese tempered panel exporters.
Laminated glass commands the premium specification tier; insulated glass configurations are gaining share fastest under energy code tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Float glass manufacturing clusters in Shandong Province anchor Asia-Pacific feedstock supply for toughened facade panels. Stainless steel hardware foundries in northern Italy and Germany dominate spider fitting and cable net component production for premium architectural specifications.
China
Domestic project pipelines across Yangtze River Delta commercial towers consume bolted glass systems under tightening GB seismic standards. The MEE enforces embodied carbon disclosures on imported facade materials, pre-qualifying suppliers with Environmental Product Declarations. Shanghai and Beijing clusters concentrate robotic glass edge grinding capacity for point-supported panel fabrication.
United Arab Emirates
Giga-project developments in Dubai and Abu Dhabi elevate architect-specified cable net atriums for hospitality and transit terminals. MOHAP procurement guidelines favor consolidated design-build contractors with turnkey facade capability. Jebel Ali industrial zone hosts integrated fabrication lines serving Red Sea Project hardware demand.
Saudi Arabia
NEOM and Qiddiya developments specify custom-finished spider fittings with 316-grade stainless mill-certificate traceability. The Saudi Building Code adoption tightens wind load resistance requirements for point-fixed assemblies. Riyadh and Jeddah commercial towers concentrate specification volume for high-transparency lobby glazing.
Germany
REPowerEU building renovation targets retrofit commercial atriums with insulated point-fixed units for daylight harvesting. CE marking and ETAG 002 standards extend certification timelines for structural silicone compatibility. Bavarian and North Rhine-Westphalia fabricators supply precision-engineered hardware to Middle East project pipelines.
United States
FAA glazing fragmentation criteria mandate point-fixed systems in airport terminal modernization programs. Design-build procurement concentrates specification authority with integrated facade contractors in Dallas-Fort Worth and Atlanta hub expansions. California OSHPD requires jurisdiction-specific shake-table testing for seismic zone hardware validation.
Point Supported Glass Curtain Wall Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue building-integrated photovoltaic convergence and embodied carbon disclosure capabilities. The vendor base stratifies across three tiers: integrated design-build contractors capturing turnkey contracts, specialized hardware fabricators supplying spider fittings and cable nets, and regional glass processors providing toughened and laminated panels. Dominant competitive moves include backward integration into stainless steel casting foundries and strategic partnerships with robotic fabrication equipment suppliers.
Within the integrated contractor tier, Yuanda China and Permasteelisa North America exemplify scale-driven positioning across Asia-Pacific and North American project pipelines. Arconic Corporation anchors the engineered metal hardware segment with seismic-zone structural performance capabilities. Among North American specialists, Apogee Enterprises and Oldcastle BuildingEnvelope occupy positions in commercial complex and airport terminal specifications.
| Leading Market Players |
|---|
| Apogee Enterprises |
| YKK Corporation |
| Arconic Corporation |
| Enclos Corp. |
| W&W Glass |
| Oldcastle BuildingEnvelope |
| Permasteelisa North America |
| Benson Curtain Wall & Glass |
| Yuanda China |
| Others |
Pricing and Supply Chain Analysis
Sovereign wealth-backed developers in the UAE and Saudi Arabia are consolidating procurement under design-build contractors, compressing supplier margins while elevating lifecycle cost modeling over first-cost bidding. This ownership pattern tightens pricing discipline across spider fitting and cable net hardware tiers, rewarding fabricators with captive stainless steel casting capacity and embodied carbon disclosure capabilities.
Pricing Analysis
Warranty and installation service bundling separates premium spider fitting suppliers from unbundled commodity hardware vendors across Middle East giga-projects. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under China's GB standards and EU CE marking, plus geographic delivery cost to Red Sea Project sites. Price erosion runs through standard-tier Chinese toughened panel exports as float glass energy costs compress margins. Commercial complex developers in Riyadh and Jeddah exhibit highest price sensitivity; museum and airport architects in Qatar and Dubai remain least sensitive, prioritizing span performance and mill-certificate traceability.
Supply Chain Analysis
Saudi Arabia's local content mandates under Vision 2030 are reshaping sourcing patterns, requiring 316-grade stainless mill-certificate traceability for NEOM hardware specifications. Supply concentrates with foundries in Italy and Germany for spider fittings, Chinese producers in Shandong Province for toughened glass feedstock, and UAE fabricators in Jebel Ali for integrated panel processing. Raw material dependencies span silica sand for float glass, nickel-bearing stainless for cable nets, and structural silicone for laminated assemblies. Single-source vulnerability concentrates in Italian casting foundries serving premium architectural specifications. Distribution runs through consolidated design-build contractors with turnkey facade capability across Dubai and Riyadh developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The point supported glass curtain wall market sits in a technology-transition phase as robotic glass edge grinding and CNC drilling displace manual fabrication, compressing field adjustment tolerance and installation schedules for complex geometry facades.
For Market Incumbents: Lock in specification authority by deepening backward integration into stainless steel casting foundries in Italy and Germany, securing mill-certificate traceability for Saudi giga-project compliance. Invest in robotic fabrication partnerships to defend against Chinese producers' automated panel capacity expansion. Certification investment under China's MEE embodied carbon frameworks and EU CSRD disclosure requirements serves as the critical lever for pre-qualification on public project pipelines. For New Entrants and Emerging Players: Building-integrated photovoltaic laminates offer a technology-first wedge into net-zero commercial tower specifications where energy generation merges with transparency requirements. Target exhibition center retrofits in China's Yangtze River Delta under tightening GB seismic standards, where mid-rise commercial applications favor bolted glass systems over cable net complexity. Pursue design-build subcontractor partnerships with UAE consolidated contractors as the primary go-to-market angle, bypassing direct architect specification barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized facade consultants with seismic zone hardware validation capabilities in Milan, Dubai, and Shanghai, where talent scarcity constrains project delivery capacity elsewhere. Long-term viability hinges on positioning for performance-based procurement displacement of first-cost bidding across the analysis window. Watch for inflection in Saudi Building Code wind load resistance adoptions as the signal for premium hardware demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Casting | Captures mill-certificate traceability required by NEOM and Red Sea Project procurement teams. |
| Robotic Fabrication Partnership | Compresses dimensional tolerance errors for complex geometry airport terminal commissions in Qatar. |
| Photovoltaic Glass Convergence | Merges energy generation with point-fixed transparency for net-zero commercial tower specifications. |
| Environmental Product Declaration Investment | Pre-qualifies suppliers under China's MEE and EU CSRD for public project eligibility. |
| Design-Build Contractor Alliance | Secures specification access as consolidated procurement narrows channel entry for hardware specialists. |
Research Methodology
Document review covered technical standards including China's GB 16776 seismic codes, EU ETAG 002 structural silicone protocols, and US FAA glazing fragmentation criteria, complemented by interviews with facade engineering directors, stainless steel hardware procurement leads at Middle East developers, robotic fabrication equipment suppliers, and structural glass consultants in Milan and Dubai. Secondary validation drew from customs trade data on float glass and stainless steel strand imports, SEC filings of listed facade contractors, and project development databases for giga-project pipelines. Bottom-up project pipeline enumeration triangulated against top-down market sizing across hardware topology and building typology segments.
Cross-referencing historical specification rates with expert panel input on cable net fatigue resistance advances and embodied carbon disclosure adoption shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include hardware topology, building typology, procurement channel, and glass composition, with regional regulatory clusters treated as distinct adoption curves. CAGRs derived from weighted average of demand elasticity estimates and supply capacity expansion schedules, incorporating airport terminal modernization program announcements and REPowerEU renovation target trajectories as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including abrupt shifts in China's dual carbon policy enforcement, silica sand export restrictions from Southeast Asian suppliers, and unforeseen seismic code revisions in Japan or California. Forecasts reflect documented assumptions on stainless steel strand price stability and laminated interlayer availability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Runway Pavement Grade Asphalt Market
Building & Construction Materials
Concrete Aggregate Market
Building & Construction Materials
Sheet Metal Market
Building & Construction Materials
Building Modules Market
Building & Construction Materials
GCC Faucet Market
Building & Construction Materials
Warm Mix Asphalt Market
Building & Construction Materials
Insulated Concrete Form (ICF) Market
Building & Construction Materials
Tar Paper Market
Building & Construction Materials
Welded Steel Tanks Market
Building & Construction Materials
Poland Ceramic Tiles Market
Building & Construction Materials
North America Rainscreen Cladding Market
Building & Construction Materials
China Concrete Superplasticizer Market
Building & Construction Materials
Red Brick Market
Building & Construction Materials
Sink Float Tank Market
Building & Construction Materials
Particleboard Market
Building & Construction Materials
Sandwich Panel System Market