
 Air Barrier Market | 2026-2036
Air Barrier Market Size, Share, and Industry Trends Forecast 2026-2036
Air Barrier Market Analysis
Building envelope specialty distribution is reconfiguring as national distributors consolidate regional air barrier suppliers and expand technical service capabilities. BASF SE leverages its polyurethane chemistry platform to sustain membrane performance leadership across climate zones. DuPont de Nemours, Inc. anchors its position through Tyvek brand recognition and building science education programs that shape specifier behavior. Carlisle Companies Inc. competes through integrated roofing and waterproofing distribution that bundles air barrier solutions with membrane systems.
An air barrier is a continuous plane of materials, joints, and assemblies that resists uncontrolled air flow between conditioned and unconditioned spaces, typically achieving air permeance below 0.02 L/(s·m²) at 75 Pa differential pressure to satisfy ASTM E2178 testing protocols. Its primary purpose is to eliminate infiltration-driven thermal loads, moisture condensation within wall cavities, and associated structural degradation in framed construction. Membranes command the largest value share due to established specification pathways in commercial construction, while liquid-applied coatings represent the fastest-expanding segment as contractors seek field-adaptable detailing at complex geometries. Rigid panels occupy a mature niche in prefabricated wall assemblies where factory quality control offsets premium material costs.
The International Code Council publishes the IECC which mandates continuous air barrier coverage in climate zones 3 through 8, while ASTM International maintains E2357 whole-building air leakage testing standards that jurisdictions adopt into local amendments. The National Institute of Standards and Technology has quantified air barrier performance impacts on HVAC sizing, creating economic justification tools that accelerate code adoption. Stakeholders must monitor state-level stretch code proliferation and utility incentive program design, as these mechanisms increasingly determine whether advanced air barrier specifications penetrate mid-market construction segments.
Market Dynamics
Stringent energy code adoption across North America is compressing specification windows and forcing material upgrades as jurisdictions enforce IECC amendments mandating continuous air barrier coverage.
Growth Catalysts
- IECC Climate Zone Mandates:Code jurisdictions in zones 3 through 8 now require documented air barrier continuity, creating specification pull for compliant membrane and fluid-applied systems.
- HVAC Downsizing Economics:NIST quantification of air leakage impacts on mechanical system sizing gives developers hard cost justification for premium envelope investments.
- Prefabrication:Offsite wall panel manufacturers integrate rigid air barrier substrates at factory scale, embedding quality control that field-applied methods cannot replicate.
Market Restraints
- Petrochemical Input Volatility:Polyurethane and acrylic resin costs fluctuate with crude oil indices, squeezing margin on liquid-applied membrane formulations.
- Specialty Contractor Concentration:Certified air barrier installer pools remain shallow in secondary US markets, limiting project throughput outside major metropolitan corridors.
- Alternative Envelope Strategies:Rainscreen cavity ventilation systems with pressure-moderated joints compete for specification in mild climate zones where code minimums permit less stringent air tightness.
Strategic Opportunities
- Mid-Market Retrofit:Utility incentive program expansion in states like Massachusetts and New York creates accessible financing for air barrier upgrades in Class B commercial stock.
- Building-Integrated Photovoltaics Convergence:Air barrier manufacturers partnering with BIPV module suppliers can capture envelope-plus-energy specification bundles in net-zero commercial projects.
- Digital Submittal Platforms:Third-party certification databases streamline code official review, reducing approval friction for innovative membrane products entering new jurisdictions.
Industry Challenges
- Detail Complexity at Penetrations:Field crews struggle with consistent sealing around MEP rough-ins, generating callback risk and warranty exposure for membrane system warranties.
- Whole-Building Testing Coordination:ASTM E2357 blower door scheduling conflicts with interior build-out timelines, compressing envelope contractor completion windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Barrier Market |
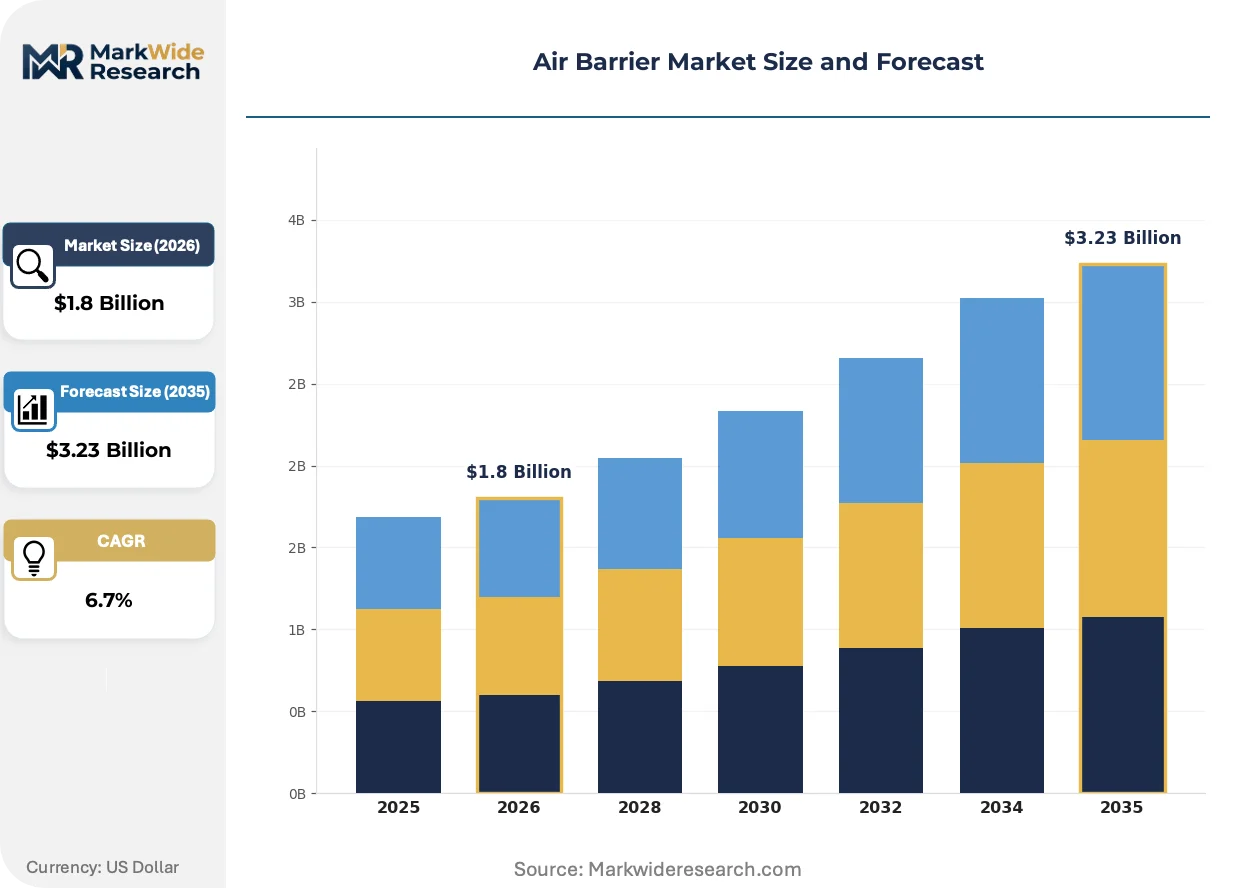
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membranes, Coatings, Sealants, Rigid Panels Application: Commercial Buildings, Residential Homes, Industrial Facilities, Renovation Projects Delivery Mode: Rolls, Sheets, Liquid Form, Pre-formed Shapes End User: Contractors, Architects, Engineers, Homeowners |
| Companies Covered | BASF SE, DuPont de Nemours, Inc., Carlisle Companies Inc., W.R. Meadows, Inc., 3M Company, Soprema Group, GCP Applied Technologies Inc., CertainTeed Corporation, Owens Corning, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Barrier Market Emerging Trajectories
Material science advances are dissolving traditional boundaries between air barrier, vapor control, and thermal functions, creating multifunctional envelope layers that simplify assembly sequencing.
Fluid-applied membrane chemistry is hybridizing silicone and polyurethane backbone structures to achieve both low-temperature cure flexibility and UV resistance without secondary protection. High-rise envelope contractors in Chicago and Toronto are specifying these systems for podium slab transitions where sheet membrane detailing fails. The convergence is compressing demand for standalone vapor retarders in mixed-humidity climate zones.
ASHRAE 90.1 appendix amendments are tightening air leakage limits for commercial envelopes, triggering specification reviews in jurisdictions referencing the standard. Building departments in California and Washington are adopting these limits into local energy codes ahead of IECC revision cycles. Manufacturers with pre-validated whole-building test data capture specification preference where code officials lack field verification capacity.
Specifier behavior is rotating toward performance-based envelope specifications that delegate material selection to contractor means-and-methods. Design-build delivery in Texas and Florida healthcare construction embeds air barrier accountability within single-source envelope contracts. This compresses traditional architect-specifier influence and elevates contractor technical capability as a competitive differentiator.
Air Barrier Market Segmentation
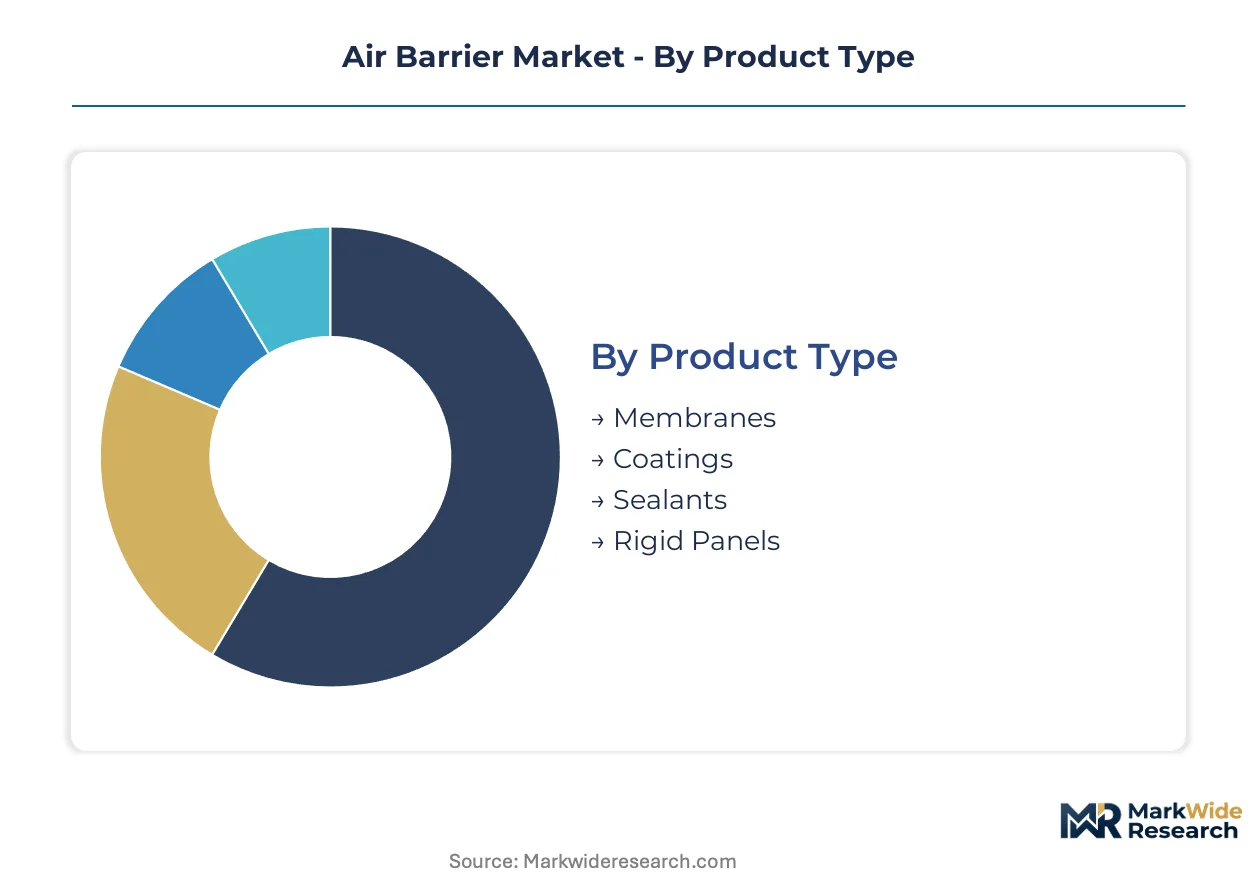
Segmentation in the air barrier market reveals how specification pathways diverge across building types, installation methods, and professional decision-makers. Understanding these divisions exposes where technical education, distribution investment, and code compliance tools generate competitive advantage.
Product Type:
Maturity varies sharply across material platforms, with established sheet goods competing against emergent fluid chemistries for specification share.
- Membranes:Sheet-based polyethylene and polypropylene assemblies achieve sub-0.02 L/(s·m²) permeance ratings through factory-controlled calendering. Commercial envelope specifications in the United States and Canada concentrate here due to decades of IECC compliance documentation and contractor familiarity with heat-welded seam detailing.
- Coatings:Fluid-applied polyurethane and silicone hybrids cure into monolithic layers that adapt to complex geometries without field cutting. Podium slab transitions and curtainwall perimeters in high-rise construction across Chicago, Toronto, and Vancouver drive specification as sheet membranes fail at these irregular interfaces.
- Sealants:Acrylic and butyl compounds bridge membrane overlaps and penetration points. These materials command lower per-square-foot value but generate recurring demand through maintenance cycles and warranty repair protocols.
- Rigid Panels:Factory-laminated gypsum or fiber-cement substrates integrate air barrier, vapor control, and structural sheathing in prefabricated wall assemblies. Offsite construction facilities in the United States embed these panels at production scale where quality control offsets material premiums.
Membranes retain volume leadership; coatings hold the steepest expansion curve.
Application:
End-use concentration maps directly onto code enforcement intensity and capital investment cycles across building sectors.
- Commercial Buildings:Office, retail, and institutional envelopes face the strictest IECC climate zone mandates for documented air barrier continuity. ASHRAE 90.1 appendix amendments tighten leakage limits ahead of base code cycles, triggering specification reviews in California and Washington state jurisdictions.
- Residential Homes:Single-family and multifamily construction adopt air barriers through builder program requirements rather than prescriptive code. ENERGY STAR certification and utility rebate structures in Massachusetts and New York create accessible financing pathways that penetrate mid-market housing stock.
- Industrial Facilities:Warehouse and manufacturing envelopes prioritize operational energy cost reduction over envelope sophistication. ASHRAE standards for process cooling loads create niche specification for high-performance air barriers in controlled-environment production.
- Renovation Projects:Deep energy retrofits of Class B commercial stock access utility incentive programs for air barrier upgrades. Building envelope forensics identify infiltration-driven thermal bridging as a primary target for intervention.
Commercial buildings dominate specification value; residential retrofits climb fastest as incentive programs expand.
Delivery Mode:
Physical form factors determine logistics economics, field labor requirements, and waste generation at the construction site.
- Rolls:Continuous membrane sheets up to 10 feet wide minimize field seams in large wall areas. Distribution concentrates through building envelope specialty channels that provide technical support for contractor training and code submittal preparation.
- Sheets:Pre-cut dimensions target specific opening flashings and detail conditions. These formats reduce cutting waste but require precise quantity estimation and generate higher per-square-foot packaging and handling costs.
- Liquid Form:Pail or drum containers enable spray, roller, or brush application without geometric constraints. Shelf life and temperature-controlled storage requirements complicate inventory management for distributors serving secondary markets.
- Pre-formed Shapes:Injection-molded or thermoformed corners, pipe boots, and window bucks standardize critical detail execution. Factory geometry eliminates field cutting errors that generate warranty exposure and callback risk.
Rolls sustain the highest shipment volumes; liquid forms gain share fastest among specialty contractors.
End User:
Decision-making authority fragments across project phases, with specification influence shifting from design professionals to installation contractors under design-build delivery.
- Contractors:Single-source envelope subcontractors in Texas and Florida healthcare construction now carry air barrier accountability within integrated roofing and waterproofing contracts. Technical capability with fluid-applied systems and whole-building testing protocols differentiates competitive position.
- Architects:Specifier behavior rotates toward performance-based envelope requirements that delegate material selection to contractor means-and-methods. Continuing education programs from membrane manufacturers shape familiarity with specific product platforms.
- Engineers:Building envelope consultants validate air barrier continuity through hygrothermal modeling and whole-building leakage testing. ASTM E2357 blower door coordination falls within their scope on projects pursuing green building certification.
- Homeowners:Residential decision-making concentrates in custom construction and deep retrofit contexts where direct engagement with energy efficiency outcomes overrides first-cost sensitivity.
Contractors command the largest procurement volume; engineers drive the fastest adoption of performance-based specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Houston's petrochemical throughput underwrites Gulf Coast polyurethane resin supply chains that feed membrane manufacturing across North American construction markets.
United States
Commercial building code adoption concentrates specification pull in California, Washington, and Massachusetts where stretch codes exceed IECC baselines. The Department of Energy's Building Technologies Office funds envelope performance validation that accelerates air barrier deployment in federal construction. Chicago's high-rise podium construction cluster drives fluid-applied system specification for complex geometry detailing.
Germany
Passive House Institute certification requirements create premium demand for sub-0.6 ACH50 whole-building airtightness that exceeds typical commercial standards. The Federal Ministry for Economic Affairs and Climate Action funds deep retrofit programs targeting 1950s-1970s building stock with integrated envelope solutions. The Rhine-Ruhr industrial corridor hosts membrane manufacturing facilities serving Central European distribution networks.
Canada
National Building Code amendments harmonize air barrier continuity requirements across provinces, compressing specification windows for commercial envelope contractors. Natural Resources Canada's EnerGuide rating system embeds air tightness metrics in residential new construction marketing. Toronto's condominium tower pipeline generates sustained demand for fluid-applied systems at podium and balcony transitions.
China
Dual carbon policy targets drive envelope performance upgrades in commercial building energy efficiency standards issued by the Ministry of Housing and Urban-Rural Development. The Yangtze River Delta manufacturing cluster produces rigid air barrier panels for prefabricated construction systems targeting 14th Five-Year Plan decarbonization goals. Shanghai's Pudong district mandates whole-building air leakage testing for large commercial projects.
United Kingdom
Future Homes Standard 2025 implementation tightens fabric energy efficiency targets that elevate air barrier specification in residential construction. The Department for Business, Energy and Industrial Strategy funds envelope innovation through the Industrial Strategy Challenge Fund. London's commercial retrofit pipeline targets 2050 net-zero compliance with deep envelope interventions in 1960s-1980s office stock.
Air Barrier Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying chemistries and substrates to branded membrane assemblers. The vendor base concentrates among diversified materials conglomerates with construction chemicals portfolios and regional waterproofing specialists with distribution depth in specific climate zones. Three archetypes dominate: multinational chemical platforms leveraging polymer science crossovers, building envelope specialists bundling air barriers with roofing and waterproofing systems, and regional contractors with captive membrane fabrication serving local code jurisdictions. Consolidation pressure runs through distributor acquisitions of certified installer networks; technical service capability emerges as the primary differentiation vector as specification authority shifts toward contractor means-and-methods.
Among chemical-platform players, BASF SE and DuPont de Nemours, Inc. occupy positions where polymer science heritage translates into membrane performance claims. Carlisle Companies Inc. exemplifies the envelope-system integrator archetype, bundling air barrier specification with established roofing and waterproofing distribution relationships. These three entities represent distinct competitive vectors: chemistry-led material innovation, brand-anchored specifier education, and contractor-facing technical service integration.
| Leading Market Players |
|---|
| BASF SE |
| DuPont de Nemours, Inc. |
| Carlisle Companies Inc. |
| W.R. Meadows, Inc. |
| 3M Company |
| Soprema Group |
| GCP Applied Technologies Inc. |
| CertainTeed Corporation |
| Owens Corning |
| Others |
Supply Flow & Price Mechanics
The Port of Houston's petrochemical throughput anchors North American polyurethane resin supply, concentrating feedstock pricing power among Gulf Coast chemical producers who dictate membrane formulation costs for downstream air barrier manufacturers serving commercial construction across climate zones 3 through 8.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and volume commitment. Premium tiers command position through PHI-certified airtightness performance and extended warranty terms, while economy grades serve residential retrofit programs where utility rebates offset first-cost sensitivity. Pricing pressure stems from acrylic and polyurethane resin volatility tracking crude oil indices, compressing margins on liquid-applied formulations. Mid-market commercial contractors exhibit highest price sensitivity, deferring to standard-grade membranes unless stretch code mandates force upgrade.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for rigid panel substrates and specialty sealant chemistries. Manufacturing concentrates in the United States, Germany, and China, with the Yangtze River Delta hosting prefabricated panel production for Asian markets and the Rhine-Ruhr corridor serving Central European distribution. Feedstock dependence on MDI and polyol derivatives from petrochemical complexes creates vulnerability to energy price spikes. Distribution runs through building envelope specialty channels that bundle technical training with material supply, consolidating procurement decisions among certified installer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The air barrier market represents a high-growth disruption as IECC climate zone mandates harden from voluntary stretch codes into enforced baselines, compressing specification windows and forcing material upgrades across commercial construction.
For Market Incumbents: Harden market position through backward integration into polyurethane resin production, capturing margin from volatile petrochemical inputs that currently squeeze liquid-applied membrane profitability. Invest in factory-laminated rigid panel capacity to serve prefabrication demand from offsite wall manufacturers seeking embedded quality control. Certify installer networks at scale to defend against regional waterproofing specialists bundling air barriers with roofing systems. For New Entrants and Emerging Players: Mid-market commercial retrofits in Massachusetts and New York represent the most penetrable entry point, where utility incentive program expansion creates accessible financing for Class B building envelope upgrades underserved by incumbent distribution. Fluid-applied silicone-polyurethane hybrids for high-rise podium transitions offer technical differentiation where sheet membranes fail at complex geometries. Partner with digital submittal platforms to streamline code official review and reduce approval friction in new jurisdictions. For Investors and Strategic Acquirers: Long-term, this sits as a building decarbonization infrastructure play because envelope performance upgrades constitute the lowest-cost pathway to net-zero compliance for existing commercial stock. Target acquisition profiles should emphasize regional envelope specialists with captive certified installer networks and established relationships with single-source roofing contractors. The signal to watch is state-level stretch code proliferation, as jurisdictions exceeding IECC baselines determine whether advanced specifications penetrate mid-market segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive MDI supply insulates margin from Gulf Coast petrochemical volatility. |
| Prefabricated Panel Manufacturing Scale-Up | Factory quality control offsets premium material costs for offsite wall producers. |
| Certified Installer Network Acquisition | Technical service capability differentiates as specification authority shifts to contractors. |
| Fluid-Applied Chemistry R&D Partnership | Silicone-polyurethane hybrids capture high-rise podium specification from sheet membranes. |
| Digital Submittal Platform Integration | Third-party certification databases reduce approval friction for innovative membrane products. |
Methodological Framework
Desk research of building code amendment records, ASTM and ASHRAE standard documentation, and utility incentive program filings preceded structured interviews with commercial envelope contractors, building science consultants, membrane manufacturer technical directors, and code official review staff. Secondary validation drew from IECC adoption tracking databases, NIST building performance studies, and construction materials trade flow data. Bottom-up segment sizing triangulated against top-down energy code compliance modeling across climate zones.
Assumptions held fixed include continued IECC climate zone mandate enforcement intensity and prevailing petrochemical feedstock pricing relationships, while variables tested included stretch code proliferation velocity and prefabrication adoption rates across commercial construction. The analytical framework modeled product type, application sector, and delivery mode segmentation throughout the forecast period. CAGRs derived from installation volume trajectories correlated with code compliance deadlines and green building certification penetration curves.
Macroeconomic conditions sit as an overlay; deviation in commercial construction starts, interest rate environments affecting retrofit financing accessibility, or petrochemical input cost shocks would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement consistency and material substitution elasticity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Ultra High Performance Concrete (UHPC) Market
Building & Construction Materials
EPS Sandwich Panels Market
Building & Construction Materials
Asia-Pacific Cross-Laminated Timber Market
Building & Construction Materials
Global Rainscreen Cladding Market
Building & Construction Materials
Tar Paper Market
Building & Construction Materials
North America Ceiling Tiles Market
Building & Construction Materials
Risers Market
Building & Construction Materials
Rebars Market
Building & Construction Materials
Australia and New Zealand Industrial Flooring Market
Building & Construction Materials
Household Mosaic Tiles Market
Building & Construction Materials
Indonesia Ceramic Tiles Market
Building & Construction Materials
India Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Drainage System Market
Building & Construction Materials
North America Concrete Cellulose Fiber Reinforcement Market
Building & Construction Materials
Global Aggregates Market
Building & Construction Materials
Geogrid Market