
 Glazed Tiles Market | 2026-2036
Glazed Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Glazed Tiles Market Analysis
Residential construction is decoupling from hospitality-driven renovation cycles as the dominant demand engine for glazed tiles. Mohawk Industries leverages its North American manufacturing footprint to anchor supply for large-format porcelain flooring. RAK Ceramics sustains export dominance across the Middle East through vertically integrated production in the UAE. Kajaria Ceramics Limited specializes in India's premium residential segment, competing on design breadth rather than commodity volume.
Glazed tiles are ceramic or porcelain surfacing materials coated with a glass-forming silica-based layer, fired at temperatures exceeding 1,000 degrees Celsius to create a non-porous, stain-resistant finish specified for interior and exterior architectural applications. Porcelain variants command the strongest margin pools due to density specifications that support thin-format large panels for commercial wall cladding. Ceramic retains volume leadership in residential flooring where cost sensitivity shapes procurement. The hospitality end user segment shows the fastest specification growth, driven by renovation cycles in luxury hotel chains seeking durable, low-maintenance surfaces.
ISO 13006 defines ceramic tile classification and quality benchmarks that govern cross-border trade acceptance, while India's BIS certification mandates ceramic glaze durability testing for domestic market access. The EU's REACH framework restricts heavy metal content in ceramic glazes, forcing reformulation of traditional lead-based fluxes across European supply chains. China's GB standards for building ceramics enforce water absorption thresholds that filter substandard producers from state-backed infrastructure tenders. Stakeholders must monitor regulatory divergence between emission standards and performance testing protocols as procurement patterns fragment across regional compliance zones.
Market Dynamics
India's BIS certification mandates for ceramic glaze durability testing are compressing supply timelines while forcing quality-tier stratification across export corridors. Hospitality renovation cycles operating on compressed three-to-five-year refresh schedules are pulling specification demand away from traditional residential construction timelines.
Growth Catalysts
- REACH heavy metal restrictions:ECHA's reformulation requirements for lead-based ceramic glazes are accelerating R&D investment in alternative flux chemistries across European supply chains.
- Hospitality specification surge:Luxury hotel chains are prioritizing large-format porcelain for high-traffic lobbies and guest bathrooms, creating durable surface demand independent of new construction.
- Vietnam export corridor concentration:Manufacturing clusters around Ho Chi Minh City and Hai Phong are capturing specification tile orders from Australian and Middle Eastern importers seeking cost-competitive quality.
Market Restraints
- Feldspar and zircon input volatility:Ceramic tile body formulations depend on concentrated feldspar deposits from Turkey and zircon sand from Australia, exposing margins to mining supply disruptions and freight cost spikes.
- Foshan supply concentration:China's building ceramics sector clusters in Guangdong Province, creating single-point vulnerability to regional power rationing and environmental compliance shutdowns under MEE enforcement.
- Thin-format technical limits:Large porcelain panels below 6mm thickness require specialized handling equipment and certified installer networks that remain scarce outside major metropolitan markets.
Strategic Opportunities
- Saudi giga-project pipeline:NEOM and Red Sea tourism developments are specifying premium glazed tiles for coastal and desert hospitality applications with accelerated procurement timelines.
- Digitally printed surface convergence:Inkjet decoration technology combined with through-body porcelain coloration is enabling custom short-run production for boutique hospitality brands.
- E-commerce specification channels:Architect and interior designer platforms are disintermediating traditional distributor relationships, allowing direct sample-to-specification workflows for commercial projects.
Industry Challenges
- Certified installer scarcity:Large-format porcelain panel installation requires specialized training and equipment that existing tile contractor networks lack, slowing specification adoption in secondary markets.
- BIS testing backlog:India's domestic market access depends on glaze durability certification queues that currently extend beyond six months, delaying product launches for reformulated compositions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glazed Tiles Market |
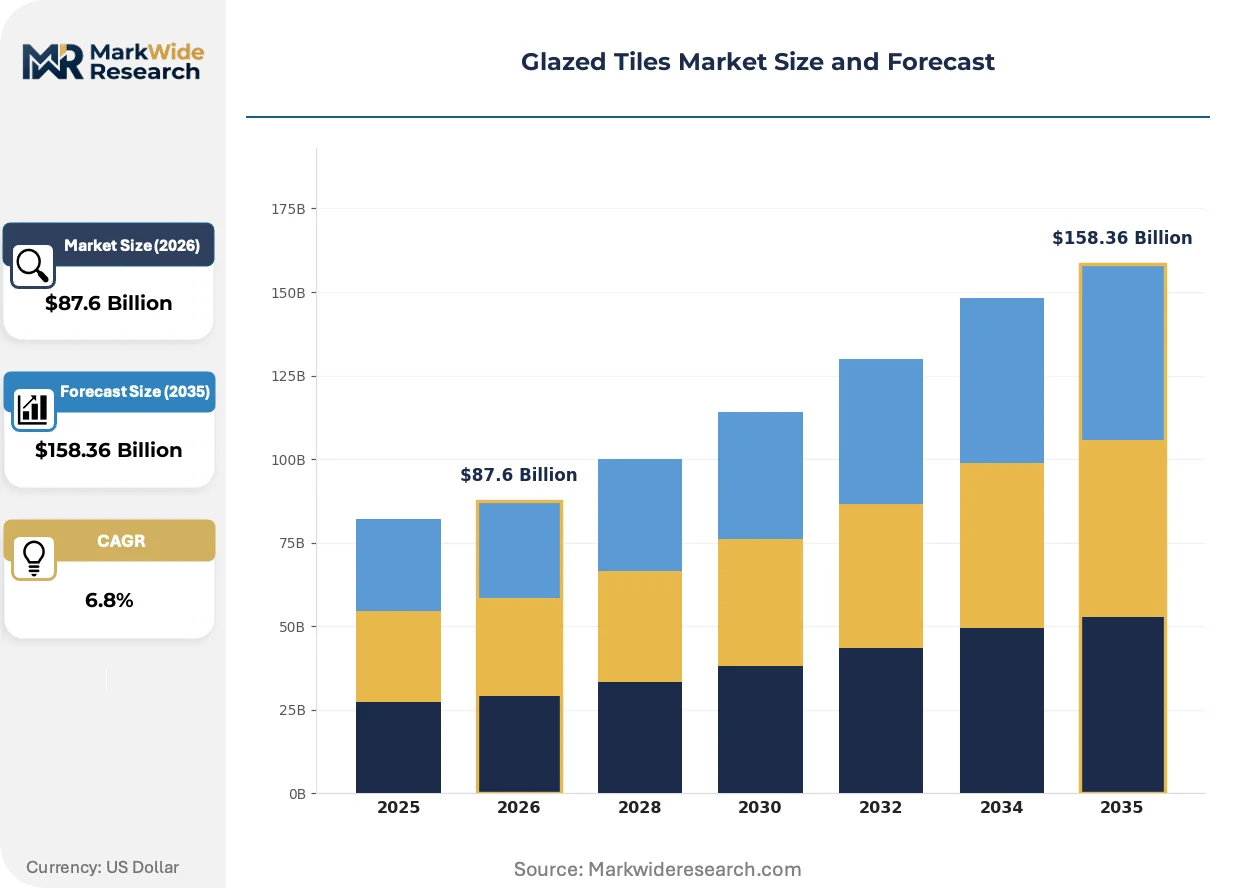
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic, Porcelain, Glass, Stone Application: Flooring, Wall Cladding, Countertops, Outdoor End User: Residential, Commercial, Industrial, Hospitality Distribution Channel: Retail, Online, Wholesaler, Direct Sales |
| Companies Covered | Mohawk Industries, RAK Ceramics, Kajaria Ceramics Limited, Grupo Lamosa, Pamesa Cerámica, Porcelanosa Grupo, SCG Ceramics, Atlas Concorde, Cerámica Carmelo Fior, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glazed Tiles Market Emerging Trajectories
Digital surface decoration technologies are compressing design-to-production cycles while enabling batch-size flexibility that traditional screen printing cannot match. Regulatory pressure on heavy metal content is forcing material science innovation across glaze chemistry portfolios.
Single-pass inkjet printing with reactive inks is rewriting how tile manufacturers manage SKU proliferation and inventory risk. Hospitality designers are specifying digitally printed stone and wood replicas at volumes that now rival natural material procurement. This technology is rewriting the economics of short-run custom production, collapsing minimum order quantities from container-load to pallet-load scales.
REACH Annex XVII restrictions on lead and cadmium in ceramic glazes are forcing reformulation of traditional flux systems across EU-facing production lines. Spanish and Italian manufacturers are investing in boron-alternative melt chemistry to maintain surface hardness specifications without restricted additives. Export-oriented plants in Morocco and Turkey are capturing specification share by achieving REACH compliance ahead of domestic competitors.
Architects are consolidating specification authority through digital material libraries that bypass traditional distributor showrooms. Large hospitality chains are deploying centralized procurement platforms that standardize tile specifications across property portfolios, compressing supplier negotiation cycles. This concentration is most visible in Dubai and Riyadh, where master developers specify materials across multiple hotel and residential towers simultaneously.
Glazed Tiles Market Segmentation
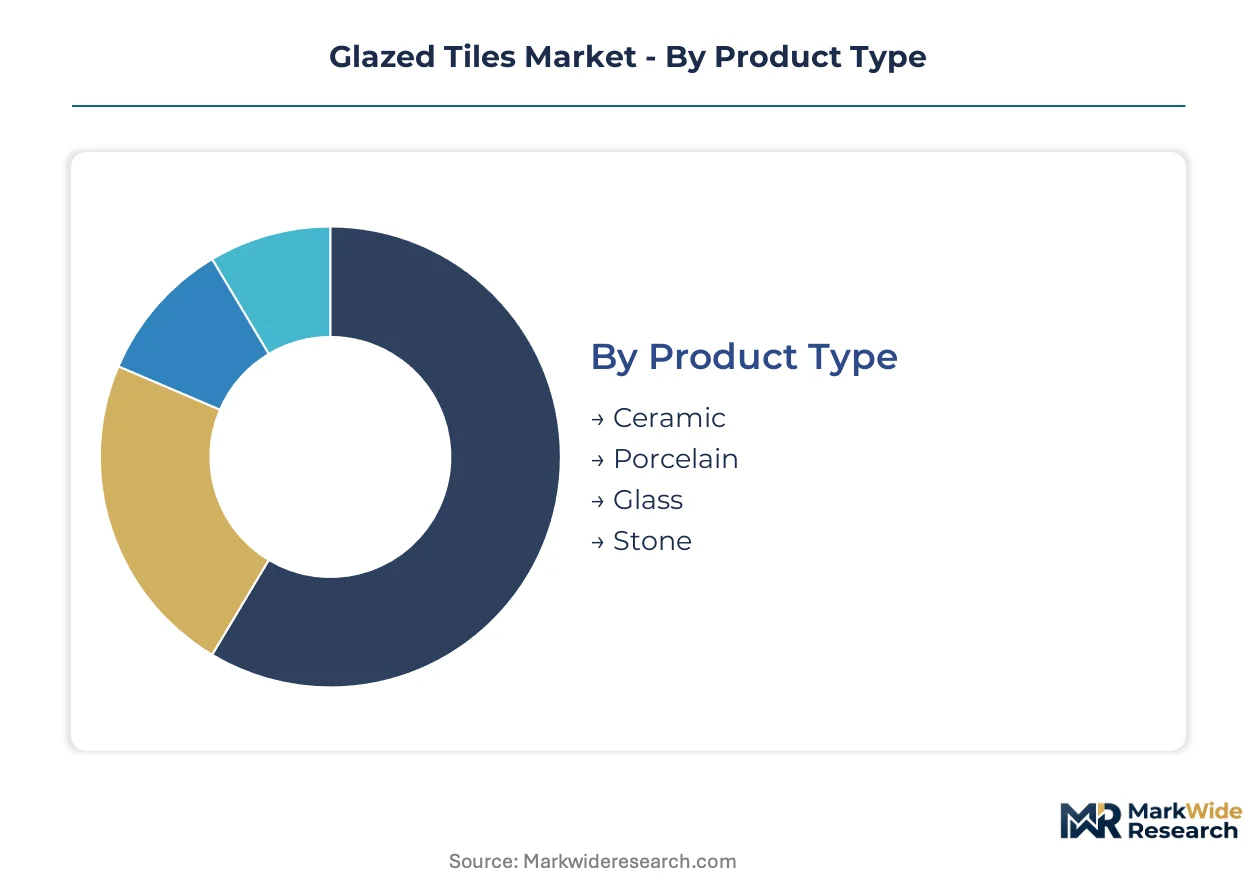
Glazed tiles serve distinct performance requirements across architectural surfaces, with specification decisions driven by traffic load, moisture exposure, and aesthetic durability rather than interchangeable commodity selection. Segmentation reveals how manufacturers align production capabilities with divergent end-use demands.
Product Type:
Upgrade cycles vary dramatically by material density, with porcelain replacement intervals stretching twice as long as ceramic in high-traffic commercial installations.
- Ceramic:Clay-based bodies with water absorption above 0.5% suit residential flooring where cost thresholds dominate procurement. India's BIS certification mandates are compressing supply timelines for reformulated glazes targeting this volume segment.
- Porcelain:Fired at higher temperatures to achieve sub-0.5% absorption, these dense bodies support large-format panels for hospitality wall cladding where durability specifications are non-negotiable. Demand concentrates in Saudi giga-projects specifying thin-format panels for accelerated construction timelines.
- Glass:Recycled silica compositions deliver translucent surfacing for accent walls and backsplashes in boutique hospitality interiors.
- Stone:Natural material glazing preserves organic variation while adding stain resistance for luxury residential applications.
Volume placements concentrate in Ceramic; the faster expansion belongs to Porcelain.
Application:
Surface location determines glaze hardness specifications, with flooring applications demanding Mohs ratings two tiers above wall installations.
- Flooring:Abrasion-resistant glazes with PEI ratings of 4-5 support residential and commercial foot traffic. Specification demand is decoupling from new construction cycles as hospitality renovation accelerates refresh schedules.
- Wall Cladding:Large-format porcelain panels reduce grout lines for seamless hospitality interiors. REACH heavy metal restrictions are forcing reformulation of decorative glazes across EU-facing production lines.
- Countertops:Heat-resistant glaze chemistries withstand kitchen thermal shock in residential and food-service environments.
- Outdoor:Frost-resistant formulations with enhanced slip resistance serve climate-exposed installations in northern European and North American markets.
Specification density runs highest in Wall Cladding; Flooring retains the deepest volume base.
End User:
Procurement authority fragments across decision-makers, with architects controlling commercial specifications while homeowners drive retail channel volume.
- Residential:Cost-sensitive volume segment where ceramic dominates flooring replacement and kitchen renovation cycles. India's premium segment competes on design breadth rather than commodity scale.
- Commercial:Office and retail specifications prioritize lifecycle cost over first-cost, favoring porcelain durability in high-traffic circulation zones.
- Industrial:Chemical-resistant glaze formulations serve manufacturing and laboratory environments with specialized performance requirements.
- Hospitality:Luxury hotel chains are consolidating procurement across property portfolios, creating specification concentration for large-format porcelain in guest bathrooms and lobby surfaces.
Residential channels move the highest unit volumes; Hospitality is climbing the fastest as renovation cycles compress.
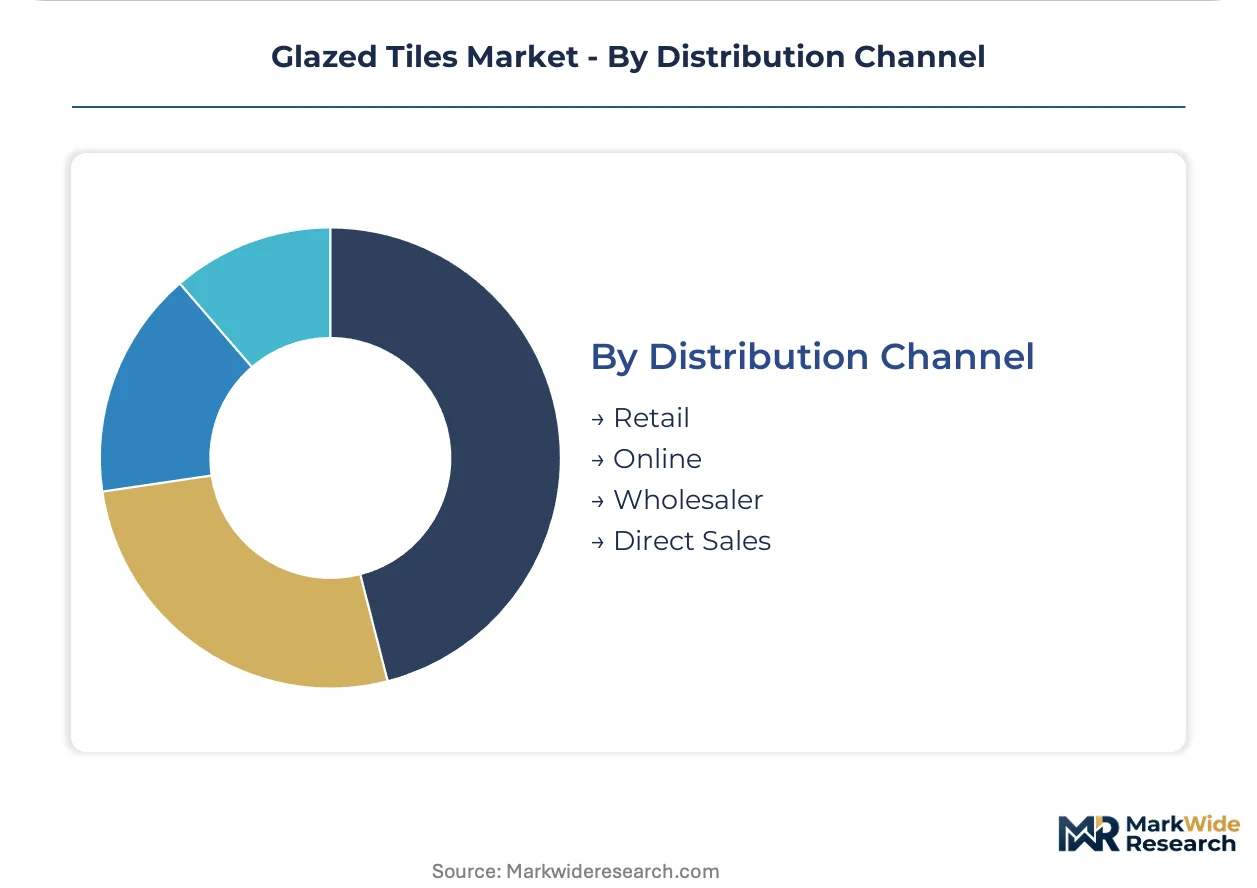
Distribution Channel:
Channel selection reflects project scale and specification complexity, with commercial contracts bypassing retail intermediaries entirely.
- Retail:Showroom-based selection dominates homeowner renovation projects with tactile material evaluation. Vietnam's export corridors are capturing specification orders through cost-competitive quality positioning.
- Online:Architect and designer platforms are disintermediating traditional distributor relationships for sample-to-specification workflows.
- Wholesaler:Volume contractors source standardized grades through regional distribution networks serving multi-unit residential developers.
- Direct Sales:Master developers in Dubai and Riyadh deploy centralized procurement platforms standardizing specifications across simultaneous tower projects.
Retail maintains the broadest geographic reach; Direct Sales is gaining share fastest through hospitality procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Vietnam's manufacturing corridors are concentrating export-oriented tile production, while India's BIS certification mandates reshape domestic supply timelines. Regulatory divergence across major producing regions is fragmenting procurement patterns and compliance investments.
China
Foshan's ceramics cluster in Guangdong Province drives global supply volume despite environmental compliance pressures from MEE enforcement. GB standards for building ceramics enforce water absorption thresholds that filter substandard producers from state-backed infrastructure tenders. Manufacturing gravity centers on Guangdong's Pearl River Delta, where power rationing and shutdowns create single-point vulnerability.
India
Gujarat and Morbi's tile belt serve premium residential demand where Kajaria Ceramics competes on design breadth rather than commodity scale. BIS certification mandates for ceramic glaze durability testing compress supply timelines while forcing quality-tier stratification across export corridors. Morbi's manufacturing cluster faces certification queues extending beyond six months, delaying product launches for reformulated compositions.
Vietnam
Export-oriented manufacturing around Ho Chi Minh City and Hai Phong captures specification tile orders from Australian and Middle Eastern importers seeking cost-competitive quality. The country's central bank monitors currency stability for dollar-denominated export contracts. Hai Phong's port infrastructure supports containerized shipments to Gulf markets with accelerated procurement timelines.
Italy
Sassuolo's ceramics district anchors European design leadership in large-format porcelain for hospitality applications. REACH Annex XVII restrictions on lead and cadmium in ceramic glazes force reformulation of traditional flux systems across EU-facing production lines. Italian manufacturers invest in boron-alternative melt chemistry to maintain surface hardness specifications without restricted additives.
Saudi Arabia
NEOM and Red Sea tourism developments specify premium glazed tiles for coastal and desert hospitality applications with accelerated procurement timelines. SFDA oversees imported building material compliance alongside national construction codes. Riyadh's master developers deploy centralized procurement platforms standardizing specifications across simultaneous hotel and residential towers.
Glazed Tiles Market Vendor Landscape
Top-tier vendors anchor specification-driven hospitality and premium residential segments, while mid-scale fabricators compete on volume throughput for standard-grade ceramic flooring. The vendor base stratifies across three tiers: multinational surface-material conglomerates with captive distribution, regional specialists with vertically integrated production, and export-oriented contract manufacturers serving private-label demand. Two dominant competitive moves define current positioning: backward integration into raw material sourcing to secure feldspar and zircon supply, and technology licensing partnerships for single-pass inkjet decoration systems.
Within the multinational tier, Mohawk Industries and RAK Ceramics exemplify divergent geographic anchoring strategies. Mohawk leverages its North American manufacturing footprint to supply large-format porcelain flooring for commercial specifications. RAK Ceramics sustains export dominance across Middle Eastern markets through UAE-based vertically integrated production. Kajaria Ceramics Limited occupies a position as India's premium-segment specialist, competing on design portfolio breadth rather than commodity volume scale. These three entities represent the archetype spectrum: continent-anchored supply base, export-corridor vertical integration, and domestic-market premium positioning.
| Leading Market Players |
|---|
| Mohawk Industries |
| RAK Ceramics |
| Kajaria Ceramics Limited |
| Grupo Lamosa |
| Pamesa Cerámica |
| Porcelanosa Grupo |
| SCG Ceramics |
| Atlas Concorde |
| Cerámica Carmelo Fior |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists across Morbi and Foshan anchor supply discipline through generational capital structures that resist short-term margin compression, enabling pricing stability even when raw material volatility spikes freight and mineral input costs.
Pricing Analysis
Lead-time-driven pricing stratification separates spot inventory discounts from premium surcharges on certified short-lead specifications. Three-tier pricing structure across premium, standard, and economy levels reflects BIS certification tier, volume scale, and customization depth. Cost compression in economy-grade ceramic flooring is intensifying because Turkish feldspar supply disruptions and Australian zircon freight spikes squeeze converter margins. Residential renovators exhibit highest price sensitivity, while hospitality procurement teams prioritize lifecycle durability over first-cost.
Supply Chain Analysis
BIS certification queues and REACH Annex XVII compliance gates filter substandard producers from premium specification corridors. Manufacturing gravity centers on China's Guangdong Province, India's Gujarat belt, and Vietnam's Hai Phong corridor, drawing from Turkish feldspar deposits, Australian zircon sand, and Italian glaze chemistry IP. Single-source vulnerability concentrates in Foshan's power-rationing exposure under MEE enforcement. Distribution runs through architect-specification platforms and master-developer direct contracts for hospitality volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from India's six-month BIS certification backlogs and REACH reformulation costs will force subscale glaze formulators and undifferentiated ceramic converters into distressed exits.
For Market Incumbents: Hedge feldspar supply disruption through backward integration into Turkish mining partnerships or long-term offtake with Australian zircon processors. Accelerate boron-alternative R&D to preempt REACH enforcement gaps before competitors achieve compliant scale.
For New Entrants and Emerging Players: Capture specification share in Vietnam's export corridor through digitized short-run production for Australian boutique hospitality brands. Lead with inkjet-enabled custom stone replicas that bypass container-minimum constraints of established players.
For Investors and Strategic Acquirers: Six-month BIS testing queue extensions are the leading indicator that India's domestic certification bottleneck is creating acquisition targets among Morbi's glaze-reformulation specialists. Five-to-ten-year viability favors REACH-compliant producers with captive feldspar supply. Monitor ECHA enforcement acceleration as the inflection signal for European margin recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Supply | Turkish feldspar partnerships insulate margins from mining disruption and freight spikes. |
| Boron-Alternative Glaze Chemistry R&D | REACH Annex XVII compliance unlocks EU hospitality specification access ahead of domestic competitors. |
| Single-Pass Inkjet Decoration Licensing | Short-run digital production collapses minimum orders from container-load to pallet-load scales. |
| Certified Installer Network Development | Large-format porcelain adoption in secondary markets hinges on trained contractor availability. |
| E-Commerce Specification Platform Partnership | Architect-direct channels disintermediate distributor markups for commercial project procurement. |
Methodological Framework
Independent corroboration across plant managers at Morbi and Foshan manufacturing clusters, procurement leads at Middle Eastern hospitality developers, and distribution channel partners in Vietnam's export corridors underwrites the qualitative findings. Secondary validation drew from BIS certification databases, ECHA REACH substance restrictions, customs trade flows, and SEC filings of listed surface-material conglomerates. Bottom-up production capacity surveys triangulate against top-down specification demand estimates from architect and interior designer platform data.
Rate-of-change decomposition across product type, application surface, end-user procurement authority, and distribution channel structure anchors the analytical framework. Modeled dimensions span ceramic versus porcelain density grades, flooring versus wall cladding performance specifications, residential versus hospitality demand cycles, and retail versus direct sales channel mix. CAGRs derive from production capacity expansion schedules, certification queue dynamics, and specification intensity shifts in Saudi giga-project pipelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA enforcement acceleration, Turkish mining license renewals, and Vietnam's central bank currency stability management. Forecasts reflect documented assumptions on BIS testing throughput, REACH reformulation adoption curves, and hospitality renovation cycle compression. A model refresh is warranted upon material change in India's certification queue duration or Saudi procurement timeline acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Bed Headwall Systems Market
Building & Construction Materials
Sink Float Tank Market
Building & Construction Materials
North America Gypsum Board Market
Building & Construction Materials
Vegetal Concrete Market
Building & Construction Materials
India Ready-Mix Concrete Market
Building & Construction Materials
EMEA Prestressed Concrete (PC) Wire and Strand Market
Building & Construction Materials
Roof Window Market
Building & Construction Materials
Finishing Lines Market
Building & Construction Materials
North America UPVC Doors and Windows Market
Building & Construction Materials
Fiberboard Ceiling Market
Building & Construction Materials
Plastic Formwork Market
Building & Construction Materials
Europe Gypsum Board Market
Building & Construction Materials
France Oriented Strand Board Market
Building & Construction Materials
Cement Grinding Aids Market
Building & Construction Materials
US Prefabricated Steel Market
Building & Construction Materials
Africa Construction Chemicals Market