
 Engineered Wood Market | 2026-2036
Engineered Wood Market Size, Share, and Industry Trends Forecast 2026-2036
Engineered Wood Market Intelligence
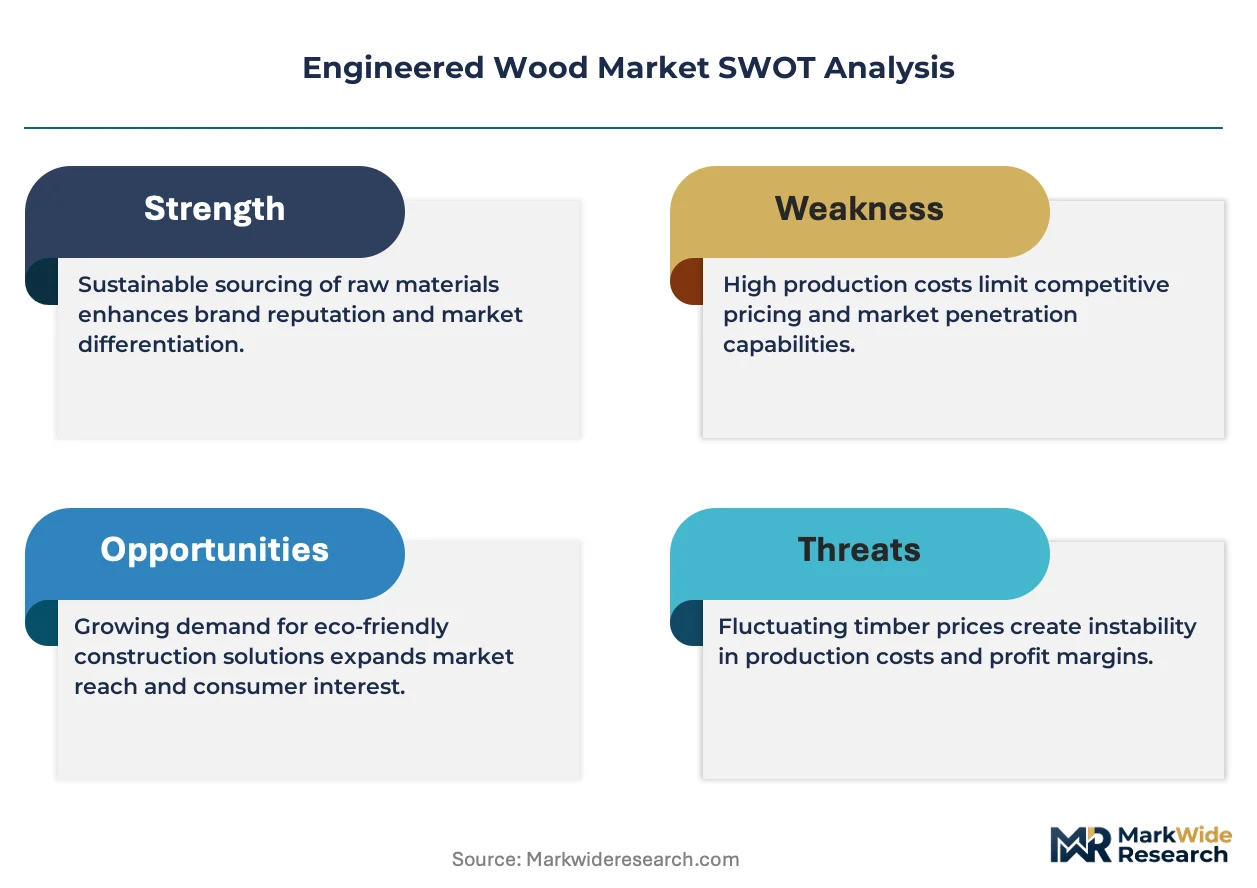
The capital-intensity divergence between integrated timberland owners and specialized panel producers is bifurcating competitive dynamics across the industry. Georgia-Pacific leverages its captive southern yellow pine supply to control input costs across multiple product lines. West Fraser anchors its position through large-scale oriented strand board capacity in the US Southeast and Western Canada. Boise Cascade competes via a balanced portfolio of plywood and engineered lumber tied to distributor relationships.
Engineered wood comprises structural and non-structural composite products manufactured from wood strands, veneers, fibers, or particles bonded with adhesives under heat and pressure, with density ranging from 500 to 1,000 kg per cubic meter depending on product category. Its primary purpose is to deliver predictable mechanical performance, dimensional stability, and efficient material utilization for construction and furniture applications. Oriented strand board dominates volume in North American residential sheathing due to cost efficiency and consistent quality. Laminated veneer lumber commands premium positioning in long-span structural applications where strength-to-weight ratio determines specification. Medium density fiberboard occupies the furniture and cabinetry segment where surface uniformity and machinability drive selection.
The US EPA regulates formaldehyde emissions from composite wood products under TSCA Title VI, directly shaping adhesive formulation and panel certification requirements across domestic manufacturing. The EU Timber Regulation and CE marking under the Construction Products Regulation govern chain-of-custody verification and structural performance claims for European producers. Stakeholders must monitor evolving carbon-accounting frameworks and building-code amendments for tall mass timber structures as jurisdictions recalibrate height and exposure limits.
Market Dynamics
Mass timber engineering capabilities are compressing specification cycles for mid-rise construction, while adhesive chemistry constraints under evolving emissions frameworks force simultaneous reformulation investments across manufacturing footprints.
Growth Catalysts
- EU Timber Regulation:Mandatory chain-of-custody verification accelerates certified sourcing for European construction procurement, elevating compliant suppliers in specification decisions.
- Cross-laminated timber:Structural fire-performance testing advances enable height-limit recalibration in building codes, opening mid-rise segments previously reserved for steel and concrete.
- Germany:Large-format CLT production clusters around Binderholz and Stora Enso anchor supply security for Central European developers, reducing lead-time uncertainty for complex projects.
Market Restraints
- Southern yellow pine supply concentration:Georgia-Pacific and West Fraser control integrated timberland positions in the US Southeast, creating input cost asymmetry for non-integrated panel producers.
- Formaldehyde emission limits:US EPA TSCA Title VI and evolving state-level amendments impose reformulation costs that compress margin structures for commodity-oriented manufacturers.
- Dimensional lumber substitution:Light-frame residential builders retain switching flexibility between OSB sheathing and plywood when relative price spreads compress, capping volume commitment visibility.
Strategic Opportunities
- Carbon-accounting frameworks:Embodied carbon disclosure mandates in public procurement create premium positioning for mass timber suppliers with verified lifecycle data.
- Prefabricated construction:Offsite manufacturing integration enables panelized mass timber systems that compress on-site labor requirements for skilled carpentry-constrained markets.
- Tall mass timber codes:Jurisdictions including Oregon and British Columbia are recalibrating height and exposure limits, creating first-mover advantage for engineering-capable producers.
Industry Challenges
- Mass timber engineering capacity:Qualified structural engineers with timber-specific fire and seismic design expertise remain concentrated in Nordic and Pacific Northwest markets, constraining project scalability.
- CE marking compliance timelines:European manufacturers face extended certification cycles under the Construction Products Regulation for novel adhesive systems, delaying product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engineered Wood Market |
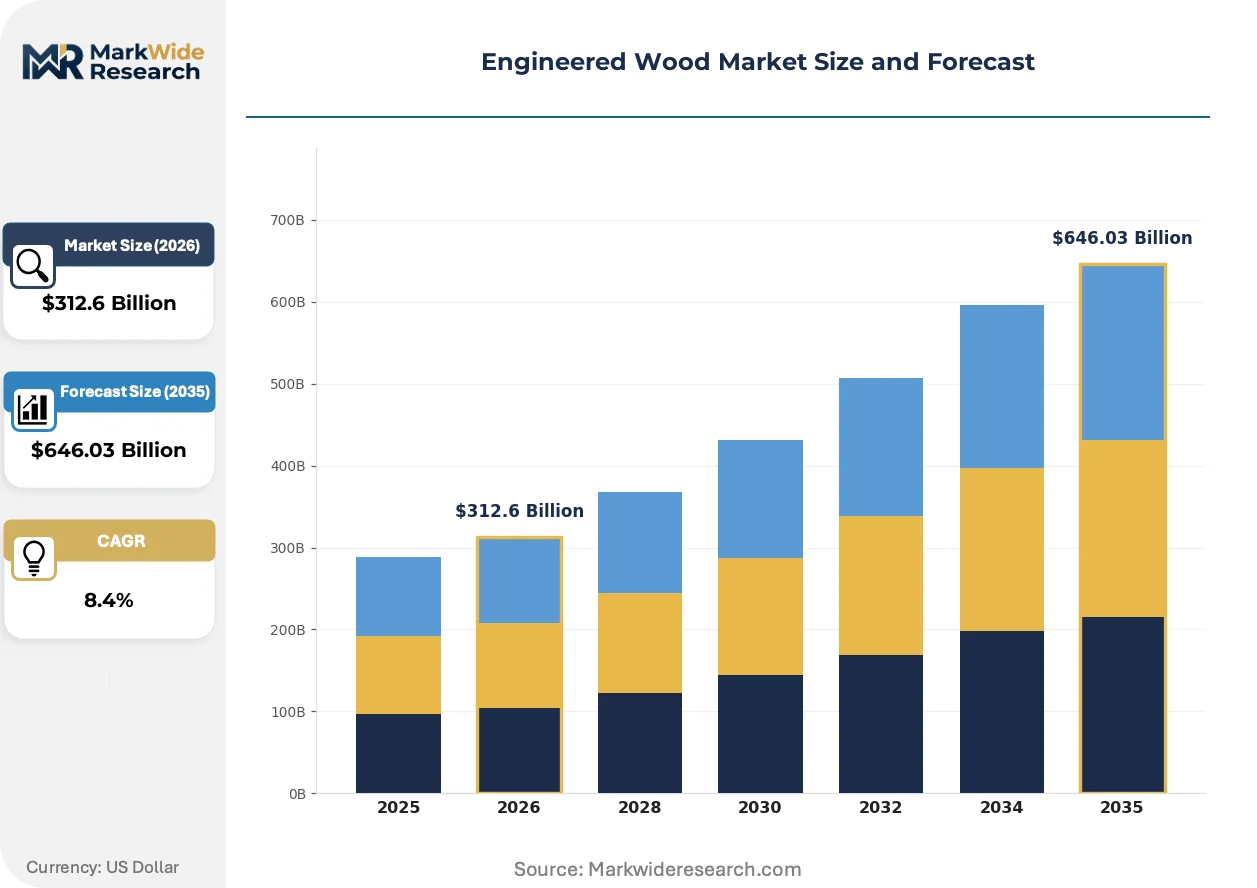
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $646.03 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plywood, Laminated Veneer Lumber, Oriented Strand Board, Medium Density Fiberboard Application: Furniture, Flooring, Cabinetry, Building Construction End User: Residential, Commercial, Industrial, Institutional Distribution Channel: Direct Sales, Retail, Online, Wholesalers |
| Companies Covered | Georgia-Pacific, West Fraser, Boise Cascade, Huber Engineered Woods LLC, Stora Enso, Weyerhaeuser Company, Roseburg, Binderholz GmbH, Louisiana-Pacific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engineered Wood Market Strategic Shifts & Innovations
Adhesive chemistry diversification and digital fabrication integration are compressing traditional manufacturing-process boundaries, while procurement transparency requirements force supply-chain visibility investments.
Bio-based adhesive formulations are fragmenting the historical dominance of formaldehyde-based resins in structural panel production. European manufacturers including those supplying German CLT clusters are accelerating soy-protein and tannin-based system adoption. This chemistry shift is fragmenting competitive positioning between early reformulators and legacy resin-dependent capacity.
REACH authorization processes for isocyanate-based binders are tightening formulation flexibility for European OSB and LVL producers. Industrial consequence includes accelerated R&D allocation toward exempt chemistry pathways. Nordic producers with captive forestry-to-panel integration are responding fastest due to consolidated technical-resource deployment.
Specification decisions increasingly hinge on Environmental Product Declaration availability rather than sole first-cost comparison. General contractors in Pacific Northwest and Scandinavian markets now embed lifecycle carbon data into bid evaluation matrices. This pattern is most visible in public-sector procurement for educational and civic buildings where mandate compliance creates non-price selection criteria.
Engineered Wood Market Segmentation
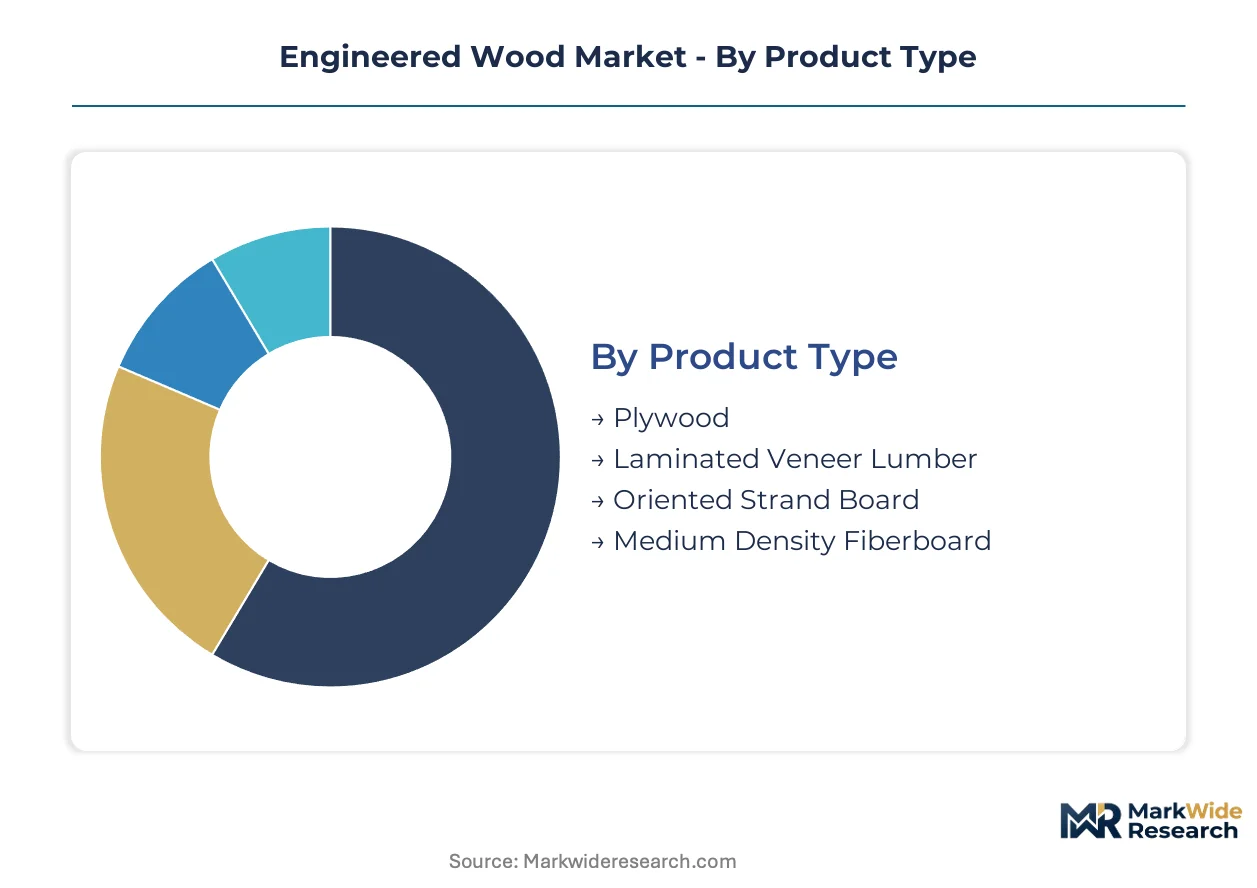
Segmentation in engineered wood reveals distinct procurement patterns across construction and furniture value chains. Product categories map to different specification authority centers, while end-use concentration determines margin capture and inventory risk profiles for manufacturers.
Product Type:
Channel mix varies sharply by product category, with structural panels flowing through distributor networks and non-structural boards concentrating in direct mill-to-furniture-fabricator relationships.
- Oriented Strand Board:Manufactured from cross-oriented wood strands bonded with phenol-formaldehyde or isocyanate resins under heat and pressure. Residential builders in the US Southeast specify OSB for wall sheathing and roof decking, though substitution elasticity with plywood constrains pricing power during lumber price volatility cycles.
- Laminated Veneer Lumber:Composed of peeled veneer sheets laminated parallel to the grain with structural adhesives, delivering predictable strength-to-weight ratios for long-span applications. German and Austrian mid-rise developers specify LVL for primary structural members where CE marking under the Construction Products Regulation governs performance claims.
- Plywood:Cross-laminated veneer construction providing dimensional stability and fastener-holding strength.
- Medium Density Fiberboard:Homogeneous wood fiber mat formed under heat and pressure, prized for surface uniformity in furniture substrates.
OSB dominates installed base in North American residential sheathing. LVL is where expansion concentrates as mass timber engineering capabilities advance.
Application:
Cost tier stratification separates commodity structural applications from premium interior finish specifications, with the former competing on delivered cost and the latter on machinability and surface quality.
- Building Construction:Structural and non-structural applications including sheathing, subflooring, and mass timber systems for mid-rise structures. Oregon and British Columbia building code amendments for tall mass timber are accelerating specification in Pacific Northwest commercial projects where fire-performance testing data supports height-limit recalibration.
- Furniture:Cabinetry, casegoods, and fixture substrates requiring tight thickness tolerances and smooth surfaces for lamination or painting. European furniture manufacturers specify MDF and particleboard from German and Austrian mills where E1 and E05 emission classifications drive adhesive chemistry selection.
- Flooring:Underlayment and decorative hardwood veneer substrates.
- Cabinetry:Kitchen and bath cabinet components demanding moisture-resistant formulations.
Building construction commands volume leadership. Furniture applications are climbing the fastest as European cabinetry exports expand.
End User:
Customer type determines specification authority location, with residential builders delegating material selection to framers and commercial developers retaining engineering-led procurement teams.
- Residential:Single-family and multifamily construction where production builders specify OSB and engineered lumber through national distributor relationships. US EPA TSCA Title VI compliance requirements filter supplier qualification, favoring domestic manufacturers with certified panel testing infrastructure.
- Commercial:Office, retail, and hospitality projects where general contractors embed lifecycle carbon data into bid evaluation matrices. Scandinavian and Pacific Northwest markets now mandate Environmental Product Declaration availability for public-sector educational and civic buildings.
- Industrial:Manufacturing facility construction and material handling applications.
- Institutional:Schools, healthcare, and government buildings with extended design-life requirements.
Residential absorbs the highest shipment volumes. Commercial is gaining share fastest as embodied carbon disclosure mandates proliferate.
Distribution Channel:
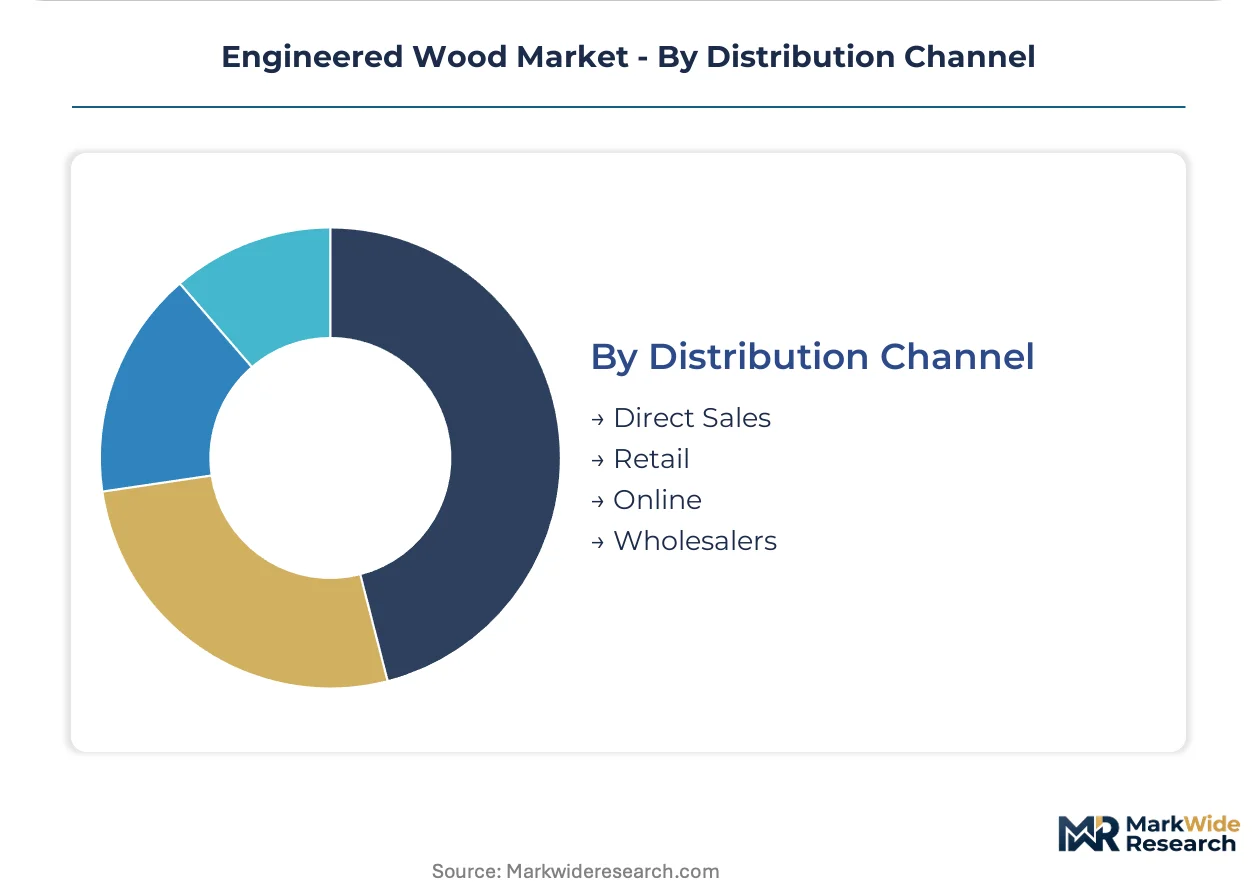
Volume concentration tracks project scale, with large commercial developments sourcing direct from mills and smaller residential jobs flowing through stocking distributors.
- Direct Sales:Mill-direct procurement for large-scale commercial and institutional projects requiring custom panel dimensions or certified chain-of-custody documentation. Binderholz and Stora Enso in Germany anchor direct relationships with Central European developers for CLT supply security.
- Wholesalers:Regional distribution networks aggregating mixed-product loads for residential contractors. US Southeast wholesalers stock southern yellow pine-based OSB and plywood from integrated producers, capturing logistics efficiency through multi-product truckload deliveries.
- Retail:Big-box and specialty lumber yards serving repair and remodeling demand.
- Online:Emerging channel for specification-grade samples and small-quantity specialty orders.
Wholesalers dominate installed base. Direct sales is where expansion concentrates as mass timber project scale increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-setting power concentrates in German and Austrian CLT clusters while North American OSB producers absorb greater input cost volatility from southern yellow pine supply swings.
United States
Residential builders in the Southeast specify OSB sheathing for single-family construction, though substitution elasticity with plywood constrains pricing during lumber volatility cycles. EPA TSCA Title VI compliance filters supplier qualification toward domestic manufacturers with certified testing infrastructure. Georgia-Pacific and West Fraser anchor integrated timberland positions across the US Southeast, controlling input costs for multiple product lines.
Germany
Mid-rise developers specify cross-laminated timber for primary structural members where CE marking under the Construction Products Regulation governs performance claims. EU Timber Regulation mandates chain-of-custody verification, accelerating certified sourcing for European construction procurement. Binderholz GmbH and Stora Enso have anchored large-format CLT production clusters, reducing lead-time uncertainty for complex Central European projects.
Canada
Mass timber engineering capabilities in British Columbia are compressing specification cycles for commercial mid-rise structures. Provincial building code amendments for tall mass timber are recalibrating height and exposure limits, creating first-mover advantage for engineering-capable producers. Western Canadian oriented strand board capacity anchored by West Fraser supplies North American residential sheathing demand.
Austria
Specialized laminated veneer lumber producers serve German mid-rise structural applications where strength-to-weight ratio determines specification. REACH authorization processes for isocyanate-based binders are tightening formulation flexibility, accelerating R&D toward exempt chemistry pathways. Upper Austrian industrial zones concentrate veneer-processing and adhesive-formulation technical resources.
Japan
Seismic-resistant mass timber design expertise concentrates in METI-supported research consortia, though qualified structural engineers with timber-specific fire and seismic capabilities remain scarce. JIS standards govern structural performance claims for engineered wood products in building applications. Kanto region fabricators import European CLT engineering methodologies while adapting to local seismic code requirements.
Engineered Wood Market Key Industry Players
Concentration sits with integrated timberland owners who control captive southern yellow pine supply against specialized panel producers dependent on spot fiber markets. Three strategic archetypes dominate: vertically integrated forest-products conglomerates with multi-product portfolios, regional specialists focused on single structural categories, and Nordic mass timber engineering houses with captive forestry-to-panel integration. Competitive moves center on backward integration into timberland assets and adhesive chemistry reformulation investments under evolving emissions frameworks.
Among North American integrated producers, Georgia-Pacific LLC, West Fraser Timber Ltd., and Boise Cascade Company exemplify the timberland-anchored archetype, each representing distinct geographic and product-mix positioning within the structural panel value chain. Stora Enso Oyj and Binderholz GmbH occupy parallel positions in European mass timber engineering, anchoring the Nordic-Central European corridor where CE marking compliance and carbon-accounting capabilities determine specification access.
| Leading Market Players |
|---|
| Georgia-Pacific |
| West Fraser |
| Boise Cascade |
| Huber Engineered Woods LLC |
| Stora Enso |
| Weyerhaeuser Company |
| Roseburg |
| Binderholz GmbH |
| Louisiana-Pacific Corporation |
| Others |
Cost & Logistics Intelligence
Soy-protein adhesive substitution for formaldehyde-based resins in German CLT production is redrawing supply geography toward Nordic forestry clusters while compressing margin structures for legacy resin-dependent manufacturers locked into spot chemical markets.
Pricing Analysis
Configured-to-order CLT panel pricing commands a 15-25% premium over standard dimension stock due to project-specific engineering and fire-performance certification requirements. Three-tier pricing structure across premium, standard, and economy levels tracks CE marking tier, volume commitment scale, and chain-of-cody documentation depth. Cost compression in commodity OSB sheathing is intensifying because southern yellow pine supply swings amplify input volatility for non-integrated producers. Light-frame residential builders exhibit highest price sensitivity, while commercial developers with embodied carbon mandates show lowest elasticity.
Supply Chain Analysis
Germany and Austria anchor large-format CLT and LVL production for Central European mid-rise construction, with Nordic countries feeding veneer and fiber inputs through integrated forestry-to-panel operations. Manufacturing draws from southern yellow pine timberlands in the US Southeast, peeled hardwood veneers from Central European mills, and isocyanate-based adhesives subject to REACH authorization processes. Single-source vulnerability concentrates in qualified structural engineers with timber-specific fire and seismic expertise, concentrated in Nordic and Pacific Northwest markets. Distribution runs through regional wholesalers for residential contractors and direct mill relationships for commercial mass timber projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineered wood markets reward producers who control timberland assets and adhesive formulation capabilities, while scarcity of mass timber engineering talent constrains project scalability and creates acquisition premiums for technical-resource clusters.
For Market Incumbents: Fortify backward integration into southern yellow pine timberlands to neutralize input cost asymmetry against Georgia-Pacific and West Fraser. Expand CE marking certification infrastructure for novel bio-based adhesive systems to preempt REACH-driven formulation lockout. Prioritize captive forestry-to-panel technical-resource deployment in Nordic corridors where qualified structural engineers concentrate. For New Entrants and Emerging Players: Prefabricated panelized system integration represents a service-layer gap where incumbents under-serve skilled-carpentry-constrained markets in Pacific Northwest and Scandinavian urban corridors. Target direct sales channel penetration for mid-rise commercial projects requiring Environmental Product Declaration availability and lifecycle carbon disclosure. Deploy digital fabrication partnerships as entry wedge against established distributor relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional OSB specialists lacking timberland integration and facing formaldehyde reformulation cost compression. Five-to-ten-year viability hinges on carbon-accounting framework adoption velocity and tall mass timber code expansion. Watch Oregon and British Columbia building code amendment trajectories as inflection signals for engineering-capable producer valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Timberland Assets | Georgia-Pacific's captive southern yellow pine supply neutralizes input cost volatility across OSB and plywood lines. |
| Bio-Based Adhesive Reformulation | European manufacturers accelerating soy-protein systems fragment competitive positioning against legacy resin-dependent capacity. |
| CE Marking Infrastructure Expansion | German CLT clusters under Construction Products Regulation compliance secure specification access for Central European mid-rise developers. |
| Prefabricated Panelized System Development | Offsite manufacturing integration compresses on-site labor requirements for skilled-carpentry-constrained Pacific Northwest markets. |
| Environmental Product Declaration Investment | Verified lifecycle carbon data creates non-price selection criteria in Scandinavian public-sector educational and civic procurement. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with mass timber structural engineers, CLT procurement managers at Central European developers, adhesive R&D directors, and EPA-certified panel testing facility operators; and secondary validation against US EPA TSCA Title VI filings, EU Timber Regulation chain-of-custody databases, Construction Products Regulation CE marking records, and trade flow data from German and Austrian customs authorities. Bottom-up shipment estimates by product category triangulated against top-down construction spend allocation models.
Across the analysis window, forecasts applied product-type segmentation by structural versus non-structural application, end-use concentration across residential and commercial verticals, and regional regulatory cluster differentiation. CAGRs derived from elasticity-adjusted demand projections incorporating substitution dynamics between OSB and plywood sheathing, and mass timber engineering capacity expansion curves. Key inputs included southern yellow pine stumpage price volatility indices and REACH authorization timeline assumptions for isocyanate-based binders.
Forecasts assume regulatory continuity in US EPA TSCA Title VI enforcement and EU Construction Products Regulation certification timelines; material policy shifts in formaldehyde emission limits or tall mass timber height restrictions would require re-modeling. Recalibration cycles align with material shifts in carbon-accounting framework adoption and building code amendment trajectories in Pacific Northwest jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Aluminum Board Raised Access Floor Market
Building & Construction Materials
Autoclave Aerated Concrete Market
Building & Construction Materials
Exterior Sheathing Market
Building & Construction Materials
Global Sandwich Panels Market
Building & Construction Materials
Timber Floor Joist Market
Building & Construction Materials
Gypsum Concrete Market
Building & Construction Materials
Customized Shopfitting Materials Market
Building & Construction Materials
US Ceiling Tiles Market
Building & Construction Materials
Roofing Underlayment Market
Building & Construction Materials
Global Concrete Repair Mortars Market
Building & Construction Materials
Hygienic Cladding Market
Building & Construction Materials
Japan Oriented Strand Board Market
Building & Construction Materials
Foldable Houses Market
Building & Construction Materials
Door and Window Hardware Market
Building & Construction Materials
Global Formwork Market
Building & Construction Materials
Structural Insulated Panels (Sips) Market