
 Prefabricated Bathroom Modules Market | 2026-2036
Prefabricated Bathroom Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Prefabricated Bathroom Modules Market Insights
Skilled plumbing and waterproofing labor availability is collapsing across major construction corridors, pushing general contractors toward factory-integrated bathroom solutions. SurePods leverages its Florida-based manufacturing scale to serve North American hospitality chains with fully finished modules. Guangzhou Seagull Housing Industry Co., Ltd. anchors supply across Asia-Pacific through steel-frame production lines optimized for high-rise residential towers. Walker Modular Limited specializes in concrete-frame units for UK student housing and military barracks, competing on fire-rated performance.
Prefabricated bathroom modules are self-contained wet-room assemblies manufactured off-site with pre-installed plumbing, electrical, and waterproofing systems, typically delivered as steel-frame or concrete-frame units rated for specific load and acoustic performance. These modules eliminate sequential wet-trade coordination on construction sites, compressing project schedules for hotels, hospitals, and residential towers. Fully finished modules dominate current revenue as end users prioritize plug-and-install solutions that minimize on-site finishing labor. Steel-frame technology leads volume in high-rise applications where weight constraints govern structural design, while composite materials represent the fastest-growing category as manufacturers pursue thinner wall profiles and improved thermal bridging performance.
FDA guidelines influence healthcare facility bathroom specifications in the United States, particularly around infection control surfaces and accessibility clearances that modular designs must incorporate at the factory stage. The EU Green Deal and CE marking requirements under the Construction Products Regulation shape European demand by mandating embodied carbon disclosure and energy performance certificates for building components. ECHA REACH compliance on composite material chemistry further constrains supplier formulation choices. Stakeholders must monitor how evolving national building codes reconcile factory quality assurance with site-specific structural integration liabilities.
Market Dynamics
The collapse of skilled wet-trade labor availability across construction corridors is forcing general contractors to outsource bathroom assembly to factory environments, fundamentally restructuring project delivery economics.
Growth Catalysts
- EU Green Deal energy performance mandates:Germany's KBA building codes and EU-wide embodied carbon disclosure requirements are compelling developers to specify factory-built modules with pre-certified thermal bridging performance.
- Steel-frame weight optimization:High-rise residential towers in Dubai and Abu Dhabi are specifying steel-frame bathroom modules to reduce structural load and accelerate vertical construction schedules.
- Healthcare facility mandates:UAE MOHAP infection control specifications for hospital wet rooms are driving procurement of modules with factory-integrated antimicrobial surfaces and sealed plumbing systems.
Market Restraints
- Composite material chemistry constraints:ECHA REACH compliance requirements limit supplier formulation choices for wall panel resins, raising raw material costs and extending qualification timelines.
- Transportation cost volatility:Fuel price fluctuations and specialized flatbed capacity shortages inflate delivered costs for oversized module shipments to remote construction sites.
- Site integration liability fragmentation:Ambiguity between factory quality assurance and structural connection responsibilities creates insurance and warranty disputes that delay contract closures.
Strategic Opportunities
- Modular retrofit penetration:Aging hotel stock in Florida and California presents untapped demand for bathroom replacement modules that minimize guest room downtime.
- Composite-convergence innovation:Thin-wall composite materials combined with integrated smart water monitoring systems enable premium positioning in net-zero residential developments.
- Direct-to-developer channel expansion:Bypassing traditional general contractor markups through factory-direct procurement models captures margin for module manufacturers and cost savings for institutional buyers.
Industry Challenges
- Waterproofing certification bottlenecks:Factory-applied membrane testing protocols lack harmonization across national building codes, forcing redundant third-party validation for export markets.
- Plumbing rough-in coordination:Dimensional tolerances between module utility connections and site infrastructure require skilled trade intervention that erodes schedule advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prefabricated Bathroom Modules Market |
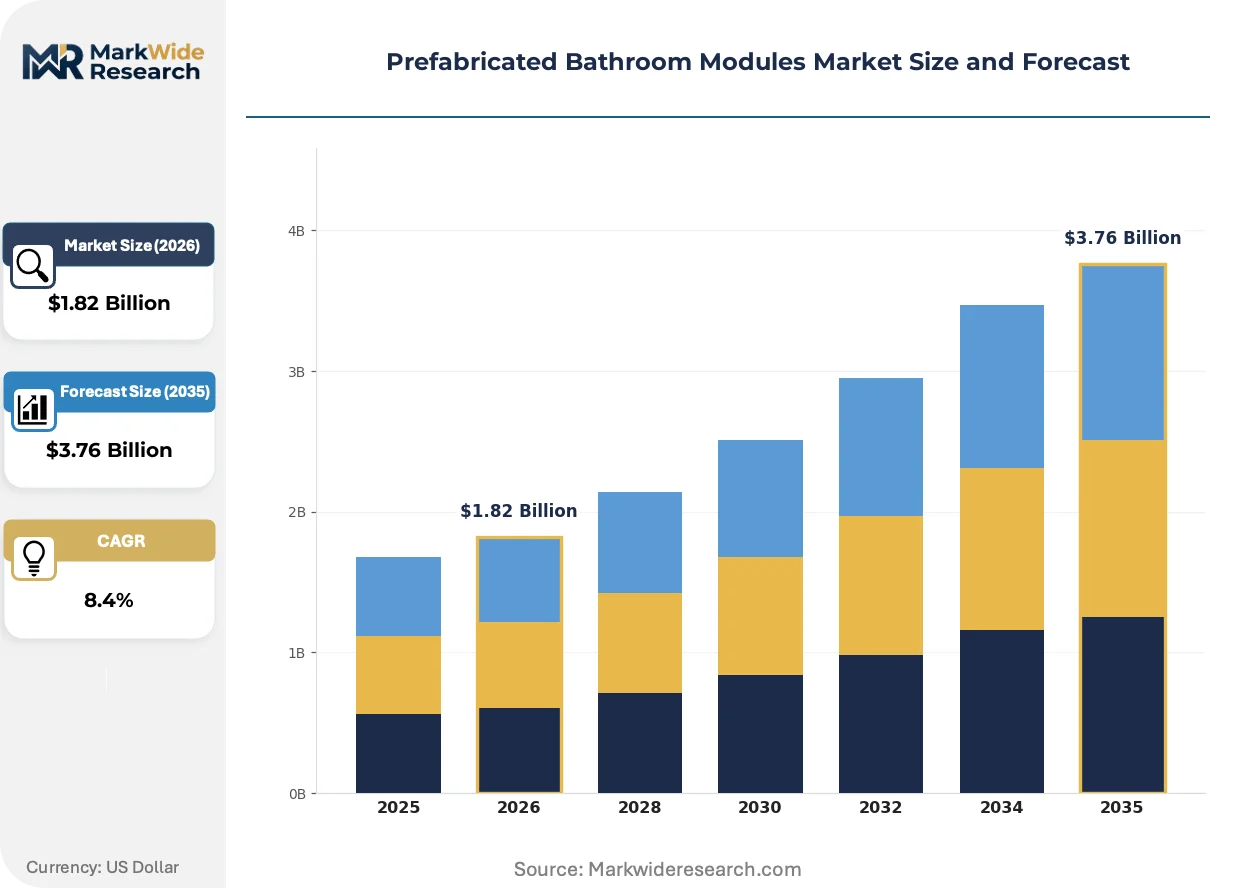
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.76 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fully Finished Modules, Semi-Finished Modules, Frame Only, Customized Units Technology: Steel Frame, Concrete Frame, Composite Materials, Modular Plastics, Timber Frame Application: Hospitality, Commercial Complexes, Educational Institutions, Military Facilities, High-Rise Residences End User: Construction Contractors, Real Estate Developers, Modular Building Providers, Facility Management Firms |
| Companies Covered | Badelement, PDM Constructors Limited, Walker Modular Limited, Interpod Australia Pty Ltd, Bathsystem Group, SurePods, Guangzhou Seagull Housing Industry Co., Ltd., ModularPods, Offsite Solutions Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prefabricated Bathroom Modules Market Trends and Innovations
Digital fabrication and material science advances are compressing module development cycles while regulatory pressure on embodied carbon is reshaping specification criteria across hospitality and healthcare verticals.
Composite wall panel systems with integrated insulation and vapor barriers are decomposing the traditional multi-trade sequential construction process. Hotel developers in the United States are specifying these systems for new-build properties to eliminate on-site waterproofing subcontractor coordination. This technology is decomposing project schedules from twelve-week bathroom rough-in cycles to single-day crane-set operations.
CE marking requirements under the Construction Products Regulation are mandating factory-level environmental product declarations and embodied carbon calculations for bathroom modules entering European projects. Manufacturers must now document supply chain emissions and material circularity credentials before tender qualification. Student housing and military barracks specifications in the United Kingdom are prioritizing concrete-frame modules with verified fire-rated performance and full lifecycle transparency.
General contractors are consolidating vendor relationships around single-source module suppliers who assume design-assist responsibility and warranty integration risk. This concentration is displacing fragmented subcontractor bidding for traditional wet-room construction in high-rise residential towers. The shift is most visible in the United Arab Emirates, where Dubai-based developers are awarding multi-tower contracts to manufacturers with in-house engineering capabilities and regional installation partnerships.
Prefabricated Bathroom Modules Market Segmentation
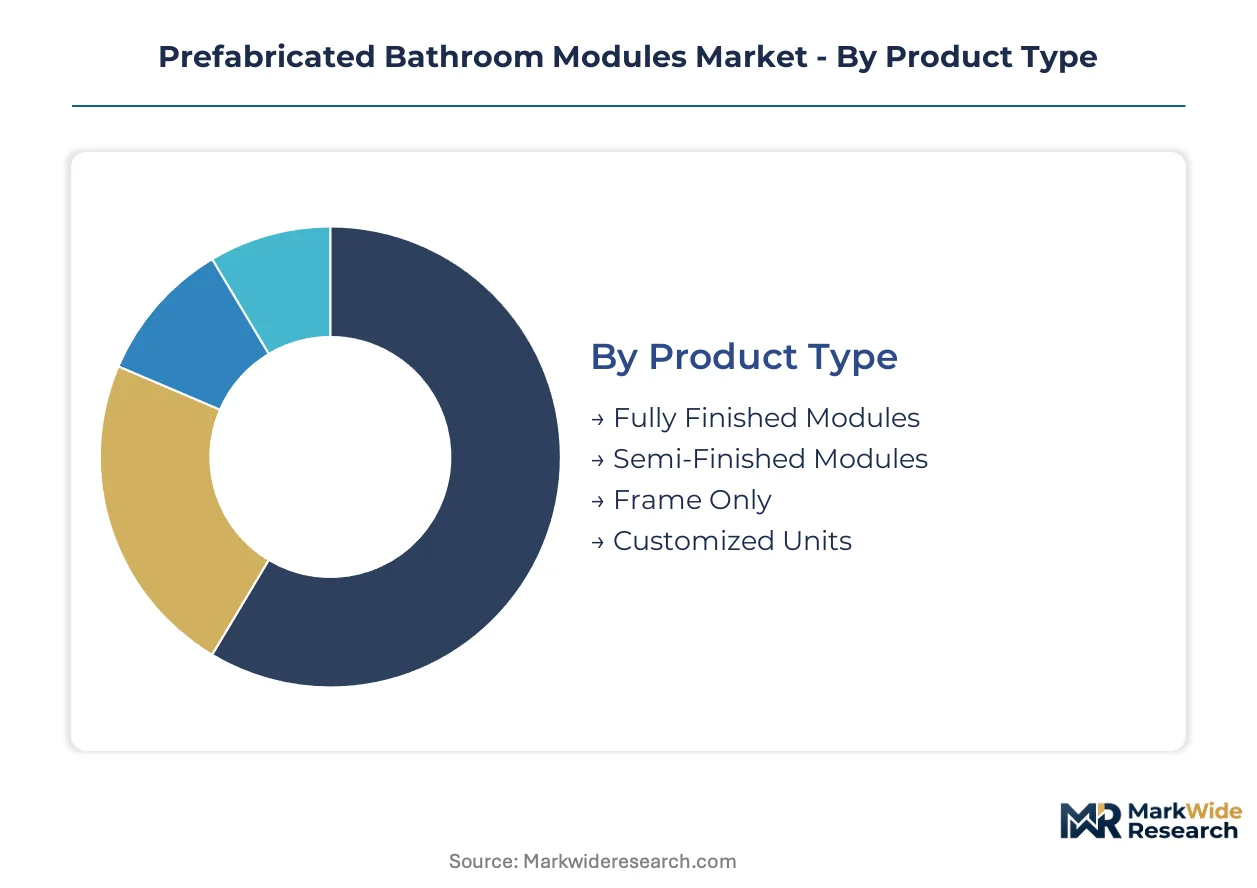
Prefabricated bathroom modules serve divergent structural and performance requirements across hospitality, healthcare, and residential verticals. Segmentation reveals how regulatory pressure on thermal efficiency, fire safety, and infection control reshapes procurement patterns by product specification and end-use environment.
Product Type:
EU Green Deal embodied carbon disclosure requirements and national building code variances on factory certification create sharp procurement divides between plug-and-install and site-finished alternatives.
- Fully Finished Modules:Complete wet-room assemblies with pre-installed fixtures, waterproofing membranes, and surface finishes delivered crane-ready for immediate connection. Hospitality chains in Dubai and Abu Dhabi specify these for guest tower projects where MOHAP infection control standards mandate sealed, factory-tested plumbing systems.
- Semi-Finished Modules:Structural shells with rough-in plumbing and electrical but unfinished surfaces allowing site-specific material selection. German KBA building codes on thermal bridging performance drive specification of these units in residential towers where developers must optimize wall assembly R-values during final fit-out.
- Frame Only:Structural chassis without waterproofing or utility rough-ins for maximum site customization flexibility.
- Customized Units:Bespoke dimensional and specification modules for heritage retrofit or specialized healthcare applications.
Established volume favors fully finished configurations; emerging adoption favors semi-finished variants where energy performance customization intersects with local code compliance.
Technology:
Weight constraints in high-rise construction and fire-rated performance mandates in dense urban corridors determine structural material selection across project types.
- Steel Frame:Lightweight galvanized steel chassis optimized for vertical transportation efficiency and rapid crane-set installation. UAE high-rise residential towers specify steel-frame modules to reduce structural load and accelerate floor-cycle times in Dubai's dense development corridors.
- Concrete Frame:Precast or cast-in-place concrete wall and floor assemblies delivering superior acoustic isolation and fire resistance. UK student housing and military barracks procurement prioritizes these units where Building Regulations Approved Document B mandates two-hour fire-rated compartmentation.
- Composite Materials:Expanding most quickly as manufacturers pursue thinner wall profiles and improved thermal bridging performance for net-zero residential specifications.
- Modular Plastics:Polymer-based panel systems for temporary or rapid-deployment healthcare facilities requiring chemical-resistant surfaces.
- Timber Frame:Cross-laminated timber chassis for low-rise residential and hospitality projects targeting biogenic carbon credentials under EU Green Deal circularity metrics.
Steel-frame technology commands current volume leadership in vertical construction; composite materials gain share fastest where thermal performance and embodied carbon reduction converge.
Application:
End-use environment dictates waterproofing certification depth, fixture durability specifications, and accessibility compliance integration at the factory stage.
- Hospitality:Guest room and back-of-house wet rooms requiring rapid installation cycles and standardized repeatability across multi-property portfolios.
- Commercial Complexes:Office tower washroom facilities with high-traffic durability specifications and ADA-compliant accessibility clearances.
- Educational Institutions:Dormitory and campus housing modules with vandal-resistant surfaces and institutional-grade fixture longevity.
- Military Facilities:Barracks and training accommodation with extreme durability requirements and rapid deployment logistics.
- High-Rise Residences:Residential tower bathrooms where structural load limits, acoustic privacy, and fire-rated performance intersect in procurement criteria.
Hospitality and high-rise residential segments concentrate procurement volume; military and educational applications present specialized specification niches with extended qualification cycles.
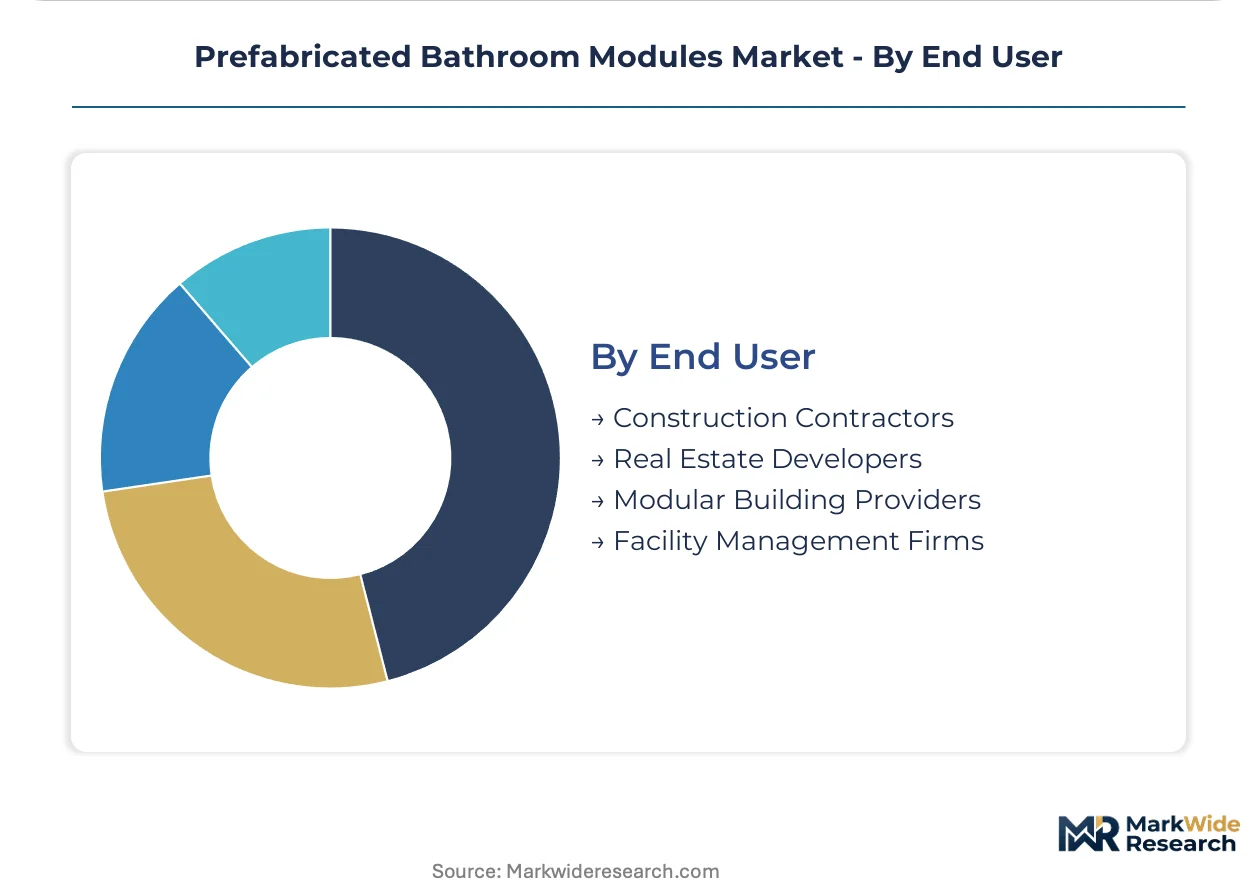
End User:
Procurement authority distribution between general contractors, developers, and facility operators determines warranty integration risk allocation and design-assist responsibility depth.
- Construction Contractors:General contractors outsourcing wet-trade labor to factory environments under lump-sum or guaranteed-maximum contracts.
- Real Estate Developers:Institutional owners specifying modules across multi-tower portfolios to compress construction schedules and reduce carrying costs.
- Modular Building Providers:Off-site construction specialists integrating bathroom modules into volumetric or panelized building systems.
- Facility Management Firms:Operators of aging hotel and healthcare stock procuring replacement modules for renovation programs minimizing operational downtime.
Construction contractors currently dominate transaction volume; facility management firms represent the steepest expansion trajectory as retrofit replacement cycles accelerate in mature building stock.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German manufacturing clusters where KBA thermal efficiency mandates justify premium module specifications, while UAE developers extract volume discounts through multi-tower procurement commitments that compress supplier margins.
United States
Florida and California hotel renovation cycles drive demand for rapid-install replacement modules that minimize guest room downtime. FDA infection control guidelines for healthcare facilities shape factory surface specifications and accessibility clearances. SurePods anchors North American supply from its Florida manufacturing base, serving hospitality chains with fully finished units.
Germany
KBA building codes on thermal bridging performance and EU Green Deal embodied carbon disclosure requirements compel developers to specify factory-certified modules. CE marking under the Construction Products Regulation mandates environmental product declarations before tender qualification. Industrial concentration in Bavaria and North Rhine-Westphalia hosts engineering-intensive suppliers optimized for residential tower integration.
United Arab Emirates
MOHAP healthcare facility mandates for sealed plumbing systems and antimicrobial surfaces accelerate hospital procurement of factory-integrated wet rooms. Dubai high-rise residential construction specifies steel-frame modules to reduce structural load and compress floor-cycle schedules. Abu Dhabi developers award multi-tower contracts to manufacturers with regional installation partnerships.
United Kingdom
Building Regulations Approved Document B fire-rated compartmentation requirements prioritize concrete-frame modules for student housing and military barracks. Walker Modular Limited specializes in these specifications, competing on verified acoustic isolation and lifecycle transparency. Procurement concentrates in London and the Southeast where dense urban corridors demand rapid vertical construction.
China
Guangzhou Seagull Housing Industry Co., Ltd. anchors Asia-Pacific supply through steel-frame production lines optimized for high-rise residential towers. National dual carbon goals and GB standards on building energy efficiency tighten factory emission accountability. Manufacturing clusters in the Pearl River Delta serve domestic demand and export markets across Southeast Asia.
Prefabricated Bathroom Modules Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where engineering-intensive specialists coexist with scale-driven fabricators. The vendor base separates into three strategic clusters: premium-tier providers with in-house design-assist capabilities, mid-market regional fabricators serving single-country demand, and commodity producers competing on volume throughput. Dominant competitive moves include capacity expansion in high-growth corridors and strategic partnerships with regional installation contractors to assume warranty integration risk.
Among European specialists, Walker Modular Limited and Bathsystem Group occupy positions within the fire-rated performance tier, while SurePods exemplifies the North American hospitality-focused archetype with factory-direct procurement models. Guangzhou Seagull Housing Industry Co., Ltd. anchors the Asia-Pacific scale-driven segment. These three represent distinct geographic and vertical specializations without overlapping core markets.
| Leading Market Players |
|---|
| Badelement |
| PDM Constructors Limited |
| Walker Modular Limited |
| Interpod Australia Pty Ltd |
| Bathsystem Group |
| SurePods |
| Guangzhou Seagull Housing Industry Co., Ltd. |
| ModularPods |
| Offsite Solutions Limited |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts with multi-tower developers in Dubai lock in steel-frame module supply visibility while insulating manufacturers from fuel price volatility in oversized flatbed logistics. These arrangements bind factory capacity to institutional buyers, compressing spot-market exposure and anchoring price predictability across project portfolios.
Pricing Analysis
The customization-premium spread between configured-to-order concrete-frame units and standard steel-frame configurations runs wide. Project-based pricing dominates procurement, with differentiation driven by fire-rated certification tier and volume scale commitments. Cost compression in semi-finished variants is intensifying because ECHA REACH compliance extends raw material qualification timelines. Facility management firms executing retrofit programs exhibit highest price sensitivity, while healthcare developers under MOHAP mandates show lowest.
Supply Chain Analysis
Inventory buffers for composite resin feedstocks stretch lead times when ECHA REACH audits disrupt qualified supplier lists. Manufacturing concentrates in Germany, the United Arab Emirates, and China, drawing from galvanized steel coil, precast concrete aggregate, and polymer resin inputs. Single-source vulnerability runs through specialized flatbed carriers serving remote construction corridors. Distribution runs through factory-direct procurement models that displace general contractor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Prefabricated bathroom modules function as a service-attach business where installation partnership networks and warranty integration services expand faster than hardware margins. Recurring revenue from multi-tower maintenance contracts and retrofit replacement cycles outpaces unit sales growth in mature corridors.
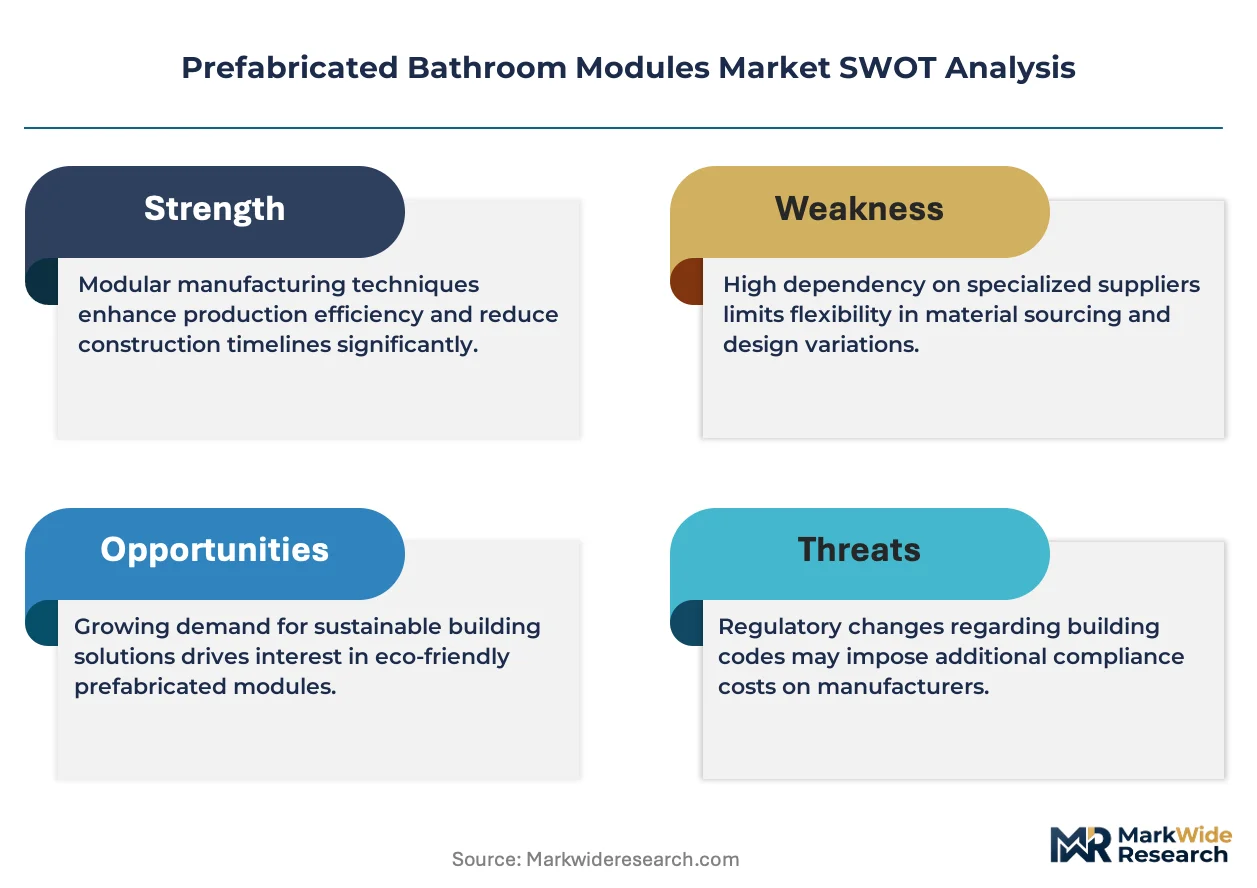
For Market Incumbents: Consolidate vendor relationships around single-source design-assist contracts that absorb structural connection liability. Capture regional installation partnerships in Dubai and Abu Dhabi to lock out emerging steel-frame competitors. Deepen backward integration into composite panel production to offset ECHA REACH cost inflation. For New Entrants and Emerging Players: Differentiate on thin-wall composite technology with integrated smart water monitoring for net-zero residential specifications. Target aging hotel stock in Florida and California where rapid-install replacement modules minimize guest room downtime. Pursue direct-to-developer channel expansion that bypasses general contractor procurement layers. For Investors and Strategic Acquirers: Engineering-intensive specialists with in-house fire-rated certification capabilities and regional installation partnerships represent the most defensible acquisition profile. Long-term viability hinges on regulatory tightening in thermal efficiency and embodied carbon disclosure across European and Middle Eastern markets. Watch for harmonization of waterproofing membrane testing protocols as inflection signal for export market consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in UAE Corridor | Captures Dubai high-rise residential demand under MOHAP procurement mandates. |
| Backward Integration into Composite Resin | Reduces ECHA REACH compliance cost exposure and qualification timeline risk. |
| Regional Installation Partnership | Assumes warranty integration liability that accelerates contract closure velocity. |
| CE Marking Pathway Investment | Unlocks German KBA thermal efficiency specification compliance for residential towers. |
| Smart Water Monitoring Integration | Positions composite modules for premium net-zero residential developer procurement. |
Research Methodology
The analysis maps fully finished, semi-finished, frame-only, and customized module configurations, each validated through general contractor procurement directors, real estate developer portfolio managers, facility management executives, and modular building provider engineering leads. Primary interview intelligence triangulates against customs trade data, national building code filings, EU EPD registry entries, and SEC construction sector disclosures. Bottom-up project pipeline enumeration cross-checks with top-down construction spend estimates.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models product type, technology material, application vertical, and end-user procurement authority dimensions. CAGRs derive from segment-level growth rate synthesis. Forecast inputs incorporate skilled wet-trade labor availability indices and steel-frame weight optimization adoption curves in vertical construction.
Forecasts assume regulatory continuity in EU Green Deal implementation, KBA thermal bridging codes, and UAE MOHAP healthcare facility mandates; material policy shifts would require re-modeling. Supply chain disruption from fuel price volatility or REACH chemical restriction expansion could revise trajectory. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
North America Particle Board Market
Building & Construction Materials
Artificial Bowling Surface Market
Building & Construction Materials
Global Screw Piles Market
Building & Construction Materials
South America Ready Mix Concrete Market
Building & Construction Materials
Plastic Door and Window Market
Building & Construction Materials
Global Sandwich Panels Market
Building & Construction Materials
Barn Door Hardware Market
Building & Construction Materials
North America Rainscreen Cladding Market
Building & Construction Materials
Exterior Sheathing Market
Building & Construction Materials
Fiber Cement Rainscreen Panels Market
Building & Construction Materials
Indonesia Ready-Mix Concrete Market
Building & Construction Materials
Ball Iron Rods Market
Building & Construction Materials
Russia Ceramic Tiles Market
Building & Construction Materials
Global Aluminum Cladding Panels Market
Building & Construction Materials
Saudi Arabia Tiles Market
Building & Construction Materials
Global Fiber Cement Board Market