
 Autoclaved Aerated Concrete (AAC) Blocks Market | 2026-2036
Autoclaved Aerated Concrete (AAC) Blocks Market Size, Share, and Industry Trends Forecast 2026-2036
Autoclaved Aerated Concrete (AAC) Blocks Market Insights
Market Context
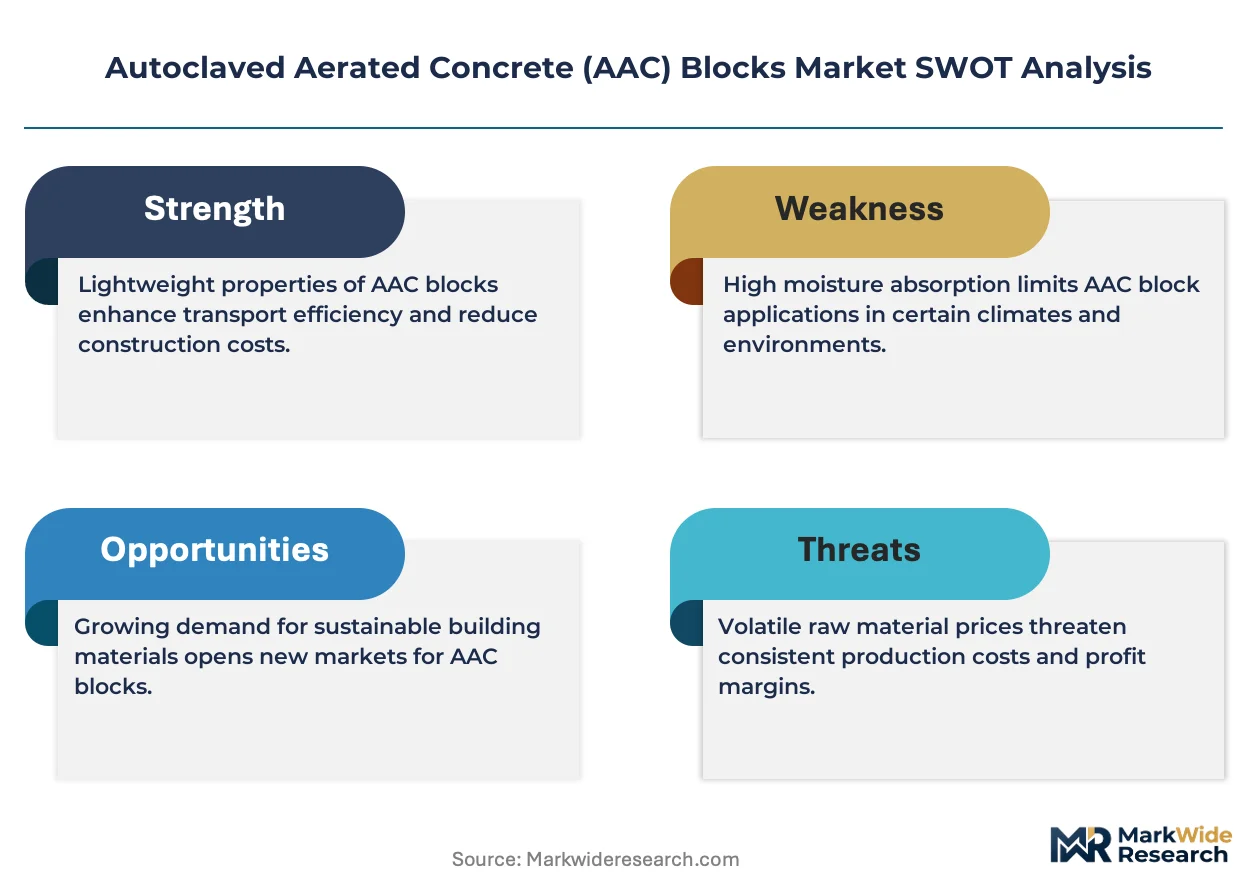
The capital-intensity divergence between autoclave-equipped integrated producers and import-reliant distributors is unwinding competitive stability across the AAC blocks sector. Xella Group leverages captive lime and cement sourcing across Central European kilns to sustain margin resilience against energy volatility. H+H International A/S anchors Nordic supply through vertically controlled curing networks that dominate Scandinavian project specifications. UltraTech Cement Ltd. competes on raw material arbitrage, extending clinker logistics into captive AAC output for Indian infrastructure corridors.
Technical Profile and Segment Structure
Autoclaved Aerated Concrete blocks are lightweight masonry units manufactured from quartz sand, lime, cement, water, and aluminum powder, then cured under pressurized steam at approximately 200 degrees Celsius to form a cellular calcium silicate hydrate structure with bulk densities between 300 and 800 kilograms per cubic meter. These blocks deliver thermal insulation, fire resistance, and seismic load reduction for structural and non-structural walling across mid-rise and high-rise construction. Wall blocks occupy the dominant volume position across residential and commercial verticals where mortar application remains the standard installation protocol. Panel blocks represent the fastest-growing product configuration as prefabricated panels gain traction among contractors seeking site labor reduction. Floor blocks command concentrated margin pools in institutional and industrial facilities where span-bearing specifications exceed standard wall-block ratings.
Regulatory Environment and Strategic Outlook
The European Union's Construction Products Regulation mandates CE marking for AAC structural elements, while India's BIS enforces IS 2185 dimensional and strength classifications that determine market access for domestic and imported supply. The EPA's National Emission Standards for Hazardous Air Pollutants from lime manufacturing indirectly shapes AAC feedstock costs and regional production economics. Stakeholders must monitor evolving green building certification thresholds and carbon-border adjustment mechanisms that will redefine competitive positioning between regional curing networks and long-distance supply lanes.
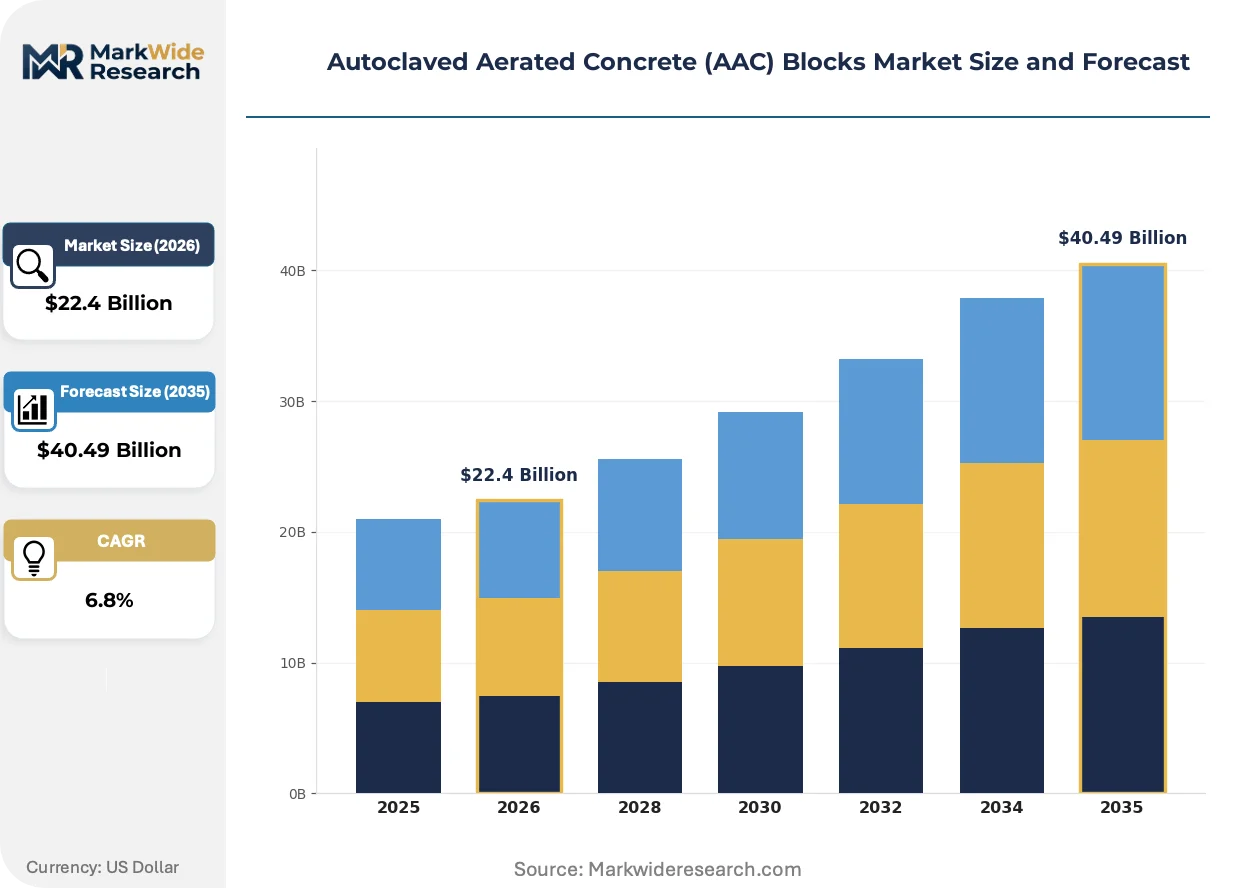
Market Dynamics
Capital-intensity divergence between autoclave-equipped integrated producers and import-reliant distributors is unwinding competitive stability across the AAC blocks sector, forcing margin compression on distributors lacking captive lime and cement sourcing.
Growth Catalysts
- IS 2185 Density Revisions:India's Bureau of Indian Standards tightened block density norms, accelerating replacement of substandard clay brick stock with certified AAC in Gujarat and Maharashtra green-rated projects.
- Prefabricated Panel Adoption:Panel blocks are displacing traditional wall-block installation among contractors seeking site labor reduction in Scandinavian mid-rise residential construction.
- Seismic Load Specifications:Floor blocks command concentrated specification in institutional facilities across Japan where span-bearing ratings exceed standard wall-block performance thresholds.
Market Restraints
- Energy Input Volatility:Pressurized steam curing at 200°C requires sustained natural gas or biomass feedstock, exposing margin structures to European energy price spikes.
- Raw Material Concentration:High-purity quartz sand deposits cluster in specific Brazilian and Chinese provinces, creating geographic supply vulnerability for distant curing networks.
- Clay Brick Substitution:Fired clay masonry retains cost advantage in rural Indian construction where thermal efficiency specifications remain unenforced.
Strategic Opportunities
- Carbon-Border Adjustment Positioning:EU Green Deal implementation creates premium positioning for low-carbon AAC against high-embodied-carbon imports from non-EU curing networks.
- Rural Indian Housing Stock:Underpenetrated thermal-efficient construction in Bihar and Uttar Pradesh offers volume expansion as state building codes extend green mandates beyond tier-one cities.
- Aluminum Powder Recycling:Converging metal recovery technologies with AAC production is opening captive feedstock sourcing for producers integrating secondary aluminum processing.
Industry Challenges
- Autoclave Operator Certification:Pressurized vessel operation requires specialized welding and pressure-system licensing that constrains workforce scalability in emerging production regions.
- CE Marking Timeline Compression:European Construction Products Regulation conformity assessment delays product launch windows for novel block densities and panel configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autoclaved Aerated Concrete (AAC) Blocks Market |
| Market Size in 2026 | $22.4 Billion |
| Market Size in 2035 | $40.49 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panel Blocks, Wall Blocks, Floor Blocks, Lintel Blocks, Partition Blocks Application: Residential Construction, Commercial Complexes, Institutional Structures, Infrastructure Projects, Industrial Facilities Installation Method: Mortar Application, Dry Stacking, Reinforced Masonry, Prefabricated Panels, Adhesive Bonding End User: Contractors, Construction Companies, Real Estate Developers, Property Managers, Renovators |
| Companies Covered | Aercon AAC, Solbet Sp. z o.o, Xella Group, Bauroc AS, UltraTech Cement Ltd., H+H International A/S, AKG Gazbeton, Magicrete Building Solutions Pvt. Ltd., ACICO Industries Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autoclaved Aerated Concrete (AAC) Blocks Market Trends and Innovations
Cellular curing automation and digital density monitoring are compressing quality variance while regulatory carbon accounting is rewiring procurement criteria across institutional buyers.
Digital twin modeling of autoclave thermal profiles is fragmenting traditional batch-process quality assurance. Nordic producers deploy real-time sensor arrays to predict compressive strength before demolding, reducing rejection rates. This capability is fragmenting competitive advantage toward data-integrated curing networks and away from legacy manual inspection protocols.
REACH chemical registration requirements for aluminum powder additives are tightening feedstock documentation obligations across European supply chains. Manufacturers must now trace powder particle distribution and reactivity certification through multi-tier suppliers. Panel block categories face the steepest compliance burden due to structural performance claims requiring extended durability testing.
Developer procurement teams are consolidating specification authority away from site contractors toward centralized technical departments. This concentration compresses vendor qualification cycles and elevates certified-sustainability documentation above unit pricing in Nordic and German residential tenders. Institutional buyers in Dutch healthcare construction now mandate Environmental Product Declaration submission as a gate to bid participation.
Autoclaved Aerated Concrete (AAC) Blocks Market Segmentation
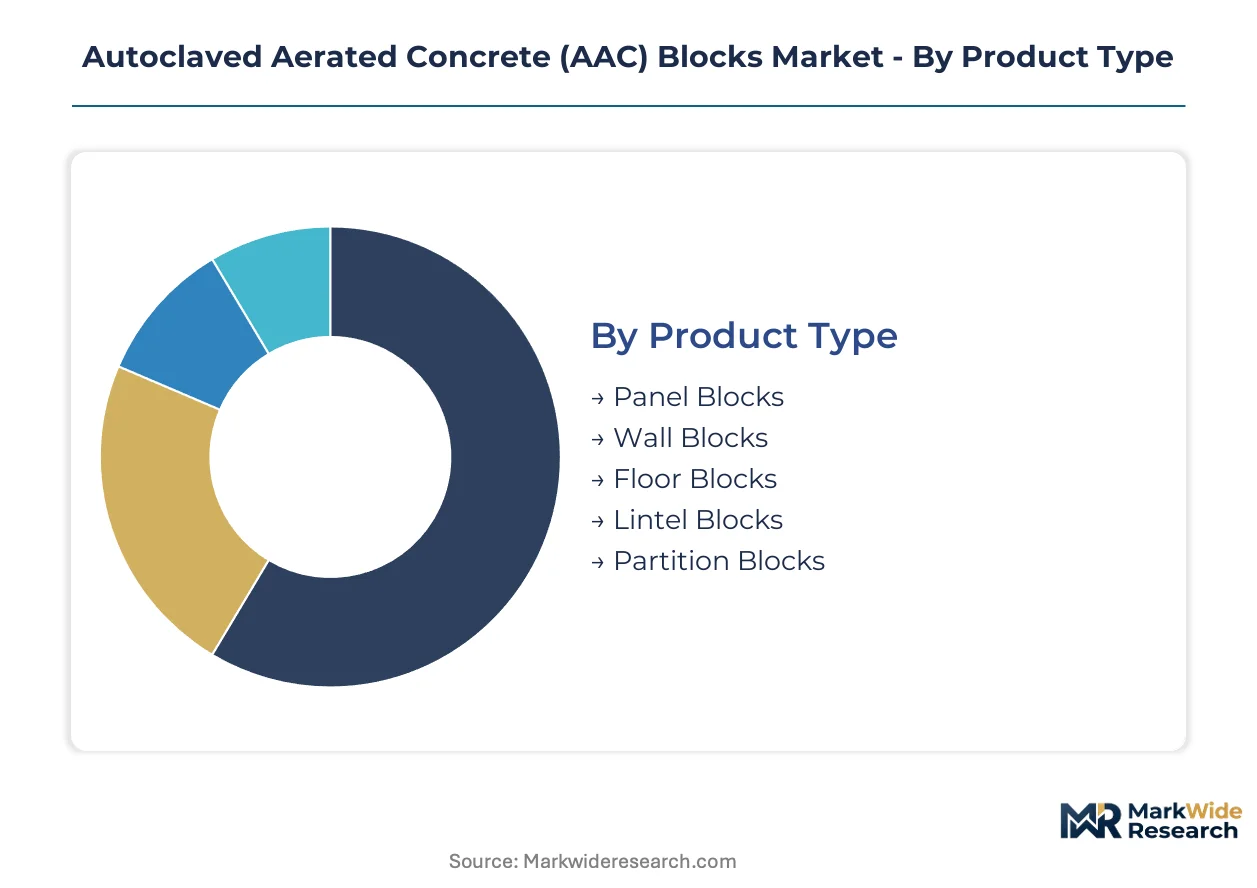
Autoclaved Aerated Concrete blocks fragment across product geometry, application intensity, and installation sophistication. Procurement patterns diverge sharply between standardized wall units for mass housing and engineered panels for premium commercial specifications. Understanding these fault lines exposes where margin pools concentrate and where volume scale accrues.
Product Type:
Domestic production clusters serve wall-block demand across India and China, while panel-block supply concentrates in Nordic and German export networks serving prefabrication specialists.
- Panel Blocks:Large-format reinforced units manufactured with embedded steel mesh for crane-handled installation. German and Swedish contractors specify these for mid-rise residential projects where site labor costs exceed material premiums by factor of three.
- Wall Blocks:Standard rectangular masonry units with hand-lay dimensions. Gujarat and Maharashtra developers procure these under revised IS 2185 density certifications for green-rated housing stock.
- Floor Blocks:High-density structural units with enhanced span-bearing capacity. Japanese institutional specifications drive concentrated demand for seismic-load-rated configurations.
- Lintel Blocks:U-shaped reinforced units for structural openings. Standardized dimensions dominate domestic European supply chains.
- Partition Blocks:Low-density non-load-bearing units for interior division. Cost-sensitive Indian commercial fit-outs represent primary volume sink.
Wall blocks hold the largest share; momentum sits with panel blocks.
Application:
Cost-tier stratification separates premium institutional specifications from economy residential volume, with infrastructure projects occupying an intermediate value band.
- Residential Construction:Multi-story housing developments across tier-one Indian cities specify AAC for thermal compliance with state energy codes. Scandinavian passive-house standards drive super-insulated panel adoption.
- Commercial Complexes:Office and retail structures in German urban centers prioritize fire-rated wall assemblies. Fast-track construction timelines favor prefabricated panel delivery.
- Institutional Structures:Healthcare and education facilities in Japan and the Netherlands mandate seismic performance and EPD documentation. Floor blocks command specification for long-span atrium construction.
- Infrastructure Projects:Transportation terminals and utility buildings across Indian infrastructure corridors source AAC through integrated cement producer channels.
- Industrial Facilities:Warehouse and manufacturing construction in Brazil leverages AAC fire resistance for insurance-rated storage zones.
Residential construction anchors volume; institutional structures generate steepest margin expansion.
Installation Method:
Volume concentrates in traditional mortar-bed techniques, while labor-cost pressure accelerates adhesive and prefabricated alternatives in high-wage geographies.
- Mortar Application:Conventional cement-based bedding remains standard across Indian and Southeast Asian construction. Skilled mason availability constrains adoption speed in rural markets.
- Dry Stacking:Precision-manufactured blocks with interlocking profiles eliminate wet trades. Brazilian and South African residential developers deploy these for speed-critical social housing programs.
- Reinforced Masonry:Steel-reinforced cores with grout infill satisfy seismic codes in Japanese and Californian high-risk zones. Specialized contractor certification limits supplier pool.
- Prefabricated Panels:Factory-integrated window and electrical rough-in reduces site labor. Swedish and German mid-rise residential contractors report 40% schedule compression.
- Adhesive Bonding:Thin-bed polymer mortars for high-precision blocks. Premium commercial specifications in the Netherlands and Denmark specify these for thermal-bridge minimization.
Mortar application dominates unit volume; prefabricated panels are expanding most quickly.
End User:
Customer-type fragmentation separates price-tendering contractors from specification-controlling developers, with procurement authority shifting toward centralized technical departments.
- Contractors:Project-based builders select AAC for labor-efficiency gains in Scandinavian and German markets. Margin pressure drives substitution toward clay brick in unenforced Indian rural zones.
- Construction Companies:Tier-one Indian infrastructure contractors source through UltraTech Cement captive channels for corridor projects. Volume commitments secure preferential allocation.
- Real Estate Developers:Mumbai and Bangalore developers specify certified AAC for green-building rating compliance. Procurement teams now mandate EPD submission as bid gate.
- Property Managers:Renovation and retrofit specifications favor partition blocks for non-structural interior reconfiguration. Dutch healthcare facility upgrades represent concentrated demand.
- Renovators:Small-scale residential retrofit in European markets sources through distributor networks. Energy-efficiency subsidy programs in Germany and France accelerate replacement of solid masonry.
Construction companies command largest procurement volume; real estate developers are gaining share fastest through centralized specification authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scandinavian producers command premium pricing through captive energy infrastructure, while Indian distributors absorb margin compression from volatile natural gas feedstock costs. This asymmetry fragments procurement authority between specification-controlled Nordic project teams and price-sensitive South Asian contractors.
Germany
Prefabricated panel specifications dominate mid-rise residential tenders in Berlin and Hamburg. The country's national construction regulator mandates CE marking under the Construction Products Regulation for all structural AAC elements. Bavarian fabricators supply crane-handled reinforced units to passive-house developments across the southern federal states.
India
Residential developers in Maharashtra and Gujarat scale AAC procurement for thermal-efficient housing stock under state green-building codes. The Bureau of Indian Standards tightened block density norms through revised IS 2185 standards. UltraTech Cement channels captive clinker logistics into AAC output for infrastructure corridors linking Mumbai to Pune.
Sweden
Contractors specify super-insulated panels for passive-house residential construction in Stockholm and Gothenburg. The country's national building code enforces stringent thermal-bridge minimization for multi-story housing. Vertically controlled curing networks dominate Scandinavian project specifications through integrated lime sourcing.
Japan
Institutional facilities in Tokyo and Osaka mandate seismic-load-rated floor blocks for long-span atrium construction. The Ministry of Economy, Trade and Industry oversees industrial standards for structural masonry performance. Kanto-region producers supply high-density configurations to healthcare and education projects facing earthquake resistance thresholds.
United Arab Emirates
Green-rated commercial towers in Dubai specify AAC for fire-rated wall assemblies under municipal sustainability mandates. The country's national standards body enforces construction product conformity for imported masonry. Fabricators in the Jebel Ali industrial zone serve Gulf Cooperation Council projects seeking insurance-rated storage zones.
Autoclaved Aerated Concrete (AAC) Blocks Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, fragmenting competitive stability across the AAC blocks sector. Autoclave-equipped integrated producers sustain margin resilience through captive lime and cement sourcing, while import-reliant distributors face compression from energy price volatility. Three archetypes dominate: vertically integrated cement conglomerates, specialized Nordic curing-network operators, and regional distributors dependent on third-party supply. Capacity expansion and backward integration into raw material feedstock represent the dominant competitive moves reshaping procurement relationships.
Among European specialists, Xella Group and H+H International A/S exemplify archetypes anchored in captive energy infrastructure and vertically controlled distribution networks. Solbet Sp. z o.o. occupies a position within the Central European tier of integrated producers leveraging proximity to lime kiln clusters. These companies represent contrasting strategic postures between scale-driven specification authority and regional density concentration.
| Leading Market Players |
|---|
| Aercon AAC |
| Solbet Sp. z o.o |
| Xella Group |
| Bauroc AS |
| UltraTech Cement Ltd. |
| H+H International A/S |
| AKG Gazbeton |
| Magicrete Building Solutions Pvt. Ltd. |
| ACICO Industries Company |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Nordic curing networks and German passive-house developers lock in supply access while insulating price visibility against European natural gas volatility. These arrangements concentrate procurement authority among autoclave-equipped integrated producers who control captive lime and cement sourcing, forcing import-reliant distributors into spot-market exposure.
Pricing Analysis
Configured-to-order panel blocks command a 40-60% premium over standard wall-block units due to embedded steel mesh and crane-handled logistics. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and thermal performance rating. Cost compression in economy-tier Indian supply is intensifying because UltraTech Cement leverages captive clinker arbitrage. Real estate developers in Mumbai and Bangalore demonstrate lowest price sensitivity, mandating EPD documentation above unit cost.
Supply Chain Analysis
Inventory lead times stretch 8-12 weeks for high-purity quartz sand sourced from designated Brazilian and Chinese provinces. Manufacturing gravity centers on Germany, Sweden, and India, with feedstock anchored in Central European lime kiln clusters. Single-source vulnerability concentrates in aluminum powder additives facing REACH documentation obligations. Distribution runs through vertically controlled curing networks in Scandinavia and cement-conglomerate channels in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AAC blocks market is entering a cyclical recovery phase as residential construction rebounds across tier-one Indian cities and Scandinavian passive-house specifications accelerate. This recovery is underpinned by regulatory tightening of thermal efficiency codes in Maharashtra and Gujarat.
For Market Incumbents: Consolidate backward integration into captive lime and cement sourcing to defend margin resilience against energy price spikes. Expand autoclave capacity in Gujarat and Maharashtra to capture IS 2185-certified demand from green-rated housing developers. Deepen certification investment for CE marking under the Construction Products Regulation to maintain specification authority in German mid-rise residential tenders.
For New Entrants and Emerging Players: Differentiate on carbon-accounting transparency to exploit EU Green Deal positioning against high-embodied-carbon imports. Target underpenetrated rural Indian housing stock in Bihar and Uttar Pradesh where state building codes are extending green mandates beyond tier-one cities. Deploy prefabricated panel configurations as the go-to-market angle for contractors seeking site labor reduction.
For Investors and Strategic Acquirers: Capital is best deployed toward autoclave-equipped integrated producers with captive energy infrastructure and vertically controlled distribution networks. Long-term viability across a 5-10 year window favors archetypes with backward integration into raw material feedstock and certification depth for institutional specifications. The signal to watch is carbon-border adjustment implementation timelines that will restructure competitive positioning between regional curing networks and long-distance supply lanes.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lime Sourcing | Captive kiln access insulates Xella Group and H+H International from European energy volatility. |
| Prefabricated Panel Capacity Expansion | German and Swedish contractors report 40% schedule compression from crane-handled reinforced units. |
| IS 2185 Certification Investment | Revised density norms determine market access for domestic and imported supply in Maharashtra. |
| Carbon Accounting Documentation | Dutch healthcare construction now mandates EPD submission as a gate to bid participation. |
| Aluminum Powder Recycling Integration | Secondary metal processing convergence opens captive feedstock sourcing for AAC producers. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant managers, procurement leads at downstream construction firms, distribution channel partners, and technical R&D directors; and secondary validation through customs and trade data, BIS certification records, SEC filings from listed cement conglomerates, and European Construction Products Regulation documentation. Bottom-up volume modeling across product geometries and installation methods was triangulated against top-down macro construction spend indicators.
Across the analysis window, the forecasting framework modeled demand trajectories by product type, application intensity, installation sophistication, and regional regulatory cluster. CAGRs were derived from segment-level growth rate synthesis anchored in construction permit flows and green-building certification adoption curves. Key inputs included state building code amendment timelines, natural gas price volatility indices, and aluminum powder reactivity certification trends.
Forecasts assume regulatory continuity in EU Construction Products Regulation enforcement and Indian BIS density standards; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Building and Construction Plastic Fasteners Market
Building & Construction Materials
Global Wall Putty Market
Building & Construction Materials
Composite Slate Roofing Market
Building & Construction Materials
Precast Concrete Members Market
Building & Construction Materials
Bed Headwall Systems Market
Building & Construction Materials
Central & South America Iron Casting Market
Building & Construction Materials
Rebars Market
Building & Construction Materials
Asia-Pacific Cross-Laminated Timber Market
Building & Construction Materials
Global Shotcrete/Sprayed Concrete Market
Building & Construction Materials
Building and Construction Sealants Market
Building & Construction Materials
Concrete Repair Product Market
Building & Construction Materials
Fiberglass Doors Market
Building & Construction Materials
Artificial Bowling Surface Market
Building & Construction Materials
APAC Commercial Glazing System Market
Building & Construction Materials
Europe Sandwich Panels Market
Building & Construction Materials
Italy Ceramic Tiles Market