
 Flooring Tools Market | 2026-2036
Flooring Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Flooring Tools Market Analysis
China is reconfiguring regional supply chains for flooring tools through expanded manufacturing zones in Zhejiang and Guangdong provinces. Q.E.P. Co. Inc. leverages extensive distribution networks across North American home improvement retail. iQ Power Tools anchors premium positioning through integrated dust containment engineering. Roberts Consolidated Industries Inc. competes on breadth across fastening and finishing tool categories.
Flooring tools encompass cutting, fastening, leveling, and finishing instruments engineered to specific tolerances for surface preparation and installation. Laser-guided leveling tools achieve accuracy within millimeters per meter, while pneumatic fastening systems operate at 70-120 PSI for consistent substrate attachment. Cutting tools command the largest product type share due to universal need across material categories. Electric technology segments are gaining share where cordless lithium-ion platforms displace pneumatic dependency on residential job sites. Specialty stores retain margin concentration through contractor loyalty programs and technical service bundling.
OSHA enforces respirable crystalline silica standards that mandate dust collection on cutting operations, directly shaping tool design requirements. EPA regulations on volatile organic compounds influence adhesive and finishing product formulations, with downstream effects on compatible application tools. ISO 28927 establishes hand-held power tool vibration emission measurement protocols that manufacturers must satisfy for European market access. Stakeholders should monitor battery platform standardization battles between cordless ecosystems, as compatibility decisions will lock in contractor purchasing patterns for multi-year replacement cycles.
Market Dynamics
OSHA silica dust enforcement is compressing contractor equipment replacement cycles toward dust-integrated cutting platforms, while cordless lithium-ion battery standardization battles lock purchasing patterns across multi-year horizons.
Growth Catalysts
- OSHA Respirable Crystalline Silica Standard:Mandated dust collection on cutting operations forces contractor equipment upgrades toward integrated containment systems, accelerating replacement demand across residential renovation segments.
- Cordless lithium-ion platforms:Battery technology advances displace pneumatic dependency on residential job sites, enabling tool mobility without compressor infrastructure.
- Sun Belt housing construction:Active residential development across Arizona, Texas, and Florida concentrates flooring installation demand and tool procurement volume.
Market Restraints
- Lithium-ion battery raw material volatility:Cobalt and nickel price swings compress margins for cordless platform manufacturers and create inventory valuation risk.
- Zhejiang and Guangdong supply concentration:Regional clustering of precision machining capacity in eastern China exposes distributors to single-point geopolitical and logistics disruption.
- Pneumatic legacy infrastructure:Established compressor systems in commercial contracting create switching cost friction against cordless adoption despite performance parity.
Strategic Opportunities
- Underpenetrated Canadian renovation market:Lagging dust-collection compliance adoption relative to US contractors creates first-mover positioning for integrated system suppliers.
- Rental channel expansion:Tool-as-a-service models for specialized cutting equipment address sporadic-use contractors without capital outlay requirements.
- ISO 28927 vibration compliance:European market access protocols create certification-based differentiation for low-emission hand-held power tool portfolios.
Industry Challenges
- Dust containment engineering talent scarcity:Cross-disciplinary expertise spanning mechanical filtration, airflow dynamics, and power tool design commands premium compensation and constrains R&D velocity.
- Multi-platform battery incompatibility:Proprietary cordless ecosystems fragment contractor fleets and complicate inventory management for multi-brand distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flooring Tools Market |
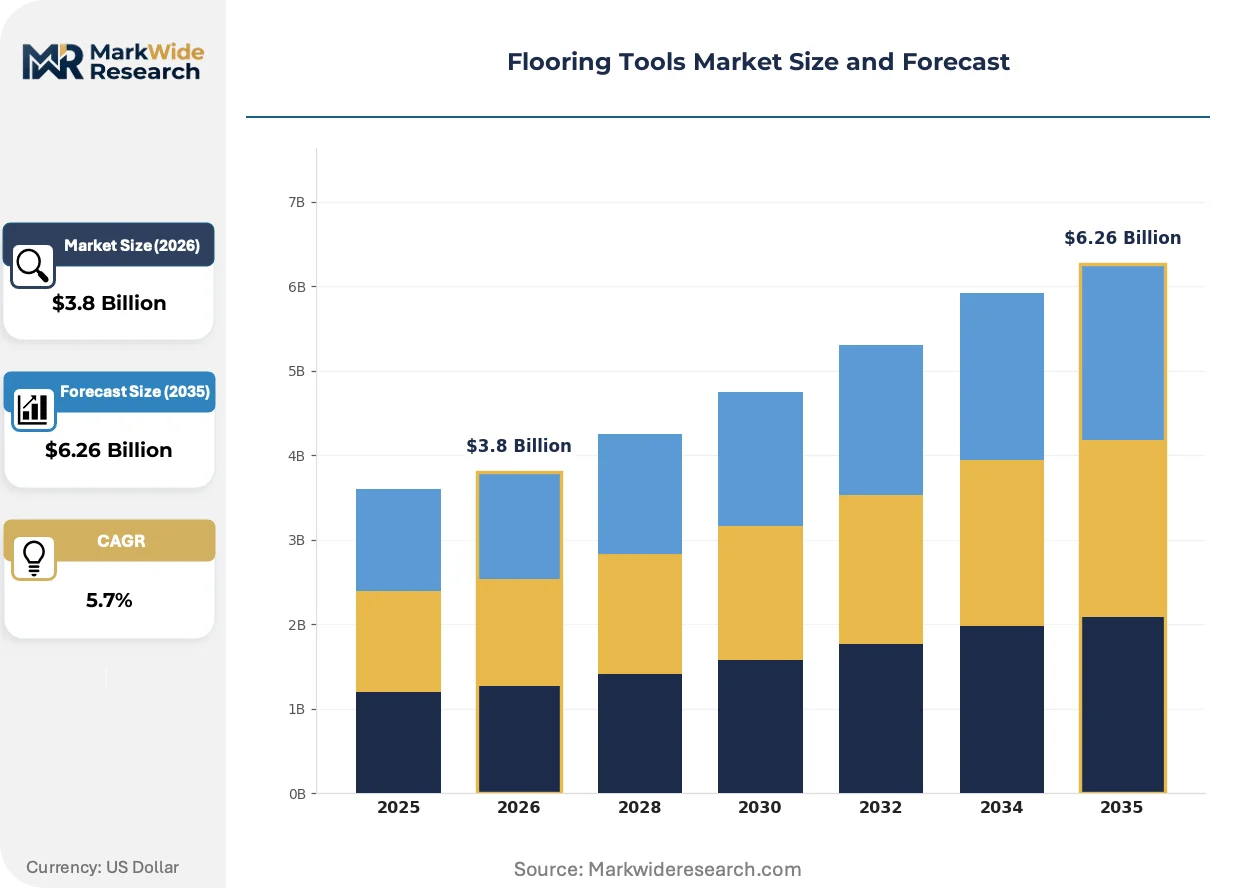
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cutting Tools, Fastening Tools, Leveling Tools, Finishing Tools Technology: Laser Technology, Pneumatic Technology, Electric Technology, Manual Technology Application: Residential, Commercial, Industrial, Renovation Distribution Channel: Online Retail, Direct Sales, Wholesale, Specialty Stores |
| Companies Covered | Q.E.P. Co. Inc., Hyde Tools Inc., Better Tools LLC, iQ Power Tools, Taylor Tools Inc., Roberts Consolidated Industries Inc., Crain Cutter Co., Orcon Products, Surface Shields Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flooring Tools Market Emerging Trajectories
Active regulatory enforcement and battery platform wars are reshaping product architecture and procurement behavior simultaneously, with compliance engineering and interoperability emerging as decisive competitive variables.
Laser-guided leveling systems is hybridizing optical measurement with digital readout interfaces, achieving sub-millimeter accuracy across extended ranges. Commercial contractors in high-specification segments are specifying these hybrid platforms for large-format tile and luxury vinyl installations. The technology is compressing demand for traditional bubble-level and manual screed methods while elevating precision tolerances that downstream fastening and finishing tools must match.
EPA volatile organic compound regulations on adhesive and finishing product formulations are forcing compatible application tool redesigns, particularly around temperature control and viscosity management in pneumatic dispensers. Flooring adhesive manufacturers are reformulating solvent content to meet emission thresholds, requiring tool suppliers to recalibrate spray patterns and cure-rate compatibility. The Southwest and Southeast US markets, where heat accelerates VOC release, show the fastest specification response.
Contractor loyalty program consolidation is concentrating procurement decisions through specialty store technical service bundling, displacing transactional hardware retail relationships. Mid-size residential renovation firms are consolidating vendor relationships to secure priority access to dust-integrated cutting inventory and field repair capabilities. This pattern is most pronounced in Texas and Florida metropolitan corridors where contractor density supports dedicated service infrastructure.
Flooring Tools Market Segmentation
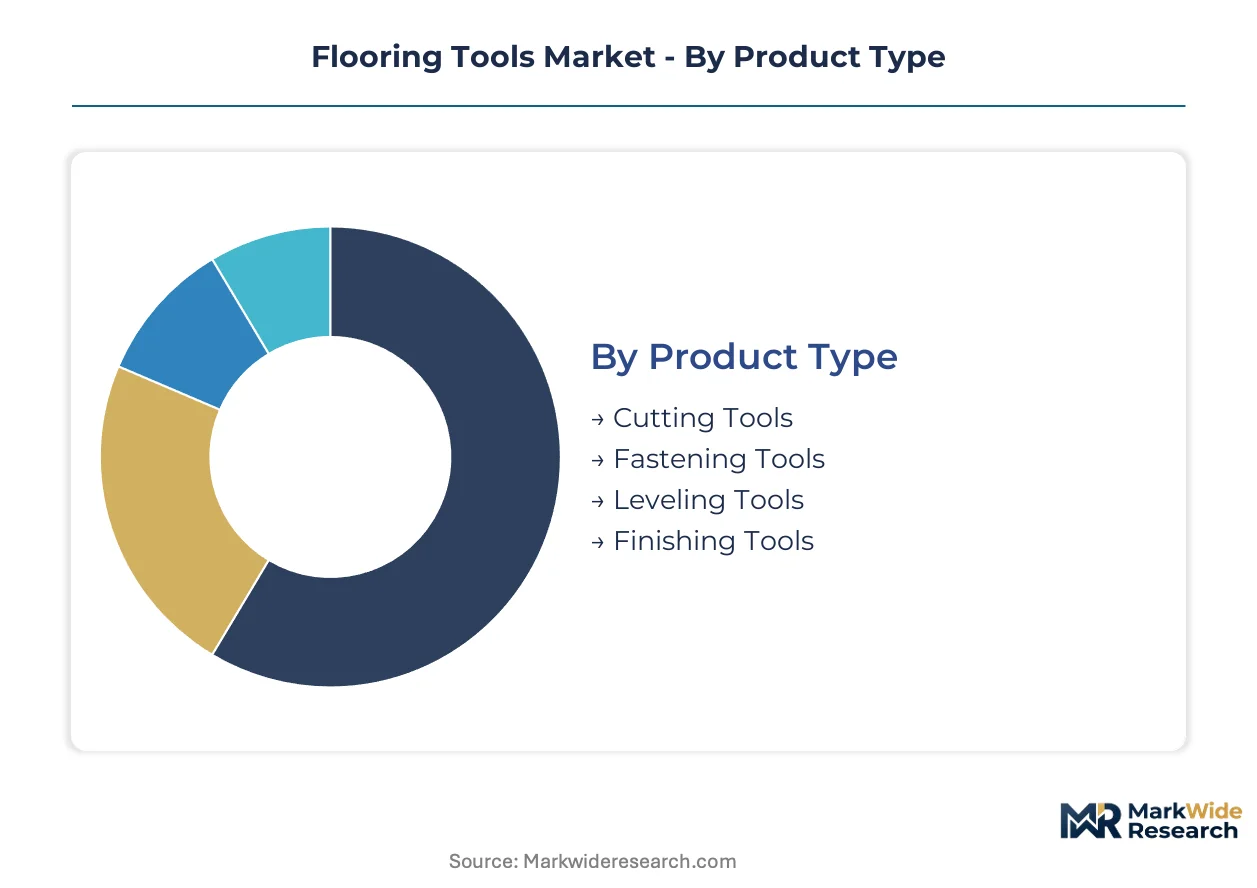
Flooring tool procurement patterns diverge sharply across job site requirements, with silica compliance mandates and battery platform standardization driving category-specific purchasing decisions. Contractors configure tool portfolios around material specialization, power infrastructure, and project scale rather than generic multi-purpose equipment.
Product Type:
Use-case spectrum spans rough preparation through precision finishing, with each phase demanding distinct engineering tolerances and dust containment integration.
- Cutting Tools:Rotary saws, tile cutters, and undercut saws engineered for respirable silica containment dominate contractor capital allocation. OSHA enforcement across Arizona, Texas, and Florida residential renovation corridors forces integrated vacuum-system purchases, compressing replacement cycles for legacy unguarded equipment.
- Fastening Tools:Pneumatic nailers and staplers operating at 70-120 PSI deliver consistent substrate attachment for hardwood and engineered flooring. Commercial contractors in high-volume Sun Belt markets specify these for speed, though cordless lithium-ion alternatives gain traction where compressor logistics prove burdensome.
- Leveling Tools:Laser-guided and bubble-level instruments achieve surface flatness within millimeter tolerances for large-format tile and luxury vinyl installation.
- Finishing Tools:Sanders, buffers, and edge trimmers execute final surface refinement with dust collection integration increasingly mandatory.
The dominant share belongs to Cutting Tools, while Fastening Tools is closing the gap fastest as cordless platforms displace pneumatic dependency.
Technology:
Cost tier stratification separates premium precision systems from commodity manual alternatives, with power infrastructure requirements determining contractor adoption thresholds.
- Electric Technology:Cordless lithium-ion platforms delivering 18V-60V performance ranges eliminate compressor tethering for residential renovation crews. Battery standardization battles between proprietary ecosystems lock contractors into multi-year replacement cycles, with interoperability emerging as a decisive procurement variable.
- Pneumatic Technology:Compressed air systems maintain cost efficiency and runtime endurance for commercial high-volume installation. Established compressor infrastructure in legacy contracting operations creates switching friction against cordless migration despite performance parity.
- Laser Technology:Optical measurement systems achieve sub-millimeter accuracy across extended ranges for precision leveling and layout.
- Manual Technology:Hand-operated cutting, fastening, and finishing instruments serve sporadic-use contractors and budget-constrained residential segments.
Electric Technology commands expanding share through mobility advantages, though Pneumatic Technology retains volume leadership in commercial flooring installation.
Application:
Volume concentration tracks housing construction intensity, with regulatory compliance timelines creating asynchronous adoption curves across end-use segments.
- Residential:Single-family and multi-family flooring installation drives the highest tool procurement volume, particularly across Sun Belt states with active housing starts. Renovation contractors expanding tool inventories for dust-integrated cutting systems concentrate demand in this segment.
- Renovation:Retrofit flooring replacement projects accelerate equipment turnover as older contractors face OSHA silica enforcement deadlines. Canadian markets lag US compliance adoption, creating geographic expansion opportunity for integrated system suppliers.
- Commercial:Office, retail, and hospitality flooring installation specifies durability-focused fastening and finishing systems for high-traffic environments.
- Industrial:Manufacturing and warehouse flooring demands heavy-duty preparation and installation equipment with extended duty cycles.
Residential claims the dominant position, while Renovation is expanding most quickly as compliance-driven replacement cycles accelerate.
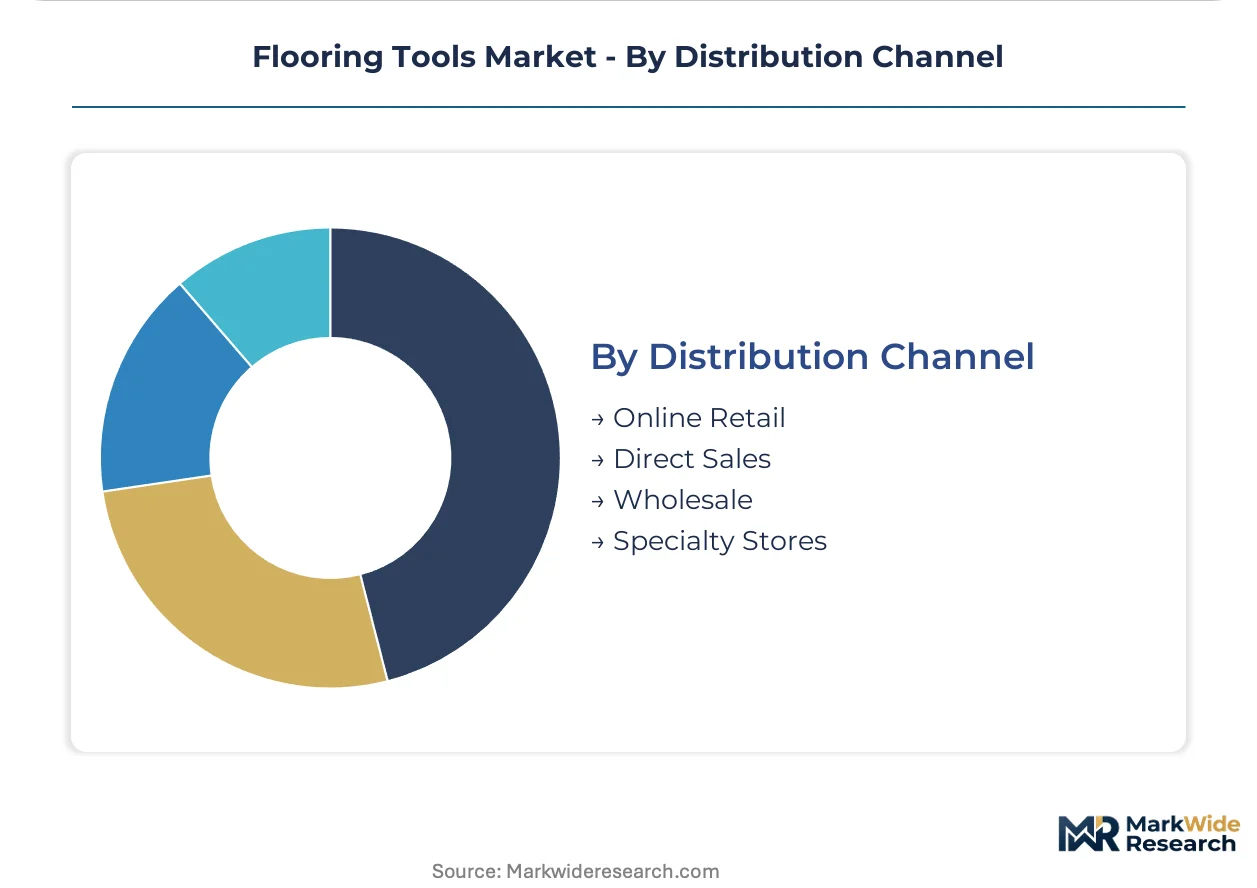
Distribution Channel:
Customer type determines channel preference, with technical service requirements and inventory immediacy driving procurement venue selection.
- Specialty Stores:Contractor loyalty programs bundling field repair capabilities and priority dust-integrated inventory access consolidate procurement decisions. Texas and Florida metropolitan corridors support dedicated service infrastructure that displaces transactional hardware retail relationships.
- Online Retail:E-commerce platforms serve price-sensitive sporadic-use contractors and remote geographies lacking specialty store presence.
- Direct Sales:Manufacturer-direct relationships secure volume pricing and custom specification for large commercial flooring contractors.
- Wholesale:Distributor networks supply multi-brand inventory for generalist contractors requiring one-stop procurement efficiency.
Specialty Stores maintain margin concentration through service bundling, while Online Retail is climbing the fastest as digital procurement habits penetrate residential renovation segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision machining capacity clusters in eastern China expose distributors to single-point disruption risk, while contractor equipment procurement concentrates in Sun Belt housing corridors across the United States. Regulatory enforcement timelines create asynchronous adoption curves for dust-integrated cutting systems.
United States
Residential renovation contractors across Arizona, Texas, and Florida are expanding tool inventories for silica-compliant cutting systems. OSHA respirable crystalline silica standards mandate dust collection on cutting operations, compressing replacement cycles for legacy equipment. Houston and Dallas metropolitan corridors support dedicated specialty store infrastructure that consolidates procurement decisions through technical service bundling.
China
Zhejiang and Guangdong provinces are reconfiguring regional supply chains through expanded manufacturing zones for flooring tool production. The country's national industrial standards regulator enforces GB standards on power tool vibration emissions that manufacturers must satisfy for domestic market access. Ningbo and Dongguan industrial clusters house precision machining capacity that feeds North American distribution networks.
Canada
Renovation contractors lag US counterparts in dust-collection compliance adoption, creating first-mover positioning for integrated system suppliers. Health Canada guidelines on occupational silica exposure influence provincial enforcement timelines, with Ontario and British Columbia leading adoption. Toronto and Vancouver metropolitan areas concentrate contractor density that supports specialty store expansion.
Germany
Commercial flooring contractors specify durability-focused fastening systems for high-traffic environments in office and retail installations. CE marking requirements and EU machinery directives shape tool design specifications for European market access. Baden-Württemberg and Bavaria industrial regions host precision engineering firms that supply vibration-compliant hand-held power tool components.
Japan
Manufacturers prioritize low-vibration hand-held power tool portfolios to satisfy ISO 28927 compliance requirements for export market access. METI industrial standards on power tool safety influence domestic design specifications. Osaka and Nagoya industrial clusters concentrate component fabrication capacity for battery platform and pneumatic system suppliers.
Flooring Tools Market Vendor Landscape
Dust-integrated engineering specialists and pneumatic legacy suppliers split the market between compliance-driven replacement demand and established compressor infrastructure. The vendor base stratifies across three tiers: premium dust-containment engineering firms, mid-market cordless platform suppliers, and commodity manual tool fabricators. Dominant competitive moves include battery ecosystem standardization battles that lock contractors into multi-year replacement cycles, and geographic expansion into underpenetrated Canadian renovation markets.
Within the premium engineering tier, iQ Power Tools and Roberts Consolidated Industries Inc. exemplify archetype positioning through specialized technical capabilities. Q.E.P. Co. Inc. occupies a position among North American distribution-focused entities that leverage retail network scale. These three companies represent distinct strategic postures: engineering-led differentiation, portfolio breadth across fastening and finishing categories, and channel dominance through home improvement retail penetration.
| Leading Market Players |
|---|
| Q.E.P. Co. Inc. |
| Hyde Tools Inc. |
| Better Tools LLC |
| iQ Power Tools |
| Taylor Tools Inc. |
| Roberts Consolidated Industries Inc. |
| Crain Cutter Co. |
| Orcon Products |
| Surface Shields Inc. |
| Others |
Supply Flow & Price Mechanics
Ningbo and Dongguan industrial clusters anchor global precision machining capacity for flooring tool components, concentrating supplier pricing power in the hands of eastern Chinese manufacturers who dictate terms to North American distributors. This geographic concentration compresses margins for cordless platform suppliers while amplifying cost volatility from lithium-ion battery raw material markets.
Pricing Analysis
OSHA Respirable Cryrystalline Silica Standard dictates the pricing tier structure across the market, separating dust-integrated cutting systems commanding premium positioning from legacy unguarded equipment facing accelerated depreciation. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Cost compression in the economy tier is intensifying because cobalt and nickel price swings transmit directly to cordless platform bill-of-materials. Residential renovation contractors show highest price sensitivity, while commercial flooring contractors prioritize runtime endurance over unit cost.
Supply Chain Analysis
Extended payment terms from Zhejiang and Guangdong manufacturers to North American distributors have become standard, with supply-chain finance facilities bridging working capital gaps for inventory-heavy specialty store channels. Precision machining capacity draws from China, Japan, and Germany, with cobalt and nickel feedstocks resting on South African and Indonesian mining output. Single-source vulnerability concentrates in eastern Chinese component fabrication exposed to geopolitical disruption. Distribution runs through specialty store networks bundling field repair capabilities with priority inventory access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue layers including field repair capabilities and priority dust-integrated inventory access are expanding faster than hardware unit sales, reframing competitive advantage around technical service bundling rather than transactional product movement.
For Market Incumbents: Pre-empt cordless lithium-ion battery standardization battles by securing exclusive ecosystem partnerships with residential renovation contractor fleets before interoperability demands fragment purchasing patterns. Defend margin position through backward integration into precision machining capacity in Baden-Württemberg or Bavaria regions, reducing exposure to Zhejiang supply concentration. Anchor certification investment in ISO 28927 vibration compliance to lock European market access against emerging low-cost competitors. For New Entrants and Emerging Players: Pursue underpenetrated Canadian renovation markets where Health Canada guidelines on occupational silica exposure lag US enforcement timelines, creating first-mover positioning for integrated dust-collection system suppliers. Target rental channel expansion for specialized cutting equipment addressing sporadic-use contractors without capital outlay requirements. Lead with tool-as-a-service go-to-market models bundling maintenance and compliance upgrade pathways. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-driven replacement cycle play because OSHA enforcement timelines and battery platform lock-in effects create predictable multi-year demand visibility. Acquisition target archetype: mid-market cordless platform suppliers with established contractor fleet relationships but underoptimized service-attach revenue. Watch battery raw material price stabilization as the inflection signal for margin expansion resumption.| Strategic Initiative | Industry Significance |
|---|---|
| Dust Containment Engineering Acquisition | Secures scarce cross-disciplinary talent spanning mechanical filtration and airflow dynamics for OSHA compliance leadership. |
| Battery Ecosystem Exclusive Partnership | Locks residential renovation contractors into multi-year replacement cycles through proprietary cordless platform standardization. |
| Canadian Market Geographic Expansion | Captures first-mover advantage in dust-collection compliance adoption lagging US enforcement timelines. |
| Rental Channel Infrastructure Buildout | Addresses sporadic-use contractor segments without capital outlay requirements through tool-as-a-service models. |
| ISO 28927 Certification Investment | Enables European market access through vibration emission compliance differentiation against low-cost competitors. |
Methodological Framework
Cross-validation between distributor procurement data and contractor fleet inventory surveys anchors the qualitative findings on replacement cycle timing and brand switching behavior. Primary interviews with flooring installation contractors, specialty store procurement managers, and aftermarket service technicians combined with secondary validation from OSHA enforcement records, EPA volatile organic compound filings, and customs trade data. Bottom-up contractor equipment spend estimates triangulate against top-down manufacturer shipment volumes.
Calibration against historical silica compliance adoption curves in adjacent construction equipment categories informed the projection framework across the analysis window. Segmentation dimensions modeled include product type, power technology, application end-use, and distribution channel, with regional regulatory enforcement timelines as a cross-cutting variable. CAGRs derived from equipment replacement cycle compression rates and housing construction permit trajectories, incorporating lithium-ion battery cost curves and precision machining capacity expansion plans as industry-specific inputs.
Sensitivities concentrate around OSHA enforcement intensity variation across state jurisdictions and cobalt-nickel price volatility transmission to cordless platform margins. Forecasts reflect documented assumptions on contractor compliance adoption timelines and battery ecosystem standardization outcomes. Macroeconomic housing construction downturn, regulatory enforcement delay, or breakthrough solid-state battery commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Global DC Torque Tool Market
Tools
GCC Machine Tools Market
Tools
Level Floats Market
Tools
Global Table Saws Market
Tools
Thread Milling Machine Market
Tools
Lathe Machines Market
Tools
Cutting Equipment Market
Tools
Bandsaw Market
Tools
Fine Blanking Tools Market
Tools
Metal Forming Tools Market
Tools
Pneumatic Marking Machines Market
Tools
Landscaping Tools Market
Tools
Screwdriver Market
Tools
Tooling Market
Tools
Yard Scraper Market
Tools
Sand Control Tools Market