
 Steel Roofing Market | 2026-2036
Steel Roofing Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Roofing Market Analysis
Standing seam roll-forming automation is rewriting fabrication economics across the steel roofing supply chain. Kingspan leverages captive coil supply and insulated panel integration to anchor its North American and European positions. MBCI competes through extensive distributor networks and project-specific engineering support for commercial and industrial builds. ATAS International differentiates via architectural-grade finishes and custom color matching for institutional facades.
Steel roofing consists of formed metal panels fabricated from coated or alloyed steel sheet, typically ranging from 22 to 29 gauge, designed to shed precipitation and withstand structural loads over building envelopes. Galvalume substrates dominate specification for coastal and high-humidity environments due to superior corrosion resistance against galvanized alternatives. Standing seam products command premium positioning in commercial new construction where weathertight longevity and thermal movement accommodation justify higher installed cost. Retrofit installation represents a growing service dimension as building owners seek to overlay existing substrates without full tear-off, reducing landfill burden and accelerating project schedules.
US building codes enforced by the International Code Council and state-level amendments shape wind uplift and fire resistance ratings that filter product eligibility. EPA Energy Star and Cool Roof Rating Council standards steer specification toward solar reflectance-index-compliant coatings, particularly across sun-belt jurisdictions. ECHA REACH restrictions on hexavalent chromium in pretreatment chemistry are forcing European mills to reformulate passivation layers. Stakeholders must monitor evolving embodied-carbon disclosure rules under the EU Green Deal and emerging US state-level buy-clean procurement laws that will recalibrate competitive advantage toward low-carbon steel sourcing.
Market Dynamics
Standing seam roll-forming automation is compressing fabrication costs and redistributing margin capture from distributors toward coil-integrated manufacturers with captive supply chains.
Growth Catalysts
- Commercial standing seam specification:Building owners in sun-belt US jurisdictions prioritize weathertight longevity and thermal movement accommodation for energy-efficient envelopes.
- China's GB green building standards:Tightening performance requirements for coated steel substrates are accelerating substrate upgrades across institutional construction.
- Retrofit overlay demand:Building owners seek to overlay existing substrates without full tear-off, reducing landfill burden and accelerating project schedules.
Market Restraints
- Zinc and aluminum input volatility:Galvalume substrate pricing fluctuates with base metal commodity markets, compressing fabricator margins during spike periods.
- Coil supply concentration:North American and European mills control premium coated steel substrate availability, creating bottleneck risk for independent roll-formers.
- ECHA REACH hexavalent chromium restrictions:European pretreatment chemistry reformulation is extending qualification timelines for new coating systems.
Strategic Opportunities
- India institutional construction:Gujarat and Maharashtra state infrastructure programs are driving specification of high-strength galvalume roofing for schools and hospitals.
- Cool Roof Rating Council compliance:Solar reflectance-index-compliant coatings command premium positioning across EPA Energy Star jurisdictions.
- Insulated panel integration:Building envelope manufacturers are converging roofing with thermal insulation to capture full-system specification.
Industry Challenges
- Skilled roll-forming technician scarcity:Automated standing seam equipment requires programming and maintenance expertise that outpaces vocational training output.
- Embodied-carbon disclosure compliance:EU Green Deal and emerging US state-level buy-clean procurement laws demand supply-chain traceability that legacy ERP systems cannot deliver.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Roofing Market |
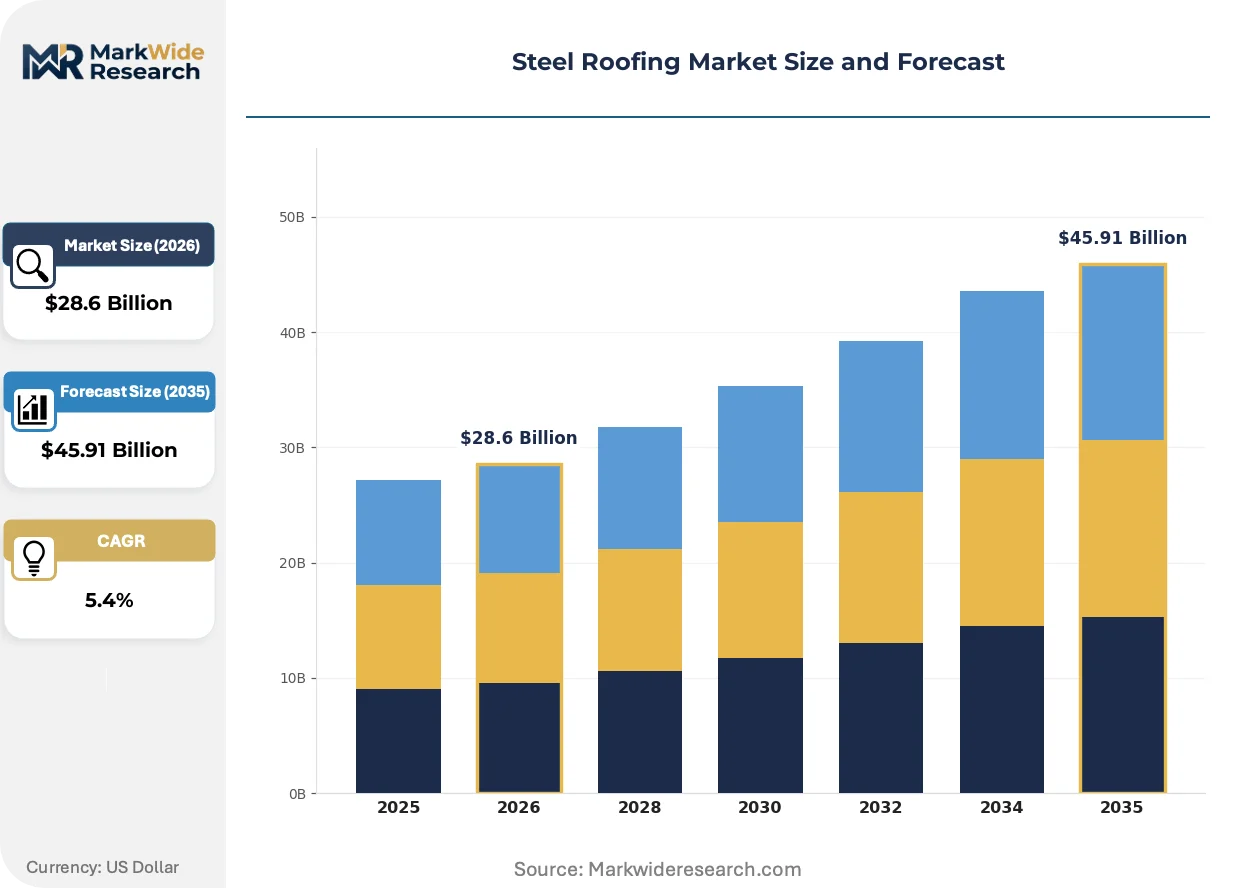
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $45.91 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standing Seam, Corrugated Panels, shingles, Tiles End User: Residential, Commercial, Industrial, Institutional Material Grade: Galvalume, Galvanized, Coated, High-Strength Installation Type: New Construction, Retrofit, Replacement, DIY |
| Companies Covered | MBCI (Metal Building Components, Inc.), Kingspan, Elevate (Formerly Firestone Building Products), Petersen Aluminum Corporation, ATAS International, Inc., McElroy Metal, Englert, Inc., Berridge Manufacturing Co., Metal Sales, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Roofing Market Emerging Trajectories
Automation, regulatory chemistry reform, and procurement model evolution are restructuring how steel roofing is fabricated, specified, and purchased across commercial and institutional construction.
Seam-sealing robotic workstations are eliminating manual crimping operations in standing seam fabrication. Commercial contractors with large-scale new construction portfolios are adopting these systems fastest. Labor-dependent fabrication economics is rendering obsolete for mid-volume producers competing on installed-cost precision.
ECHA REACH restrictions on hexavalent chromium in pretreatment chemistry are forcing European mills to reformulate passivation layers. Qualification timelines for alternative chemistries have extended by several production cycles. Coil coaters serving architectural-grade finishes are absorbing the highest compliance costs and passing through price adjustments.
Building owners are consolidating envelope procurement under single-source contractors who coordinate roofing, insulation, and cladding. Distributors relying on product-only relationships are losing specification influence to systems integrators. This consolidation is most visible in US commercial new construction where general contractors prioritize schedule certainty over component sourcing flexibility.
Steel Roofing Market Segmentation
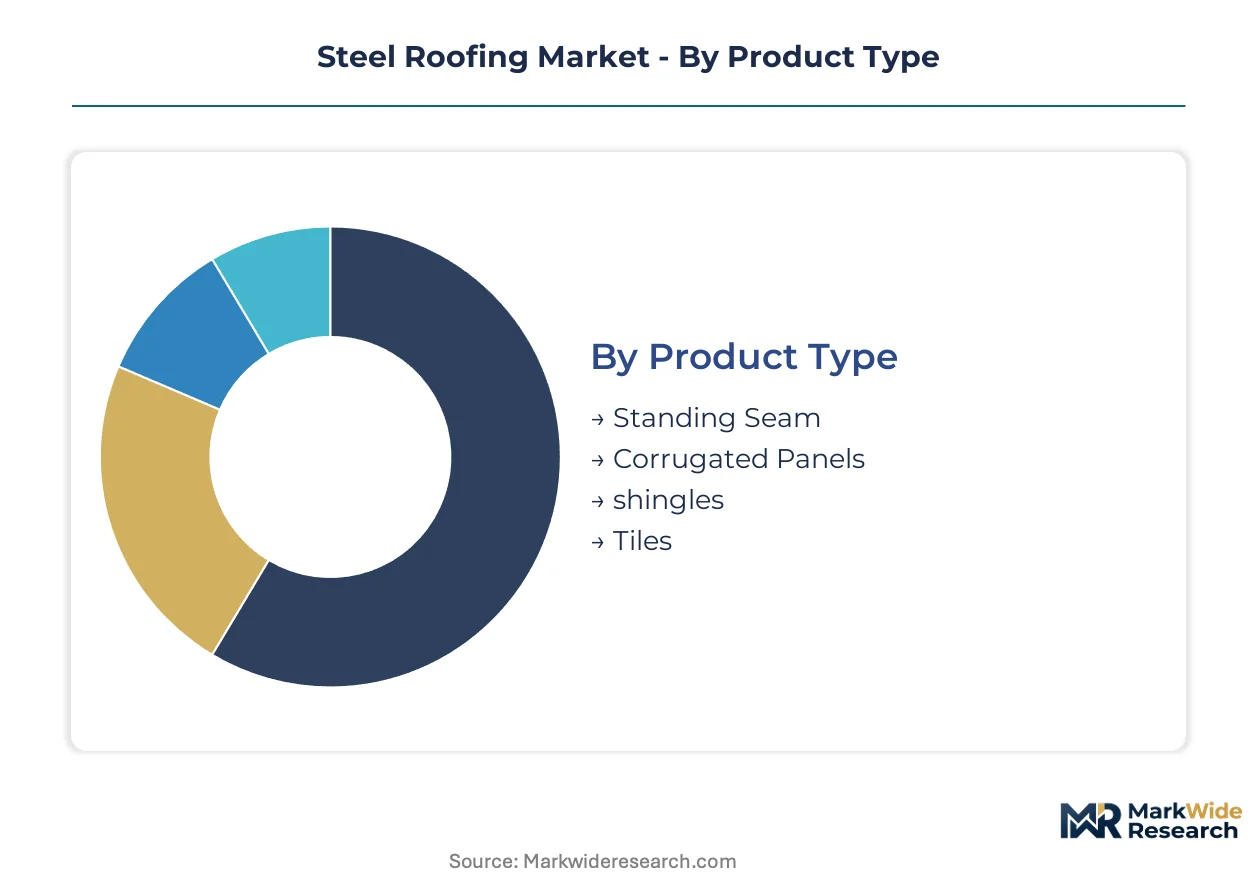
Steel roofing segmentation reveals divergent margin structures and specification cycles across product architectures and installation contexts. Product type and material grade classifications determine fabrication complexity and corrosion performance, while end-user and installation type dimensions govern project scale and service intensity.
Product Type:
Standing seam systems turn over slowest due to premium specification cycles and extended building envelope lifecycles, while corrugated panels cycle faster through agricultural and utility building replacement waves.
- Standing Seam:Concealed fastener systems with raised longitudinal seams accommodate thermal expansion across large commercial roof planes. Demand concentrates in sun-belt US jurisdictions where thermal movement accommodation and weathertight longevity justify premium installed cost for energy-efficient envelopes.
- Corrugated Panels:Exposed fastener profiles with sinusoidal or trapezoidal ribs prioritize material economy and rapid installation. Agricultural outbuilding and warehouse construction across India's Gujarat and Maharashtra states drives specification of standard-duty profiles for cost-sensitive institutional infrastructure.
- Shingles:Modular stamped panels replicate dimensional asphalt or slate aesthetics for residential retrofit applications.
- Tiles:Interlocking profiles with deep water channels serve Mediterranean and Spanish colonial architectural specifications in coastal US markets.
Corrugated panels dominate installed base across agricultural and light industrial building stock. Standing seam is where expansion concentrates as commercial new construction prioritizes thermal performance and weathertight longevity.
End User:
Commercial and institutional segments concentrate specification authority with architects and envelope consultants, while residential and industrial procurement flows through contractor networks with shorter decision cycles.
- Commercial:Office, retail, and hospitality buildings specify architectural-grade finishes with CRRC-compliant solar reflectance indices. China's GB green building standards tighten performance requirements for coated steel substrates across institutional construction in tier-one cities.
- Institutional:Schools, hospitals, and government facilities prioritize lifecycle cost analysis and embodied-carbon disclosure compliance under EU Green Deal procurement rules.
- Residential:Single-family and multifamily housing selects shingle and tile profiles for aesthetic compatibility with neighborhood covenants.
- Industrial:Manufacturing plants and distribution centers specify high-strength galvalume for wide-span structural loads with minimal slope.
Industrial applications dominate installed base through repetitive warehouse and manufacturing construction. Institutional is where expansion concentrates as green building codes tighten substrate performance requirements.
Material Grade:
Galvalume commands coastal premium positioning while galvanized retains economy-segment share; coating chemistry differentiation separates architectural from utilitarian applications.
- Galvalume:Aluminum-zinc alloy coating delivers superior corrosion resistance in marine and high-humidity environments. Coastal US jurisdictions and India's monsoon-exposed western states specify galvalume for schools and hospitals in Gujarat and Maharashtra infrastructure programs.
- High-Strength:Advanced high-strength steel substrates enable reduced gauge with maintained structural performance for wide-span industrial roofs.
- Galvanized:Zinc coating provides baseline corrosion protection for dry-climate agricultural and interior applications.
- Coated:Factory-applied PVDF, SMP, or polyester finishes deliver color retention and chalk resistance for architectural visibility.
Galvanized dominates installed base across legacy agricultural and interior building stock. Galvalume is where expansion concentrates as coastal construction and green building standards elevate corrosion performance requirements.
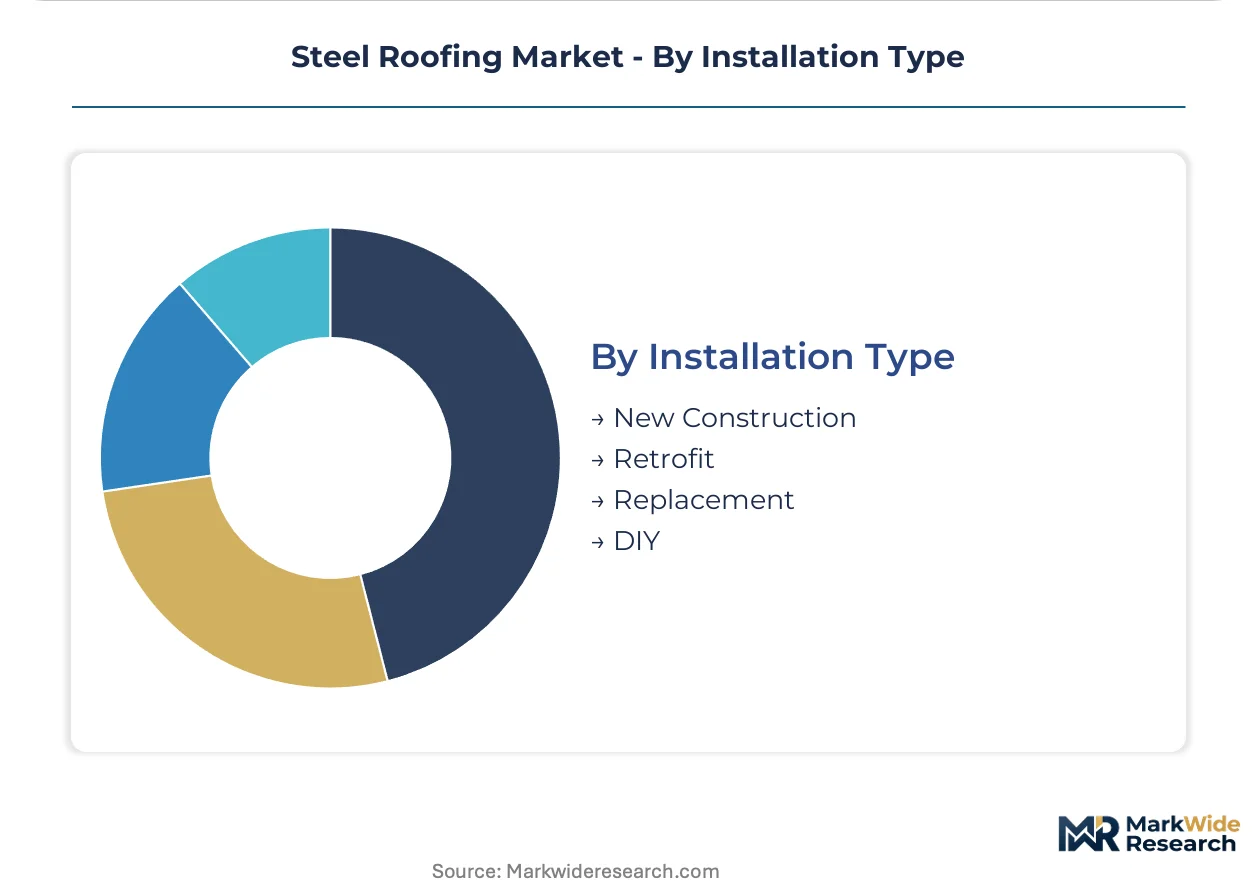
Installation Type:
New construction concentrates volume in standing seam and insulated panel systems, while retrofit overlay accelerates project schedules and reduces landfill burden for building envelope renewal.
- New Construction:Full-system specification integrates roofing with thermal insulation and air barriers under single-source contractor procurement. US commercial new construction prioritizes schedule certainty through systems integrators over component sourcing flexibility.
- Retrofit:Overlay installation atop existing substrates eliminates full tear-off, accelerating project timelines and reducing landfill burden for building envelope renewal.
- Replacement:Full tear-off and re-roofing addresses substrate degradation beyond overlay feasibility.
- DIY:Contractor-supplied corrugated panels for agricultural outbuildings and accessory structures bypass professional installation.
New construction dominates installed base through commercial and institutional building expansion. Retrofit is where expansion concentrates as building owners seek envelope renewal without full tear-off disruption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese coated steel substrate exports flow predominantly to institutional construction sites across India and Southeast Asia, where green building codes accelerate specification upgrades. Domestic absorption in China centers on tier-one city commercial envelopes governed by tightening GB standards.
United States
Commercial building owners in Florida, Texas, and Arizona specify standing seam systems for thermal movement accommodation across large roof planes. EPA Energy Star and Cool Roof Rating Council standards filter product eligibility through solar reflectance-index requirements. Dallas-Fort Worth and Houston metropolitan construction corridors concentrate demand for weathertight longevity in sun-belt jurisdictions.
China
GB standards for green building materials tighten performance requirements for coated steel substrates in Beijing, Shanghai, and Shenzhen institutional projects. Ministry of Ecology and Environment enforcement accelerates substrate upgrades for schools and hospitals. Yangtze River Delta manufacturing clusters supply premium coil to domestic and export markets.
India
Gujarat and Maharashtra state infrastructure programs drive specification of high-strength galvalume roofing for schools and hospitals. Bureau of Indian Standards certification requirements elevate corrosion performance benchmarks for monsoon-exposed western states. Ahmedabad and Mumbai construction corridors concentrate institutional procurement authority.
Germany
EU Green Deal embodied-carbon disclosure rules recalibrate procurement toward low-carbon steel sourcing for commercial envelopes. ECHA REACH restrictions on hexavalent chromium force pretreatment chemistry reformulation across Ruhr Valley coil coating operations. Bavaria and North Rhine-Westphalia industrial clusters absorb highest compliance costs.
Japan
METI energy efficiency standards steer commercial specification toward thermally optimized standing seam systems in Tokyo and Osaka metropolitan construction. JIS certification requirements govern substrate performance for high-humidity coastal applications. Kansai region manufacturing maintains captive coil supply integration.
Steel Roofing Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fabrication, distribution, and specification influence. Coil-integrated manufacturers capture margin through captive substrate supply and insulated panel integration. Independent roll-formers depend on distributor relationships and project-specific engineering support. Strategic moves concentrate on backward integration into coil coating and geographic expansion through distributor network density.
Within the coil-integrated tier, Kingspan and MBCI occupy positions anchored by captive supply chains and systems integration capabilities. ATAS International exemplifies the architectural-grade specialist archetype through custom finish capabilities. These three fabricators represent divergent competitive vectors: scale-driven envelope integration, distributor-network commercial penetration, and specification-driven premium positioning.
| Leading Market Players |
|---|
| MBCI (Metal Building Components, Inc.) |
| Kingspan |
| Elevate (Formerly Firestone Building Products) |
| Petersen Aluminum Corporation |
| ATAS International, Inc. |
| McElroy Metal |
| Englert, Inc. |
| Berridge Manufacturing Co. |
| Metal Sales |
| Others |
Supply Flow & Price Mechanics
North American and European coil coating mills control premium coated steel substrate availability, anchoring margin capture downstream toward manufacturers with captive supply chains and insulated panel integration capabilities. Independent roll-formers without upstream control face persistent margin compression when zinc and aluminum commodity spikes transmit through contract structures.
Pricing Analysis
Current-generation standing seam systems with automated roll-forming and robotic seam-sealing command substantial premiums over prior-generation manually crimped profiles, while next-generation coil-integrated insulated panel systems are resetting price floors through full-envelope bundling. Three-tier pricing structure across architectural-grade, commercial-standard, and agricultural-economy levels reflects certification tier and finish durability differentiation. Pricing pressure stems from zinc and aluminum input volatility transmitting through galvalume substrate contracts. Agricultural and light industrial buyers exhibit highest price sensitivity, while institutional purchasers with lifecycle cost mandates accept premium positioning for weathertight longevity.
Supply Chain Analysis
Hot-dip coated steel coil feedstock concentrates in the United States, Germany, and China, with Yangtze River Delta and Ruhr Valley clusters supplying architectural-grade substrates to domestic and export markets. Galvalume production draws from aluminum and zinc ingot streams, with coating chemistry formulations resting on chrome-free pretreatment alternatives under ECHA REACH compliance. Single-source vulnerability concentrates in premium coil availability for independent roll-formers without mill-direct relationships. Distribution runs through manufacturer-direct specification for large commercial projects and regional distributor networks for agricultural and residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Steel roofing constitutes a high-growth building envelope disruption as standing seam automation and cool roof regulatory mandates recalibrate competitive advantage toward coil-integrated systems manufacturers.
For Market Incumbents: Pre-empt margin erosion from commodity volatility by securing captive coil supply through backward integration or long-term offtake agreements with North American and European mills. Anchor specification influence through insulated panel integration that captures full-envelope procurement consolidation from general contractors prioritizing schedule certainty over component sourcing flexibility.
For New Entrants and Emerging Players: Build out regional distributor density in India's Gujarat and Maharashtra institutional construction corridors where Bureau of Indian Standards certification requirements create qualification barriers for established exporters. Target high-strength galvalume specification for schools and hospitals through engineering-led project support that differentiates from product-only relationships.
For Investors and Strategic Acquirers: Capital is best deployed toward coil-integrated mid-cap specialists with standing seam automation and architectural-grade finish capabilities that capture premium positioning as green building codes tighten substrate performance requirements. Monitor EPA Energy Star and Cool Roof Rating Council standard evolution as signal for specification shift timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coil Coating | Captive substrate supply insulates margin from zinc and aluminum commodity volatility. |
| Insulated Panel Systems Integration | Full-envelope bundling captures specification authority from component distributors. |
| Robotic Seam-Sealing Deployment | Automation eliminates manual crimping labor and compresses fabrication cost structures. |
| Cool Roof Certification Investment | CRRC and EPA Energy Star compliance unlocks premium positioning in sun-belt jurisdictions. |
| Geographic Expansion through Distributor Acquisition | Channel density in India's western states captures institutional construction procurement flows. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with coil coating specialists, standing seam fabricators, commercial roofing contractors, and institutional procurement officers; and secondary validation through customs trade records, SEC filings from publicly traded building products manufacturers, American Iron and Steel Institute production data, and Cool Roof Rating Council certification databases. Bottom-up volume estimates from regional construction permit analysis were triangulated against top-down market sizing from coated steel substrate consumption trends.
Forecast inputs span product type segmentation across standing seam, corrugated, shingle, and tile architectures; material grade differentiation between galvalume, galvanized, and high-strength substrates; and installation context across new construction, retrofit overlay, and replacement scenarios. CAGRs were derived from regression analysis against construction spending indices, green building code adoption curves, and coil coating capacity expansion announcements. Zinc and aluminum price elasticity and skilled technician availability constraints were incorporated as scenario variables.
Stress conditions across base metal commodity spikes, ECHA REACH chemistry reformulation delays, and buy-clean procurement law implementation timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of construction permit issuance in Dallas-Fort Worth, Houston, Ahmedabad, and Mumbai corridors is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Gulf Corporation Council Cement Market
Building & Construction Materials
Porcelain Tiles Market
Building & Construction Materials
Composite Slate Roofing Market
Building & Construction Materials
US Exterior Wall Systems Market
Building & Construction Materials
Architectural Acoustic Panels Market
Building & Construction Materials
Aluminum Board Raised Access Floor Market
Building & Construction Materials
North America Mineral Wool Ceiling Tiles Market
Building & Construction Materials
Moisture Resistant Gypsum Board Market
Building & Construction Materials
External Wall Insulation Board Market
Building & Construction Materials
Roof Coating Market
Building & Construction Materials
Reclaimed Lumber Market
Building & Construction Materials
Warm Mix Asphalt Market
Building & Construction Materials
Autoclaved Aerated Concrete (AAC) Blocks Market
Building & Construction Materials
Precast Concrete Pile Market
Building & Construction Materials
Germany Construction Chemicals Market
Building & Construction Materials
Clean Room Panels Market