
 Concrete Densifier Market | 2026-2036
Concrete Densifier Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete Densifier Market Outlook
The gap between premium lithium silicate formulations and commodity sodium silicate products is repositioning how manufacturers allocate R&D budgets. BASF SE leverages its chemical synthesis expertise to dominate high-performance lithium silicate supply. Sika AG anchors its position through integrated distribution networks across industrial flooring channels. Prosoco specializes in specification-grade systems that command premium positioning with architects and engineers.
A concrete densifier is a chemical hardener, typically based on silicate compounds, that penetrates cementitious surfaces to react with calcium hydroxide and form calcium silicate hydrate, increasing surface hardness from roughly 4-6 Mohs to 7-8 Mohs while reducing dusting and porosity. Its primary purpose is to extend service life of concrete floors in high-traffic industrial and commercial environments. Lithium silicate products lead in premium specification work due to their smaller molecular size and deeper penetration profile, while sodium silicate maintains volume dominance in cost-sensitive infrastructure applications. The industrial flooring segment concentrates margin pools where facility operators prioritize lifecycle cost over initial material outlay.
EPA emissions standards and OSHA crystalline silica exposure limits directly shape product formulation requirements and jobsite application protocols for densifier manufacturers. The EU REACH framework and associated VOC restrictions limit cross-border sale of solvent-containing variants, pushing reformulation toward water-based silicate chemistry. Stakeholders must monitor evolving state-level green building codes and procurement specifications that increasingly mandate low-emitting floor treatments in public construction.
Market Dynamics
Formulation chemistry divides sharply between lithium silicate premium tiers and sodium silicate commodity volumes, with R&D investment flowing disproportionately toward molecular-size optimization for deeper substrate penetration.
Growth Catalysts
- OSHA crystalline silica exposure limits:Tighter jobsite safety mandates accelerate specification of low-dust application methods in US industrial flooring contracts.
- Distribution center construction:E-commerce fulfillment infrastructure drives polished concrete specifications across warehousing and logistics facilities.
- Lithium silicate molecular engineering:Smaller particle size enables deeper penetration profiles that extend surface hardness ratings in high-traffic commercial environments.
Market Restraints
- Alkali metal feedstock volatility:Lithium carbonate and sodium silicate raw material costs fluctuate with battery-sector demand competition and energy-intensive production economics.
- Water-based formulation constraints:EU REACH VOC restrictions eliminate solvent-containing variants from cross-border trade, compressing margin structures for reformulation.
- Surface preparation dependency:Densifier performance hinges on precise substrate profiling, creating specification risk where contractor skill levels vary regionally.
Strategic Opportunities
- Retrofit renovation cycles:Aging commercial and institutional floor stock in the United States creates specification upgrade potential as lifecycle cost analysis displaces first-cost procurement.
- Green building procurement mandates:State-level low-emitting material requirements in public construction channels favor water-based silicate chemistry with environmental product declarations.
- IoT-enabled floor monitoring:Embedded sensor convergence with densified surfaces enables predictive maintenance contracts for facility operators managing large industrial footprints.
Industry Challenges
- Applicator certification gaps:Proper densifier performance requires trained concrete polishing contractors, and qualified labor pools remain thin in secondary markets.
- Specification fragmentation:Architect and engineer education on silicate chemistry differentiation lags behind product innovation, slowing premium-tier adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete Densifier Market |
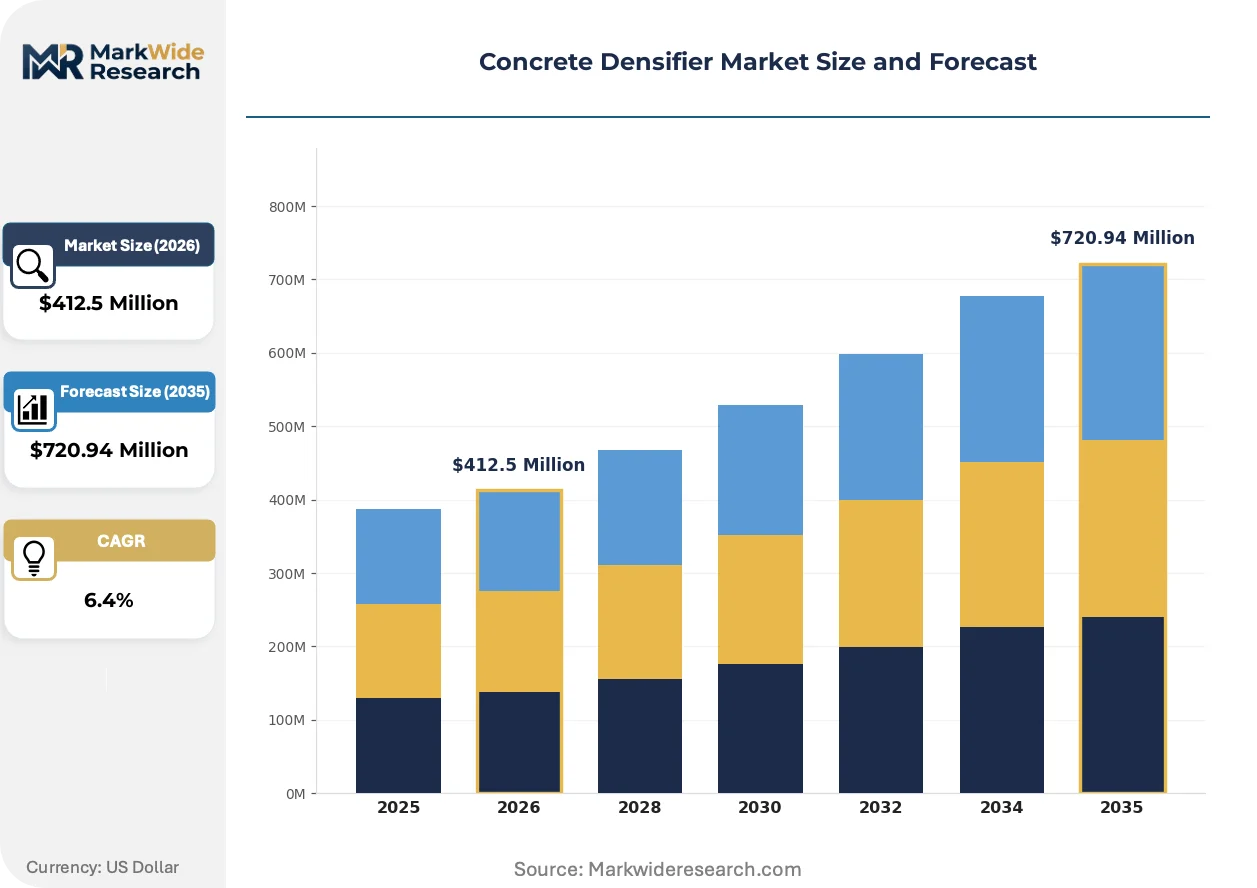
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium Silicate, Sodium Silicate, Potassium Silicate, Chloride-Based Application: Industrial Flooring, Residential Flooring, Decorative Treatments, Infrastructure End User: Construction Companies, Homeowners, Architects, Engineers Distribution Channel: Direct Sales, Retail Outlets, Online Sales, Distributors |
| Companies Covered | BASF SE, Sika AG, W. R. Meadows, The Euclid Chemical Company, Mapei S.p.A., LATICRETE International, RPM International, Evonik, Prosoco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete Densifier Market Strategic Shifts
Application technology and regulatory chemistry are converging to reshape how densifier systems penetrate, cure, and validate performance in commercial flooring environments.
Automated surface profiling equipment is automating substrate preparation consistency that previously varied with manual grinder operation. Large-format retail and logistics developers specify machine-guided floor flatness tolerances that densifier performance depends upon. This automation compresses contractor qualification thresholds while raising baseline specification compliance.
EPA emissions standards for architectural coatings continue tightening allowable VOC content in surface treatment products. Water-based lithium silicate formulations gain specification share as solvent-borne alternatives face formulation bans in multiple state jurisdictions. Industrial flooring contractors in California and the Northeast adapt procurement toward compliant chemistry ahead of federal rule harmonization.
Facility operators now bundle densifier application with extended warranty and performance guarantee contracts rather than purchasing materials separately. Integrated flooring system providers displace independent product distributors in large commercial projects. This pattern concentrates most visibly in distribution center construction where single-source accountability reduces project risk for developer-owners.
Concrete Densifier Market Segmentation
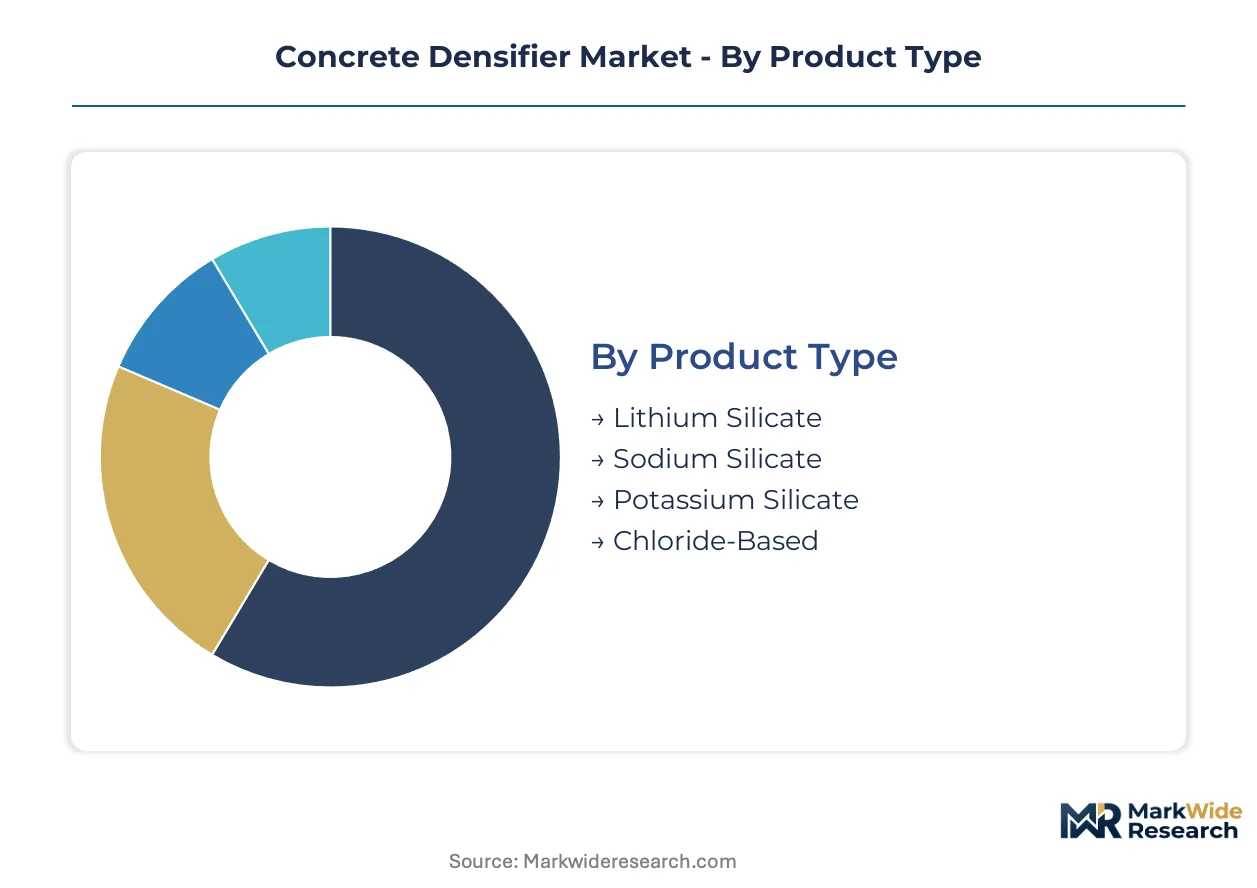
Concrete densifier segmentation reveals how formulation chemistry, application environment, and procurement channel each impose distinct compliance burdens and margin structures. Specification-grade lithium silicate products carry architect-engineer certification requirements that commodity sodium silicate formulations bypass entirely.
Product Type:
Lithium silicate formulations require EPA VOC compliance documentation and LEED v4.1 low-emitting materials certification for specification in public construction channels. Sodium silicate and potassium silicate products face lighter documentation loads, while chloride-based variants trigger corrosion-risk disclosures under OSHA workplace safety protocols.
- Lithium Silicate:Smaller molecular structure enables penetration depths exceeding 5mm in polished concrete substrates. Demand concentrates in distribution center flooring across the United States, where LEED certification mandates and lifecycle cost analysis displace first-cost procurement in e-commerce fulfillment infrastructure.
- Sodium Silicate:Alkaline silicate compound with larger molecular size limits penetration to surface-hardening applications. Volume dominance persists in cost-sensitive municipal infrastructure across the American Midwest and Southeast, where budget-constrained public works departments prioritize material economy over performance specifications.
- Potassium Silicate:Intermediate reactivity profile bridges penetration depth and material cost considerations.
- Chloride-Based:Accelerated hardening chemistry carries corrosion-risk warnings that restrict specification in reinforced concrete environments.
Sodium silicate sits at the top of the volume ranking, with lithium silicate climbing the fastest.
Application:
Industrial flooring specifications demand the most rigorous surface preparation protocols and contractor certification, while residential and decorative applications tolerate wider performance variance. Infrastructure projects impose public procurement compliance that fragments demand across federal, state, and municipal purchasing systems.
- Industrial Flooring:High-traffic warehouse and manufacturing environments require Mohs hardness ratings of 7-8 and dust-reduction performance guarantees. Demand concentrates in logistics facilities across California, Texas, and Pennsylvania, where OSHA crystalline silica exposure limits accelerate specification of low-dust polishing systems.
- Residential Flooring:Polished concrete basements and garage applications prioritize aesthetic finish over abrasion resistance. Growth is expanding most quickly in suburban renovation markets across Florida and Arizona, where cooling-load reduction from thermal mass flooring complements residential energy efficiency priorities.
- Decorative Treatments:Stained and dyed concrete surfaces in retail and hospitality environments.
- Infrastructure:Bridge decks, parking structures, and transportation facilities subject to freeze-thaw cycling and de-icing chemical exposure.
Industrial flooring commands the highest specification density, with decorative treatments gaining share fastest among non-industrial segments.
End User:
Architects and engineers carry professional liability exposure that drives specification toward EPD-documented, third-party-certified products. Homeowners and construction companies operate with lighter documentation requirements but face divergent incentive structures around initial cost versus lifecycle value.
- Construction Companies:General and specialty contractors purchasing materials for project execution. Procurement concentrates in national flooring contractors serving distribution center developers across the American Sun Belt, where single-source accountability contracts bundle densifier application with extended performance warranties.
- Homeowners:Direct purchasers in residential renovation and new construction segments. Demand clusters in metropolitan areas with active resale markets and design-conscious buyer demographics.
- Architects:Specification authority in commercial and institutional projects with LEED or WELL certification targets.
- Engineers:Structural and materials engineers evaluating substrate compatibility and load-bearing performance.
Construction companies sit at the top of the volume ranking, with architects climbing the fastest as green building mandates expand specification authority.
Distribution Channel:
Direct sales relationships carry the heaviest technical support obligations and specification influence, while online and retail channels serve replacement and small-project demand with minimal documentation. Distributor networks fragment margin capture across regional industrial supply chains.
- Direct Sales:Manufacturer-to-contractor relationships with embedded application training and warranty support. Volume concentrates in large-format retail and logistics developers operating across multiple states, where integrated flooring system providers displace independent product distributors through single-source accountability structures.
- Distributors:Regional industrial supply houses stocking multiple brands for contractor pickup. Channel relevance persists in secondary markets where qualified polishing contractors remain scarce and technical support requirements are lower.
- Retail Outlets:Big-box and specialty construction material stores serving homeowner and small-contractor segments.
- Online Sales:E-commerce platforms capturing specification-grade and commodity product demand with limited technical consultation.
Direct sales sits at the top of the volume ranking, with online sales climbing the fastest as contractor procurement patterns digitize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled concrete polishing contractors concentrate in the United States, Germany, and China, anchoring regional densifier demand through specification-grade installation capacity. Distribution center construction and industrial flooring renovation cycles drive geographic variation in product chemistry preferences.
United States
E-commerce fulfillment infrastructure and data center construction propel densifier specification across Texas, California, and Pennsylvania. OSHA crystalline silica exposure limits tighten jobsite application protocols in industrial flooring contracts. The Dallas-Fort Worth metroplex anchors contractor training concentration, where large-format logistics developers bundle densifier application with extended performance warranties.
Germany
Automotive manufacturing facilities and chemical processing plants demand high-performance lithium silicate systems for abrasion-resistant flooring. EU REACH VOC restrictions eliminate solvent-containing variants from cross-border trade, pushing reformulation toward water-based chemistry. The Rhine-Ruhr industrial corridor concentrates specification-grade installation capacity serving BASF SE and Bayer AG facility networks.
China
Battery manufacturing plants and semiconductor fabrication facilities drive premium densifier adoption for cleanroom-compatible flooring. The country's national environmental regulator enforces GB standards on indoor air quality in industrial construction. The Yangtze River Delta manufacturing belt anchors lithium silicate demand, where BYD and CATL facility expansions specify polished concrete systems.
India
Pharmaceutical manufacturing and food processing facilities specify densified concrete for FDA-compliant flooring surfaces. BIS certification requirements for construction chemicals create documentation barriers for imported formulations. The Gujarat pharmaceutical cluster around Ahmedabad anchors specification-grade demand, where Sun Pharma and Cadila Healthcare facility upgrades prioritize lifecycle cost analysis.
United Arab Emirates
Airport terminals and luxury retail developments specify polished concrete for thermal mass and aesthetic durability in extreme climate conditions. MOHAP indoor air quality guidelines influence material selection in healthcare construction. Dubai's logistics free zones concentrate industrial flooring demand, where DP World facility expansions drive lithium silicate specification for high-traffic cargo handling surfaces.
Concrete Densifier Market Competitive Environment
Top-tier vendors anchor specification-grade lithium silicate supply, while regional distributors and commodity sodium silicate producers occupy volume-driven tiers. The vendor base stratifies between chemistry specialists with molecular engineering capabilities and construction chemical conglomerates with integrated distribution networks. Two strategic archetypes dominate: silicate synthesis specialists leveraging feedstock control, and flooring system integrators bundling application services with material supply. Competitive moves concentrate on backward integration into alkali metal feedstocks and geographic expansion through distributor acquisition.
Within the silicate synthesis specialist tier, BASF SE and Evonik exemplify molecular engineering capabilities that enable premium penetration profiles. Sika AG and Mapei S.p.A. occupy positions as construction chemical conglomerates with integrated flooring channels. Among US-based specification-grade providers, Prosoco represents the architect-engineer certification archetype, while W. R. Meadows and The Euclid Chemical Company exemplify regional distributor-anchored models. LATICRETE International and RPM International sit within the construction chemical portfolio diversification pattern, leveraging cross-product bundling in commercial flooring contracts.
| Leading Market Players |
|---|
| BASF SE |
| Sika AG |
| W. R. Meadows |
| The Euclid Chemical Company |
| Mapei S.p.A. |
| LATICRETE International |
| RPM International |
| Evonik |
| Prosoco |
| Others |
Value Chain & Pricing Dynamics
Large-format logistics developers operating across multiple states anchor pricing power through bundled single-source accountability contracts that disperse independent material distributors. This procurement concentration forces manufacturers to absorb application training and extended warranty costs into headline pricing.
Pricing Analysis
Bundled service contracts dominate project-based procurement while unbundled material-only sales persist in small-contractor and retail channels. Three-tier pricing structure across specification-grade lithium silicate, standard sodium silicate, and economy chloride-based formulations reflects certification documentation burdens and penetration performance. Pricing pressure stems from lithium carbonate feedstock competition with battery-sector demand. Construction companies exhibit highest price sensitivity due to first-cost procurement mandates, while architects and engineers prioritize lifecycle value over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from major distribution center developers mandate multi-manufacturer qualification to mitigate single-source vulnerability in alkali metal feedstock supply. Manufacturing concentrates in the United States, Germany, and China where silicate synthesis expertise clusters. Raw material dependencies center on lithium carbonate, sodium silicate, and potassium hydroxide. Supply chain risk rests on energy-intensive production economics and battery-sector demand competition. Distribution runs through direct manufacturer-to-contractor relationships in premium tiers and regional industrial supply houses in secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The concrete densifier market represents a late-cycle quality story as facility operators shift procurement criteria from first-cost outlay toward lifecycle cost analysis and LEED certification compliance.
For Market Incumbents: Deploy backward integration into lithium carbonate supply to secure feedstock access against battery-sector competition. BASF SE and Sika AG should deepen molecular engineering R&D to extend penetration depth advantages. Channel control through certified contractor networks defends margin position against commodity sodium silicate imports from cost-sensitive producers. For New Entrants and Emerging Players: Launch via regional distributor partnerships serving secondary markets where qualified polishing contractors remain scarce. White-space targets include residential renovation segments in Florida and Arizona, and pharmaceutical manufacturing facilities in India requiring FDA-compliant flooring surfaces. Specification-grade lithium silicate for cleanroom environments offers the most penetrable premium tier. For Investors and Strategic Acquirers: Construction chemical conglomerates represent the most active acquirer category in this space, seeking silicate synthesis specialists to fill molecular engineering capability gaps. Long-term viability favors vendors with integrated flooring system bundling and EPD-documented product lines. Watch lithium carbonate price volatility as the inflection signal for margin compression risk in premium-tier supply.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Feedstocks | Captive lithium carbonate supply insulates margin structure from battery-sector demand competition. |
| Contractor Certification Program Expansion | OSHA-compliant training networks lock in specification-grade channel control for lithium silicate products. |
| Water-Based Formulation Transition | EPA VOC compliance and EU REACH alignment enable cross-border trade in regulated jurisdictions. |
| IoT-Enabled Performance Monitoring | Embedded sensor integration creates recurring revenue streams through predictive maintenance contracts. |
| Green Building Certification Investment | LEED v4.1 and WELL documentation captures public construction procurement mandates. |
Study Parameters
Direct dialogue with concrete polishing contractors, industrial flooring procurement managers, construction chemical R&D directors, and architect specification writers grounded qualitative insights. Secondary validation drew from EPA emissions filings, OSHA crystalline silica exposure databases, EU REACH substance registrations, and trade data from the American Chemistry Council. Bottom-up demand modeling triangulated against top-down market sizing across formulation chemistry, application environment, and procurement channel dimensions.
Segment-level value and volume trajectories emerged from penetration rate modeling across industrial flooring, residential renovation, and infrastructure end-uses. The analytical framework incorporated silicate chemistry grade tiers, LEED certification requirements, and regional contractor density as core segmentation variables. CAGRs derived from historical demand elasticity analysis applied to projected distribution center construction and commercial renovation cycles. Key inputs included lithium carbonate price indices, e-commerce fulfillment square footage expansion, and state-level green building code adoption timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained lithium feedstock price volatility or accelerated federal VOC harmonization. Projections reflect assumptions around OSHA enforcement continuity, EU REACH substance restriction timelines, and contractor certification program expansion rates. Deviation in battery-sector lithium demand would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Wood Truss Market
Building & Construction Materials
Poland Ceramic Tiles Market
Building & Construction Materials
US and Canada Corner Beads and Caps Market
Building & Construction Materials
Concrete Repair Product Market
Building & Construction Materials
Engineered Wood Market
Building & Construction Materials
Timber Construction Connectors Market
Building & Construction Materials
Foldable Container House Market
Building & Construction Materials
Facade Anchor Systems Market
Building & Construction Materials
Residential Non-metal Electrical Conduit Market
Building & Construction Materials
Asia-Pacific Particle Board Market
Building & Construction Materials
Asia-Pacific Ready-Mix Concrete Market
Building & Construction Materials
Global Steel Sections Market
Building & Construction Materials
Waterstop Market
Building & Construction Materials
China Concrete Superplasticizer Market
Building & Construction Materials
Construction Aggregates Market
Building & Construction Materials
North America Laminated Veneer Lumber Market