
 South America Industrial Flooring Market | 2026-2036
South America Industrial Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
South America Industrial Flooring Market Analytics
Epoxy resin is decoupling from traditional solvent-based formulations as waterborne and high-solids alternatives reshape product economics in South America. Sika AG leverages its Brazilian manufacturing footprint to anchor supply for regional infrastructure projects. RPM International Inc. competes through specialized coating systems designed for chemical resistance in industrial environments. BASF SE sustains R&D intensity in polyurethane formulations tailored to tropical humidity conditions.
Industrial flooring encompasses polymer-based and cementitious surface systems engineered to withstand mechanical abrasion, chemical exposure, and thermal cycling, typically specified with compressive strengths exceeding 50 MPa and slip resistance ratings per local safety codes. These installations protect concrete substrates while enabling hygienic operations in manufacturing and warehousing environments. Epoxy formulations dominate installed value across heavy-duty applications where chemical resistance and load-bearing capacity prove critical. Polyurethane segments capture growing share in food processing facilities requiring thermal shock resistance and seamless hygiene profiles. Cementitious systems retain position in renovation projects where rapid return-to-service and compatibility with existing substrates reduce downtime costs.
CONMETRO, Brazil's national metrology and industrial quality regulator, enforces flooring performance standards that manufacturers must satisfy for market access, while Argentina's IRAM certification requirements shape product specifications for cross-border suppliers. REACH-aligned chemical restrictions from European trade frameworks indirectly influence imported resin formulations and additive packages. Stakeholders must monitor evolving Mercosur technical regulations and local content requirements that could restructure sourcing strategies and competitive positioning across the region.
Market Dynamics
Brazil's CONMETRO certification tightening is forcing material specification upgrades across the value chain, compressing timelines for solvent-based formulation phase-outs while elevating waterborne and high-solids alternatives.
Growth Catalysts
- Food Processing Hygiene Mandates:Brazil's sanitary surveillance agency ANVISA enforces stricter surface hygiene protocols in meat and dairy facilities, driving seamless polyurethane system specifications.
- CONMETRO Performance Standards:Load-bearing and slip-resistance benchmarks for industrial safety flooring are accelerating certified product adoption in São Paulo's manufacturing corridor.
- Logistics Zone Expansion:Warehouse construction near Buenos Aires and Rosario is concentrating demand for abrasion-resistant epoxy systems in Argentina's freight distribution network.
Market Restraints
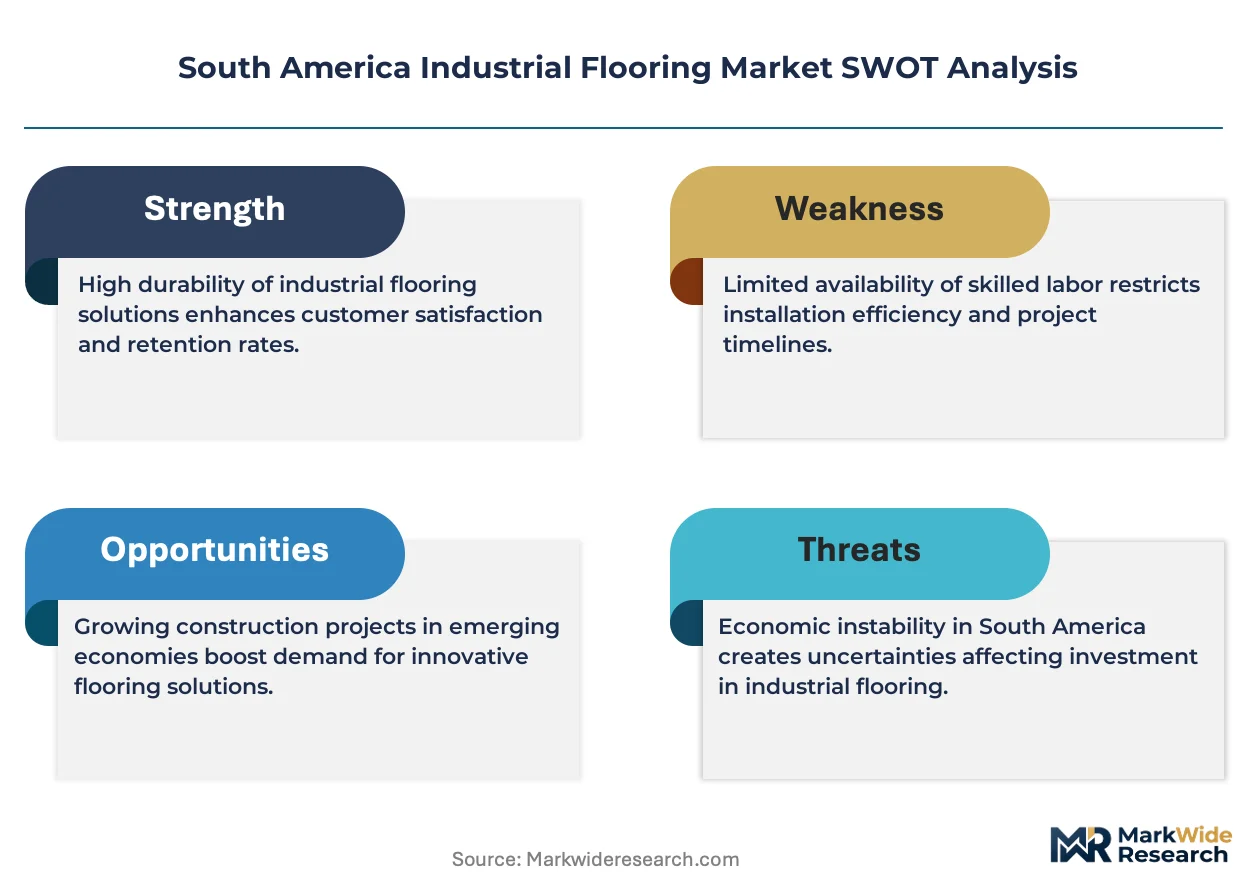
- Petrochemical Input Volatility:Epoxy resin pricing tracks naphtha and propylene feedstock fluctuations from Brazilian and Argentine refineries, compressing margin visibility for applicators.
- Import Dependency Concentration:Specialty isocyanates and curatives concentrate in Asian supplier bases, exposing South American formulators to currency and shipping cost instability.
- Substrate Compatibility Limitations:High-moisture concrete conditions in tropical climates restrict rapid-cure cementitious system performance, extending project timelines.
Strategic Opportunities
- Colombian Infrastructure Gap:Bogotá's underdeveloped industrial flooring specification culture offers first-mover positioning for certified system providers entering Andean markets.
- Cold Chain Facility Buildout:Thermal shock-resistant polyurethane formulations capture emerging demand from Chilean seafood processing and pharmaceutical logistics investments.
- Mercosur Technical Alignment:Harmonized cross-border certification frameworks are reducing duplicate testing burdens for suppliers operating across Brazil, Argentina, Paraguay, and Uruguay.
Industry Challenges
- Certified Applicator Scarcity:CONMETRO-authorized installation training programs remain limited in Brazil's northeast and Amazon regions, constraining project execution capacity.
- Legacy System Integration Friction:Renovation projects in Argentina's aging industrial base require extensive substrate remediation before polymer overlay compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Industrial Flooring Market |
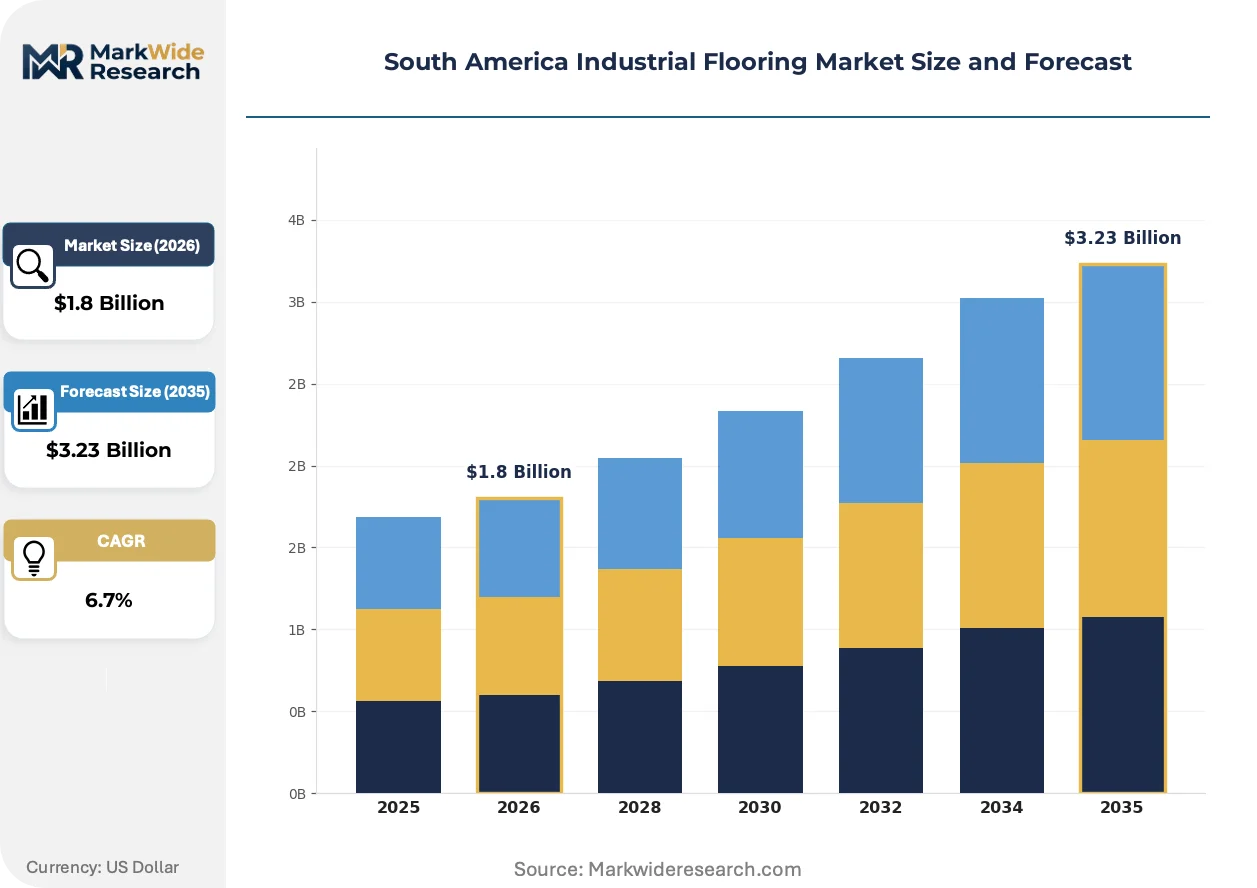
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Cementitious, Vinyl Industry Vertical: Manufacturing, Warehousing, Food Processing, Healthcare Installation Type: New Construction, Renovation, Waterproofing, Heavy Duty End User: OEMs, Contractors, Distributors, Facility Managers |
| Companies Covered | BASF SE, Sika AG, RPM International Inc., The Sherwin-Williams Company, Flowcrete Group Ltd., Armstrong Flooring Inc., Tarkett, Forbo Flooring Systems, PPG Industries, Inc., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Industrial Flooring Market Evolving Landscape
Waterborne formulation chemistry is compressing the performance gap with solvent-based systems while regulatory pressure accelerates environmental compliance timelines across Brazilian and Argentine manufacturing.
Hybrid epoxy-polyurethane systems are unifying chemical resistance and thermal shock performance in single-application specifications. Food processing facilities in São Paulo state are specifying these formulations for blast freezer-to-production floor transitions. The technology is unifying previously separate coating categories, reducing specification complexity for facility engineers.
CONMETRO's updated NBR standards for industrial safety flooring are mandating enhanced slip-resistance testing protocols. Brazilian resin formulators must recertify product lines under accelerated timelines. Heavy-duty manufacturing segments in Rio de Janeiro's port industrial zone are prioritizing pre-certified systems to avoid project delays.
Facility managers are consolidating maintenance contracts under single-source flooring lifecycle agreements. Independent applicator networks in Buenos Aires are losing specification influence to manufacturer-direct service models. This concentration is most visible in Brazil's automotive assembly plant sector, where OEMs demand decade-long performance warranties bundled with installation.
South America Industrial Flooring Market Segmentation
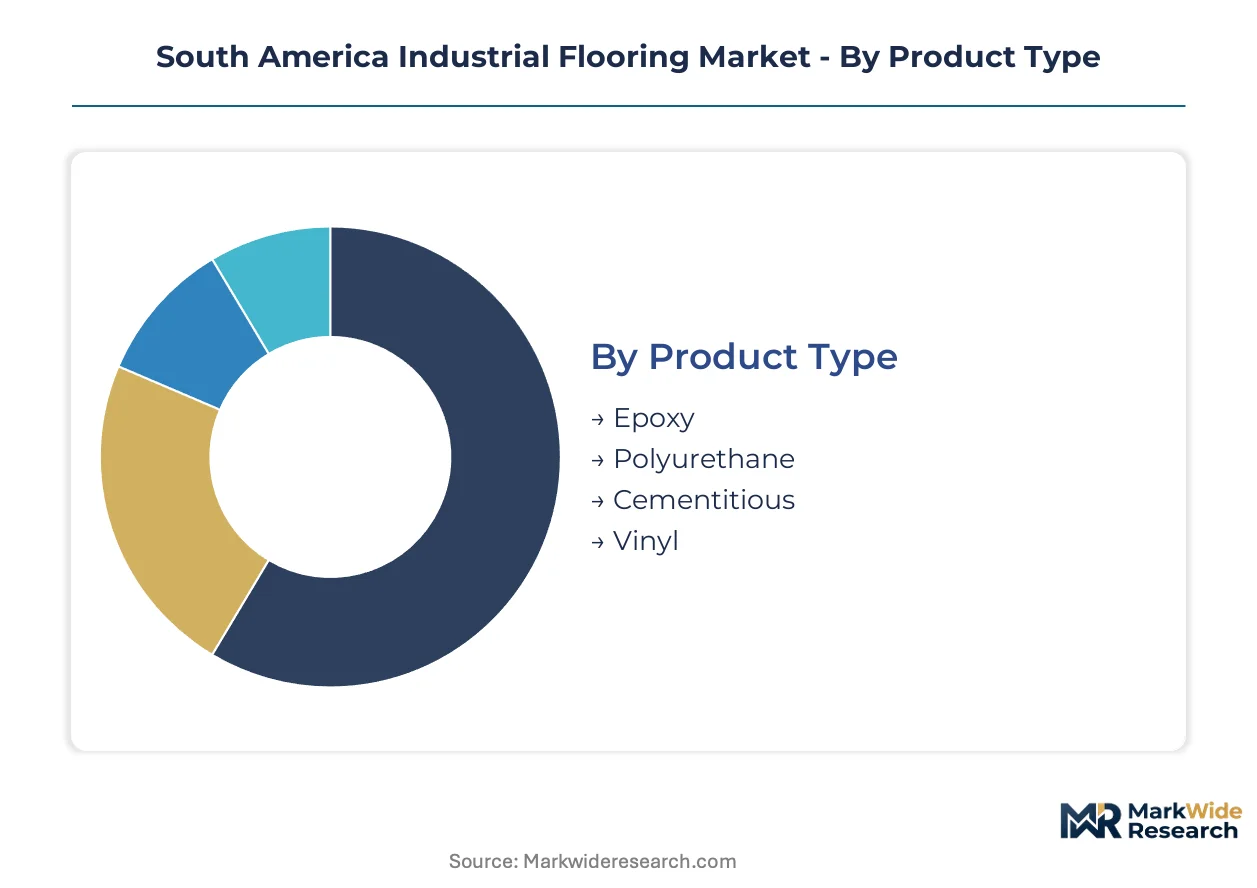
Industrial flooring segmentation in South America reflects divergent performance requirements across tropical humidity zones, regulatory compliance tiers, and substrate condition variability. Specification decisions hinge on balancing installed cost against lifecycle durability under ANVISA hygiene mandates and CONMETRO safety certifications.
Product Type:
Epoxy formulations command volume leadership through chemical resistance specifications, while polyurethane captures premium positioning in thermal cycling applications.
- Epoxy:Two-component thermosetting systems deliver compressive strengths exceeding 50 MPa with superior chemical resistance to acids and solvents. São Paulo's automotive and electronics manufacturing corridors specify these systems for heavy-duty production zones where point loading and chemical spill exposure concentrate. CONMETRO's updated NBR standards are accelerating certified epoxy adoption in Rio de Janeiro's port industrial facilities.
- Polyurethane:Elastomeric formulations accommodate thermal shock from -40°C to 120°C cycles while maintaining seamless hygiene profiles. Brazilian meat and dairy processors under ANVISA jurisdiction specify these systems for blast freezer-to-production floor transitions where thermal cycling would fracture rigid epoxy alternatives. Buenos Aires cold chain logistics investments are expanding addressable demand.
- Cementitious:Polymer-modified cement screeds enable rapid return-to-service in renovation scenarios with existing concrete substrates.
- Vinyl:Homogeneous and heterogeneous sheet goods serve light commercial and healthcare antistatic requirements with lower installed cost profiles.
Today's leader: Epoxy. Tomorrow's challenger: Polyurethane.
Industry Vertical:
Food processing commands specification intensity through hygiene mandates, while warehousing delivers volume scale through standardized abrasion-resistant systems.
- Manufacturing:Automotive assembly plants and electronics fabrication facilities specify high-build epoxy systems with ESD conductivity ratings. Brazil's southeastern manufacturing belt from Campinas to Sorocaba concentrates demand for chemically resistant flooring under continuous forklift traffic.
- Warehousing:Distribution centers near Buenos Aires and Rosario specify thin-film epoxy coatings with abrasion resistance exceeding 1,000 Taber cycles. E-commerce fulfillment buildouts across Argentina's freight corridor are accelerating standardized system specifications.
- Food Processing:ANVISA-enforced surface hygiene protocols mandate seamless polyurethane or epoxy formulations with antimicrobial additives in meat, dairy, and beverage facilities.
- Healthcare:Pharmaceutical manufacturing and hospital sterile processing departments specify low-VOC systems with chemical resistance to disinfectant protocols.
Manufacturing anchors current volume. Food processing is climbing the fastest under regulatory pressure.
Installation Type:
New construction enables optimal substrate preparation, while renovation segments command premium pricing for compatibility engineering.
- New Construction:Greenfield industrial facilities allow specification of high-performance systems with controlled cure conditions and moisture barrier integration. Brazil's expanding logistics zones near São Paulo's Guarulhos airport corridor favor these installations.
- Renovation:Aging industrial bases in Argentina require extensive substrate remediation including shot blasting, crack injection, and moisture mitigation before polymer overlay compatibility.
- Waterproofing:Below-grade and wet-process areas specify elastomeric membrane systems with hydrostatic pressure resistance.
- Heavy Duty:Foundry, forging, and metalworking operations specify trowel-applied epoxy mortars with aggregate reinforcement exceeding 6mm thickness.
New construction dominates project pipelines. Renovation is gaining share fastest as facility lifecycle extension priorities intensify.
End User:
OEMs consolidate procurement under lifecycle agreements, while contractors retain influence in fragmented regional markets.
- OEMs:Automotive and consumer goods manufacturers specify decade-long performance warranties bundled with installation, consolidating maintenance contracts under manufacturer-direct service models. Brazil's assembly plant sector exemplifies this concentration.
- Contractors:Independent applicator networks in Argentina's interior provinces and Brazil's northeast retain specification influence where certified manufacturer presence remains limited.
- Distributors:Regional material suppliers serve small-to-mid facilities with standardized product packages and basic technical support.
- Facility Managers:Industrial plant maintenance departments prioritize rapid-cure systems minimizing production downtime during scheduled maintenance windows.
OEMs anchor premium segment value. Facility managers represent the steepest expansion trajectory as lifecycle cost analytics mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's manufacturing corridor anchors South American industrial flooring demand through automotive assembly plants and electronics fabrication clusters requiring chemically resistant epoxy systems.
Brazil
ANVISA hygiene mandates drive polyurethane specifications in meat and dairy processing facilities across São Paulo state. CONMETRO's tightened NBR certification standards accelerate product recertification timelines for resin formulators. Rio de Janeiro's port industrial zone prioritizes pre-certified slip-resistant systems to avoid construction delays.
Argentina
Warehouse construction near Buenos Aires and Rosario concentrates demand for abrasion-resistant epoxy coatings in freight distribution networks. IRAM certification requirements shape cross-border supplier specifications for imported resin systems. Aging industrial bases in Córdoba require extensive substrate remediation before polymer overlay compatibility.
Chile
Seafood processing and pharmaceutical logistics investments expand demand for thermal shock-resistant polyurethane formulations in Santiago's cold chain corridor. The country's national quality regulator enforces performance benchmarks for industrial safety flooring in export-oriented facilities. Antofagasta's mining support services specify heavy-duty cementitious screeds for rapid equipment bay refurbishment.
Colombia
Bogotá's underdeveloped industrial flooring specification culture offers first-mover positioning for certified system providers entering Andean markets. Infrastructure investment programs in the national development plan prioritize logistics zone construction with standardized surface requirements. Medellín's emerging manufacturing clusters adopt epoxy formulations for light industrial assembly operations.
Uruguay
Free trade zone expansion near Montevideo attracts pharmaceutical and medical device manufacturing requiring low-VOC seamless flooring systems. Mercosur technical alignment reduces duplicate testing burdens for Brazilian suppliers crossing into this market. Punta del Este's logistics infrastructure investments specify thin-film coatings for e-commerce fulfillment buildouts.
South America Industrial Flooring Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers localize production to satisfy CONMETRO certification requirements and reduce import dependency on Asian resin feedstocks. The market structure concentrates around multinational chemical conglomerates with established Brazilian manufacturing footprints, regional specialty coating formulators, and construction chemical distributors serving fragmented interior markets. Three archetypes define competitive positioning: integrated resin producers controlling upstream formulation chemistry, application-focused service providers bundling installation with material supply, and regional distributors leveraging logistics networks for project site delivery. Geographic expansion into underpenetrated Andean markets and portfolio diversification into waterborne alternatives represent the dominant competitive vectors.
Among European-based chemical conglomerates, BASF SE and Sika AG exemplify the integrated producer archetype through captive resin formulation capabilities and regional manufacturing infrastructure. RPM International Inc. occupies a position within the specialty coating tier, representing North American entrants competing through differentiated product positioning. These three anchors illustrate how competitive advantage derives from certification compliance, supply chain proximity to São Paulo's industrial corridor, and formulation flexibility across epoxy and polyurethane chemistries.
| Leading Market Players |
|---|
| BASF SE |
| Sika AG |
| RPM International Inc. |
| The Sherwin-Williams Company |
| Flowcrete Group Ltd. |
| Armstrong Flooring Inc. |
| Tarkett |
| Forbo Flooring Systems |
| PPG Industries, Inc. |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between CONMETRO-compliant systems and uncertified alternatives splits pricing power along compliance tiers while reshaping supplier sourcing toward Brazilian manufacturing footprints. Premium formulations command project premiums in São Paulo's automotive corridor, whereas commodity epoxy imports from Asian suppliers serve price-sensitive renovation segments in Argentina's interior.
Pricing Analysis
Epoxy resin pricing tracks naphtha and propylene feedstock fluctuations from Brazilian and Argentine refineries, compressing margin visibility for regional formulators. Three-tier pricing structure across premium, standard, and economy levels separates CONMETRO-certified systems from IRAM-aligned imports and uncertified local blends. Pricing pressure stems from petrochemical input volatility and currency instability affecting specialty isocyanate imports. Facility managers in Brazil's food processing sector show lowest price sensitivity due to ANVISA hygiene mandates, while Argentine warehouse contractors exhibit highest elasticity.
Supply Chain Analysis
Freight costs from Asian specialty chemical suppliers concentrate supply risk for isocyanates and curatives serving Brazilian formulators. Manufacturing gravity centers on São Paulo state, with secondary concentration in Buenos Aires for Argentine market access. Raw material dependencies include epoxy resins, aliphatic isocyanates, and antimicrobial additives. Single-source vulnerability from Asian curative suppliers exposes formulators to shipping cost spikes. Distribution runs through manufacturer-direct service models in Brazil's OEM sector and independent applicator networks in Argentina's fragmented interior.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where CONMETRO certification costs in Brazil create margin expansion opportunities for pre-certified suppliers entering underregulated Andean markets. Regulatory divergence between Brazil's tightened NBR standards and Colombia's nascent specification culture enables tiered market entry strategies.
For Market Incumbents: Anchor market position through captive production of waterborne formulations in São Paulo state to satisfy accelerating CONMETRO solvent-based phase-out timelines. Defend against Asian import erosion by deepening technical service bundling with decade-long warranty structures for automotive OEMs. Prioritize backward integration into epoxy resin production to insulate margin compression from naphtha volatility. For New Entrants and Emerging Players: Launch via certified-applicator partnerships in Bogotá's logistics zone construction, where specification culture remains undeveloped and first-mover positioning is achievable. Target Chilean cold chain facility buildouts with thermal shock-resistant polyurethane formulations underserved by incumbent distribution. Penetrate through manufacturer-direct service models rather than fragmented contractor networks to capture lifecycle contract value. For Investors and Strategic Acquirers: Consolidation pressure builds where certified-applicator scarcity in Brazil's northeast and Amazon regions constrains project execution capacity for national formulators. Long-term viability favors vertically integrated resin producers with CONMETRO-compliant manufacturing footprints over import-dependent blenders. Acquisition targets include regional specialty coating formulators with established IRAM certification pathways. Watch for Mercosur technical harmonization announcements as inflection signals for cross-border scale economics.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Local Brazilian production satisfies CONMETRO certification requirements while reducing import dependency on Asian resin feedstocks. |
| Backward Integration | In-house epoxy resin production insulates formulators from naphtha and propylene price volatility in regional refining markets. |
| Certification Investment | CONMETRO NBR recertification timelines accelerate competitive separation between compliant and non-compliant system providers. |
| Joint Venture | Partnerships with certified applicator networks address scarcity constraints in Brazil's northeast and Amazon project corridors. |
| Geographic Expansion | Andean market entry into Colombia and Peru captures first-mover positioning before specification culture matures. |
Research Methodology
Coverage spans Brazil, Argentina, Chile, Colombia, and Uruguay, with primary inputs from each market's manufacturing and logistics corridors. The approach combines structured interviews with plant engineers, procurement leads at food processing facilities, certified flooring applicators, and technical R&D directors at resin formulators with secondary validation from ANVISA regulatory filings, CONMETRO certification databases, IRAM standards documentation, and customs trade records. Bottom-up project pipeline analysis triangulates against top-down sector spending estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models segmentation dimensions including product chemistry (epoxy, polyurethane, cementitious), industry vertical (manufacturing, warehousing, food processing), installation type (new construction, renovation), and end-user procurement model (OEM lifecycle contracts, contractor-specified, distributor-supplied). CAGRs derive from normalized historical trajectory analysis adjusted for regulatory inflection points and infrastructure investment cycles specific to Mercosur logistics development.
Several conditions sit outside the modeled scope, including abrupt petrochemical feedstock disruptions, currency devaluation episodes exceeding historical bands, and unilateral tariff impositions disrupting Asian chemical imports. Forecasts reflect documented assumptions regarding CONMETRO enforcement continuity and ANVISA hygiene mandate stability. A model refresh is warranted upon material change in Mercosur technical regulation harmonization timelines or Brazilian central bank policy affecting import financing costs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Steel Wire Rod Market
Building & Construction Materials
Aerated Autoclaved Concrete (AAC) Market
Building & Construction Materials
Concrete Floating Floors System Market
Building & Construction Materials
US Precast Concrete Market
Building & Construction Materials
Wood House Frame Market
Building & Construction Materials
North America Cast-In-Place Concrete Flooring Market
Building & Construction Materials
Thailand Construction Chemicals Market
Building & Construction Materials
Australia and New Zealand Industrial Flooring Market
Building & Construction Materials
US Exterior Wall Systems Market
Building & Construction Materials
Electrochromic Glass for Construction Market
Building & Construction Materials
Girdle Plates Market
Building & Construction Materials
Roofing Tiles Market
Building & Construction Materials
Building Acoustic Insulation Market
Building & Construction Materials
Fiberglass Doors Market
Building & Construction Materials
APAC Commercial Glazing System Market
Building & Construction Materials
South Africa Wall Putty Market