
 Welded Wire Mesh Market | 2026-2036
Welded Wire Mesh Market Size, Share, and Industry Trends Forecast 2026-2036
Welded Wire Mesh Market Analysis
Automation in resistance welding is narrowing the cost gap between manual and robotic production lines across welded wire mesh fabrication. Riverdale Mills sustains its position through vertical integration into galvanized wire drawing, controlling raw material quality from melt to finished panel. Anping Yangze Metal Wire Mesh Co.,Ltd anchors volume supply for Asia-Pacific infrastructure tenders, leveraging proximity to Chinese steel mills. Banker Wire differentiates through architectural-grade stainless mesh for facade and interior applications, commanding premium positioning in design-specified projects.
Welded wire mesh consists of longitudinal and transverse wires joined at intersections by electric resistance welding, producing grid patterns with aperture sizes ranging from fractional inches to several inches for load-distribution or containment functions. The product serves primarily as concrete crack-control reinforcement, security fencing, animal enclosure, and industrial filtration support. Reinforcing mesh dominates value contribution as construction-grade steel specifications tighten under structural building codes. Stainless steel material commands outsized margins despite smaller volume, driven by coastal infrastructure corrosion-resistance mandates and food-processing hygiene requirements. Square mesh retains the largest installed base in agricultural fencing, though grating applications in offshore platforms and wastewater treatment plants represent the fastest-expanding demand pool.
ASTM International governs welded steel wire fabric for concrete reinforcement through A185 and A497 specifications, while ISO 15630 sets global baseline testing protocols for welded mesh used in structural concrete. China's GB/T 1499.3 standard mandates mechanical property verification for reinforcing mesh in state-funded construction, effectively filtering non-compliant suppliers from public project procurement. The EU Construction Products Regulation requires CE marking for structural mesh sold in member states, adding conformity assessment costs that favor scaled producers with in-house testing laboratories. Stakeholders must track evolving carbon-border adjustment mechanisms and scrap-steel sourcing disclosure rules, as these will reshape cost structures for carbon-intensive welded mesh manufacturing faster than product specification changes.
Market Dynamics
Resistance welding automation is compressing unit economics across welded wire mesh fabrication, eroding the historical cost advantage of manual production lines and forcing mid-scale producers toward robotic retrofit or exit.
Growth Catalysts
- ASTM A185 compliance mandates:North American infrastructure contractors now require certified reinforcing mesh for federal highway bids, filtering uncertified suppliers from public procurement pools.
- China's state-funded rail expansion:Heavy-gauge mesh consumption concentrates in port and high-speed rail projects where GB/T 1499.3 verification is mandatory for tender eligibility.
- Stainless steel corrosion resistance:Coastal infrastructure specifications in marine environments are specifying 316-grade mesh for bridge decks and seawall reinforcement.
Market Restraints
- Scrap steel price volatility:Electric arc furnace feedstock costs swing with commodity cycles, compressing margins for producers without captive raw material supply.
- Supplier concentration in Hebei Province:Chinese wire rod production clusters create geographic single-point vulnerability for mesh fabricators dependent on imported feedstock.
- Composite rebar substitution:Glass fiber reinforced polymer bars are displacing steel mesh in specific corrosion-critical applications where weight reduction justifies premium pricing.
Strategic Opportunities
- India's PLI scheme for specialty steel:Production-linked incentives are attracting mesh producers to establish localized fabrication for domestic infrastructure build-out.
- Offshore platform grating applications:Oil and gas decommissioning standards are expanding specification for heavy-duty welded mesh in temporary work platforms.
- EU Carbon Border Adjustment Mechanism:First-mover producers with verified low-carbon wire supply are positioning for premium access to European structural mesh markets.
Industry Challenges
- Resistance welding technician scarcity:Automated line programming and electrode maintenance skills are in short supply as vocational pipelines shrink across manufacturing regions.
- CE marking conformity timelines:EU Construction Products Regulation assessment delays are extending product launch cycles for new mesh specifications by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Welded Wire Mesh Market |
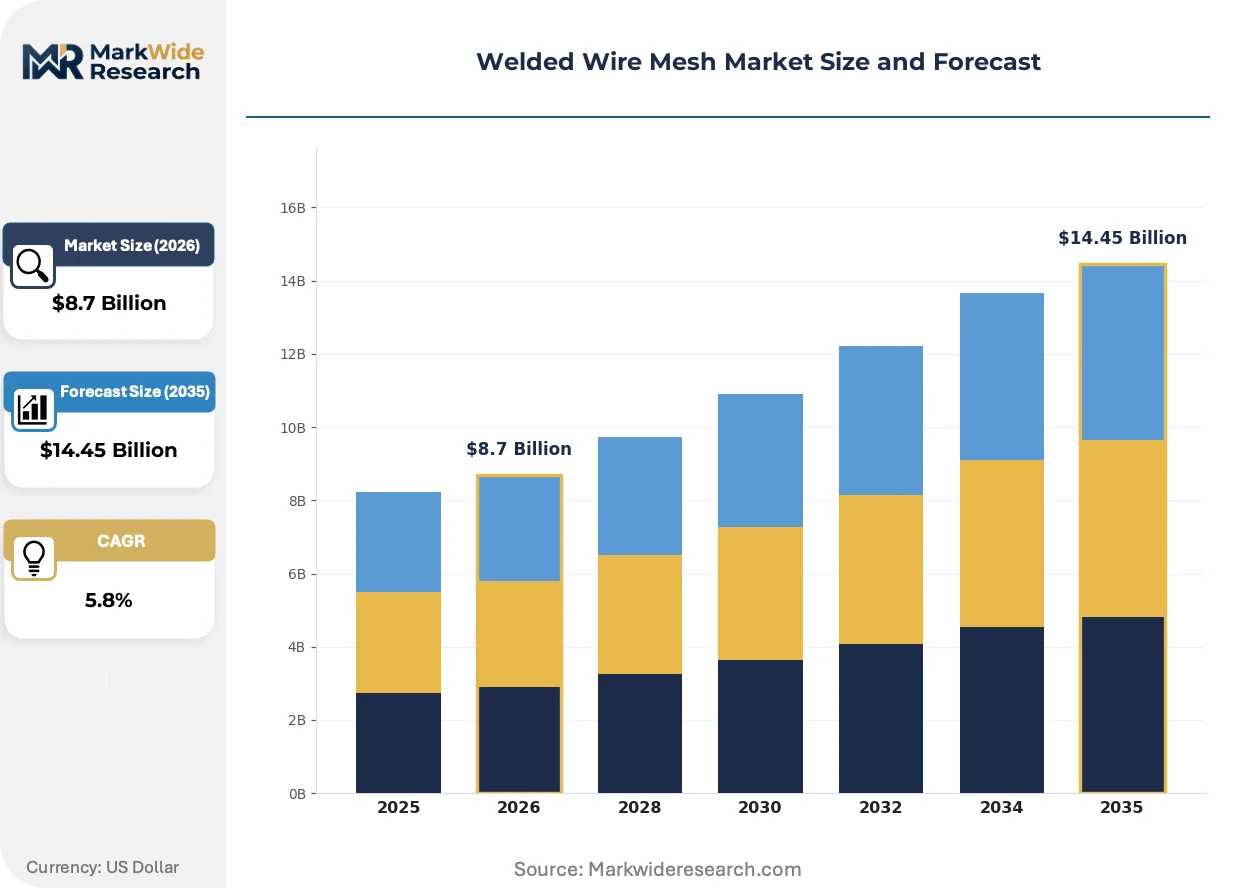
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Square Mesh, Rectangular Mesh, Grating, Reinforcing Mesh Application: Construction, Agriculture, Industrial, Fencing Material: Steel, Stainless Steel, Aluminum, Composite End User: Contractors, Manufacturers, Farmers, Retailers |
| Companies Covered | Riverdale Mills, Direct Metals, Marco Specialty Steel, Inc., Wire Mesh Corporation, Dorstener Wire Tech, Anping Yangze Metal Wire Mesh Co.,Ltd, Banker Wire, McNICHOLS Company, CIB Wire & Iron Works, LLC., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Welded Wire Mesh Market Emerging Trajectories
Digital thread integration across welding parameter monitoring and quality assurance is compressing defect rates while enabling predictive maintenance on resistance welding lines.
Digital twin simulation of weld nugget formation is virtualizing process optimization for mesh fabricators, allowing parameter refinement without production line downtime. Automotive tier suppliers are adopting these tools fastest, transferring expertise from precision component welding to structural mesh applications. The technology is virtualizing quality assurance workflows, reducing physical destructive testing requirements by enabling real-time weld integrity prediction.
China's evolving GB standards for low-carbon steel products are tightening embodied carbon disclosure requirements for reinforcing mesh used in state projects. Producers must now document scrap-to-finished-product emissions or face tender disqualification. Hebei-based mills are responding by integrating electric arc furnace traceability systems to maintain public procurement access.
Direct mill-to-contractor purchasing platforms are disintermediating traditional distribution channels for standard mesh specifications. Large infrastructure contractors in Australia and Canada are establishing preferred supplier portals that bypass wholesale intermediaries for recurring volume orders. This channel compression is most visible in highway and bridge segments where project-scale procurement justifies dedicated logistics arrangements.
Welded Wire Mesh Market Segmentation
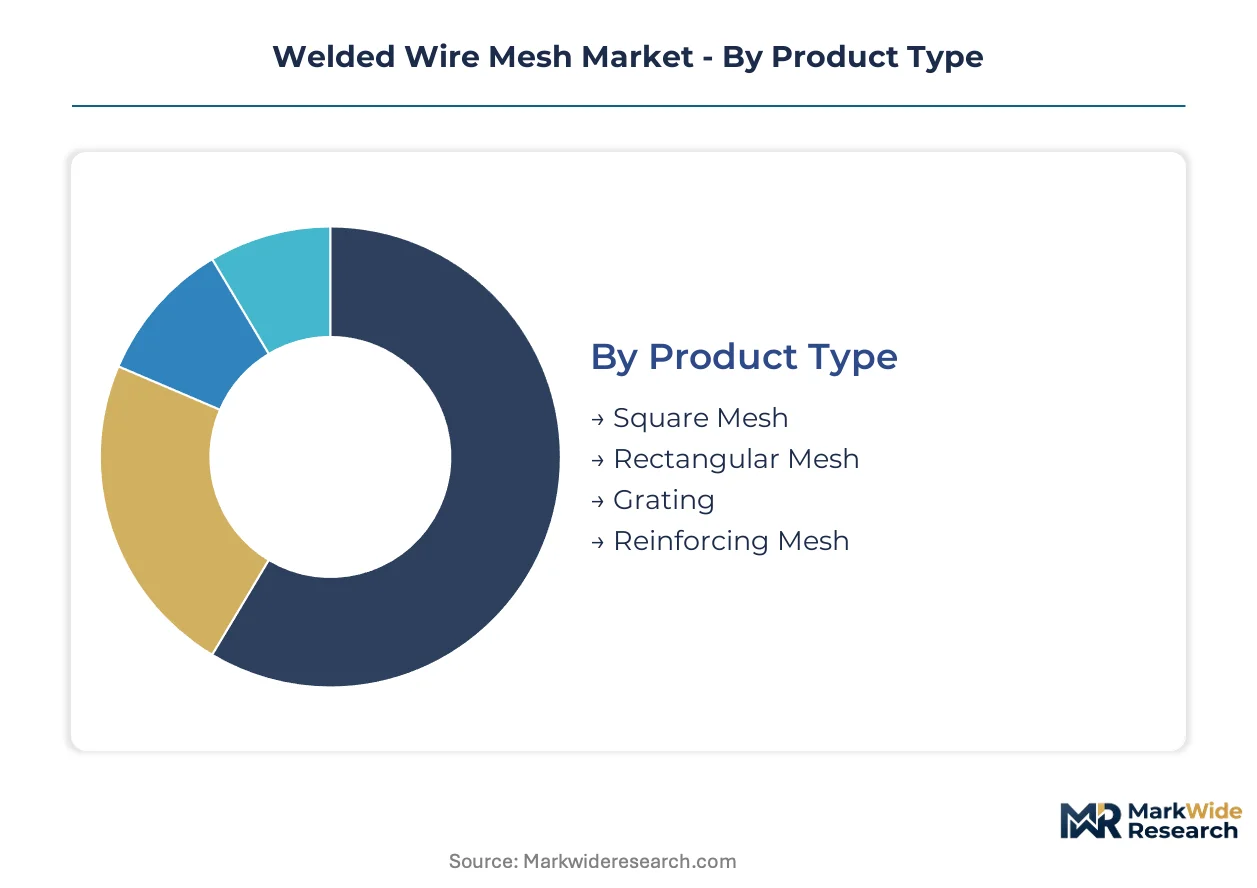
Welded wire mesh segmentation reflects divergent performance requirements across load-bearing infrastructure, corrosion-critical environments, and containment applications. Specification-grade differentiation determines procurement channels, certification burdens, and margin structures for fabricators serving distinct end-use clusters.
Product Type:
Product architecture separates containment-grade specifications from structural reinforcement grades, with aperture geometry and wire gauge dictating performance envelopes.
- Reinforcing Mesh:Heavy-gauge welded grids engineered to ASTM A185 and ISO 15630 standards for concrete crack control and load distribution. China's state-funded rail and port projects in Hebei Province consume this grade at scale under mandatory GB/T 1499.3 verification.
- Square Mesh:Uniform aperture patterns ranging from fractional inches to several inches, optimized for agricultural fencing and general containment. Livestock enclosure specifications in Australia and Brazil favor this geometry for cost-efficient perimeter security.
- Rectangular Mesh:Elongated aperture configurations tailored to directional load applications and architectural screening. Facade systems in coastal urban developments specify this pattern for aesthetic flexibility combined with wind-load resistance.
- Grating:Heavy-duty welded panels with bearing bar configurations for elevated work platforms and drainage covers. Offshore platform decommissioning standards are expanding procurement for temporary staging applications.
Reinforcing mesh holds installed capacity. Grating is rotating up the share rankings.
Application:
End-use concentration varies by infrastructure investment cycles, agricultural land use patterns, and industrial facility construction intensity.
- Construction:Concrete reinforcement for highways, bridges, and commercial structures dominates value capture. Federal infrastructure contractors in the United States now require ASTM A185 certification for public project eligibility.
- Fencing:Perimeter security and animal enclosure applications span residential, commercial, and agricultural boundaries. Brazilian ranching operations and Australian pastoral properties drive volume procurement for boundary demarcation.
- Industrial:Filtration support, machine guarding, and material handling applications serve manufacturing facilities. Food-processing hygiene mandates in the European Union and Saudi Arabia specify stainless steel grades for contact surfaces.
- Agriculture:Crop protection, livestock containment, and greenhouse infrastructure utilize lighter-gauge specifications. India's expanding horticultural sector under PLI incentives is absorbing mesh for protected cultivation structures.
Construction commands the dominant revenue position. Industrial is climbing fastest on corrosion-resistance specification upgrades.
Material:
Material selection balances structural performance, environmental exposure severity, and lifecycle cost calculations across deployment environments.
- Steel:Carbon steel grades dominate volume production for non-corrosive interior applications and temporary works. Electric arc furnace feedstock traceability is becoming mandatory for Chinese state project procurement under evolving GB standards.
- Stainless Steel:316-grade and 304-grade alloys command premium positioning for marine infrastructure, chemical processing, and food-contact applications. Bridge deck specifications in Florida and Mediterranean coastal zones mandate this material for salt-spray resistance.
- Aluminum:Lightweight, non-corroding alternative for architectural facades and transportation applications where weight reduction justifies material cost premiums. Airport perimeter fencing in the Middle East favors this grade for reduced foundation loads.
- Composite:Glass fiber reinforced polymer and basalt fiber alternatives displacing steel in specific electromagnetic-sensitive or chemically aggressive environments. MRI facility construction and wastewater treatment plants specify these grades for non-conductive or acid-resistant performance.
Steel maintains volume leadership. Stainless steel is expanding most quickly on coastal infrastructure mandates.
End User:
Procurement behavior diverges between project-scale specification buyers and recurring volume purchasers with inventory management requirements.
- Contractors:Highway, bridge, and commercial construction firms purchasing certified mesh to project specifications. Australian and Canadian infrastructure contractors are establishing direct mill portals that bypass wholesale intermediaries for recurring volume.
- Manufacturers:Industrial equipment builders and prefabricated structure producers integrating mesh into finished products. Filtration equipment fabricators in Germany and South Korea source precision-aperture specifications for process equipment.
- Farmers:Agricultural operators procuring fencing and livestock containment through dealer networks or cooperative purchasing. Brazilian and Argentine ranching cooperatives negotiate seasonal volume contracts with regional distributors.
- Retailers:Hardware chains and agricultural supply stores stocking standard sizes for walk-in customer demand. Inventory turnover velocity favors lighter-gauge fencing specifications over structural reinforcing grades.
Contractors anchor specification-grade demand. Manufacturers are rotating up the share rankings on industrial automation investment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in welded wire mesh track closely to steel feedstock availability and infrastructure investment cycles. China maintains net exporter status while the United States and Germany absorb significant import volumes for specialized grades.
China
State-funded rail and port projects in Hebei Province consume heavy-gauge reinforcing mesh at scale. GB/T 1499.3 verification is mandatory for tender eligibility in public procurement. Tianjin and Tangshan steel clusters supply wire rod feedstock to Anping County fabricators serving domestic and export markets.
United States
Federal highway contractors drive ASTM A185 certified mesh demand through infrastructure spending programs. OSHA workplace safety regulations shape industrial grating specifications for elevated platforms. Ohio and Pennsylvania manufacturing corridors host resistance welding operations serving North American construction markets.
Germany
CE marking requirements under the EU Construction Products Regulation filter non-compliant suppliers from structural mesh procurement. REACH chemical compliance adds conformity costs for galvanized coatings. The Ruhr industrial region maintains fabrication capacity for precision-aperture specifications serving automotive and machinery sectors.
India
PLI scheme incentives for specialty steel are attracting mesh producers to establish localized fabrication capacity. BIS certification requirements govern reinforcing mesh for government infrastructure projects. Gujarat and Maharashtra industrial zones are emerging as production hubs for domestic highway and commercial construction supply.
Australia
Direct mill-to-contractor purchasing platforms are disintermediating wholesale channels for standard mesh specifications. State-level building codes mandate corrosion-resistant grades for coastal infrastructure. Queensland and New South Wales mining operations drive heavy-duty grating demand for temporary work platforms and material handling.
Welded Wire Mesh Market Vendor Landscape
On the supply side, the industry is consolidating around scaled producers with captive wire drawing capacity and in-house certification laboratories. Mid-scale fabricators face margin compression from robotic welding automation investments by larger competitors. Two strategic archetypes dominate: vertically integrated steel-to-mesh operators controlling raw material quality, and specialized architectural-grade stainless producers commanding design-specified premiums. Capacity expansion and backward integration into galvanized wire production represent the dominant competitive moves.
Among North American fabricators, Riverdale Mills and Banker Wire occupy distinct positioning tiers. Riverdale Mills exemplifies the integrated steel-to-mesh archetype through upstream control over galvanized wire production. Banker Wire represents the premium specialization vector, anchoring architectural-grade stainless mesh supply for facade and interior applications. Anping Yangze Metal Wire Mesh Co.,Ltd sits within the Asia-Pacific volume tier, leveraging proximity to Chinese steel mills for infrastructure tender participation.
| Leading Market Players |
|---|
| Riverdale Mills |
| Direct Metals |
| Marco Specialty Steel, Inc. |
| Wire Mesh Corporation |
| Dorstener Wire Tech |
| Anping Yangze Metal Wire Mesh Co.,Ltd |
| Banker Wire |
| McNICHOLS Company |
| CIB Wire & Iron Works, LLC. |
| Others |
Supply Flow & Price Mechanics
Tianjin-Xingang freight corridors dictate landed cost spreads between Hebei wire rod clusters and coastal fabrication sites, compressing margin buffers for distributors while amplifying price differentiation between captive-mill producers and import-dependent fabricators serving ASTM A185 specification buyers.
Pricing Analysis
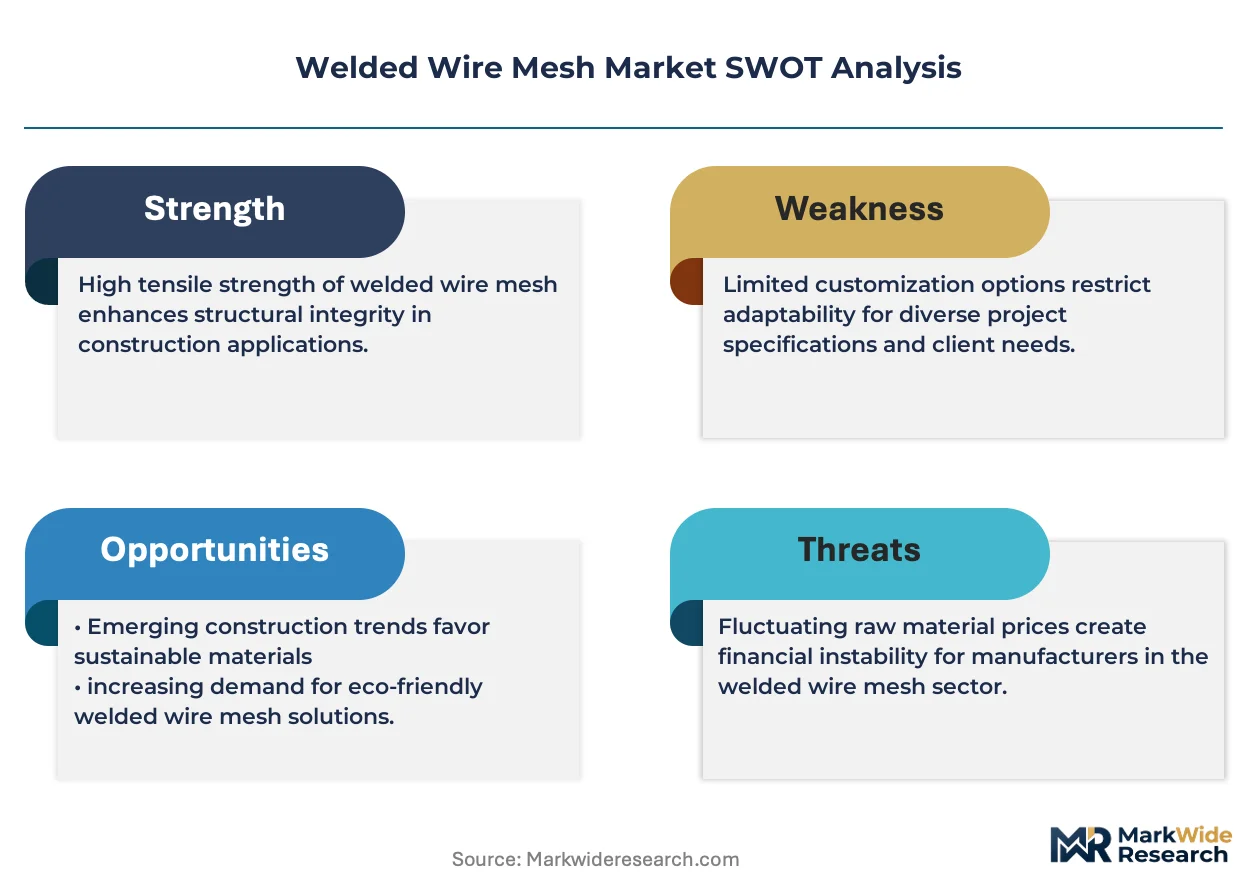
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in welded wire mesh procurement. Certification grade under ASTM A185 and ISO 15630 standards separates premium structural reinforcement tiers from uncertified commodity fencing grades, while volume scale and geographic delivery cost drive mid-tier differentiation. Pricing pressure stems from robotic welding automation investments by scaled producers, which compresses margins for manual-line competitors. Contractors represent the most price-sensitive segment due to project-bid constraints, whereas food-processing OEMs exhibit lowest sensitivity given hygiene-mandated stainless steel specifications.
Supply Chain Analysis
Scrap steel feedstock draws from electric arc furnace operations concentrated in China, the United States, and Turkey, with wire rod drawing capacity clustering in Hebei Province and the Ruhr industrial region. Zinc ingot and stainless steel alloy inputs rest on nickel price volatility and galvanized coating specifications. Single-source vulnerability characterizes the Hebei wire rod cluster, where geographic concentration creates disruption exposure for mesh fabricators lacking alternative feedstock arrangements. Distribution runs through direct mill-to-contractor portals for highway and bridge contractors, while agricultural fencing channels move through regional dealer networks and cooperative purchasing structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glass fiber reinforced polymer rebar substitution in corrosion-critical infrastructure represents the central threat incumbents must neutralize through performance differentiation and specification-grade positioning.
For Market Incumbents: Build certification moats around ASTM A185 and ISO 15630 compliance infrastructure to filter non-compliant competitors from federal highway procurement pools. Invest in robotic resistance welding retrofit to compress unit economics against manual-line rivals, while securing captive wire drawing capacity to buffer scrap steel price volatility. CE marking conformity laboratories in-house will shorten EU product launch cycles currently extended by third-party assessment delays.
For New Entrants and Emerging Players: Mid-market industrial grating for offshore platform decommissioning in the North Sea and Gulf of Mexico represents the most penetrable entry point, given specification-grade demand growth and limited incumbent specialization. India's PLI scheme-attracted specialty steel fabrication zones offer localized production access for domestic infrastructure tenders. Partner with filtration equipment OEMs in Germany and South Korea for precision-aperture specification supply, leveraging design-specified premium positioning over commodity volume competition.
For Investors and Strategic Acquirers: Carve-out targets emerge from family-owned mesh fabricators in Australia's Queensland and New South Wales mining corridors, where direct mill-to-contractor purchasing platforms are disintermediating traditional distribution channels. Long-term viability hinges on backward integration into galvanized wire production and in-house certification laboratory ownership. Monitor EU Carbon Border Adjustment Mechanism implementation timelines as the inflection signal for low-carbon wire supply premium access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Galvanized Wire Production | Captive feedstock supply from Hebei and Tangshan steel clusters buffers scrap price volatility for ASTM A185 certified mesh output. |
| CE Marking Conformity Laboratory Investment | In-house EU Construction Products Regulation assessment compresses product launch cycles from 14 months toward competitive benchmarks. |
| Robotic Resistance Welding Line Retrofit | Automation narrows unit economics against manual-line competitors while addressing technician scarcity in electrode maintenance skills. |
| Direct Mill-to-Contractor Portal Development | Channel compression bypasses wholesale intermediaries for Australian and Canadian highway contractors with recurring volume procurement. |
| Low-Carbon Wire Supply Chain Documentation | Electric arc furnace traceability systems maintain access to Chinese state-funded rail and port tenders under evolving GB standards. |
Methodological Framework
Desk research of trade customs data, ASTM and ISO standard documentation, and SEC filings from publicly traded steel producers preceded structured interviews with resistance welding line operators, highway contractor procurement directors, and galvanized wire drawing plant managers. Primary fieldwork with filtration equipment OEMs in Germany and food-processing facility engineers in Saudi Arabia validated secondary demand estimates for stainless steel grades. Bottom-up volume triangulation across product type, material specification, and end-user segment converged with top-down steel feedstock consumption analysis.
Assumptions held fixed include infrastructure budget execution rates in China and the United States, while scrap steel price volatility and EU carbon border adjustment implementation timelines were modeled as scenario variables across the projection horizon. Segmentation dimensions spanned reinforcing mesh versus containment grades, carbon versus stainless versus composite materials, and contractor versus manufacturer versus agricultural end-user procurement patterns. CAGRs derived from installed capacity expansion announcements, state-funded project pipelines, and substitution elasticity estimates for composite rebar displacement in corrosion-critical applications.
Macroeconomic conditions sit as an overlay; deviation in Chinese state construction spending execution or US federal highway appropriation cycles would shift the trajectory materially. Forecasts reflect these assumptions without claiming predictive certainty. Cross-checking against customs export data from Tianjin and Tangshan port authorities is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Concrete Block and Brick Manufacturing Market
Building & Construction Materials
GRC Conduit Fittings Market
Building & Construction Materials
European Cross-Laminated Timber Market
Building & Construction Materials
Honeycomb Sandwich Panels Market
Building & Construction Materials
Australia and New Zealand Industrial Flooring Market
Building & Construction Materials
Japan Oriented Strand Board Market
Building & Construction Materials
Ready-Mix Concrete Market
Building & Construction Materials
ASEAN Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Asia-Pacific Flanges Market
Building & Construction Materials
Drainage System Market
Building & Construction Materials
Pipe Hanger Market
Building & Construction Materials
Facade Anchor Systems Market
Building & Construction Materials
Industrial Flooring Market
Building & Construction Materials
TMT Steel Bar Market
Building & Construction Materials
USA and Canada Fence Screen Market
Building & Construction Materials
Liquid Applied Roofing Market