
 Door Hinges Market | 2026-2036
Door Hinges Market Size, Share, and Industry Trends Forecast 2026-2036
Door Hinges Market Intelligence
The market for door hinges is pivoting on a clear divergence between advanced, feature-rich products and standard commodity hardware. Assa Abloy specializes in high-security commercial solutions, while Hettich Holding GmbH Co. Ohg leverages its expertise in concealed residential hinges. Hager Companies sustains its position by supplying high-volume butt hinges to the construction sector, illustrating the market's split focus between specialized innovation and scaled production.
A door hinge is a mechanical bearing that connects a door to a frame, allowing a limited angle of rotation. These devices are typically fabricated from metals like steel or brass and are rated based on load capacity, cycle endurance, and fire resistance. Stainless steel hinges command a premium due to their corrosion resistance, particularly in commercial and coastal residential applications. While butt hinges remain the volume leader, pivot hinges represent a high-margin niche for architectural and design-led projects.
Product standards from the American National Standards Institute (ANSI/BHMA) define grades for durability, while CE marking in Europe mandates safety performance for market access. ISO 9001 standards further guide quality management for manufacturers globally. Stakeholders must now decide whether to compete on manufacturing scale for commodity products or invest in R&D for specialized, high-performance systems.
Market Dynamics
A fundamental divergence between high-volume, standardized hardware for construction and specialized, high-margin systems for architectural projects defines the market. This split influences everything from material sourcing and manufacturing scale to distribution channels and R&D investment priorities.
Growth Catalysts
- Infrastructure Development:Government-led initiatives in India, such as the Smart Cities Mission, are accelerating demand for all grades of door hardware in new public and commercial buildings.
- Hospitality Sector Renewal:A global cycle of hotel construction and renovation requires hinges that meet stringent durability, fire-safety, and aesthetic standards, particularly for high-traffic common areas.
- Performance Standards:The adoption of ANSI/BHMA A156.1 standards for graded hinges in North American commercial projects pulls demand toward certified, higher-value products.
Market Restraints
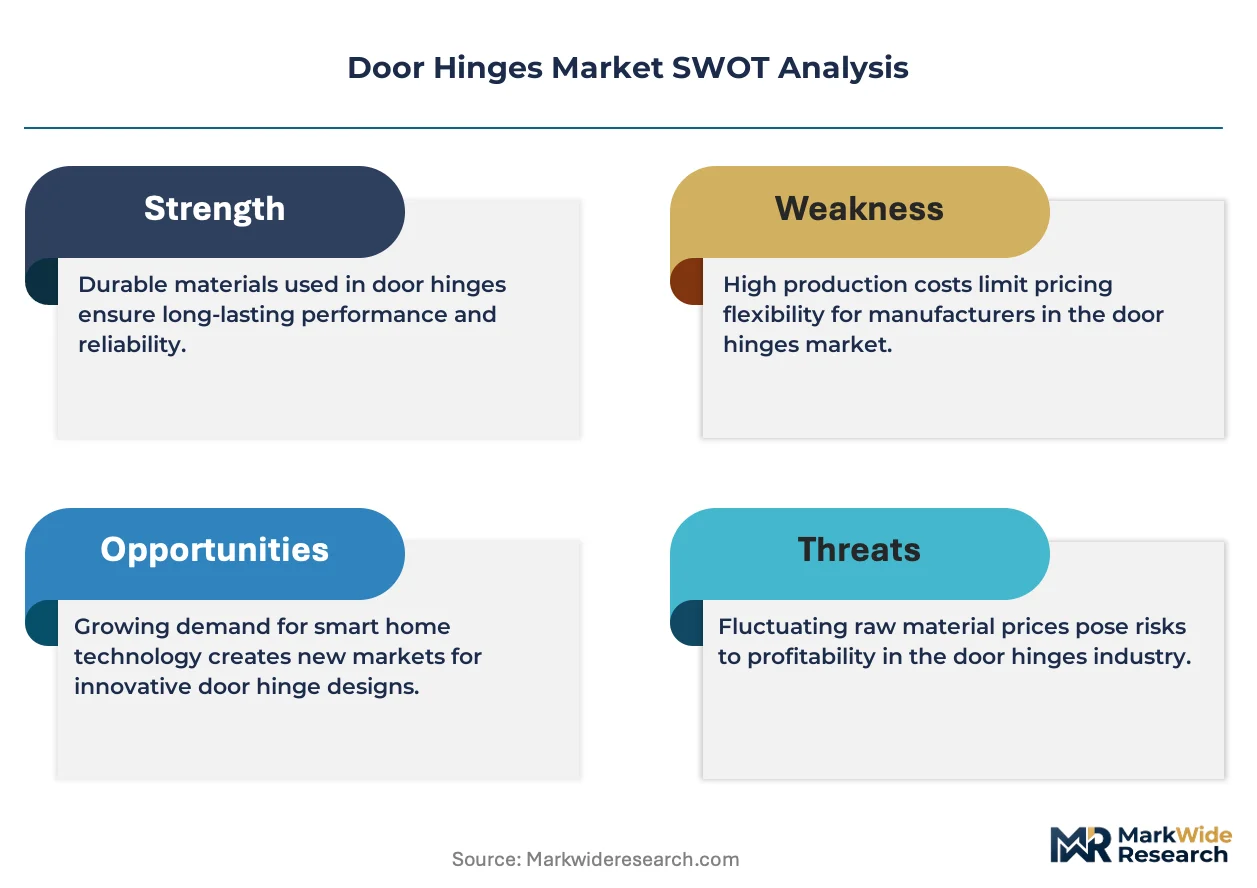
- Input Material Volatility:Price fluctuations in raw materials like stainless steel and brass, influenced by global supply and tariffs, directly impact manufacturer margins and pricing stability.
- Design-Led Substitution:The preference for minimalist aesthetics in architectural projects promotes the use of pivot and concealed hinges, eroding the market for traditional butt hinges in high-end segments.
- Logistical Bottlenecks:Heavy reliance on Asian manufacturing for both finished commodity hinges and raw material processing creates vulnerability to shipping delays and geopolitical friction.
Strategic Opportunities
- Smart Hinge Integration:Developing hinges with embedded sensors for integration with building automation and security systems opens a new service-based revenue stream for commercial facilities management.
- Specialized Coatings:Formulating advanced corrosion-resistant coatings beyond standard stainless steel creates opportunities in marine, chemical processing, and other extreme environment applications.
- Southeast Asian Expansion:Urbanization and a growing middle class in countries like Vietnam and Indonesia present new growth markets for residential and light commercial hardware.
Industry Challenges
- Global Certification Burden:Manufacturers seeking global distribution face high costs and long lead times to secure parallel certifications, such as CE marking in Europe and ANSI/BHMA compliance in the US.
- Interoperability Standards:The absence of a universal communication protocol for smart hinges fragments the market and complicates integration with diverse smart building platforms from different vendors.
- Intellectual Property Defense:Protecting unique mechanical designs and proprietary coating formulas from reverse-engineering by low-cost competitors is a persistent operational challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Door Hinges Market |
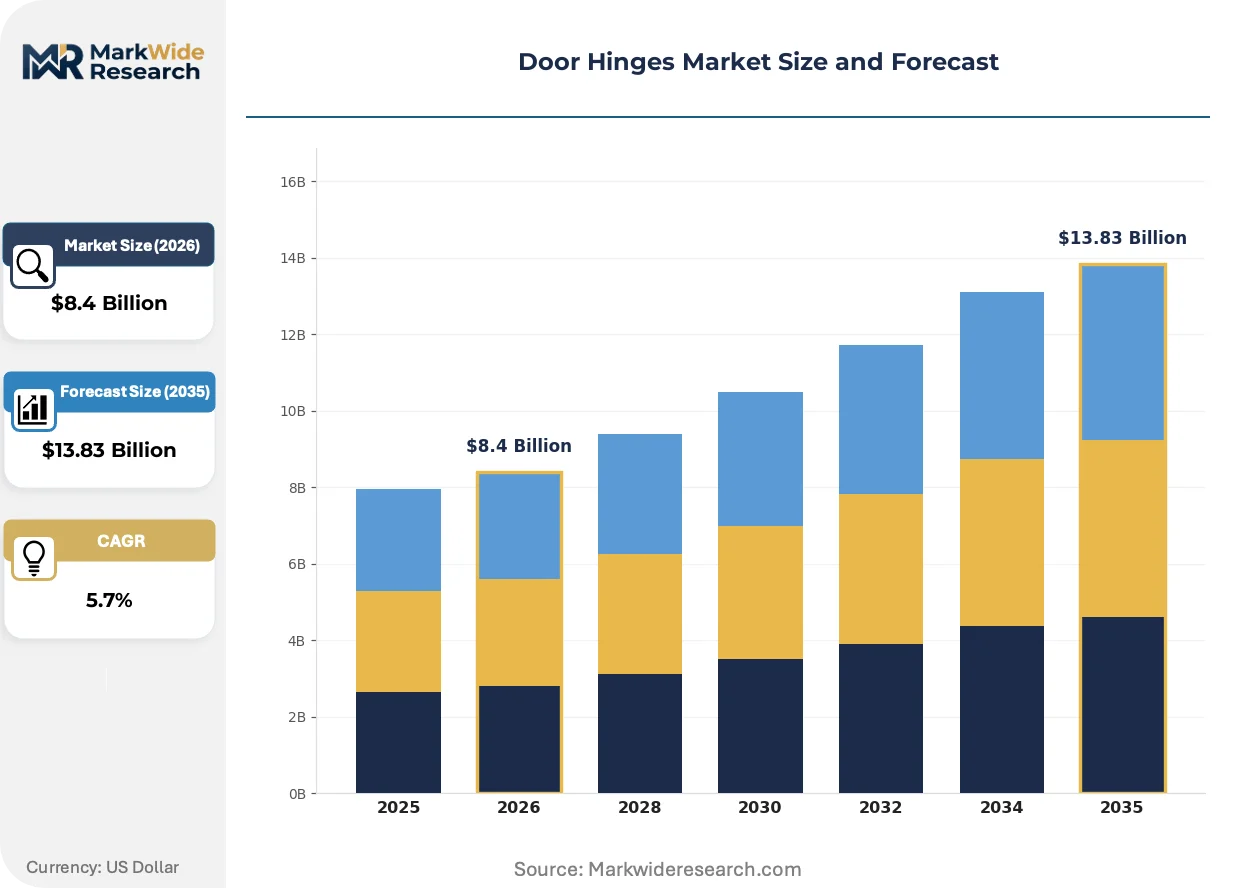
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butt Hinges, Continuous Hinges, Pivot Hinges, Strap Hinges, Spring Hinges, Barrel Hinges Material: Steel, Brass, Aluminum, Stainless Steel, Bronze, Zinc Alloy Application: Residential Doors, Commercial Entrances, Institutional Doors, Hospitality Facilities, Educational Buildings, Government Buildings End User: Homeowners, Facility Managers, Property Developers, Contractors, Architects |
| Companies Covered | Hettich Holding GmbH Co. Ohg, Southco Inc., Allegion plc, King Architectural Metals, Hager Companies, Blum Inc., Assa Abloy, Sugatsune Co. Ltd., Hafele GmbH Co. Kg, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Door Hinges Market Strategic Shifts & Innovations
Integration of digital capabilities into traditionally mechanical hardware is reshaping product development. Material science advancements are simultaneously expanding the performance envelope, allowing hinges to function reliably in more demanding physical and digital environments.
Smart hinge technology incorporates embedded sensors to monitor door status, track usage cycles, and control access. The commercial security and healthcare sectors are steadily adopting these solutions to improve building intelligence and safety protocols. This traditional mechanical component is converging with building-wide IoT networks, transforming a simple pivot point into a data-generating asset for facilities management.
The European Union’s Construction Products Regulation (CPR) mandates CE marking for hinges used in fire-rated doors, specifying performance criteria for durability and fire resistance. This regulation increases compliance costs and testing burdens for manufacturers wishing to access the single market. Consequently, the fire door hardware segment is consolidating around suppliers who can document full compliance via accredited third-party testing.
Architectural specification is increasingly bypassing traditional two-step distribution for high-end commercial and residential projects. Design firms now engage directly with manufacturers to source custom-finished or functionally unique hinges, diminishing the role of regional wholesalers for premium hardware. This direct-sourcing model is most advanced in North American and European markets focused on bespoke architectural statements.
Door Hinges Market Segmentation
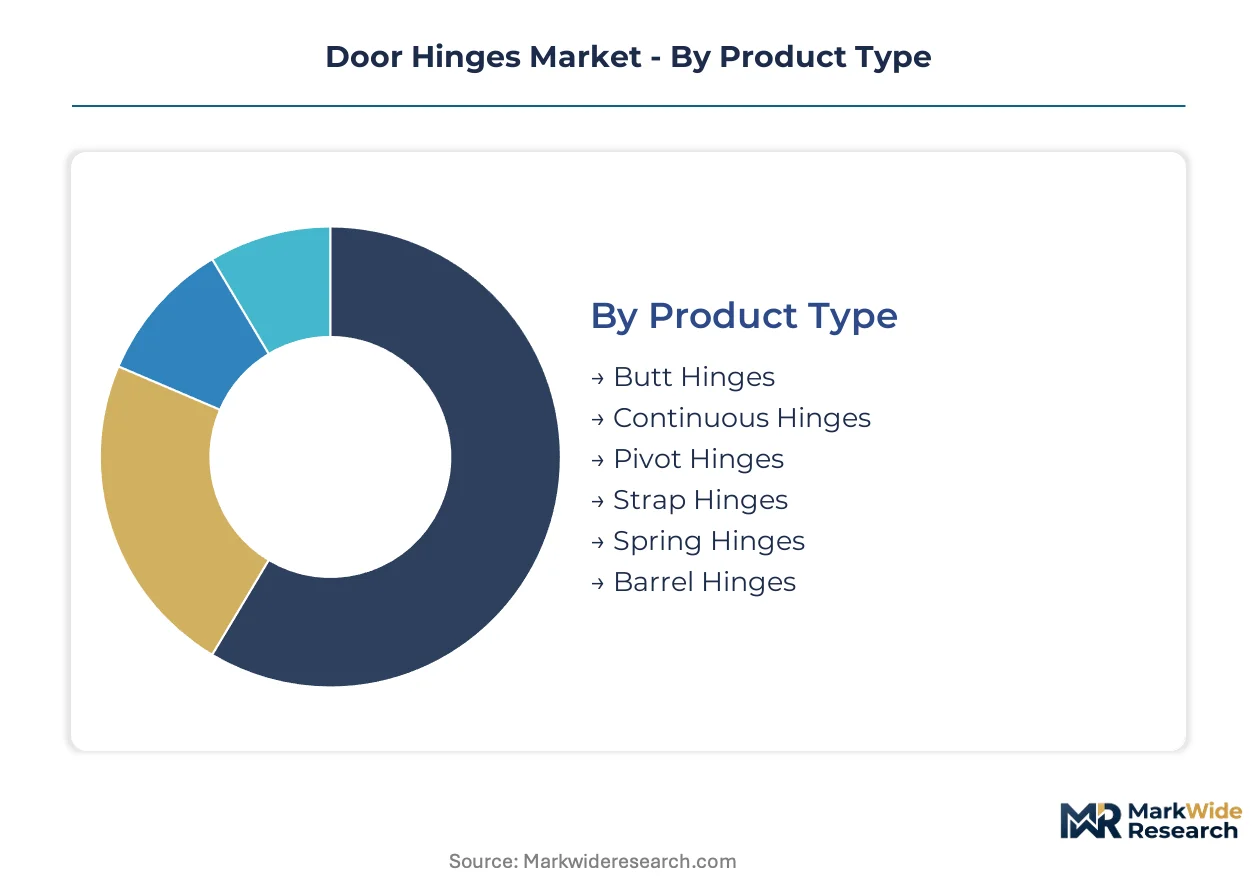
The door hinges market exhibits distinct segmentation across various parameters, reflecting the diverse requirements and applications for these essential mechanical components. Understanding these segments helps stakeholders identify specific opportunities for product development, market penetration, and strategic positioning.
Product Type:
The product type category delineates a clear spectrum from standardized, high-volume hardware to specialized, feature-rich solutions for specific architectural needs.
- Butt Hinges:These are the most common type, featuring two leaves joined by a pin, typically installed flush with the door and frame. Demand concentrates in the general construction sector, supporting high-volume residential and commercial building projects due to their cost-effectiveness.
- Pivot Hinges:Designed to be concealed, these hinges allow a door to pivot from a point at the top and bottom, rather than the side. Demand is significant in architectural and design-led projects, where minimalist aesthetics and unique door functionality are prioritized.
- Continuous Hinges:Also known as piano hinges, these run the full length of the door, distributing weight evenly for heavy or frequently used doors.
- Strap Hinges:Characterized by long leaves that extend across the door face, these hinges provide additional support for heavy gates or rustic-style doors.
- Spring Hinges:These hinges incorporate a spring mechanism to automatically close a door after it has been opened, commonly used in commercial settings and fire doors.
- Barrel Hinges:Small and decorative, barrel hinges are often used for small boxes, cabinets, or light-duty applications where a discreet hinge is desired.
Leading the category by volume: Butt Hinges. Growing fastest: Pivot Hinges.
Material:
Material selection in door hinges often balances durability, aesthetic appeal, and cost, with performance requirements varying significantly across applications.
- Stainless Steel:Composed of iron alloy with a minimum of 10.5% chromium, offering superior corrosion resistance and strength. Demand is high in commercial, coastal residential, and harsh industrial environments due to its resilience against moisture and chemicals.
- Steel:A common and robust material, typically coated for corrosion protection, providing a strong and economical solution for general-purpose applications. Demand is widespread in residential and light commercial construction, valuing its strength and affordability.
- Brass:An alloy of copper and zinc, brass hinges offer a classic aesthetic and good corrosion resistance, often chosen for decorative purposes.
- Aluminum:Lightweight and corrosion-resistant, aluminum hinges are suitable for lighter doors and specific architectural applications where weight is a factor.
- Bronze:An alloy primarily of copper, bronze hinges provide a distinctive appearance and are valued for their durability and resistance to wear in high-traffic areas.
- Zinc Alloy:Often used for more intricate designs or for applications requiring a balance of cost-effectiveness and moderate strength.
The material selection reflects a balance between cost, aesthetic requirements, and functional durability across diverse applications.
Application:
The application segment highlights where door hinges are deployed, emphasizing the specific performance and regulatory demands of different building types.
- Hospitality Facilities:This segment includes hotels, resorts, and convention centers, requiring hinges that meet stringent durability, fire-safety, and aesthetic standards. Demand is accelerating due to a global cycle of new hotel construction and extensive renovation projects.
- Commercial Entrances:Encompassing office buildings, retail stores, and public venues, these applications demand heavy-duty, high-cycle hinges often integrated with access control systems. Demand is driven by the need for enhanced security and robust performance in high-traffic areas.
- Residential Doors:Hinges for residential applications prioritize aesthetics, ease of installation, and basic functionality for interior and exterior doors.
- Institutional Doors:This includes hospitals, laboratories, and correctional facilities, requiring hinges with specific fire ratings, security features, and resistance to heavy use.
- Educational Buildings:Schools and universities utilize hinges that withstand frequent use and contribute to safety and security within campus environments.
- Government Buildings:Public sector facilities require durable and secure hinges, often adhering to specific procurement standards and safety regulations.
Each application dictates specific performance criteria, influencing hinge design and material choice for optimal functionality.
End User:
The end-user category identifies the primary decision-makers or purchasers, influencing distribution channels and product feature priorities.
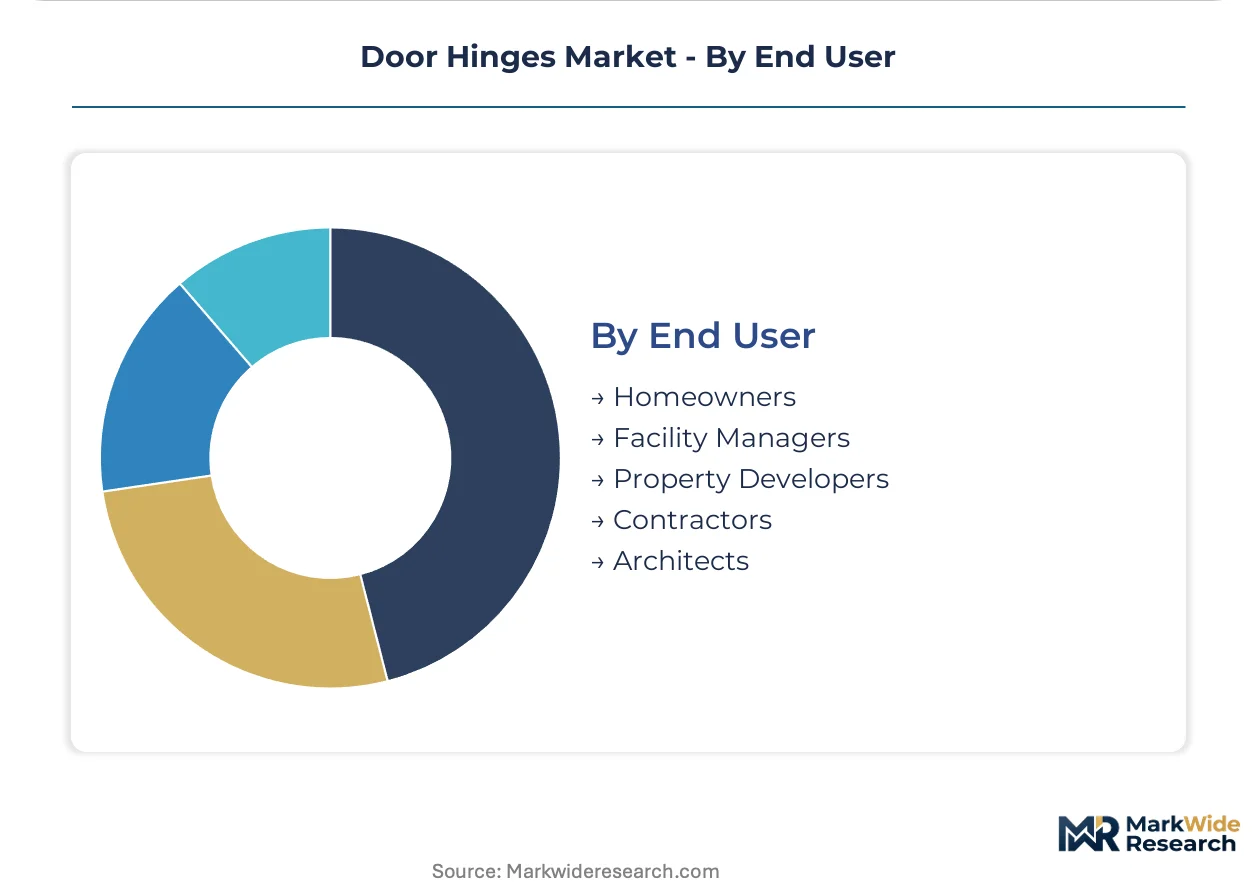
- Architects:These professionals specify hinge types, materials, and finishes based on project design, functionality, and aesthetic requirements. Demand arises from bespoke architectural statements and high-end residential or commercial developments.
- Property Developers:Responsible for planning and constructing large-scale residential, commercial, or mixed-use projects, they procure hinges in volume. Demand is concentrated in new construction initiatives and large-scale renovation projects, prioritizing cost-efficiency and consistent supply.
- Homeowners:Individuals purchasing hinges for personal renovation projects, repairs, or new home construction, often prioritizing aesthetics and ease of installation.
- Facility Managers:Oversee maintenance and upgrades for commercial and institutional buildings, focusing on durability, compliance, and long-term performance.
- Contrators:Install hinges during construction or renovation, seeking reliable products that meet project specifications and budget constraints.
The varied requirements of these end-users drive a fragmented distribution landscape and diverse product offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai's extensive urban development projects and India's national infrastructure initiatives are accelerating demand for door hinges across all grades. This activity positions India as a significant growth hub for both commodity and specialized hardware. Other nations are also contributing to market expansion through their own construction and regulatory frameworks.
India
Government-led infrastructure initiatives like the Smart Cities Mission are driving substantial demand for door hardware in public and commercial buildings. The Bureau of Indian Standards (BIS) mandates specific quality and performance criteria for construction materials, influencing hinge procurement. Residential development in cities such as Bengaluru and Hyderabad further concentrates demand for cost-effective and durable hinge solutions.
United States
Commercial construction and renovation cycles across major metropolitan areas like New York and Los Angeles generate consistent demand for high-performance door hinges. The adoption of ANSI/BHMA A156.1 standards for graded hinges in North American commercial projects pulls demand toward certified products. Specific fire safety codes in states like California further dictate hinge specifications for public buildings.
Germany
The German construction sector, particularly in sustainable building and renovation, requires high-quality and energy-efficient door hardware. CE marking regulations in Europe mandate safety performance for market access, affecting hinge manufacturers. Advanced manufacturing clusters in regions like Baden-Württemberg develop specialized, high-precision hinge systems for architectural and industrial applications.
China
Rapid urbanization and extensive residential construction continue to make China a dominant force in door hinge consumption and production. China's GB standards establish performance and quality benchmarks for domestically produced and imported door hardware. Manufacturing hubs in the Pearl River Delta and Yangtze River Delta are primary sources for high-volume commodity hinges and emerging specialized products.
Vietnam
A growing middle class and increasing foreign direct investment in manufacturing facilities are spurring new construction across Vietnam. The government's focus on improving urban infrastructure and housing drives demand for reliable door hardware. Development in cities like Ho Chi Minh City and Hanoi creates new opportunities for both residential and light commercial hinge suppliers.
Door Hinges Market Key Industry Players
Premium-margin players sit above commodity-margin players across the door hinge market, reflecting distinct value propositions. The market exhibits a tiered structure, with specialists focusing on high-performance solutions and large-scale manufacturers dominating the volume segment. Strategic archetypes include high-security system integrators, design-led component specialists, and mass-market hardware providers. Companies primarily engage in R&D investment for specialized products and capacity expansion for commodity items.
Specialists in advanced security solutions like Assa Abloy occupy a position at the high-end of the market, catering to commercial and institutional needs. Hettich Holding GmbH Co. Ohg, a German-based company, exemplifies expertise in concealed residential hinges, emphasizing design and functionality. Hager Companies, a US-based manufacturer, anchors the scaled production segment by supplying high-volume butt hinges to the general construction sector.
| Leading Market Players |
|---|
| Hettich Holding GmbH Co. Ohg |
| Southco Inc. |
| Allegion plc |
| King Architectural Metals |
| Hager Companies |
| Blum Inc. |
| Assa Abloy |
| Sugatsune Co. Ltd. |
| Hafele GmbH Co. Kg |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps in the door hinges market often dictate specialized product supply behavior, while large conglomerates influence commodity pricing discipline. This tiered ownership structure impacts material sourcing and global distribution strategies.
Pricing Analysis
Value-based pricing for high-performance hinges anchors commercial segment sales, reflecting durability and security features. Price differentiation stems from certified compliance with ANSI/BHMA standards and the aesthetic customization level required for architectural projects. Pricing pressure stems from input material volatility, particularly for steel and brass. Property developers purchasing high-volume butt hinges are the most price-sensitive segment, while architects specifying custom pivot hinges show less sensitivity.
Supply Chain Analysis
Dual-sourcing requirements for critical components are becoming standard practice among large buyers to mitigate risk. Geographic supply concentration for finished hinges centers on China and India, with raw material processing heavily reliant on Asian markets. Key raw material dependencies include stainless steel, brass, and zinc alloys. A structural supply chain risk is logistical bottlenecks, exacerbated by geopolitical friction impacting shipping routes. Distribution runs through a fragmented network of regional wholesalers and direct-to-manufacturer channels for specialized products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The door hinges market is supply-constrained, with specialized coating capacity for corrosion-resistant materials currently propping pricing for high-performance products. This bottleneck underscores the need for strategic investment across the value chain.
For Market Incumbents: Extend product lines into smart hinge technology, integrating embedded sensors for building automation systems. This move mitigates the threat from design-led substitution in high-end segments. Invest in advanced material science R&D for specialized coatings to enhance durability in extreme environments. Acquire specialized regional manufacturers to consolidate market share and control niche product development, leveraging existing certification investments.
For New Entrants and Emerging Players: Capture white-space opportunities in Southeast Asia, particularly in Vietnam and Indonesia, where urbanization drives new residential and light commercial construction. Target the fire door hardware segment by focusing on CE marking compliance and accredited third-party testing. A direct-to-architect go-to-market angle allows bypassing traditional distribution for custom-finished or functionally unique hinges.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap manufacturers with strong intellectual property in specialized coatings or smart hinge technology in Germany. The long-term viability of this market, spanning a 5-10 year window, rests on the shift towards performance-driven specifications and smart building integration. Acquire companies possessing unique mechanical designs or proprietary coating formulas. The signal to watch is the adoption rate of interoperability standards for smart building components.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Smart Hinge Ecosystem | Integrates hinges with IoT networks, transforming a mechanical component into a data-generating asset for facilities management. |
| Invest in Advanced Coating R&D | Expands application possibilities for hinges into marine and chemical processing environments. |
| Acquire Regional Specialists | Consolidates market share and gains access to proprietary designs and specialized manufacturing capabilities. |
| Expand Southeast Asian Manufacturing | Leverages growing construction demand and reduces reliance on single-region supply for commodity products. |
| Pursue CE Marking for Fire Doors | Ensures compliance with European regulations and unlocks access to high-value fire-rated door segments. |
Research Approach
Government reports, industry association data, and company annual filings formed the secondary backbone for this market analysis. Primary research involved interviews with architects, property developers, and facility managers to gather qualitative insights. This approach ensured bottom-up validation of market size estimates and top-down triangulation of growth forecasts.
Historical trendline analysis established the foundational growth trajectory for the door hinges market across the analysis window. Segmentation dimensions modeled included product type, material, application, and end-user, alongside compliance certifications. Compound annual growth rates were derived from a multi-factor regression model incorporating infrastructure spending and hospitality sector investment.
The model holds under current regulatory frameworks and expected material supply stability; deviation in global trade policies or significant technological disruption would shift the outlook materially. Forecasts reflect assumptions regarding construction activity and material pricing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Fiber Cement Board Market
Building & Construction Materials
Roofing Materials Market
Building & Construction Materials
Gulf Corporation Council Cement Market
Building & Construction Materials
Global Steel Wire Rod Market
Building & Construction Materials
Precast Concrete Market
Building & Construction Materials
Steel Bolts and Nuts Market
Building & Construction Materials
North America Concrete Cellulose Fiber Reinforcement Market
Building & Construction Materials
Rebars Market
Building & Construction Materials
Plastic Formwork Market
Building & Construction Materials
Fiberboard Ceiling Market
Building & Construction Materials
Moisture Resistant Gypsum Board Market
Building & Construction Materials
ASEAN Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Decks Market
Building & Construction Materials
Suspended Ceiling Systems Market
Building & Construction Materials
Europe I-Joist Market
Building & Construction Materials
Egypt Prefab Wood Buildings Market