
 Vapor Barriers Market | 2026-2036
Vapor Barriers Market Size, Share, and Industry Trends Forecast 2026-2036
Vapor Barriers Market Analysis
Residential construction procurement is consolidating around national homebuilders with multi-region footprints. BASF SE leverages its polymer chemistry expertise to supply high-performance polyethylene formulations for foundation-grade membranes. Owens Corning anchors its position through integrated building envelope systems that bundle insulation with vapor control layers. Carlisle Companies competes on roofing application dominance, extending its TPO membrane technology into compatible vapor retarder products.
Vapor barriers are synthetic membranes, typically manufactured from polyethylene, polypropylene, or bituminous compounds, engineered to achieve permeance ratings below 1.0 perm to block moisture vapor diffusion through building assemblies. Polyethylene sheeting dominates basement and foundation installations due to its low cost and established ASTM E1745 compliance for underslab applications. Liquid-applied systems command premium positioning in complex roof geometries where sheet goods cannot achieve continuous coverage without seams. Self-adhesive membranes represent the fastest-growing installation method as contractors prioritize labor efficiency and reduced reliance on mechanical fastening in tight envelope designs.
The EPA radon resistance standards and IRC Section R406 moisture protection requirements shape product specifications across US residential construction, while OSHA silica exposure rules during installation push contractors toward pre-manufactured sheet solutions. ASTM E96 and ASTM E2178 testing protocols determine permeance classifications that separate Class I vapor retarders from breathable Class III materials, directly influencing material selection by climate zone. Stakeholders must monitor evolving building code adoptions of continuous insulation requirements that redefine where vapor control layers sit within wall assemblies.
Market Dynamics
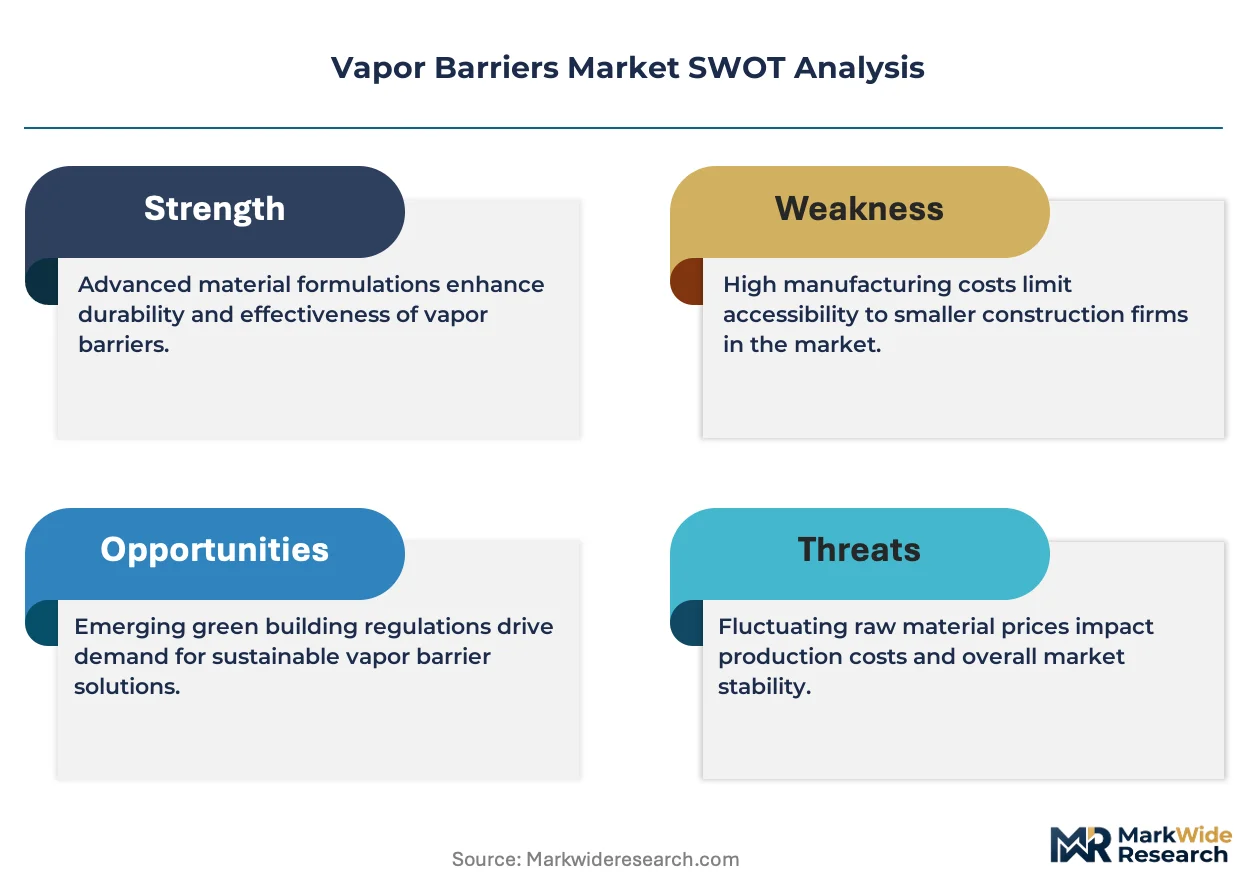
Building code adoptions of continuous insulation requirements are forcing vapor control layer repositioning within wall assemblies, compressing traditional installation methods and rewiring contractor specification habits across climate zones.
Growth Catalysts
- IRC Section R406:US moisture protection mandates in residential construction drive specification of ASTM E1745-compliant underslab membranes for basement and foundation applications.
- Self-adhesive installation technology:Labor efficiency gains in tight envelope designs accelerate contractor migration away from mechanical fastening toward peel-and-stick membrane systems.
- Slab-on-grade construction concentration:Single-family housing patterns in the United States concentrate demand for foundation-grade polyethylene sheeting in new residential builds.
Market Restraints
- Petrochemical feedstock volatility:Polyethylene and polypropylene resin prices fluctuate with crude oil markets, compressing margin stability for membrane manufacturers.
- Sheet goods technical limitation:Complex roof geometries resist continuous coverage without seams, ceding share to liquid-applied alternatives in premium positioning.
- OSHA silica exposure rules:Installation site regulations push contractors toward pre-manufactured sheet solutions but add compliance documentation burden.
Strategic Opportunities
- EPA radon mitigation standards:Certified membrane system requirements create specification pull-through for high-performance vapor retarders in residential basement retrofits.
- Liquid-applied technology convergence:Hybrid formulations combining spray polyurethane foam with integrated vapor control layers capture complex commercial envelope projects.
- Climate zone 5-8 underpenetration:Cold-weather US regions with stringent continuous insulation codes show lagging adoption of Class I vapor retarders in wall assemblies.
Industry Challenges
- ASTM E96/E2178 certification timelines:Permeance classification testing delays product launches and locks out regional membrane suppliers from specification shortlists.
- Building envelope integration complexity:Vapor barrier coordination with air barriers, water-resistive barriers, and insulation layers demands specialized contractor training.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vapor Barriers Market |
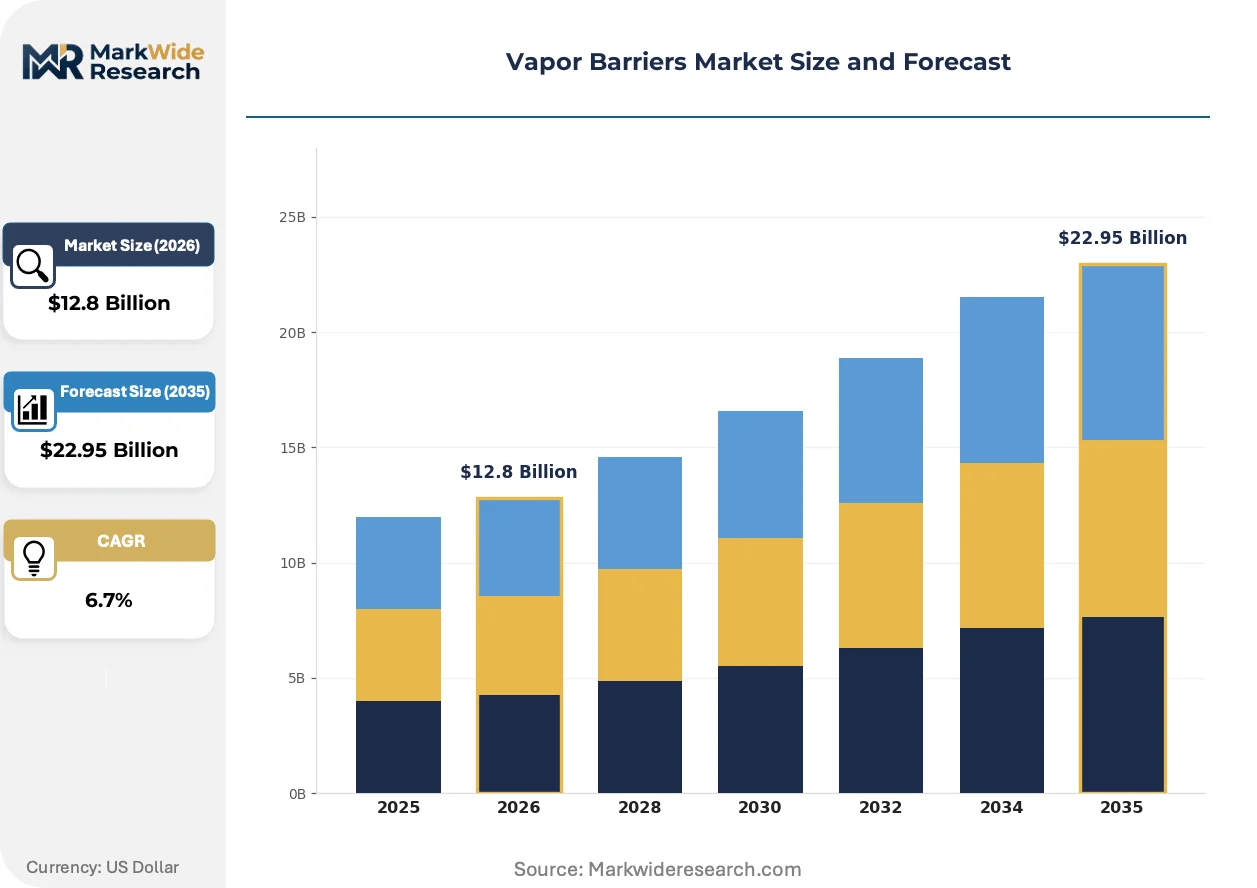
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Asphalt, EPDM Application: Basements, Roofs, Walls, Foundations Installation Method: Self-Adhesive, Mechanically Fastened, Liquid Applied, Rolled End User: Construction, Manufacturing, Residential, Commercial |
| Companies Covered | BASF SE, DuPont de Nemours, Carlisle Companies, CertainTeed Corporation, Sika AG, Owens Corning, 3M Company, Honeywell, GAF Materials LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vapor Barriers Market Emerging Trajectories
Material science advances and regulatory precision are compressing traditional product categories while elevating performance thresholds. Installation method innovation and specification science now determine competitive position more than raw material cost.
Multi-layer coextruded polyethylene membranes with integrated reinforcement scrim are overtaking commodity 6-mil sheeting in residential foundation applications. High-volume homebuilders in the United States specify these engineered films for improved puncture resistance during concrete placement. The technology is overtaking price-driven procurement models by embedding durability guarantees into standard specifications.
REACH restrictions on phthalate plasticizers in European construction materials force reformulation of flexible polyvinyl chloride vapor retarders. Membrane manufacturers serving EU markets accelerate migration to bio-based plasticizers and non-PVC alternatives. Commercial roofing contractors in Germany and France face compressed product availability windows as legacy formulations exit distribution channels.
Single-source envelope procurement contracts now bundle insulation, vapor control, and air sealing under integrated building envelope system agreements. National homebuilders consolidate supplier relationships around manufacturers offering multi-product portfolios. The pattern concentrates specification authority with polymer chemistry specialists capable of cross-category performance guarantees.
Vapor Barriers Market Segmentation
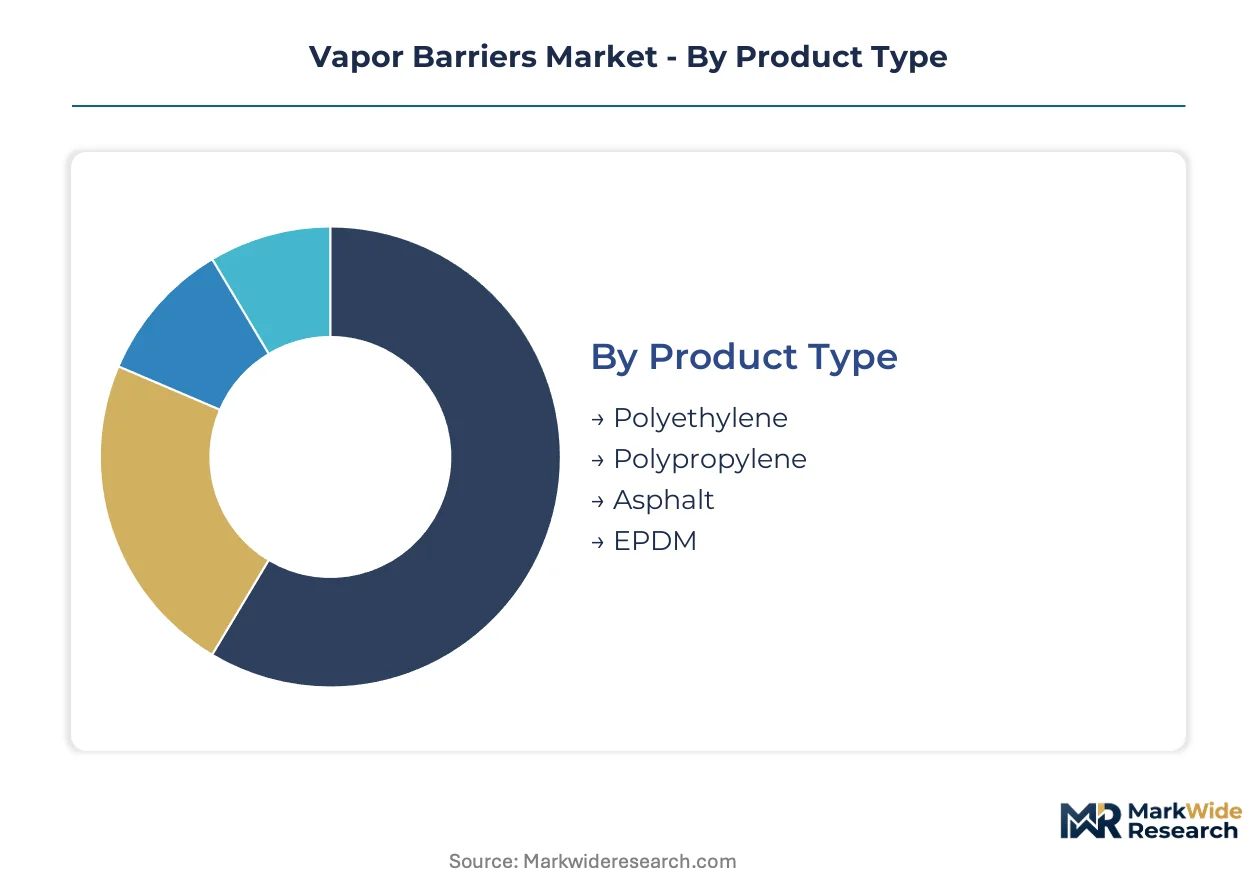
Material composition and installation technology define competitive positioning in vapor barrier procurement. Specification decisions cascade from climate zone requirements through contractor labor economics to end-use performance demands.
Product Type:
Polymer chemistry and bituminous formulations separate commodity from engineered membrane tiers.
- Polyethylene:Low-density and high-density formulations dominate residential foundation applications through ASTM E1745 underslab compliance. US single-family builders specify multi-layer coextruded grades with reinforcement scrim for puncture resistance during concrete placement.
- Polypropylene:Woven and non-woven geotextile composites command premium positioning in commercial roofing assemblies requiring dimensional stability across temperature extremes. German and French contractors face compressed availability of legacy PVC-flexible alternatives under REACH phthalate restrictions.
- Asphalt:Bituminous compounds serve below-grade waterproofing where self-healing properties accommodate minor substrate movement.
- EPDM:Synthetic rubber membranes anchor commercial roofing vapor control in thermally demanding envelope designs.
Polyethylene leads on scale; polypropylene leads on momentum.
Application:
Building assembly location determines permeance rating requirements and regulatory jurisdiction.
- Basements:Underslab and interior wall installations drive the largest volume concentration per the report's residential construction focus. IRC Section R406 moisture protection mandates and EPA radon mitigation standards shape US specification patterns for foundation-grade membranes.
- Roofs:Complex geometries in commercial construction cede share from sheet goods to liquid-applied alternatives where seam elimination proves critical. German roofing contractors bundle TPO-compatible vapor retarders with single-ply membrane systems.
- Walls:Continuous insulation code adoptions in US Climate Zones 5-8 reposition vapor control layer placement, compressing traditional installation sequences.
- Foundations:Slab-on-grade construction concentration in US residential markets concentrates polyethylene sheeting demand for ground-contact moisture blocking.
Basements lead on scale; walls lead on momentum.
Installation Method:
Labor efficiency and envelope tightness requirements are reshaping contractor technology preferences.
- Self-Adhesive:Peel-and-stick membrane systems are expanding most quickly as contractors eliminate mechanical fastening in tight envelope designs. Reduced installation time and improved seam integrity drive specification migration in US residential and commercial sectors.
- Mechanically Fastened:Traditional fastening persists in large-format commercial roofing where substrate conditions accommodate mechanical anchors. OSHA silica exposure rules add compliance documentation burden to site-applied solutions.
- Liquid Applied:Spray and roller-applied systems capture complex geometries in premium commercial envelopes where sheet goods cannot achieve continuous coverage. Hybrid formulations integrating spray polyurethane foam with vapor control layers target high-performance commercial projects.
- Rolled:Conventional sheet goods deployment dominates cost-sensitive residential basements through established contractor training and material availability.
Self-adhesive leads on momentum; mechanically fastened leads on current scale.
End User:
Procurement consolidation patterns separate volume-driven from specification-driven demand segments.
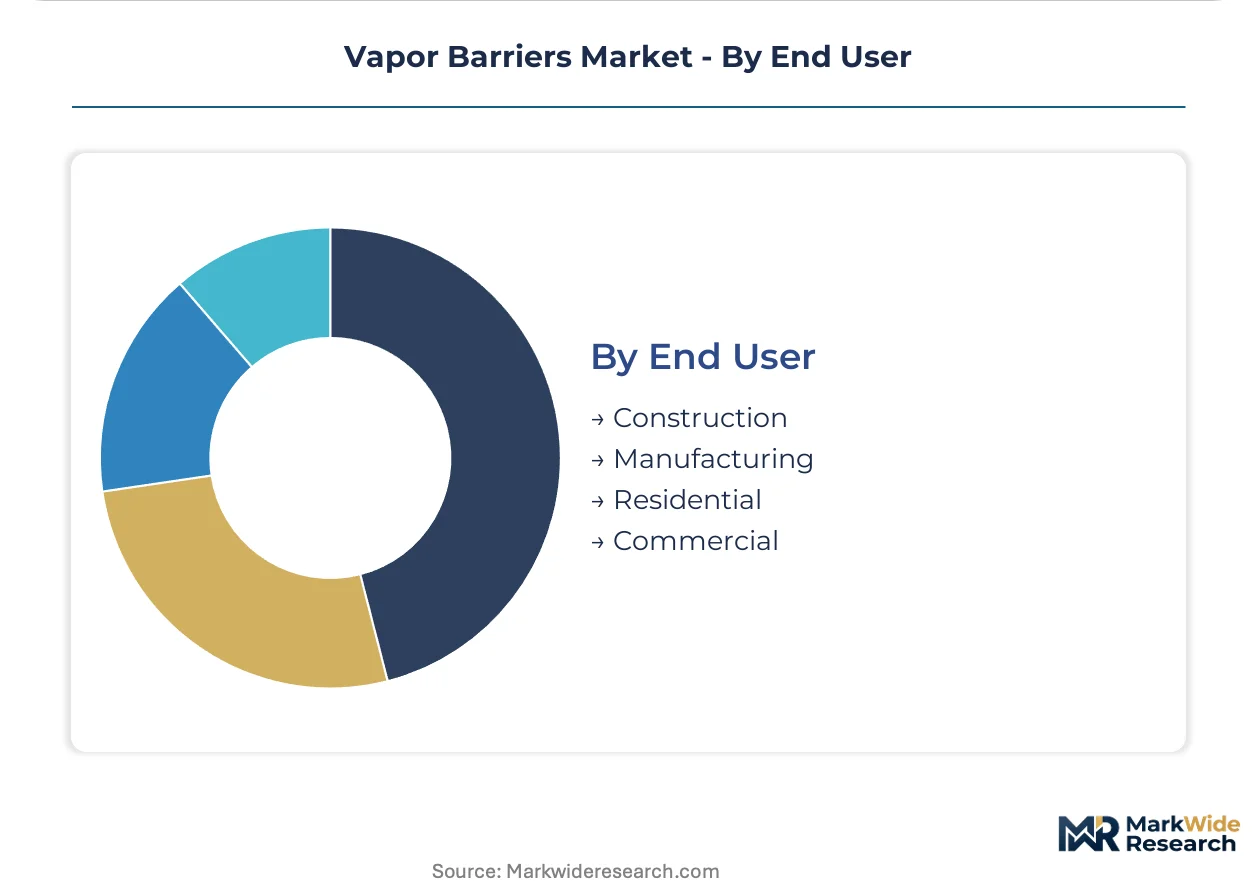
- Construction:General contracting and specialty envelope trades represent the dominant demand channel. National US homebuilders consolidate supplier relationships around integrated building envelope system agreements bundling insulation, vapor control, and air sealing.
- Manufacturing:Prefabricated building component producers specify membrane systems for factory-controlled assembly environments. Quality assurance protocols favor pre-certified Class I vapor retarders with documented ASTM E96/E2178 permeance ratings.
- Residential:Single-family and multifamily construction concentrates in US markets with slab-on-grade foundation prevalence. Moisture damage risk awareness drives homeowner investment in basement retrofit applications.
- Commercial:Office, retail, and institutional projects demand engineered membrane systems with extended performance guarantees. Complex roof geometries and continuous insulation requirements elevate specification sophistication.
Construction leads on scale; residential leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled polymer chemists and building envelope specialists concentrate in industrial clusters across the United States, Germany, China, Japan, and Canada. These talent pools anchor membrane formulation expertise and installation technology development. Regional demand patterns diverge sharply based on construction methods, regulatory frameworks, and climate-driven building code requirements.
United States
Slab-on-grade foundation prevalence in single-family housing concentrates polyethylene sheeting demand in new residential construction. IRC Section R406 moisture protection mandates and EPA radon mitigation standards shape specification patterns for ASTM E1745-compliant underslab membranes. The Southeast and Southwest construction corridors drive volume procurement through national homebuilder consolidation.
Germany
Commercial roofing contractors face compressed availability of legacy PVC-flexible vapor retarders under REACH phthalate restrictions. ECHA regulatory pressure accelerates manufacturer migration to bio-based plasticizers and non-PVC alternatives. The Rhine-Ruhr industrial cluster anchors polypropylene membrane production for thermally demanding envelope designs.
China
Rapid urbanization and basement waterproofing retrofits in older residential stock drive membrane consumption in high-humidity coastal provinces. GB standards for building waterproofing establish permeance classification requirements that parallel ASTM protocols. The Yangtze River Delta manufacturing corridor supplies both domestic construction and export markets with polyethylene and bituminous formulations.
Japan
Seismic-resistant building designs elevate demand for flexible membrane systems accommodating structural movement. METI energy efficiency guidelines for commercial buildings tighten envelope performance requirements. The Kanto region around Tokyo concentrates specialty contractor expertise in complex roof geometries where liquid-applied systems displace sheet goods.
Canada
Cold climate construction in Climate Zones 5-8 elevates specification sophistication for continuous insulation and vapor control layer integration. Health Canada building code adoptions push toward Class I vapor retarders in wall assemblies. The Greater Toronto Area anchors distribution networks serving prairie and maritime provinces with foundation-grade membrane systems.
Vapor Barriers Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across material formulation and installation technology tiers. The vendor base organizes around three strategic archetypes: integrated building materials conglomerates with multi-product portfolios, polymer chemistry specialists leveraging resin expertise, and regional membrane fabricators serving cost-sensitive segments. Dominant competitive moves include strategic partnerships bundling insulation with vapor control layers and geographic expansion through distribution network acquisition.
Among integrated building materials conglomerates, BASF SE and Owens Corning occupy positions exemplifying polymer chemistry leverage and building envelope system integration respectively. Sika AG represents the specialty chemicals archetype with membrane technology extending from roofing into compatible vapor retarder applications. These three anchors illustrate how competitive positioning depends on cross-category performance guarantees and contractor specification authority consolidation.
| Leading Market Players |
|---|
| BASF SE |
| DuPont de Nemours |
| Carlisle Companies |
| CertainTeed Corporation |
| Sika AG |
| Owens Corning |
| 3M Company |
| Honeywell |
| GAF Materials LLC |
| Others |
Supply Flow & Price Mechanics
National homebuilder consolidation around multi-product procurement contracts is compressing supplier margins while rewarding polymer chemistry specialists with cross-category bundling capabilities. ASTM E1745 certification requirements for underslab membranes create specification stickiness that insulates compliant manufacturers from pure price competition.
Pricing Analysis
Capacity additions in the Yangtze River Delta manufacturing corridor are reshaping price floors for polyethylene sheeting exports to North American residential markets. Three-tier pricing structure across premium engineered films, standard multi-layer coextruded grades, and commodity 6-mil sheeting separates ASTM E96 Class I vapor retarders from breathable Class III alternatives. Cost compression in commodity tiers is intensifying because petrochemical feedstock volatility feeds directly into resin cost pass-through mechanisms. Regional membrane fabricators serving cost-sensitive basement retrofit segments exhibit highest price sensitivity, while commercial roofing contractors specifying TPO-compatible systems show lowest.
Supply Chain Analysis
Regional distribution centers in the Greater Toronto Area and Southeast United States operate hub-and-spoke patterns serving national homebuilder networks with foundation-grade membrane systems. Manufacturing concentration spans China, Germany, and the United States, with the Rhine-Ruhr cluster anchoring polypropylene production and the Yangtze Delta supplying polyethylene formulations. Raw material dependencies draw from crude oil derivatives, reinforcement scrim textiles, and adhesive polymer compounds. Single-source vulnerability around phthalate plasticizer alternatives under REACH restrictions threatens European supply continuity. Distribution runs through building materials wholesalers and direct-to-contractor channels serving envelope specialty trades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vapor barriers market functions as a geographic-arbitrage play where REACH-driven formulation costs in Germany exceed US regulatory compliance burdens, creating margin expansion opportunities for North American exporters serving EU commercial roofing demand.
For Market Incumbents: Hedge petrochemical feedstock exposure through backward integration into resin production or long-term offtake agreements with Gulf Coast polyethylene producers. BASF SE and Owens Corning should deepen captive supply of high-density polyethylene grades to offset margin compression from crude oil volatility. Certification investment in ASTM E2178 testing protocols locks regional competitors out of specification shortlists for Climate Zone 5-8 wall assembly projects. For New Entrants and Emerging Players: Specialty roofing distributors represent the most accessible channel partner type for penetrating liquid-applied vapor control segments in complex commercial geometries. White-space targets include US Climate Zones 5-8 wall assembly retrofits where continuous insulation code adoptions lag Class I vapor retarder adoption, and Japanese seismic-resistant envelope projects demanding flexible membrane systems. A go-to-market angle bundling spray polyurethane foam with integrated vapor control layers captures high-performance commercial projects from incumbent sheet goods suppliers. For Investors and Strategic Acquirers: Asymmetric upside sits with polymer chemistry specialists possessing ASTM E96/E2178 certification infrastructure and multi-product building envelope portfolios. Long-term viability favors manufacturers with demonstrated cross-category performance guarantees spanning insulation, air sealing, and vapor control layers. Acquisition target archetypes include regional membrane fabricators in the US Southeast with established national homebuilder relationships. The signal to watch is EPA radon mitigation standard enforcement intensity in residential basement retrofits, which would accelerate specification pull-through for certified membrane systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Gulf Coast polyethylene capacity anchors margin stability against crude oil volatility. |
| ASTM E2178 Certification Investment | Testing protocol compliance locks out regional suppliers from Climate Zone 5-8 specifications. |
| Liquid-Applied Technology Convergence | Hybrid spray foam formulations capture complex commercial roof geometries from sheet goods. |
| Regional Distribution Network Acquisition | Hub-and-spoke coverage in Greater Toronto Area penetrates Canadian Climate Zone 5-8 demand. |
| REACH-Compliant Formulation Migration | Bio-based plasticizer alternatives secure EU commercial roofing channel access. |
Methodological Framework
Coverage spans the United States, Germany, China, Japan, and Canada, with primary inputs from each market's construction and polymer chemistry clusters. The analysis combines primary interviews with envelope specialty contractors, national homebuilder procurement directors, polymer plant managers, and commercial roofing distributors with secondary validation from ASTM International standards documentation, EPA radon mitigation guidelines, ECHA REACH restriction notices, and building code adoption records. Bottom-up and top-down triangulation cross-validates membrane volume estimates against resin production data and construction permit flows.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include material composition tier, installation technology, building assembly location, and climate zone regulatory cluster. CAGRs derive from regression analysis of historical construction activity correlated with code adoption timelines and membrane specification penetration curves. Industry-specific forecast inputs incorporate IRC Section R406 enforcement trajectories and continuous insulation code adoption patterns in US Climate Zones 5-8.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to petrochemical feedstock volatility, REACH regulatory expansion, and OSHA silica exposure rule enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Gulf Corporation Council Cement Market
Building & Construction Materials
PU Roof Window Market
Building & Construction Materials
Construction Bolts Market
Building & Construction Materials
Advanced Building Materials Market
Building & Construction Materials
Steel Bolts and Nuts Market
Building & Construction Materials
France Oriented Strand Board Market
Building & Construction Materials
Building and Construction Sealants Market
Building & Construction Materials
Sawn and Profiled Wood Products Market
Building & Construction Materials
Architectural Membrane Market
Building & Construction Materials
Risers Market
Building & Construction Materials
Travertine Market
Building & Construction Materials
US Windows Market
Building & Construction Materials
Technical Insulation Market
Building & Construction Materials
Construction Aggregates Market
Building & Construction Materials
Elevated Water Storage Tanks Market
Building & Construction Materials
Corrugated Polycarbonate Panels Market