
 Architectural Window Films Market | 2026-2036
Architectural Window Films Market Size, Share, and Industry Trends Forecast 2026-2036
Architectural Window Films Market Analysis
Performance-based warranty and maintenance contracts is pivoting how architectural window films are monetized beyond the initial install. 3M Company leverages its multi-layer sputtering expertise to sustain premium positioning in solar control specifications. Eastman Chemical Company anchors North American supply through captive PET resin production and vertically integrated coating lines. SAINT-GOBAIN competes on building-systems integration, bundling window films with its glass and facade portfolios.
Architectural window films are thin, optically engineered polymer laminates, typically PET-based with metalized or ceramic interference coatings, applied to glazing surfaces to modulate solar heat gain, ultraviolet transmission, and visible light distribution. The primary purpose is to reduce HVAC energy loads while preserving daylighting performance in commercial and residential envelopes. Solar control films command the largest installed base due to payback-driven retrofit economics in existing commercial stock, while decorative films capture expanding margin pools from hospitality and retail interior branding. Safety and privacy films represent faster-growing niches as building security standards tighten and open-plan layouts proliferate.
The US Department of Energy's building energy codes and the EU Green Deal's renovation wave requirements are mandating lower solar heat gain coefficients, directly expanding qualified film specifications. REACH compliance in Europe and state-level Title 24 extensions in California govern adhesive chemistry and installation practices, shaping product development roadmaps. Stakeholders must monitor how evolving dynamic glazing technologies and electrochromic alternatives alter the retrofit-versus-replace calculus for energy-conscious building owners.
Market Dynamics
Building energy codes in the United States, Germany, and China are tightening thermal performance thresholds faster than glazing replacement cycles, forcing specification of retrofit-compatible solar control films over full window replacement.
Growth Catalysts
- EU Green Deal renovation mandates:The EU Green Deal's binding renovation wave targets are compelling commercial building owners to install solar control films to meet solar heat gain coefficient requirements without structural envelope work.
- California Title 24 extensions:California's progressive building energy code extensions are mandating lower HVAC loads in existing commercial stock, directly expanding qualified film specifications across retail and office retrofits.
- Green building certification intensity:LEED and BREEAM specification rates concentrate in the United States and United Kingdom, where certification-driven procurement favors documented energy-performance improvements from window film retrofits.
Market Restraints
- PET resin supply concentration:Captive production of optical-grade PET resin concentrates among integrated chemical producers, creating input cost volatility for independent film coaters without backward integration.
- Electrochromic glazing substitution:Dynamic glazing technologies with switchable tint properties threaten solar control film retrofits in premium commercial new-builds where capital budgets accommodate higher first costs.
- REACH adhesive compliance friction:ECHA registration requirements for pressure-sensitive adhesive chemistry are extending product development timelines and reformulation costs for European market entry.
Strategic Opportunities
- India commercial building stock:Underpenetrated installation rates in India's rapidly expanding office and hospitality sectors present white space for solar control and decorative film specification as BIS energy codes mature.
- Safety-security film bundling:Building security standards tightening in Germany and France are creating demand convergence for blast-mitigation and solar-control dual-function films in institutional applications.
- Smart film-electronics convergence:Integration of transparent conductive oxide layers with traditional solar control stacks is enabling switchable film prototypes that bridge static retrofit and dynamic glazing categories.
Industry Challenges
- Certified installer scarcity:NFRC and IWFA certification requirements for warranty-eligible installation are creating bottlenecks as retrofit demand outpaces qualified technician training programs.
- Multi-layer sputtering capex intensity:Precision vacuum deposition equipment for ceramic interference coatings demands capital commitments that fragment competitive capability between integrated producers and toll coaters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Architectural Window Films Market |
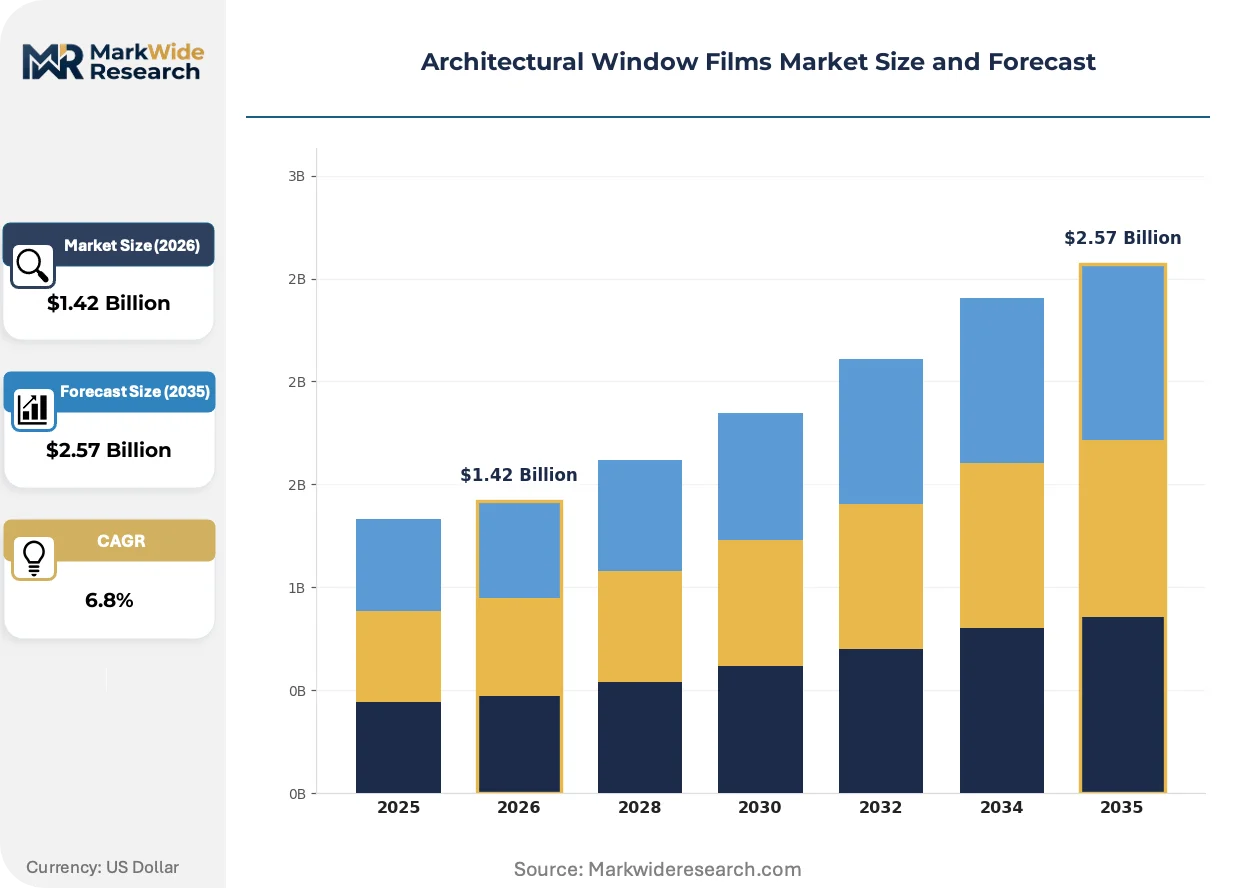
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar Control Films, Decorative Films, Safety Films, Privacy Films Application: Commercial Buildings, Residential Properties, Institutional Facilities, Automotive Film Material: PET, Polycarbonate, Vinyl, Glass Installation Type: Adhesive Films, Non-Adhesive Films, DIY Solutions, Professional Installation |
| Companies Covered | 3M Company, Eastman Chemical Company, SAINT-GOBAIN, Madico, Inc., Avery Dennison Corporation, Garware Suncontrol, Lintec Corporation, Toray Plastics, Solar Control Films, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Architectural Window Films Market Emerging Trajectories
Material science advances in nanoceramic and spectrally selective coatings are compressing the performance gap between retrofit films and replacement glazing, while digital specification tools are compressing procurement cycles.
Nanoceramic interference coatings are replacing traditional metalized layers in premium solar control specifications. Hospitality and healthcare facility managers specify these films for their neutral aesthetic and maintained radio frequency transparency. The technology is integrating with building management system data streams to enable real-time performance monitoring and predictive maintenance scheduling.
REACH chemical registration requirements are extending adhesive chemistry disclosure obligations across European supply chains. Film manufacturers must document full substance inventories for pressure-sensitive layers, compressing formulation flexibility and extending new product introduction timelines. German commercial distributors are responding by consolidating supplier bases to reduce compliance audit burden.
Facility managers are unbundling installation from product supply, demanding direct relationships with certified applicator networks separate from manufacturer channels. This pattern concentrates in United States commercial retrofits where national account procurement teams seek transparent labor pricing and localized service response. Manufacturer-direct specification support is displacing traditional distribution intermediaries in large-roll project business.
Architectural Window Films Market Segmentation
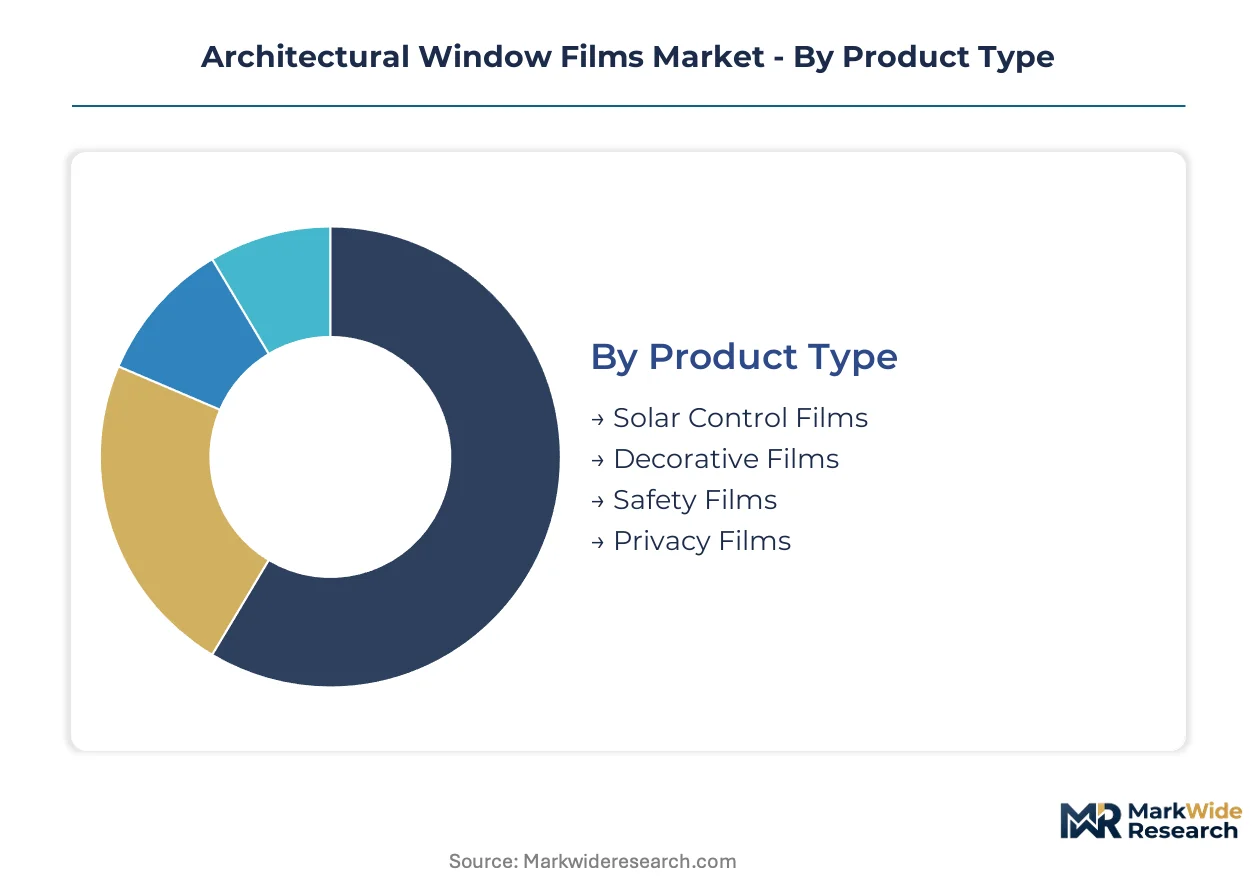
Architectural window films fragment across material chemistry, functional specification, and installation complexity. Each segment carries distinct margin profiles, certification requirements, and retrofit economics that shape procurement patterns across building types.
Product Type:
Supply concentration in multi-layer sputtering equipment favors integrated producers with captive coating lines, concentrating premium specification capability among chemical majors with backward PET integration.
- Solar Control Films:Metalized or ceramic interference coatings on PET substrates modulate solar heat gain coefficients. Demand concentrates in United States commercial retrofits where Title 24 extensions mandate HVAC load reductions without structural envelope work.
- Decorative Films:Dyed or patterned polymer laminates enable interior branding and visual privacy. Hospitality and retail sectors in Germany specify these films for aesthetic differentiation under tighter EU Green Deal renovation timelines.
- Safety Films:Thick, tear-resistant PET constructions provide blast mitigation and glass retention. Institutional applications in France drive specification as building security standards tighten.
- Privacy Films:Frosted or one-way mirror coatings obscure sightlines while transmitting daylight. Open-plan office layouts in China expand installation rates as commercial stock modernizes.
Solar control films absorb the bulk of installed capacity; decorative films are expanding most quickly.
Application:
Cost tier stratification separates premium specification in certified green buildings from economy retrofit projects competing on payback period alone.
- Commercial Buildings:Office, retail, and hospitality envelopes dominate retrofit volume. LEED and BREEAM procurement in the United States and United Kingdom favors documented energy-performance improvements from qualified film installations.
- Residential Properties:Single-family and multifamily retrofits concentrate in climate zones with extreme cooling loads. California's progressive energy codes extend mandate coverage to existing residential stock.
- Institutional Facilities:Schools, hospitals, and government buildings specify dual-function safety-solar films. Germany and France lead blast-mitigation requirements for public infrastructure.
- Automotive:Aftermarket tinting and OEM specifications utilize thinner-gauge constructions with distinct optical clarity standards. Regulatory fragmentation across national type-approval regimes shapes product roadmaps.
Commercial buildings absorb the bulk of installed capacity; institutional facilities are climbing the fastest on security-driven specification.
Film Material:
Volume concentration in optical-grade PET resin production creates input cost leverage for integrated chemical producers over independent toll coaters.
- PET:Biaxially oriented polyethylene terephthalate dominates architectural specifications for dimensional stability and optical clarity. Captive resin production at Eastman Chemical and similar integrated producers anchors North American supply security.
- Polycarbonate:Impact-resistant thermoplastics serve safety-critical applications requiring structural integrity beyond PET capabilities. Premium pricing reflects specialty polymer supply constraints.
- Vinyl:PVC-based films compete in economy decorative and short-lifecycle applications. REACH compliance friction in Europe compresses formulation flexibility for pressure-sensitive adhesive layers.
- Glass:Thin glass laminates enable highest-temperature specifications and chemical resistance. Niche penetration reflects handling complexity and installation cost premiums.
PET absorbs the bulk of installed capacity; polycarbonate is gaining share fastest on safety specification intensity.
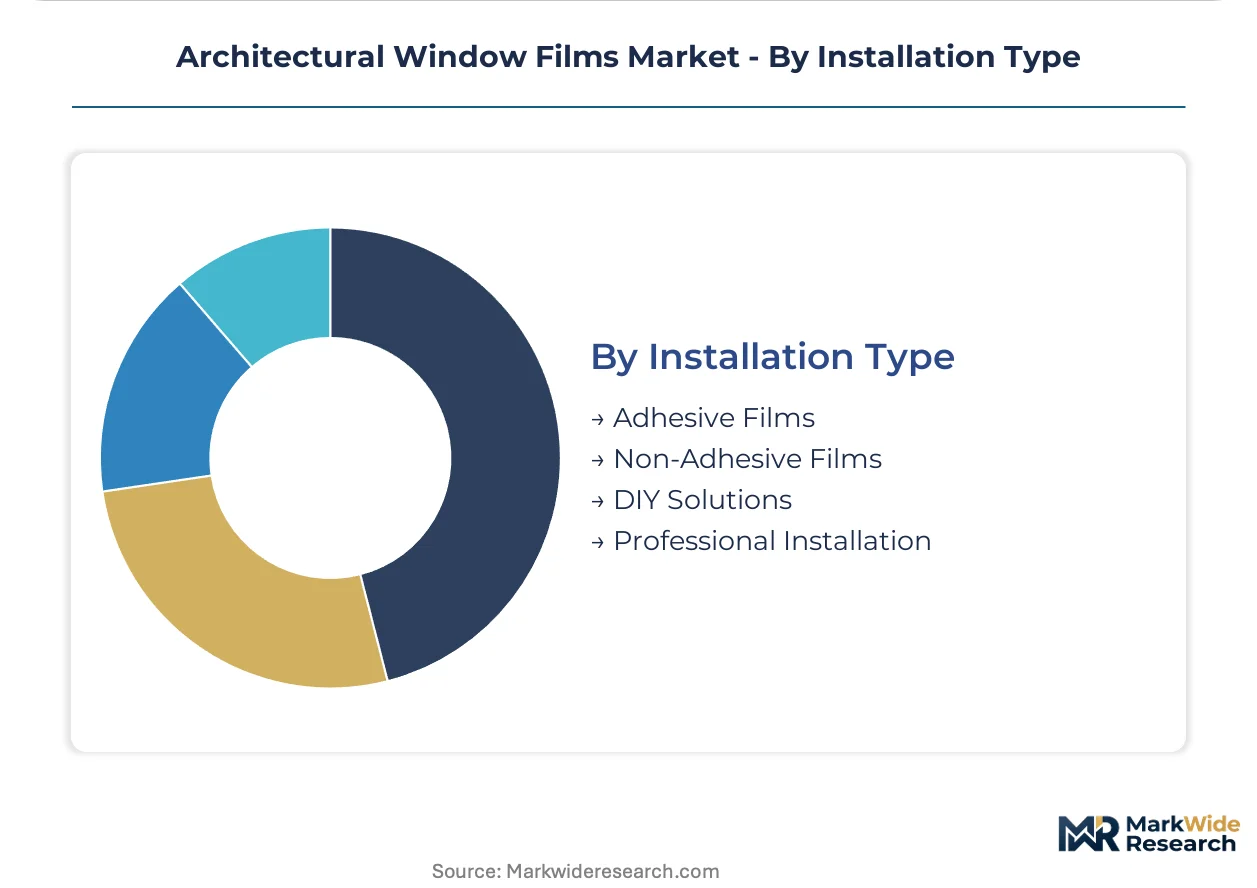
Installation Type:
Customer type stratification separates national account procurement teams seeking transparent labor pricing from residential consumers prioritizing convenience.
- Adhesive Films:Pressure-sensitive layers enable retrofit application to existing glazing without structural modification. NFRC and IWFA certification requirements for warranty eligibility concentrate qualified installer capability in the United States.
- Non-Adhesive Films:Static-cling or mechanical attachment systems allow removal and repositioning. Rental properties and temporary installations in Germany favor this flexibility under tenant protection regulations.
- DIY Solutions:Pre-cut kits and consumer-grade adhesives serve residential aftermarket channels. Quality variance creates reputation risk for manufacturers without installation control.
- Professional Installation:Certified applicator networks deliver warranty-backed performance documentation. Facility managers in the United States unbundle this service from product supply to secure localized response capability.
Adhesive films absorb the bulk of installed capacity; professional installation is expanding most quickly on certification and warranty requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates among integrated chemical producers in the United States, Germany, and Japan, while consumption tilts toward retrofit-intensive commercial building stocks in North America and Europe. This geographic split shapes trade flows and regional pricing structures.
United States
Commercial building retrofits in California, Texas, and New York Metro drive specification intensity. Title 24 extensions mandate lower HVAC loads in existing stock, compelling facility managers toward solar control film installations. Los Angeles and Dallas-Fort Worth clusters concentrate certified installer networks serving national account procurement teams.
Germany
EU Green Deal renovation wave targets compress payback thresholds for energy-efficiency investments. REACH compliance requirements extend adhesive chemistry disclosure obligations across supply chains. The Rhine-Ruhr and Munich metropolitan areas anchor specification activity for dual-function safety-solar films in institutional applications.
China
Rapid commercial stock expansion in Shanghai, Beijing, and Shenzhen creates retrofit demand alongside new-build specification. GB standards for building energy efficiency tighten thermal performance requirements in major municipalities. Yangtze River Delta manufacturing clusters supply optical-grade PET resin to domestic coating operations.
India
Underpenetrated installation rates in office and hospitality sectors present white space as BIS energy codes mature. Commercial construction in Mumbai, Bangalore, and Delhi-NCR expands qualified project pipelines. Maharashtra and Karnataka states concentrate distributor networks targeting green building certification programs.
United Kingdom
BREEAM procurement standards in London and Southeast England favor documented energy-performance improvements. Building security standards tightening in government and transport infrastructure expand safety film specifications. The Midlands and North England clusters develop installer training capacity to match retrofit demand growth.
Architectural Window Films Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across distinct capability tiers. Integrated chemical majors with captive PET resin production and in-house coating lines command premium specification channels. Independent toll coaters and regional fabricators compete on retrofit project economics and localized service response. Three archetypes dominate: backward-integrated resin-to-film producers, technology-licensed regional coaters, and installation-centric service bundlers. Competitive moves concentrate on M&A for coating asset consolidation and strategic partnerships bridging film supply with certified applicator networks.
Among North American integrated producers, 3M Company and Eastman Chemical Company exemplify the resin-captive archetype with multi-layer sputtering expertise. SAINT-GOBAIN represents the building-systems integrator model, bundling film offerings with glass and facade portfolios. These three anchors demonstrate how competitive positioning splits between materials science depth and construction channel access.
| Leading Market Players |
|---|
| 3M Company |
| Eastman Chemical Company |
| SAINT-GOBAIN |
| Madico, Inc. |
| Avery Dennison Corporation |
| Garware Suncontrol |
| Lintec Corporation |
| Toray Plastics |
| Solar Control Films |
| Others |
Supply Flow & Price Mechanics
Facility manager unbundling of installation from product supply in the United States is forcing manufacturers to restructure channel economics and compress margin structures across adhesive film tiers.
Pricing Analysis
Margin tightening in economy-grade decorative films traces to REACH adhesive compliance costs extending European product development timelines. Three-tier pricing structure across premium nanoceramic, standard metalized, and economy dyed specifications separates certified solar control from unbranded aftermarket tint. Cost-down pressure on standard-tier PET constructions accelerates as captive resin producers leverage backward integration. Price differentiation hinges on NFRC certification documentation and multi-layer sputtering capability, with residential DIY buyers exhibiting highest sensitivity while institutional safety-specification buyers absorb premium positioning.
Supply Chain Analysis
Ocean freight rate volatility between East Asian PET resin manufacturing clusters and North American coating operations is compressing margin buffers for non-integrated toll coaters. Optical-grade PET supply concentrates in the United States, Germany, and Japan, with biaxially oriented substrate production drawing from purified terephthalic acid and ethylene glycol feedstocks. Single-source vulnerability sits with multi-layer sputtering equipment manufacturers in Japan and Germany. Distribution runs through certified applicator networks in commercial retrofit corridors and home improvement retail for residential aftermarket.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capital intensity in precision vacuum deposition equipment and captive resin production is consolidating competitive capability among integrated chemical majors and forcing independent coaters toward specialty niches or exit.
For Market Incumbents: Lock in certified installer network exclusivity through performance-based warranty contracts that bind national account procurement teams to manufacturer-direct channels. Deepen captive PET resin production in the United States to offset East Asian feedstock cost volatility. Electrochromic glazing substitution in premium new-builds threatens solar control retrofit volumes; counter with smart film-electronics convergence R&D bridging static and dynamic categories. For New Entrants and Emerging Players: California Title 24 extensions open a window for solar control specification in existing commercial stock where incumbent distribution relationships remain underdeveloped. Target underpenetrated hospitality retrofit pipelines in India's Mumbai and Bangalore corridors where BIS energy code maturation lags specification demand. Lead with professional installation bundling to differentiate from manufacturer-channel conflicts and secure localized service relationships. For Investors and Strategic Acquirers: Re-rating potential sits with regional coaters possessing IWFA-certified installer networks given facility manager procurement shifts toward transparent labor pricing. Five-to-ten year viability favors asset-light designers with technology licensing arrangements over capital-heavy sputtering line owners. Monitor electrochromic glazing cost curves as inflection signal for retrofit-versus-replace calculus shifts in commercial building owner decision frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PET Resin | Captive optical-grade substrate production insulates Eastman Chemical and integrated majors from feedstock volatility. |
| Multi-Layer Sputtering Capacity Expansion | Precision vacuum deposition asset additions concentrate nanoceramic specification capability among chemical majors. |
| Certified Installer Network Consolidation | IWFA and NFRC credentialing requirements create bottlenecks that manufacturer-direct warranty contracts can capture. |
| Smart Film-Electronics Convergence | Transparent conductive oxide integration enables switchable prototypes bridging static retrofit and dynamic glazing categories. |
| EU Green Deal Compliance Repositioning | REACH adhesive chemistry documentation investments extend product development timelines and raise European market entry barriers. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with window film coating plant managers, commercial facility procurement leads, certified installer network operators, and architectural specification consultants. IWFA membership directories, ECHA registration databases, and U.S. Department of Energy building code compliance filings provided demand-side validation. Bottom-up project pipeline assessments across California, Texas, and New York Metro retrofits were triangulated against top-down construction spending forecasts.
Reconciliation of volume shipments from PET resin producers, coating line capacity utilization surveys, and certified installation job reporting generated consistent demand estimates across the projection horizon. Segmentation modeling incorporated film material chemistry, functional specification tier, installation complexity, and regional regulatory cluster dimensions. CAGRs were derived from retrofit payback economics under evolving Title 24 and EU Green Deal thermal performance thresholds, with solar heat gain coefficient mandate trajectories and electrochromic glazing cost curves as key sensitivity inputs.
The model assumes a particular technology adoption path; alternative pathways for electrochromic and thermochromic dynamic glazing would alter the retrofit-versus-replace calculus and compress solar control film specification rates. Forecasts reflect assumptions regarding regulatory enforcement intensity, certified installer training program expansion, and resin supply concentration stability. Stakeholders should weight assumptions against their own operating context and regional construction cycle exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Point Fixing Glass Curtain Wall Market
Building & Construction Materials
Granite Flooring Market
Building & Construction Materials
North America Ready-Mix Concrete Market
Building & Construction Materials
Global Wall Putty Market
Building & Construction Materials
Roof Coating Market
Building & Construction Materials
Architectural Acoustic Panels Market
Building & Construction Materials
US Terracotta Cladding Market
Building & Construction Materials
South America Ready Mix Concrete Market
Building & Construction Materials
Pre-Insulated Pipes Market
Building & Construction Materials
Finishing Lines Market
Building & Construction Materials
Foldable Houses Market
Building & Construction Materials
Saudi Arabia Tiles Market
Building & Construction Materials
Mexico Oriented Strand Board Market
Building & Construction Materials
Geofoam Market
Building & Construction Materials
Fire-Retardant Treated Wood Market
Building & Construction Materials
Gulf Corporation Council Cement Market