
 Custom Procedure Packs (CPT) Market | 2026-2036
Custom Procedure Packs (CPT) Market Size, Share, and Industry Trends Forecast 2026-2036
Custom Procedure Packs (CPT) Market Analysis
Procedure-specific subscription replenishment programs are repositioning how hospitals contract for consumables, shifting capital-light buyers toward recurring procurement models. Cardinal Health leverages its distribution density to anchor multi-year hospital agreements across integrated delivery networks. Mölnlycke Health Care AB differentiates through proprietary barrier material R&D, sustaining premium positioning in orthopedic and cardiovascular kits. Owens & Minor, Inc. competes on same-day fulfillment infrastructure, controlling last-mile logistics for ambulatory surgical centers.
Custom procedure packs are pre-assembled, sterile collections of disposable medical devices, drapes, instruments, and pharmaceuticals configured to match specific surgical protocols, typically validated to ISO 11607 sterile barrier standards and gamma-sterilized for immediate use. Their primary commercial purpose is reducing operating room turnover time, lowering surgical site infection risk through standardized sterile field preparation, and compressing hospital supply chain overhead into single-SKU procurement. Surgical packs dominate current volume due to universal applicability across general surgery, while specialty kits capture disproportionate margin pools in complex cardiovascular and orthopedic procedures where component customization is highest. Disposable packs are maturing in price-competitive segments, whereas device kits represent the fastest-growing structural category as original equipment manufacturers bundle proprietary instruments with consumables.
The FDA enforces Quality System Regulation and sterile barrier validation requirements that determine market access for domestic CPT suppliers, while the EU Medical Device Regulation imposes stricter clinical evidence thresholds on pack-as-device configurations entering European markets. ISO 13485 certification has become a baseline qualifier for contract eligibility with US group purchasing organizations, filtering smaller assemblers from national hospital network tenders. Stakeholders must monitor how FDA digitalization of device master records intersects with EU Unique Device Identification mandates to reshape traceability costs across multinational supply chains.
Market Dynamics
Health system consolidation across the United States is compressing supplier bases into single-source CPT contracts, forcing assemblers to absorb inventory risk and embed logistics services into sterile pack agreements.
Growth Catalysts
- FDA sterile barrier validation:Updated requirements for ISO 11607 compliance are filtering out regional assemblers, concentrating contract awards with certified national suppliers capable of gamma-sterilization documentation.
- Ambulatory surgical center expansion:Outpatient volume migration toward freestanding ASCs is generating pull for pre-configured packs that eliminate on-site sterile processing infrastructure.
- Subscription replenishment models:Procedure-specific auto-replenishment programs are converting capital-light buyers from spot purchasing into recurring revenue relationships with pack assemblers.
Market Restraints
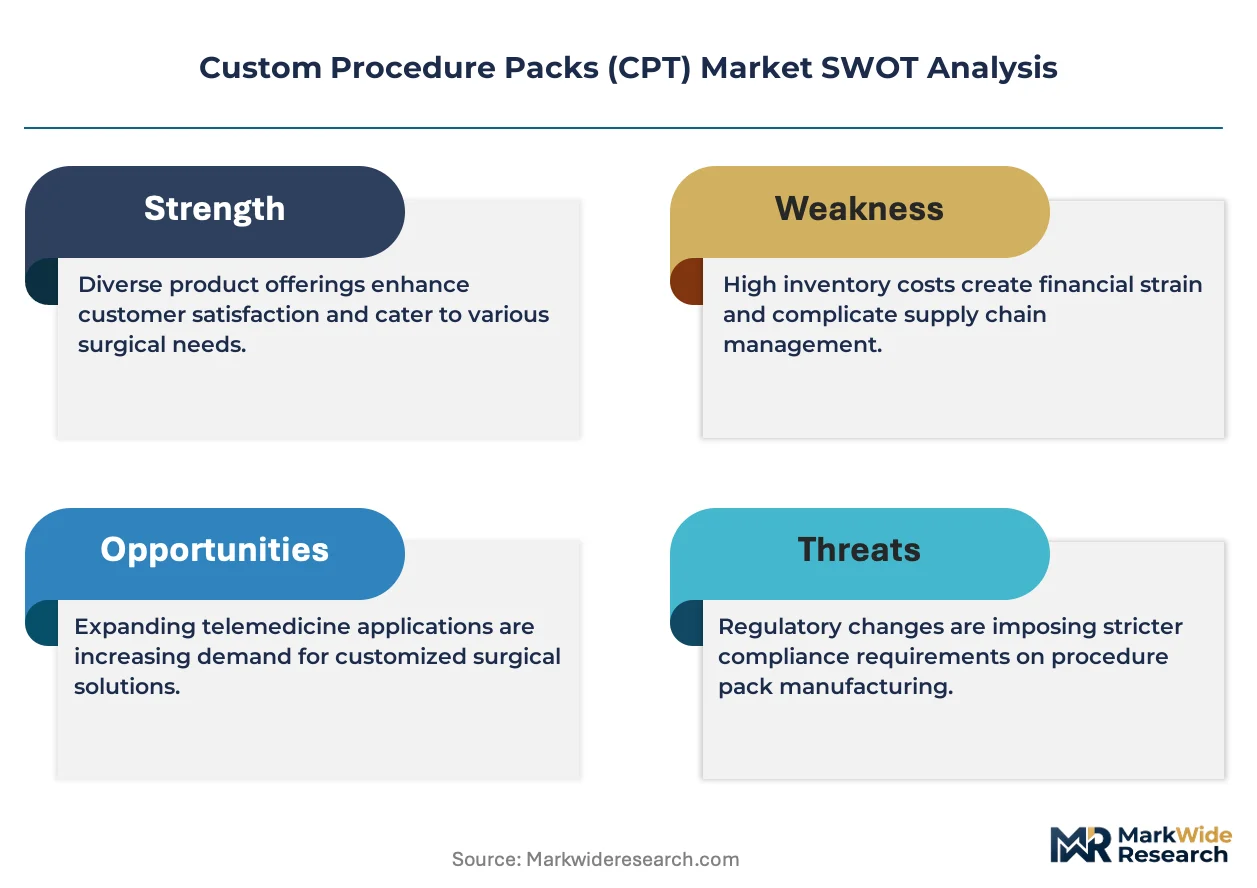
- Medical-grade polymer cost volatility:Fluctuations in ethylene and propylene feedstock pricing squeeze margin on disposable drape and tray components, particularly for price-locked multi-year hospital contracts.
- Gamma sterilization capacity concentration:North American cobalt-60 irradiation facilities cluster in limited geographic corridors, creating single-point vulnerability for just-in-time pack delivery.
- EU MDR clinical evidence thresholds:Stricter documentation requirements for pack-as-device configurations entering European markets extend registration timelines and elevate regulatory compliance spend.
Strategic Opportunities
- Cardiovascular kit premiumization:Complex catheter and stent bundle configurations command disproportionate margin pools where component customization is highest and sterile field standardization reduces procedural variability.
- Same-day ASC fulfillment infrastructure:Dedicated last-mile logistics networks for ambulatory surgical centers enable competitive differentiation through inventory reduction and case-cart readiness guarantees.
- Digital device master record convergence:FDA digitalization initiatives intersecting with EU Unique Device Identification mandates create first-mover advantage for assemblers with integrated traceability systems spanning multinational supply chains.
Industry Challenges
- ISO 13485 certification timeline compression:Group purchasing organizations now mandate quality system certification as a baseline tender qualifier, excluding smaller assemblers from national network contracts before validation cycles complete.
- Legacy ERP integration friction:Hospital materials management systems require custom API development to sync automated replenishment triggers with existing procurement workflows, extending implementation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Custom Procedure Packs (CPT) Market |
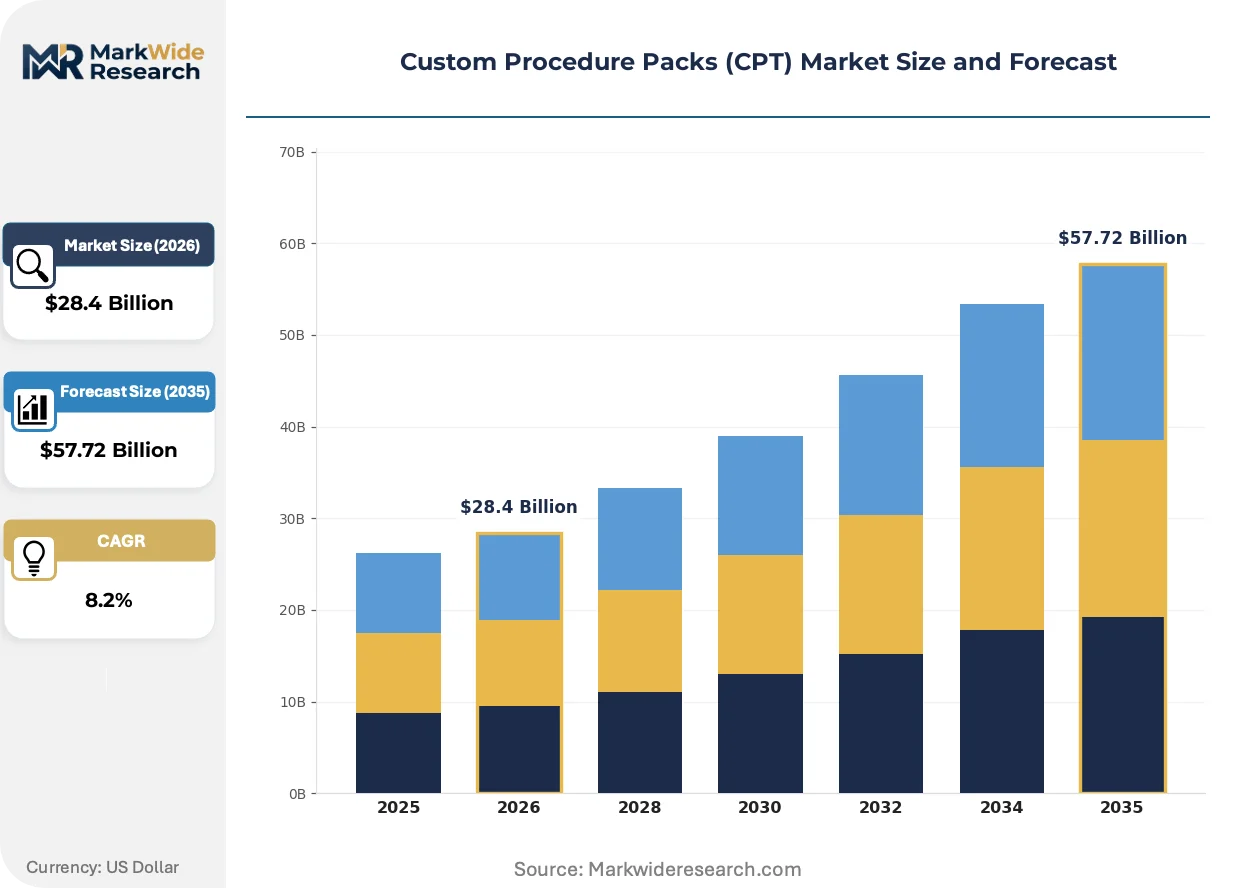
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $57.72 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Packs, Specialty Kits, Device Kits, Disposable Packs End User: Hospitals, Ambulatory Surgical Centers, Clinics, Laboratories Application: Cardiovascular, Orthopedic, General Surgery, Dental Delivery Mode: Direct Delivery, Curbside Pickup, Online Ordering, In-Hospital Distribution |
| Companies Covered | Medline Industries, LP, Cardinal Health, Mölnlycke Health Care AB, Owens & Minor, Inc., B. Braun SE, Unisurge, Kimal, PrionTex, PAUL HARTMANN AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Custom Procedure Packs (CPT) Market Emerging Trajectories
Pack configuration intelligence is migrating from static SKU libraries toward dynamic, procedure-protocol-matching algorithms that compress operating room turnover time through predictive case-cart assembly.
Radio-frequency identification tagging embedded at the component level is automating sterile field accountability and expiration tracking across hospital networks. Integrated delivery networks in the United States are piloting RFID-enabled packs that auto-reconcile consumption against surgical schedules, reducing manual count documentation burden and compressing turnover intervals between cases. This automation is eliminating discrepancies that previously triggered surgical delays and inventory reconciliation labor.
The EU Medical Device Regulation is recasting custom procedure packs with device-like clinical evidence obligations, particularly for configurations containing active components. Manufacturers must now compile biocompatibility and performance documentation previously reserved for individual instruments, elevating registration costs and compressing the viable assembler base. Specialty orthopedic and cardiovascular kit suppliers are responding by consolidating component sourcing under captive quality agreements to streamline technical file compilation.
Hospital supply chain directors are unbundling after-sales sterile processing services from pack procurement, shifting liability for tray integrity onto assemblers who must now guarantee gamma-sterilization validity through point-of-use delivery. This reconfiguration is visible most acutely in United States metropolitan markets where ASC joint ventures with health systems demand turnkey sterile solutions without on-site autoclave investment. Pack assemblers are responding with fleet-based sterilization validation and direct-to-suite logistics contracts that absorb infrastructure burden from facility operators.
Custom Procedure Packs (CPT) Market Segmentation
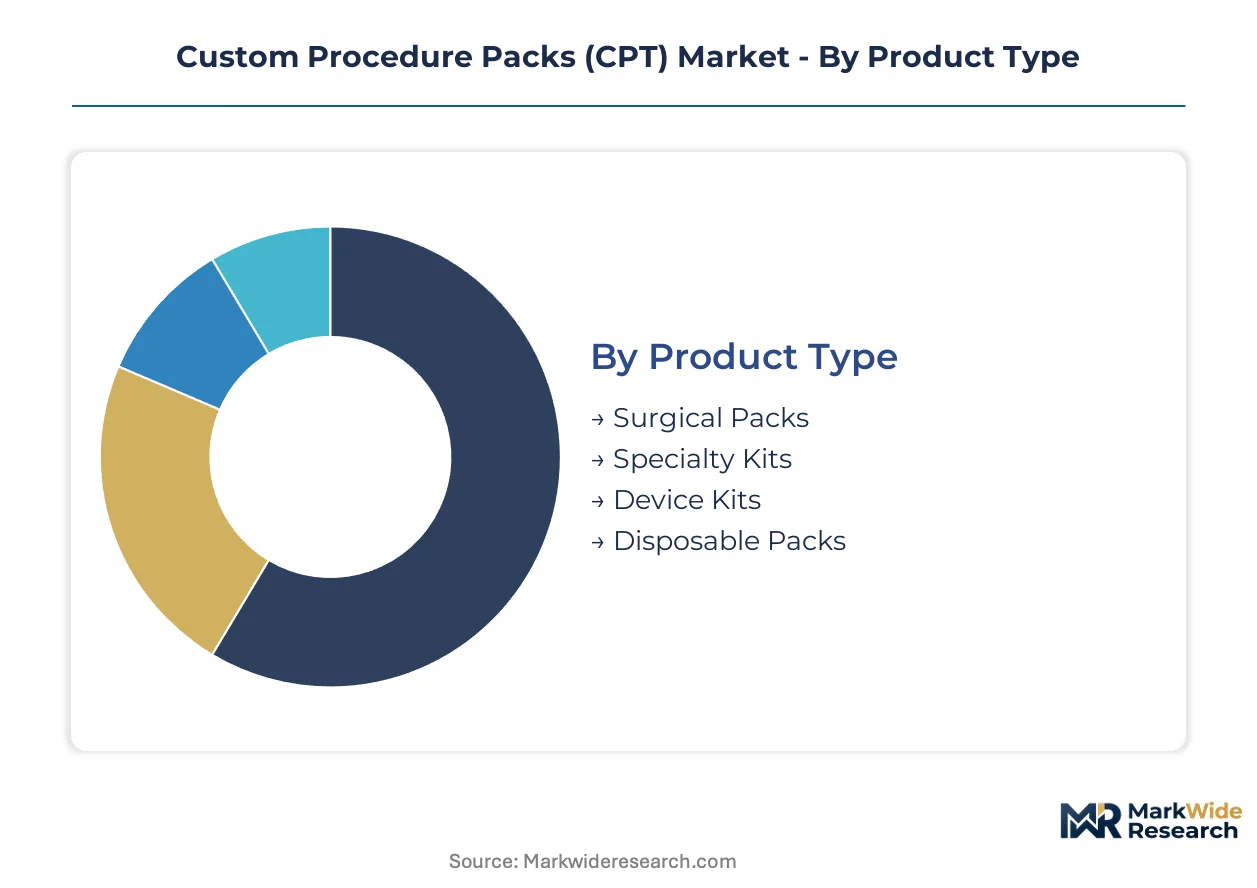
Segmentation in the Custom Procedure Packs market reveals how procurement complexity fragments across clinical settings and supply chain configurations. Pack assemblers must align sterile barrier specifications, delivery velocity, and component customization to match distinct operational requirements.
Product Type:
Customization intensity varies sharply across this spectrum, from commodity disposable collections to engineered device bundles requiring proprietary instrument integration.
- Surgical Packs:Standardized sterile collections of drapes, gowns, and basic instruments validated to ISO 11607 for general operating room turnover. Demand concentrates in United States metropolitan hospital networks where health system consolidation favors single-source contracts with gamma-sterilization documentation.
- Specialty Kits:Procedure-specific configurations for complex interventions with highest component customization and sterile field standardization requirements. Orthopedic and cardiovascular service lines in integrated delivery networks drive premium procurement, where bundle complexity reduces procedural variability and surgical site infection risk.
- Device Kits:Original equipment manufacturer bundles combining proprietary instruments with consumables, capturing expanding structural category as OEMs integrate backward into sterile pack assembly.
- Disposable Packs:Price-competitive commodity segments maturing under polymer cost volatility pressure, with ethylene and propylene feedstock fluctuations squeezing margin on multi-year hospital contracts.
Most installed capacity flows through Surgical Packs. Expansion is steepest in Device Kits.
End User:
Procurement authority and infrastructure investment separate capital-heavy institutional buyers from lean outpatient operators seeking turnkey sterile solutions.
- Hospitals:Dominant procurement volume with materials management systems requiring custom API integration for automated replenishment triggers. United States health system consolidation compresses supplier bases into multi-year agreements absorbing inventory risk.
- Ambulatory Surgical Centers:Freestanding outpatient facilities eliminating on-site sterile processing infrastructure through pre-configured pack adoption. Same-day fulfillment infrastructure and direct-to-suite logistics contracts enable competitive differentiation without autoclave investment.
- Clinics:Lower-volume purchasers with spot procurement patterns converting toward subscription replenishment models for capital-light operations.
- Laboratories:Specialized sterile requirements for diagnostic and research protocols with distinct biocompatibility documentation needs.
Contract value concentrates in Hospitals. Ambulatory Surgical Centers are climbing the fastest.
Application:
Procedure complexity and reimbursement dynamics create divergent margin pools across surgical specialties.
- Cardiovascular:Complex catheter and stent bundle configurations commanding disproportionate margin pools where sterile field standardization reduces procedural variability. United States integrated delivery networks prioritize premium kit procurement for electrophysiology and interventional cardiology service lines.
- Orthopedic:Implant and instrument bundle customization with highest sterile barrier validation requirements. EU MDR clinical evidence thresholds particularly impact this segment, extending registration timelines for pack-as-device configurations.
- General Surgery:Universal applicability driving volume concentration with standardized pack configurations and compressed price competition.
- Dental:Procedure-specific sterile collections for oral surgery and implantology with distinct regulatory pathways through FDA device classification.
Revenue margin pools concentrate in Cardiovascular. Orthopedic is expanding most quickly under premiumization pressure.
Delivery Mode:
Logistics infrastructure investment separates national assemblers with fulfillment density from regional competitors limited to traditional distribution.
- Direct Delivery:Point-of-use sterile pack delivery with gamma-sterilization validity guarantees through fleet-based validation systems. United States ASC joint ventures demand turnkey solutions absorbing infrastructure burden from facility operators.
- Curbside Pickup:Limited adoption for emergency replenishment scenarios where same-day availability outweighs sterile chain custody requirements.
- Online Ordering:Digital procurement platforms with automated replenishment triggers syncing to hospital materials management systems, though legacy ERP integration friction extends implementation cycles.
- In-Hospital Distribution:Traditional supply chain model with central sterile processing departments, increasingly unbundled as liability shifts onto assemblers for tray integrity guarantees.
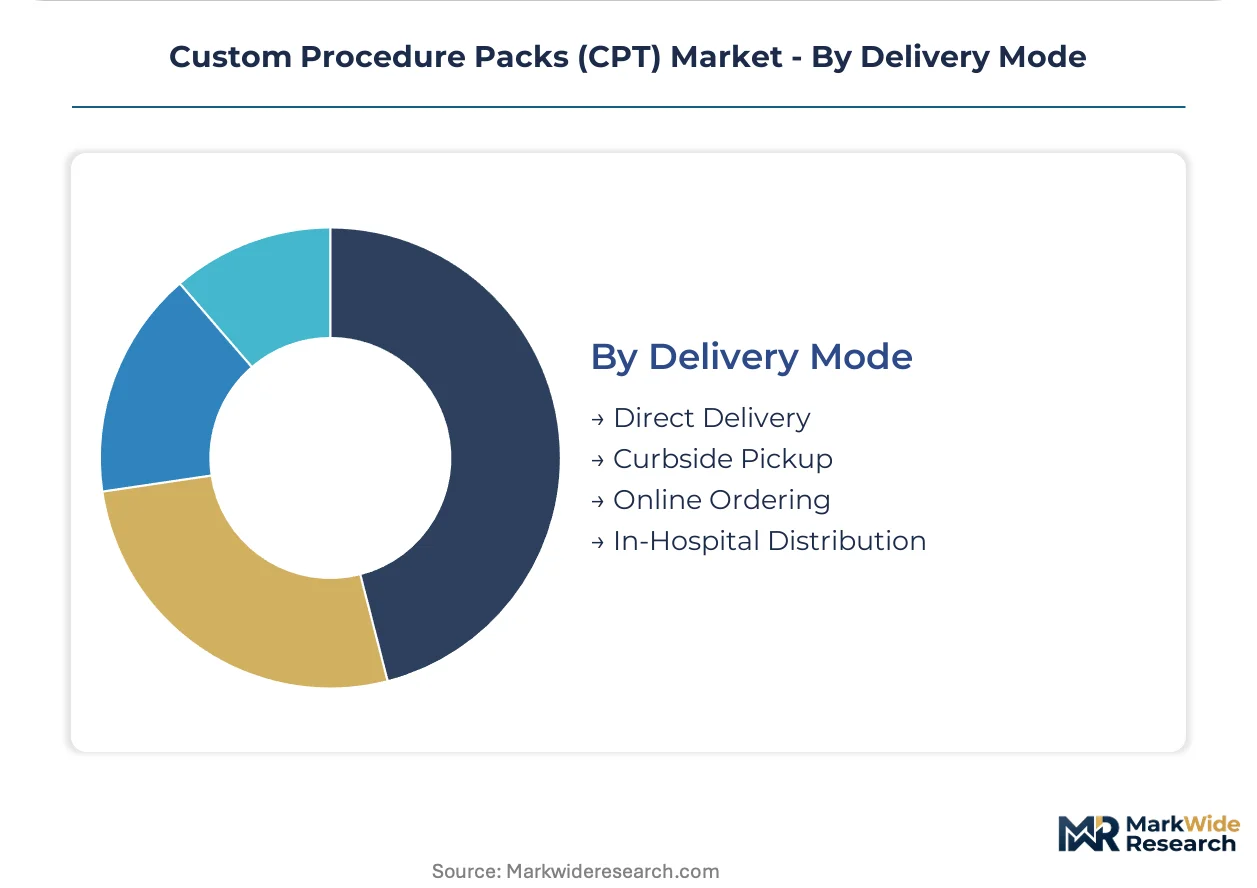
Operational scale flows through Direct Delivery. Online Ordering is gaining share fastest under digital procurement migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping CPT production geography as manufacturers migrate assembly toward jurisdictions with lower sterile validation compliance costs while maintaining FDA and EU MDR market access through dual-registered facilities.
United States
Health system consolidation concentrates procurement authority within integrated delivery networks favoring single-source CPT contracts with gamma-sterilization documentation. FDA Quality System Regulation enforcement filters regional assemblers from national hospital network tenders. The Minneapolis-St. Paul corridor anchors sterile barrier R&D clusters serving orthopedic and cardiovascular kit premiumization.
Germany
EU MDR clinical evidence thresholds extend registration timelines for pack-as-device configurations containing active components. EMA coordination with notified bodies elevates biocompatibility documentation requirements previously reserved for individual instruments. The Baden-Württemberg medical technology cluster concentrates specialty kit engineering for complex intervention protocols.
China
NMPA medical device classification reforms accelerate domestic CPT manufacturer qualification for export-grade sterile barrier validation. Dual carbon goals pressure polymer feedstock sourcing toward bio-based alternatives in drape and tray production. The Yangtze River Delta manufacturing belt scales gamma-sterilization capacity to serve Asia-Pacific ambulatory surgical center demand.
United Kingdom
Post-Brexit regulatory divergence from EU MDR creates parallel registration pathways for CPT suppliers seeking NHS supply chain access. MHRA device master record digitalization intersects with procurement centralization under NHS Supply Chain. The Greater Manchester health innovation cluster pilots RFID-enabled pack tracking for surgical schedule auto-reconciliation.
India
CDSCO medical device rules harmonization with ISO 13485 standards opens contract manufacturing opportunities for export-oriented CPT assembly. PLI scheme incentives attract sterile barrier material processing investment from multinational pack assemblers. The Gujarat pharmaceutical and medical device zone develops gamma-irradiation infrastructure for regional just-in-time delivery networks.
Custom Procedure Packs (CPT) Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated distribution networks controlling hospital procurement channels while regional assemblers serve price-sensitive disposable pack demand. Market structure concentrates around three archetypes: multinational health conglomerates with captive sterilization infrastructure, mid-scale specialists in orthopedic and cardiovascular kit configuration, and private-label contract manufacturers supplying group purchasing organizations. Dominant competitive moves include backward integration into polymer component production and strategic partnerships with ambulatory surgical center joint ventures for direct-to-suite logistics contracts.
Among health conglomerate-scale operators, Cardinal Health and Owens & Minor, Inc. exemplify the distribution-anchored archetype controlling last-mile infrastructure for integrated delivery networks. Mölnlycke Health Care AB occupies a position within the premium specialty tier, representing proprietary barrier material R&D capabilities that sustain margin pools in complex procedure kits. These three companies anchor distinct competitive vectors: fulfillment density, sterile processing validation, and material science differentiation.
| Leading Market Players |
|---|
| Medline Industries, LP |
| Cardinal Health |
| Mölnlycke Health Care AB |
| Owens & Minor, Inc. |
| B. Braun SE |
| Unisurge |
| Kimal |
| PrionTex |
| PAUL HARTMANN AG |
| Others |
Supply Flow & Price Mechanics
Ethylene and propylene feedstock indices cascade through polymer component costs into three-tier pricing structures across premium, standard, and economy levels, with gamma-sterilization validation tiers separating Cardinal Health's multi-year hospital contracts from regional assemblers locked into spot procurement.
Pricing Analysis
Distributor margin compression of 12-18 percentage points separates national GPO-anchored contracts from direct-to-ASC fulfillment models. Price differentiation hinges on ISO 13485 certification grade and gamma-sterilization documentation completeness. Margins are tightening due to medical-grade polymer cost volatility squeezing price-locked multi-year agreements. Ambulatory surgical centers exhibit highest price sensitivity; integrated delivery networks with captive sterilization infrastructure show lowest.
Supply Chain Analysis
Single-source vulnerability sits with North American cobalt-60 irradiation facilities clustering in limited geographic corridors. Manufacturing concentrates in the United States, Germany, and China. Raw material dependencies encompass ethylene-propylene polymers, cobalt-60 isotopes, and medical-grade barrier films. Tariff exposure on Chinese-sourced drape components threatens margin stability. Distribution runs through integrated delivery network central warehouses with direct-to-suite last-mile legs for ASC joint ventures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between EU MDR clinical evidence thresholds elevating European compliance costs and NMPA reforms accelerating Chinese domestic manufacturer qualification for export-grade sterile barrier validation.
For Market Incumbents: Cement gamma-sterilization capacity additions in the Minneapolis-St. Paul corridor to defend against regional assemblers gaining ISO 13485 certification. Absorb inventory risk through subscription replenishment programs that lock hospital materials management systems into custom API integrations. Prioritize backward integration into polymer component production to offset ethylene feedstock volatility.
For New Entrants and Emerging Players: Ambulatory surgical center joint ventures represent the most penetrable channel partner type for bypassing established GPO contract barriers. Target cardiovascular kit premiumization where component customization commands margin pools underserved by commodity surgical pack assemblers. Lead with same-day fulfillment infrastructure guarantees rather than price competition.
For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR registration timelines extend beyond 18 months for pack-as-device configurations. Mid-scale specialty kit engineers with captive quality agreements and proprietary barrier material R&D capabilities offer strongest 5-10 year viability. Monitor FDA digitalization of device master records intersecting with EU UDI mandates as inflection indicator for traceability system acquisition premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Gamma-Sterilization Capacity Expansion | North American cobalt-60 infrastructure gaps create first-mover advantage for ASC direct delivery networks. |
| ISO 13485 Certification Acceleration | Group purchasing organization tender qualification filters regional competitors from national hospital contracts. |
| RFID-Enabled Pack Tracking Integration | Auto-reconciliation against surgical schedules reduces OR turnover time and manual count documentation burden. |
| EU MDR Technical File Consolidation | Biocompatibility documentation for pack-as-device configurations elevates registration costs and compresses viable assembler base. |
| Subscription Replenishment Platform Development | Automated triggers syncing to hospital ERP systems convert spot purchasers into recurring revenue relationships. |
Methodological Framework
Bottom-up ambulatory surgical center and hospital procurement modeling reconciled against top-down gamma-sterilization capacity and polymer feedstock tracking forms the analytical core. Primary interviews with GPO contracts managers, hospital supply chain directors, biomedical engineers, and sterile processing department heads combined with secondary validation against FDA 510(k) filings, EU MDR notified body submissions, hospital procurement databases, and customs trade data. Triangulation across stakeholder perspectives and documentary sources ensures cross-verified demand and supply estimates.
Input-output matrices map surgical procedure volumes through pack configuration intensity to component demand across product type, end user, application, and delivery mode segmentations. CAGRs derive from regression-based trend extrapolation moderated by regulatory event probabilities and health system consolidation trajectories. Forecast inputs incorporate ambulatory surgical center joint venture formation rates and FDA sterile barrier validation update implementation timelines.
Revisions become necessary when EU MDR notified body capacity constraints extend registration timelines, cobalt-60 irradiation facility closures disrupt just-in-time delivery networks, or health system consolidation accelerates beyond modeled single-source contract adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Sterilization Box Market
Medical Supplies
Fibrin Sealants Market
Medical Supplies
Pharmacy Accessory Bagging System (PABS) Market
Medical Supplies
Europe Custom Procedure Kits Market
Medical Supplies
Global Synthetic Absorbable Sutures Market
Medical Supplies
Global Dental Syringes Market
Medical Supplies
Prepackaged Medical Kits and Trays Market
Medical Supplies
North America Hospital Supplies Market
Medical Supplies
Global Hypodermic Needles Market
Medical Supplies
Cryogenic Vials Market
Medical Supplies
Western Europe Sterile Gloves Market
Medical Supplies
Global Disposable Urinary Drainage Bag Market
Medical Supplies
Global Sterilization Wrap Market
Medical Supplies
Filter Needles Market
Medical Supplies
Global Dental Sterilization Market
Medical Supplies
Auto-Disable Syringes Market