
 Brain Mapping Instruments Market | 2026-2036
Brain Mapping Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Brain Mapping Instruments Market Analysis
North American imaging equipment manufacturing is rebalancing toward modular, AI-integrated platforms that reduce scanner footprint and service intervals. Siemens Healthineers leverages its magnet technology leadership to dominate ultra-high-field MRI installations for preclinical brain mapping. GE Healthcare sustains competitive positioning through backward integration into helium-free superconducting magnet production. Koninklijke Philips differentiates via ambulatory EEG systems that extend monitoring beyond traditional hospital settings.
Brain mapping instruments encompass devices that measure, record, and visualize neural structure and function through electromagnetic, metabolic, or hemodynamic detection, typically resolving spatial features below three millimeters and temporal dynamics within milliseconds. These systems serve primarily to localize epileptogenic tissue, map eloquent cortex prior to resection, and decode neural signals for therapeutic or assistive interfaces. Functional magnetic resonance imaging anchors the value pool due to reimbursement density and hospital capital planning cycles, while electroencephalography occupies the highest unit volume position driven by sleep medicine and intraoperative monitoring demand. Positron emission tomography competes in dementia staging workflows where amyloid and tau quantification guides therapeutic eligibility.
The FDA's breakthrough device program and the EU Medical Device Regulation reshape product development timelines, with the former compressing premarket pathways for novel neuroimaging biomarkers and the latter imposing clinical evidence requirements that favor established notified body relationships. ISO 13485 quality management certification and IEC 60601 electrical safety standards govern market access across OECD jurisdictions, with Japan's PMDA adding supplementary pharmacovigilance expectations for long-implantable neural interfaces. Stakeholders must monitor reimbursement coding decisions for quantitative EEG metrics and AI-augmented image interpretation, as these determinations will separate commercially viable platforms from research-limited installations.
Market Dynamics
Modular AI-integrated platforms are compressing scanner footprints and collapsing service intervals across North American imaging equipment manufacturing, forcing incumbents to restructure R&D roadmaps around software-defined architectures rather than hardware-centric upgrades.
Growth Catalysts
- NIH-funded brain research initiatives:Sustained federal funding for neural circuit mapping drives institutional procurement of high-channel EEG and fMRI systems at academic medical centers.
- FDA breakthrough device designation:Accelerated premarket pathways compress clearance timelines for novel neuroimaging biomarkers, reducing regulatory friction for first-movers.
- Ambulatory monitoring demand:Sleep medicine and intraoperative applications extend electroencephalography unit volumes beyond traditional hospital settings.
Market Restraints
- Helium supply concentration:Superconducting magnet production depends on constrained helium sources, with price volatility threatening MRI manufacturing economics.
- EU MDR clinical evidence requirements:Stricter notified body relationships favor established manufacturers and delay market entry for smaller innovators.
- PET radiotracer half-life limitations:Short-lived isotopes restrict distribution radius and require on-site cyclotron infrastructure, capping geographic penetration.
Strategic Opportunities
- Quantitative EEG reimbursement coding:Pending determinations on AI-augmented metrics create white space for platforms that secure favorable coverage decisions.
- Japan PMDA pharmacovigilance pathways:Supplementary expectations for long-implantable neural interfaces reward early regulatory engagement with accelerated timelines.
- Epilepsy monitoring center expansion:Academic medical centers in Germany and Japan are scaling high-channel system procurement, opening concentrated demand pockets.
Industry Challenges
- ISO 13485 certification timelines:Quality management system audits create 12-18 month delays for new market entrants across OECD jurisdictions.
- IEC 60601 electrical safety integration:Legacy device retrofitting for updated standards demands substantial engineering resources without revenue offset.
- Neural signal decoding talent scarcity:Cross-disciplinary expertise spanning neurophysiology, signal processing, and machine learning concentrates at Boston and San Francisco clusters, limiting geographic hiring flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brain Mapping Instruments Market |
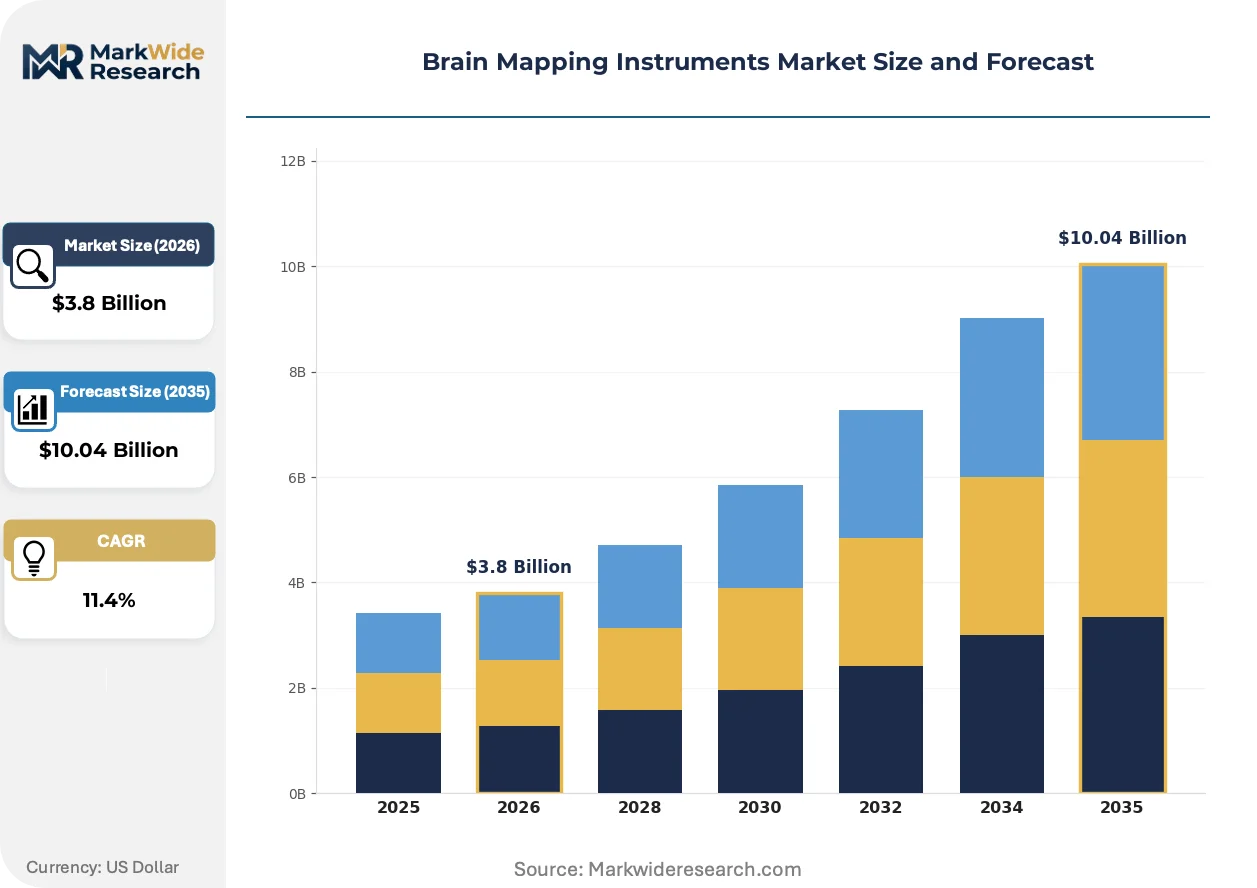
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electroencephalography, Magnetoencephalography, Functional Magnetic Resonance Imaging, Positron Emission Tomography Technology: Neuroimaging, Computational Neuroscience, Signal Processing, Data Analytics End User: Research Institutes, Hospitals, Diagnostic Centers, Neurorehabilitation Centers Application: Neurological Disorders, Cognitive Research, Surgical Planning, Brain-Computer Interface |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips, Medtronic, Natus Medical Incorporated, Advanced Brain Monitoring, Inc., Nihon Kohden Corporation, Canon Medical Systems Corporation, Brain Products GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brain Mapping Instruments Market Emerging Trajectories
Artificial intelligence is rewriting the value architecture of neuroimaging, compressing image reconstruction times and enabling real-time functional mapping that was previously confined to post-processing workflows.
Ultra-high-field MRI is expanding into preclinical brain mapping applications, delivering submillimeter spatial resolution for rodent neural circuit tracing. Contract research organizations in Boston and San Francisco are adopting 7 Tesla and above systems at accelerating pace. Siemens Healthineers leverages its magnet technology leadership to dominate these installations, compressing competitive headroom for challengers lacking captive superconducting expertise.
The EU Medical Device Regulation is reshaping neuroimaging product development timelines, imposing clinical evidence requirements that favor established notified body relationships. Manufacturers must now front-load post-market surveillance infrastructure before commercial launch. European epilepsy monitoring centers are responding by consolidating procurement around vendors with demonstrated MDR compliance track records, reducing supplier diversity.
Academic medical centers are unbundling after-sales service contracts from capital equipment purchases, demanding standalone software maintenance and remote technical support agreements. This procurement pattern shift compresses vendor margin structures while opening recurring revenue streams for platforms with cloud-native architectures. The trend is most visible in United States NIH-funded institutions, where multi-site research consortia negotiate centralized service frameworks.
Brain Mapping Instruments Market Segmentation
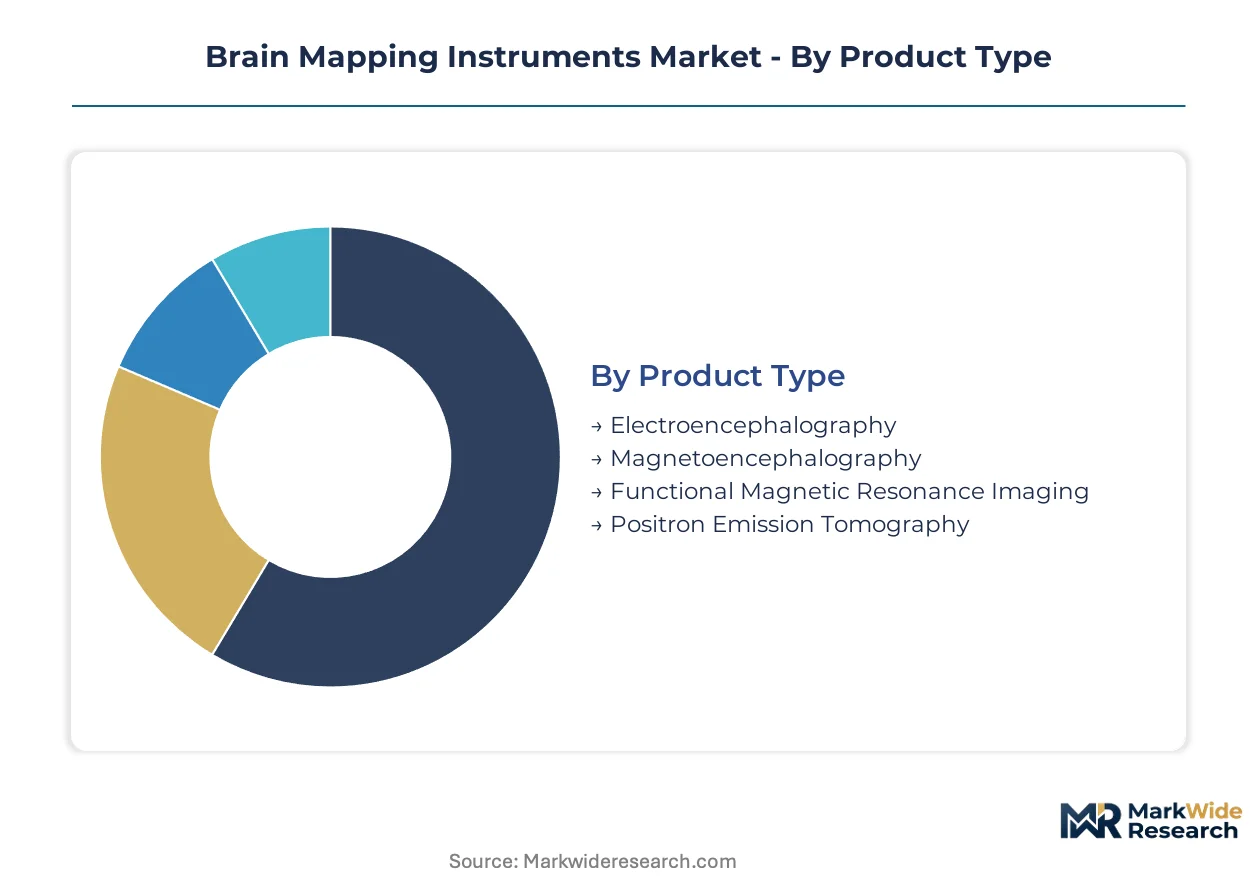
Brain mapping instruments fragment across four critical dimensions that determine procurement patterns, reimbursement pathways, and R&D investment allocation. Product type distinctions govern capital expenditure cycles and service infrastructure, while technology layers define where value capture concentrates between hardware manufacturers and software platforms.
Product Type:
Standalone imaging systems dominate hospital capital planning with dedicated facility requirements and specialized technical staff, whereas portable and embedded configurations are penetrating ambulatory and intraoperative settings.
- Functional Magnetic Resonance Imaging:Superconducting magnet systems achieve submillimeter spatial resolution through blood-oxygen-level-dependent contrast. NIH-funded academic medical centers in the United States anchor procurement volumes, though helium supply constraints compress manufacturing margins for OEMs.
- Electroencephalography:Non-invasive electrical potential recording spans 32-channel diagnostic systems to 256-channel high-density arrays for source localization. Sleep medicine clinics and epilepsy monitoring units in Germany and Japan drive unit volume expansion, with ambulatory configurations extending beyond traditional hospital settings.
- Magnetoencephalography:Superconducting quantum interference device arrays detect femtotesla-scale magnetic fields with millisecond temporal precision. Requires magnetically shielded rooms and liquid helium infrastructure, limiting installations to major research consortia.
- Positron Emission Tomography:Radiotracer-based metabolic imaging depends on cyclotron-produced isotopes with short half-lives. Amyloid and tau quantification for dementia staging concentrates demand at tertiary centers with captive radiochemistry capabilities.
Electroencephalography leads volumes today; functional magnetic resonance imaging maintains revenue concentration despite slower unit expansion.
Technology:
Value capture is shifting toward software layers as hardware commoditization accelerates across detector and magnet subsystems.
- Neuroimaging:Hardware platforms integrating electromagnetic, metabolic, and hemodynamic detection modalities. Siemens Healthineers and GE Healthcare dominate magnet technology, compressing headroom for component challengers.
- Computational Neuroscience:Neural circuit modeling and connectome reconstruction algorithms that translate raw signals into clinically actionable maps. Boston and San Francisco talent clusters concentrate algorithm development capacity.
- Signal Processing:Real-time artifact rejection, source localization, and denoising pipelines. FDA breakthrough device designation pathway accelerates clearance for novel biomarker extraction methods.
- Data Analytics:Cloud-native architectures enabling multi-site research consortia and AI-augmented interpretation. Academic medical centers are unbundling standalone software maintenance from capital equipment purchases.
Neuroimaging hardware commands installed base value; data analytics is climbing the fastest as procurement shifts toward recurring revenue models.
End User:
Capital intensity and reimbursement density separate institutional tiers, with research institutes tolerating higher technical risk than clinical settings.
- Hospitals:Tertiary centers with neurosurgery and epilepsy programs requiring intraoperative monitoring and pre-surgical mapping capabilities. Reimbursement density for fMRI and PET anchors procurement budgets.
- Research Institutes:NIH-funded brain research initiatives and European Research Council grants drive high-channel EEG and ultra-high-field MRI adoption. Multi-site consortia negotiate centralized service frameworks.
- Diagnostic Centers:Sleep medicine and routine neurological assessment facilities prioritizing cost-efficient EEG configurations. Quantitative EEG reimbursement coding decisions will determine commercial viability.
- Neurorehabilitation Centers:Brain-computer interface training and post-stroke recovery monitoring. Emerging demand pocket with undefined reimbursement pathways.
Hospitals retain revenue concentration; research institutes show steepest expansion trajectory for novel modality adoption.
Application:
Clinical utility and regulatory clearance status determine addressable market breadth across therapeutic and investigational use cases.
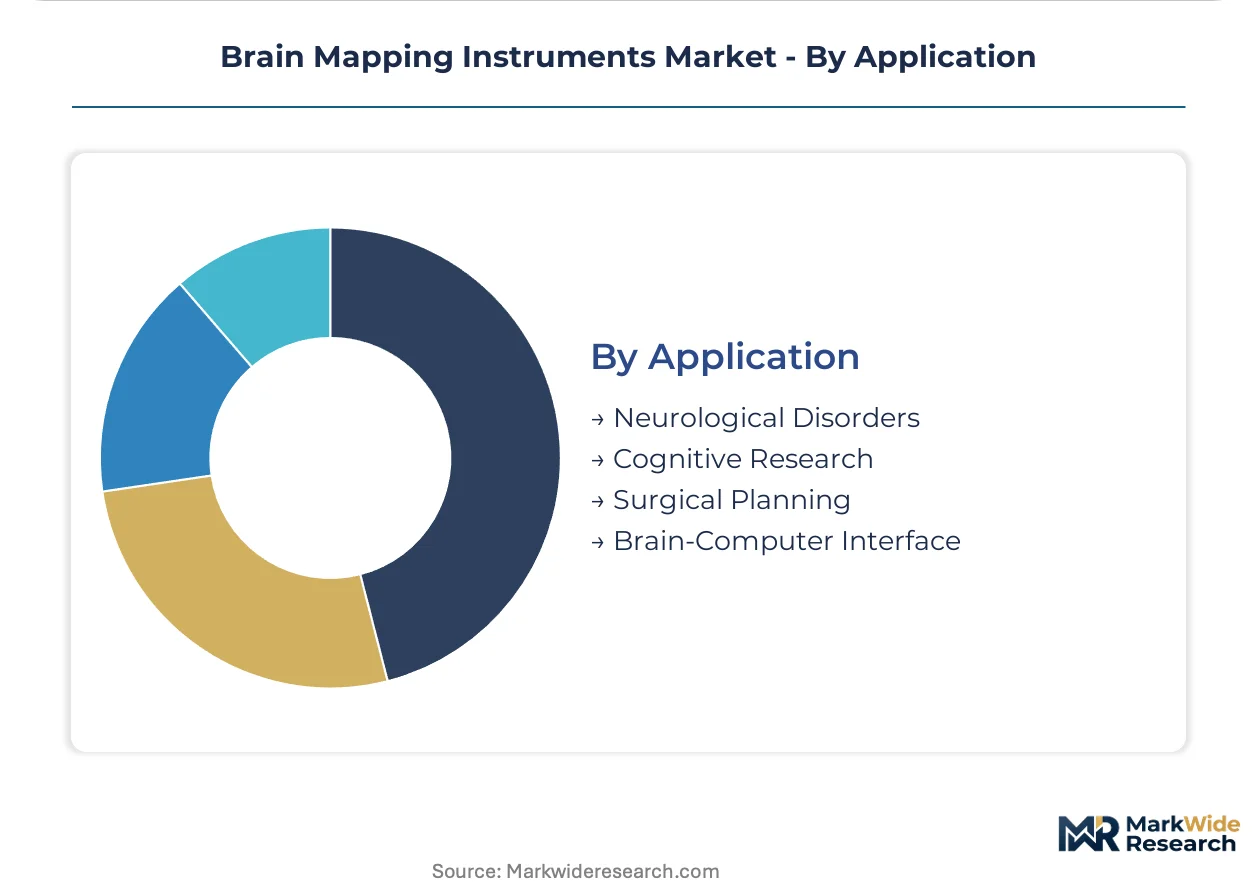
- Neurological Disorders:Epilepsy focus localization, dementia staging, and movement disorder assessment. FDA breakthrough device pathway compresses timelines for novel biomarker qualification.
- Surgical Planning:Eloquent cortex mapping prior to tumor resection or epilepsy surgery. Intraoperative EEG and fMRI demand concentrates at academic medical centers in Germany and Japan.
- Cognitive Research:Fundamental neural circuit mapping with limited immediate clinical translation. Dependent on federal funding cycles and grant renewal patterns.
- Brain-Computer Interface:Neural signal decoding for assistive communication and motor restoration. Japan's PMDA imposes supplementary pharmacovigilance expectations for long-implantable interfaces.
Neurological disorders anchor commercial value; brain-computer interface applications are gaining share fastest despite regulatory complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as EU MDR compliance costs push production planning toward jurisdictions with streamlined medical device pathways. The United States, Germany, Japan, China, and the United Kingdom concentrate demand and supply-side capacity through divergent incentive structures.
United States
NIH-funded brain research initiatives and private neurotechnology investment clusters drive institutional procurement of high-channel EEG and ultra-high-field MRI systems. FDA breakthrough device designation compresses premarket clearance timelines for novel neuroimaging biomarkers. Boston and San Francisco anchor algorithm development capacity for computational neuroscience applications.
Germany
Academic medical centers are expanding high-channel EEG procurement for epilepsy monitoring and pre-surgical mapping workflows. EU MDR clinical evidence requirements favor established notified body relationships, consolidating procurement around compliant vendors. Siemens Healthineers leverages magnet technology leadership from its Erlangen operations to dominate ultra-high-field MRI installations.
Japan
PMDA supplementary pharmacovigilance expectations for long-implantable neural interfaces create specialized regulatory pathways for brain-computer interface developers. Academic medical centers in Tokyo and Osaka are scaling high-channel system procurement for epilepsy monitoring. METI funding for neurotechnology R&D reinforces domestic manufacturing capacity.
China
NMPA medical device registration reforms are accelerating market entry timelines for imported neuroimaging platforms while building domestic EEG manufacturing capacity. Hospital procurement of fMRI systems concentrates at tertiary centers in Beijing and Shanghai. MIIT industrial policy targets captive superconducting magnet production to reduce import dependence.
United Kingdom
Medical Research Council neuroimaging infrastructure grants sustain research institute demand for MEG and high-density EEG systems. MHRA post-Brexit regulatory autonomy permits tailored pathways for AI-augmented diagnostic platforms. London and Cambridge clusters concentrate neural signal decoding talent for brain-computer interface development.
Brain Mapping Instruments Market Vendor Landscape
United States and German producers anchor the premium imaging systems tier; Japanese and Dutch specialists hold positions in ambulatory monitoring and diagnostic accessories. The vendor base concentrates around three strategic archetypes: integrated imaging conglomerates with captive magnet technology, mid-scale neurology-focused device manufacturers, and software-native platforms leveraging cloud architectures. Competitive dynamics center on M&A activity targeting EEG algorithm capabilities and strategic partnerships securing cyclotron infrastructure for PET radiotracer production.
Among integrated imaging conglomerates, GE Healthcare and Siemens Healthineers exemplify the magnet-technology-dependent archetype, while Koninklijke Philips occupies a position within the ambulatory monitoring specialization tier. These three anchors represent contrasting geographic origins and structural approaches to hardware-software value capture, with each sitting within distinct regulatory engagement strategies across FDA, EU MDR, and PMDA jurisdictions.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips |
| Medtronic |
| Natus Medical Incorporated |
| Advanced Brain Monitoring, Inc. |
| Nihon Kohden Corporation |
| Canon Medical Systems Corporation |
| Brain Products GmbH |
| Others |
Supply Flow & Price Mechanics
Magnet-technology conglomerates with captive superconducting expertise anchor pricing discipline through backward integration into helium-free production, compressing margin headroom for component challengers while concentrating procurement leverage at academic medical centers with multi-site research consortia.
Pricing Analysis
Distributor margins collapse toward single digits for standardized EEG electrode arrays, while direct-to-hospital pricing for ultra-high-field MRI systems sustains double-digit equipment markups bundled with decade-long service contracts. Three-tier pricing structure across premium, standard, and economy levels separates research-grade 256-channel systems from diagnostic 32-channel configurations and ambulatory sleep-monitoring accessories. Pricing pressure stems from academic medical centers unbundling software maintenance from capital purchases. Diagnostic centers exhibit highest price sensitivity; NIH-funded research institutes tolerate premium positioning for novel modalities.
Supply Chain Analysis
Single-source vulnerability sits with South African and Qatari helium production for superconducting magnet cooling, exposing MRI manufacturers to commodity volatility that feeds through to hospital capital budgets. Magnet wire fabrication concentrates in China and Japan, while SQUID sensor arrays for magnetoencephalography draw from specialized foundries in the United States and Germany. Tariff exposure on rare-earth magnet materials threatens MEG system cost structures. Distribution runs through regional imaging equipment distributors with certified biomedical engineering capabilities for installation and calibration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in brain mapping instruments rests on software-defined architectures collapsing hardware refresh cycles and shifting value capture toward recurring analytics revenue streams.
For Market Incumbents: Anchor competitive positioning through captive superconducting magnet production and ISO 13485 certification depth that EU MDR clinical evidence requirements favor. Defend against modular AI-native challengers by accelerating FDA breakthrough device submissions for novel biomarker extraction methods. Prioritize backward integration into helium-free cooling technology to neutralize supply volatility.
For New Entrants and Emerging Players: Contract research organizations in Boston and San Francisco offer the most penetrable channel partner type for algorithm-development partnerships with ultra-high-field MRI installations. Target ambulatory EEG configurations for sleep medicine clinics where reimbursement coding decisions remain pending. Pursue white-label signal processing modules for established hardware OEMs lacking cloud-native architectures.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale neurology-focused device manufacturers without demonstrated MDR compliance track records. Long-term viability over the coming decade hinges on securing favorable quantitative EEG reimbursement determinations. Monitor FDA coding decisions for AI-augmented image interpretation as the critical inflection signal separating commercially viable platforms from research-limited installations.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated premarket pathways compress clearance timelines for novel neuroimaging biomarkers at academic medical centers. |
| CE Marking Pathway under EU MDR | Clinical evidence requirements favor established notified body relationships and consolidate procurement around compliant vendors. |
| Hospital System Partnership | Multi-site research consortia negotiate centralized service frameworks that shift procurement toward recurring revenue models. |
| Software Companion Development | Cloud-native architectures enable unbundled software maintenance contracts beyond traditional capital equipment purchases. |
| Reimbursement Strategy | Coverage determinations for quantitative EEG metrics separate commercially viable platforms from research-limited installations. |
Methodological Framework
Bottom-up hospital and research institute procurement modeling reconciled against top-down OEM shipment tracking forms the analytical core, combining primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and epilepsy monitoring unit directors with secondary validation through FDA 510(k) filings, NIH grant award databases, CMS Medicare reimbursement schedules, and hospital capital expenditure disclosures.
Historical trendline analysis across technology adoption curves and capital equipment replacement cycles informs projection frameworks, with segmentation dimensions spanning product type, technology layer, end-user tier, and application area throughout the forecast period. CAGRs derive from equipment shipment volumes weighted by average selling price trajectories and service contract attach rates, incorporating helium supply volatility indices and regulatory pathway timelines as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NIH funding renewal patterns, EU MDR implementation delays, and breakthrough device designation award rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Medical Power Supply Market
Medical Equipment
Radiotherapy Motion Management Market
Medical Equipment
Solar Powered Vaccine Refrigerator Market
Medical Equipment
Medical Vending Machines Market
Medical Equipment
Global Ultra Low Temperature Freezers Market
Medical Equipment
Cryogenic Freezers Market
Medical Equipment
Europe Nuclear Medicine Equipment Market
Medical Equipment
Podiatry Equipment Market
Medical Equipment
Embedded Disinfection Cabinet Market
Medical Equipment
Tanning Units Market
Medical Equipment
North America Nuclear Medicine Equipment Market
Medical Equipment
Operating Table Parts Market
Medical Equipment
Autopsy Equipment Market
Medical Equipment
Global Plasma Sterilizers Market
Medical Equipment
Global Refrigerated Incubators Market
Medical Equipment
Nuclear Medicine Equipment Market