
 Filter Needles Market | 2026-2036
Filter Needles Market Size, Share, and Industry Trends Forecast 2026-2036
Filter Needles Market Intelligence
REACH compliance is consolidating the cost-of-entry calculus for European and export-oriented manufacturers, forcing material certification upgrades and supply chain documentation layers that smaller assemblers cannot absorb. Becton Dickinson and Company leverages its captive polymer compounding capability to navigate these requirements without external dependency. Terumo Corporation anchors its position through Japanese domestic production of stainless-steel cannulae with validated surface passivation protocols.
Filter needles are single-use hypodermic devices incorporating bonded microporous membranes, typically rated between 5 and 19 microns, designed to remove particulate contamination during parenteral medication preparation or laboratory fluid transfer. Stainless steel cannulae with electropolished bores dominate high-pressure applications, while polycarbonate hub assemblies reduce weight in safety-engineered configurations for home healthcare. Safety product types command premium positioning due to OSHA needlestick prevention mandates, whereas ventilated variants lead laboratory throughput metrics where air displacement during aspiration is critical.
FDA 21 CFR Part 4 quality system integration, EU MDR technical documentation requirements, and ISO 7864 dimensional standards collectively shape product development cycles and commercial access timelines across regulated jurisdictions. The EPA's evolving single-use medical device waste frameworks are beginning to influence hub material selection toward recyclable thermoplastics. Stakeholders must monitor regulatory divergence between US and European validation protocols when configuring regional manufacturing footprints.
Market Dynamics
Hospital consolidation and 503B outsourcing facility expansion are compressing procurement cycles while elevating compliance thresholds for sterile compounding filtration devices. These structural pressures favor manufacturers with captive polymer compounding and validated surface passivation capabilities.
Growth Catalysts
- OSHA needlestick prevention mandates:Safety-engineered filter needle variants command premium positioning across US healthcare systems, driving replacement cycles for legacy non-safety devices.
- 503B outsourcing facility proliferation:High-volume sterile compounding operations require ventilated filter needles with validated air displacement protocols, expanding addressable demand.
- Polycarbonate hub assemblies:Weight reduction in home healthcare configurations opens ambulatory and self-administration segments previously served by hospital-centric suppliers.
Market Restraints
- Stainless steel cannulae supply concentration:Japanese and German specialty metal processors control electropolished bore supply, creating single-source vulnerability for high-pressure applications.
- REACH compliance cost escalation:European material certification upgrades and supply chain documentation layers exceed smaller assembler absorption capacity, consolidating manufacturing toward integrated producers.
- Glass ampoule substitution:Pre-filled syringe adoption in biologics administration reduces aspiration-based filtration steps, compressing unit demand in oncology and immunology segments.
Strategic Opportunities
- Home healthcare expansion:Safety-engineered lightweight configurations address underpenetrated self-administration markets where patient handling error rates exceed hospital settings.
- EPA single-use medical device waste frameworks:Evolving recyclable thermoplastic hub requirements create first-mover advantage for manufacturers with circular material pipelines.
- Laboratory automation integration:Ventilated variants with validated air displacement protocols align with robotic liquid handling system throughput specifications in pharmaceutical QC workflows.
Industry Challenges
- ISO 7864 dimensional standard compliance:Regional validation protocol divergence between FDA 21 CFR Part 4 integration and EU MDR technical documentation extends product development timelines.
- Surface passivation technician scarcity:Validated electropolishing and chemical passivation protocols for stainless steel cannulae require specialized workforce development programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Filter Needles Market |
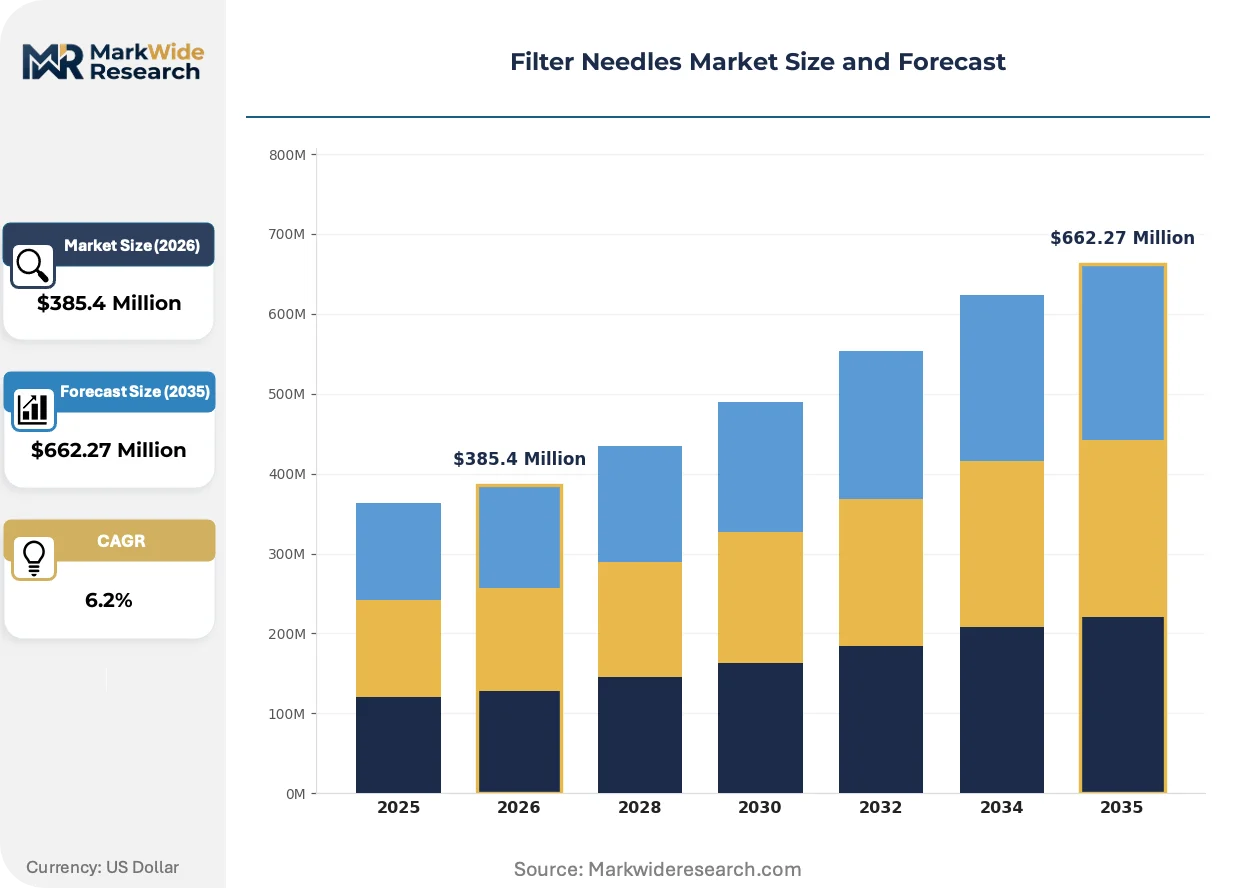
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ventilated, Non-Ventilated, Luer Lock, Safety Material: Plastic, Stainless Steel, Polycarbonate, Glass Application: Laboratory, Pharmaceutical, Veterinary, Home Healthcare End User: Hospitals, Clinics, Research Institutions, Pharmacies |
| Companies Covered | Nipro Medical Corporation, Baxter International Inc, Becton Dickinson and Company, SOL Millennium Medical Inc, Vygon SA, B Braun Medical Inc, Cardinal Health, ICU Medical Inc, Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Filter Needles Market Strategic Shifts & Innovations
Filter needle architecture is fragmenting into application-specific configurations as end-use verticals impose divergent performance specifications. Material science advances and regulatory waste frameworks are simultaneously reshaping hub composition and membrane bonding techniques.
Modular hub-and-cannula assemblies with interchangeable membrane ratings are modularizing inventory management for hospital pharmacies and 503B facilities. Compounders adopt 5-micron, 19-micron, and intermediate ratings from common platform bases rather than maintaining discrete device stockpiles. This standardization is compressing SKU proliferation while enabling rapid protocol switches between parenteral preparation types.
REACH substance restriction updates and the EU Green Deal circular economy action plan are accelerating thermoplastic hub material transitions. European manufacturers face mandatory recyclability disclosures and extended producer responsibility frameworks by 2030. The regulatory pressure is displacing legacy ABS formulations in favor of certified recyclable polycarbonate and bio-based alternatives in export-oriented production lines.
Consolidated health system procurement offices are unbundling safety-engineered filter needles from traditional distributor contracts. Direct manufacturer agreements with integrated delivery networks replace intermediated purchasing in the United States, compressing margin structures while demanding real-time utilization data exchange. This channel compression is most advanced in California and Texas health systems with centralized pharmacy operations.
Filter Needles Market Segmentation
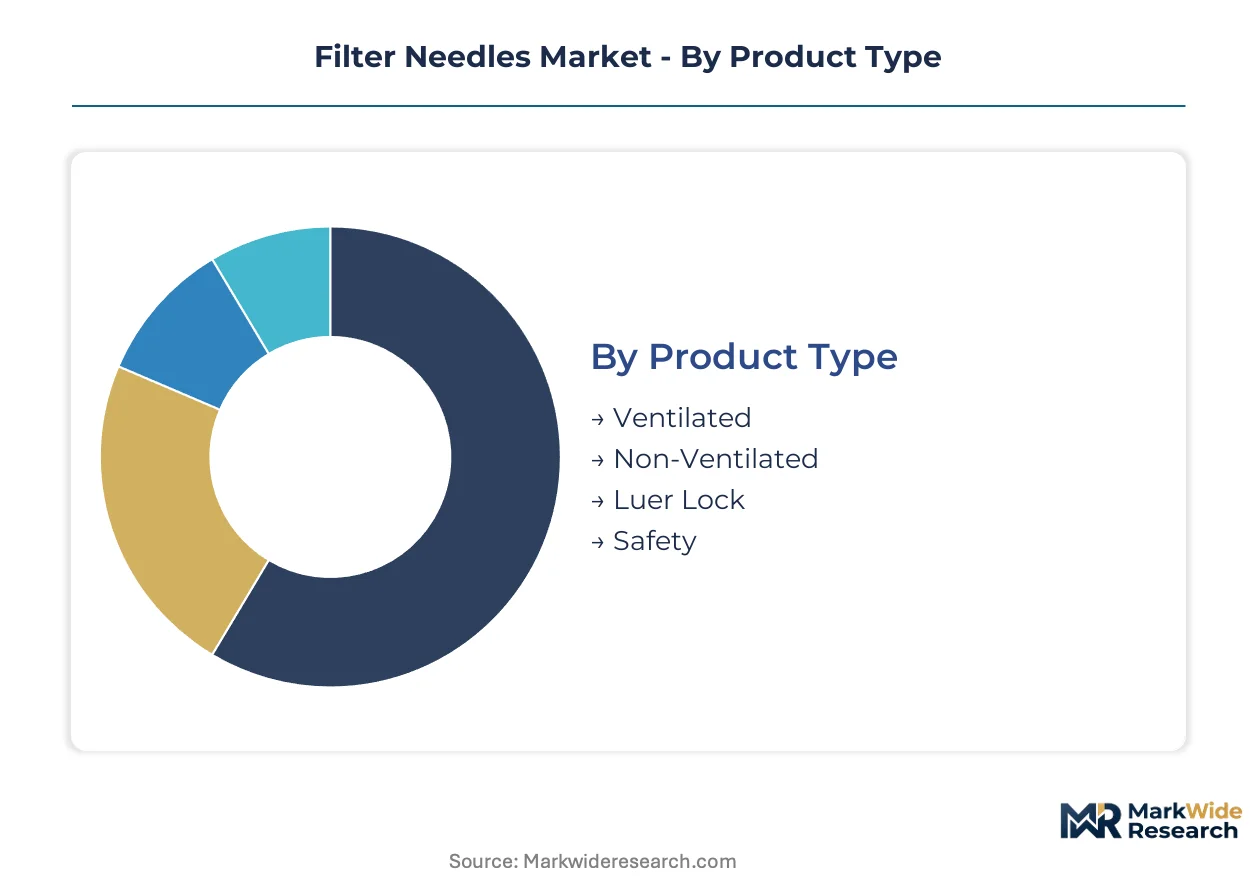
Filter needle segmentation reflects divergent performance requirements across sterile compounding, laboratory automation, and patient self-administration. Procurement patterns vary sharply between high-volume 503B outsourcing facilities and decentralized home healthcare settings.
Product Type:
The customization-vs-standardization spectrum runs from configurable ventilated systems to fixed-configuration safety devices with integrated retraction mechanisms.
- Ventilated:Incorporates hydrophobic membrane air displacement channels rated for rapid aspiration in high-throughput pharmaceutical QC workflows. Demand concentrates in United States 503B compounding facilities where validated air exchange protocols reduce vial pressure differentials during multi-dose preparation.
- Safety:Features integrated needlestick prevention mechanisms including hinged shields, sliding sleeves, or retractable cannulae meeting OSHA Bloodborne Pathogens Standard requirements. United States hospital systems mandate these configurations, compressing legacy non-safety device replacement cycles.
- Non-Ventilated:Standard closed-hub design for low-pressure applications without air displacement requirements.
- Luer Lock:Threaded hub interface ensuring secure syringe attachment in high-pressure injection scenarios.
Most installed capacity flows through Safety. Expansion is steepest in Ventilated.
Material:
Cost tier stratification separates premium electropolished metals from commodity thermoplastics, with recyclability premiums emerging at the top.
- Stainless Steel:Electropolished 304/316 grade cannulae with validated bore surface finish for high-pressure parenteral applications. Japanese and German specialty metal processors control supply, creating single-source vulnerability for pharmaceutical manufacturers requiring documented passivation protocols.
- Polycarbonate:Transparent, impact-resistant hub material enabling lightweight safety-engineered configurations for home healthcare self-administration. REACH substance restriction updates are accelerating certified recyclable polycarbonate adoption in European export production lines.
- Plastic:Lower-cost ABS and polypropylene formulations for single-use laboratory applications with minimal mechanical stress.
- Glass:Borosilicate hub assemblies for specialized chemical compatibility requirements in corrosive reagent handling.
Volume leadership sits with Stainless Steel. Margin expansion concentrates in Polycarbonate.
Application:
Customer type divergence separates regulated pharmaceutical manufacturing from decentralized veterinary and home settings with distinct validation burdens.
- Pharmaceutical:Sterile compounding operations requiring FDA 21 CFR Part 4 quality system integration and documented filtration validation for parenteral medication preparation. United States 503B outsourcing facility proliferation is expanding ventilated filter needle procurement cycles.
- Laboratory:Robotic liquid handling system integration demanding validated air displacement protocols and dimensional precision for automated QC workflows. Pharmaceutical research institutions in Massachusetts and California health corridors drive specification intensity.
- Home Healthcare:Patient self-administration of biologics and parenteral nutrition requiring lightweight, safety-engineered configurations with intuitive handling.
- Veterinary:Large-animal and companion animal clinical settings with reduced regulatory validation requirements compared to human pharmaceutical applications.
Revenue concentration rests in Pharmaceutical. Climbing the fastest is Home Healthcare.
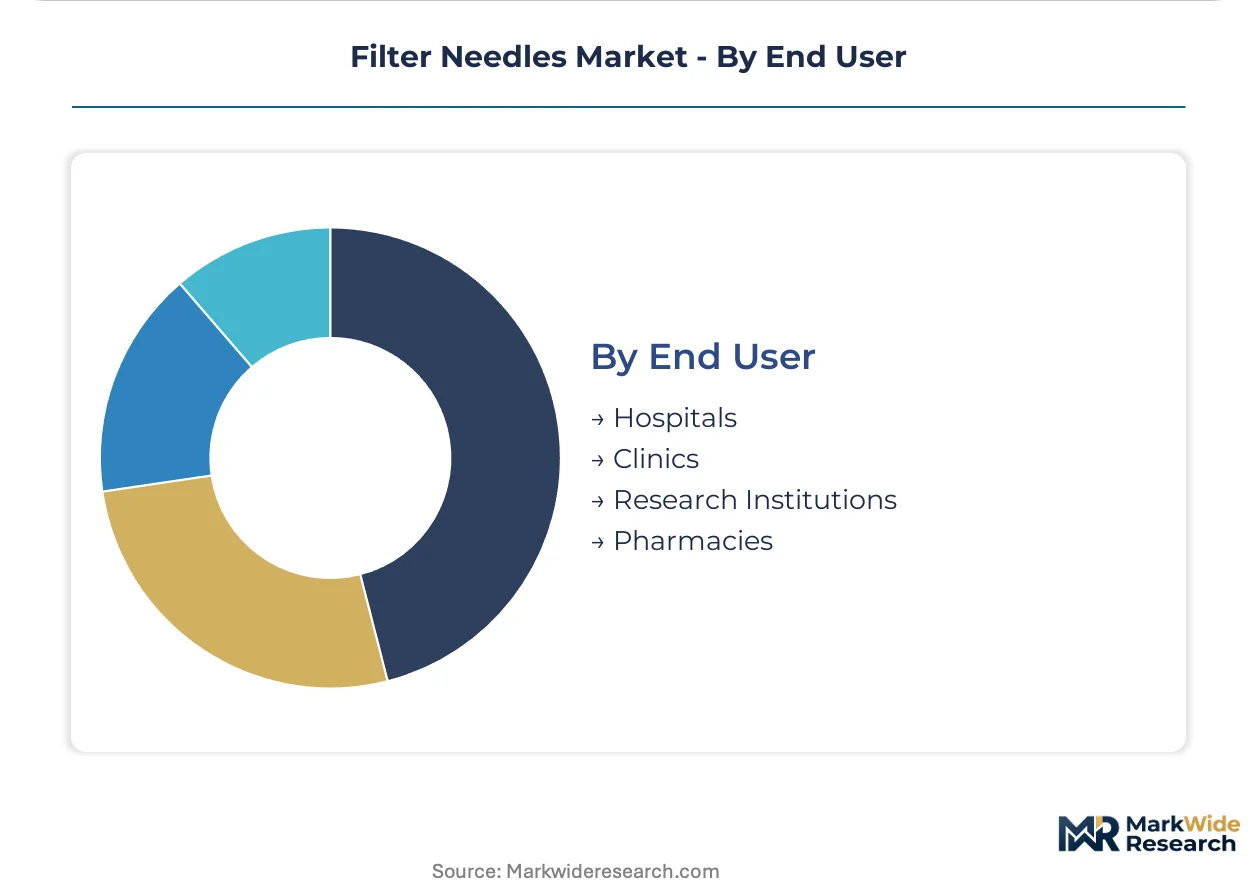
End User:
Geography of demand maps to regulatory jurisdiction density, with United States hospital consolidation and European REACH compliance creating divergent procurement patterns.
- Hospitals:Integrated delivery networks with consolidated procurement offices unbundling filter needle contracts from traditional distributor agreements. California and Texas health systems with centralized pharmacy operations lead direct manufacturer agreement adoption.
- Research Institutions:Academic and government laboratories with modular hub-and-cannula inventory systems enabling rapid protocol switches between 5-micron and 19-micron membrane ratings.
- Clinics:Outpatient settings with lower volume throughput and reduced sterile compounding complexity compared to hospital pharmacies.
- Pharmacies:Retail and specialty pharmacy operations with emerging home healthcare dispensing responsibilities requiring patient training on safety-engineered device handling.
Procurement scale peaks in Hospitals. Specification intensity is highest in Research Institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized electropolishing technicians and validated surface passivation chemists concentrate in industrial clusters where pharmaceutical manufacturing and precision metalworking intersect. Their geographic distribution shapes regional competitive advantage in high-pressure filter needle production.
United States
Hospital consolidation and 503B outsourcing facility expansion drive procurement volume in California and Texas health systems with centralized pharmacy operations. OSHA needlestick prevention mandates enforce safety-engineered device adoption across integrated delivery networks. The Massachusetts and California health corridors host pharmaceutical research institutions demanding specification-intensive ventilated variants for robotic QC workflows.
Germany
Specialty metal processors in Baden-Württemberg control electropolished bore supply for high-pressure pharmaceutical applications. REACH substance restriction updates and EU MDR technical documentation requirements exceed smaller assembler capacity, consolidating manufacturing toward integrated producers. The country's national pharmaceutical regulator enforces stringent validation protocols that extend product development timelines for export-oriented manufacturers.
Japan
Domestic production of stainless-steel cannulae with validated surface passivation protocols anchors supply security for pharmaceutical manufacturers. METI industrial standards and PMDA quality system requirements shape technical documentation burdens for device commercialization. The Kansai and Chubu industrial regions concentrate precision metalworking capabilities serving both domestic biopharma and export markets.
China
Biologics manufacturing expansion and domestic pharmaceutical compounding growth create demand for filtration devices across Yangtze River Delta pharmaceutical clusters. NMPA quality system integration and GB standards compliance shape product registration timelines for multinational and domestic manufacturers. Shanghai and Suzhou biopharma corridors drive specification intensity for ventilated variants in high-throughput sterile compounding.
India
Contract manufacturing organization expansion and domestic sterile compounding growth generate procurement cycles for cost-optimized filter needle configurations. CDSCO medical device rules and BIS standards compliance create regulatory entry barriers for export-oriented assemblers. Maharashtra and Gujarat pharmaceutical manufacturing zones concentrate formulation facilities requiring validated filtration devices for parenteral preparation.
Filter Needles Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidated health system procurement offices favor manufacturers with captive polymer compounding and validated surface passivation capabilities. Three archetypes dominate: integrated medical device conglomerates with backward material control, regional specialists in stainless-steel cannulae processing, and safety-engineered configuration innovators. Competitive moves concentrate on direct manufacturer agreements with integrated delivery networks and modular hub-and-cannula platform standardization.
Among diversified medical technology conglomerates, Becton Dickinson and Company and Baxter International Inc. exemplify integrated producers with captive supply chain capabilities. Terumo Corporation occupies a position among precision metalworking specialists with domestic Japanese production of validated cannulae. These three anchors represent distinct strategic postures: material integration, geographic supply security, and specialized process validation.
| Leading Market Players |
|---|
| Nipro Medical Corporation |
| Baxter International Inc |
| Becton Dickinson and Company |
| SOL Millennium Medical Inc |
| Vygon SA |
| B Braun Medical Inc |
| Cardinal Health |
| ICU Medical Inc |
| Terumo Corporation |
| Others |
Cost & Logistics Intelligence
EPA evolving single-use medical device waste frameworks gate qualified supply for premium-tier filter needle configurations, forcing manufacturers with certified recyclable polycarbonate pipelines to command pricing power while legacy ABS assemblers face margin compression from compliance exclusion.
Pricing Analysis
The bundled-vs-unbundled service split separates traditional distributor-mediated contracts from direct manufacturer agreements with integrated delivery networks. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale. Cost compression in safety-engineered configurations is intensifying because consolidated health system procurement offices demand real-time utilization data exchange. Hospital pharmacies exhibit highest price sensitivity, while 503B outsourcing facilities prioritize validated air displacement protocols over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and German specialty metal processors controlling electropolished bore supply for high-pressure pharmaceutical applications. Manufacturing gravity centers on Japan, Germany, and the United States for stainless steel cannulae, with polycarbonate hub assembly concentrating in domestic European and North American facilities. Raw material dependencies draw from electropolished 304/316 grade stainless steel, certified recyclable polycarbonate resins, and hydrophobic membrane substrates. Tariff exposure on precision metal imports from Japan threatens cost stability for high-pressure device manufacturers. Distribution runs through consolidated health system procurement offices and 503B facility direct agreements, displacing traditional medical device distributors in volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Filter needle economics favor margin expansion through polycarbonate hub lightweighting and safety-engineered premium positioning, with EPA recyclable thermoplastic mandates accelerating cost-down migration from legacy ABS formulations.
For Market Incumbents: Deploy captive polymer compounding capability to absorb REACH compliance cost escalation without external certification dependency. Consolidate manufacturing footprints toward integrated producers with validated surface passivation protocols, as Japanese and German metal processor concentration creates supply security premiums. Defend against pre-filled syringe substitution in biologics by emphasizing aspiration-based filtration validation for compounded parenterals. For New Entrants and Emerging Players: Home healthcare distributors represent the most penetrable channel partner type for safety-engineered lightweight configurations, given patient handling error rates exceed hospital settings and incumbent focus remains institutional. Target underpenetrated self-administration markets in California and Texas health corridors where centralized pharmacy operations create specification intensity. Pursue modular hub-and-cannula platform standardization to compress SKU proliferation for 503B facilities. For Investors and Strategic Acquirers: Roll-up economics work for regional stainless-steel cannulae specialists with validated electropolishing protocols because surface passivation technician scarcity creates durable competitive moats. Five-to-ten year viability hinges on EPA waste framework compliance and EU Green Deal circular economy positioning. Watch NMPA quality system integration timelines in China as inflection indicator for Asia-Pacific manufacturing footprint expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Hub-and-Cannula Platform Standardization | Enables 503B facilities to switch between 5-micron and 19-micron ratings without discrete inventory stockpiles. |
| Certified Recyclable Polycarbonate Transition | Aligns hub material selection with EPA single-use medical device waste frameworks and EU Green Deal mandates. |
| Direct Manufacturer Agreement with IDNs | Bypasses traditional distributor intermediation in California and Texas consolidated health system procurement. |
| Validated Surface Passivation Protocol Investment | Secures electropolished bore supply security against Japanese and German specialty metal processor concentration. |
| Home Healthcare Safety-Engineered Configuration Launch | Addresses patient handling error rates exceeding hospital settings in underpenetrated self-administration segments. |
Research Approach
Coverage spans the United States, Germany, Japan, China, and India, with primary inputs from each market cluster combined with secondary validation. Interviews incorporated sterile compounding pharmacists, 503B facility operations directors, hospital GPO contracts managers, and biomedical engineers alongside precision metalworking specialists. Secondary sources included FDA 21 CFR Part 4 quality system documentation, EU MDR technical filing databases, EPA single-use medical device waste framework dockets, and ISO 7864 dimensional standard repositories. Bottom-up facility-level procurement data triangulated against top-down manufacturer shipment estimates.
Granularity-level modeling deployed product type, material grade, application vertical, and end-user channel dimensions at the country level, with membrane rating specifications tracked for ventilated variant segmentation. CAGRs derived from regression analysis of historical procurement cycles against regulatory compliance cost trajectories across the analysis window. Forecast inputs incorporated OSHA needlestick prevention mandate enforcement intensity, 503B outsourcing facility licensing velocity, and REACH substance restriction update timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to pre-filled syringe adoption curves in oncology and immunology, glass ampoule substitution rates, and surface passivation technician pipeline development. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
North America Medical Clothing Market
Medical Supplies
Middle East and Africa Surgical Sutures Market
Medical Supplies
Compression Garments and Stockings Market
Medical Supplies
Respiratory Masks Market
Medical Supplies
Autoclaving Trays Market
Medical Supplies
Crutch Pads Market
Medical Supplies
Global Synthetic Absorbable Sutures Market
Medical Supplies
Cell Culture Media Bags Market
Medical Supplies
Global Biohazard Bag Market
Medical Supplies
Finger Splint Market
Medical Supplies
US Healthcare Personal Protective Equipment Market
Medical Supplies
Medical Tapes and Bandages Market
Medical Supplies
Japan Hospital Supplies Market
Medical Supplies
Disposable Masks Market
Medical Supplies
Port Access Needles Market
Medical Supplies
Surgical Collagen Powders Market