
 Global Dental Sterilization Market | 2026-2036
Global Dental Sterilization Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dental Sterilization Market Foresight
Instrument reprocessing service contracts is pivoting toward subscription-based maintenance models that bundle preventive calibration, software updates, and compliance documentation. STERIS leverages its installed base of autoclaves to lock in multi-year service revenue. Tuttnauer competes through aggressive channel positioning in mid-sized dental laboratories. Getinge anchors the premium segment with hospital-grade sterilization systems adapted for high-volume oral surgery centers.
Dental sterilization encompasses the elimination of all microbial life from reusable instruments through thermal, chemical, or radiation-based processes, typically validated against biological indicators containing Geobacillus stearothermophilus spores to confirm lethality. Steam sterilization at 121–134°C under pressurized saturated vapor remains the dominant clinical protocol due to its reliability, cost efficiency, and compatibility with most metallic dental handpieces and burs. Autoclaves command the largest product category share while plasma sterilization represents the fastest-expanding technology segment, driven by instrument compatibility advantages for heat-sensitive polymers and electronic components used in guided surgery. End-user demand concentrates in private practices, though dental laboratories are capturing disproportionate margin expansion through centralized reprocessing services.
FDA 510(k) clearance requirements for sterilization equipment, the EU Medical Device Regulation (MDR) reclassification of reusable surgical instruments, and ISO 17665 steam sterilization validation standards collectively elevate compliance costs and consolidate procurement toward validated system suppliers. The EPA regulates chemical sterilizer effluent discharge, particularly for glutaraldehyde and ortho-phthalaldehyde solutions, pushing clinics toward closed-system autoclaves. Stakeholders must monitor evolving MDR technical documentation requirements and FDA cybersecurity guidance for networked sterilization equipment as connectivity becomes standard.
Market Dynamics
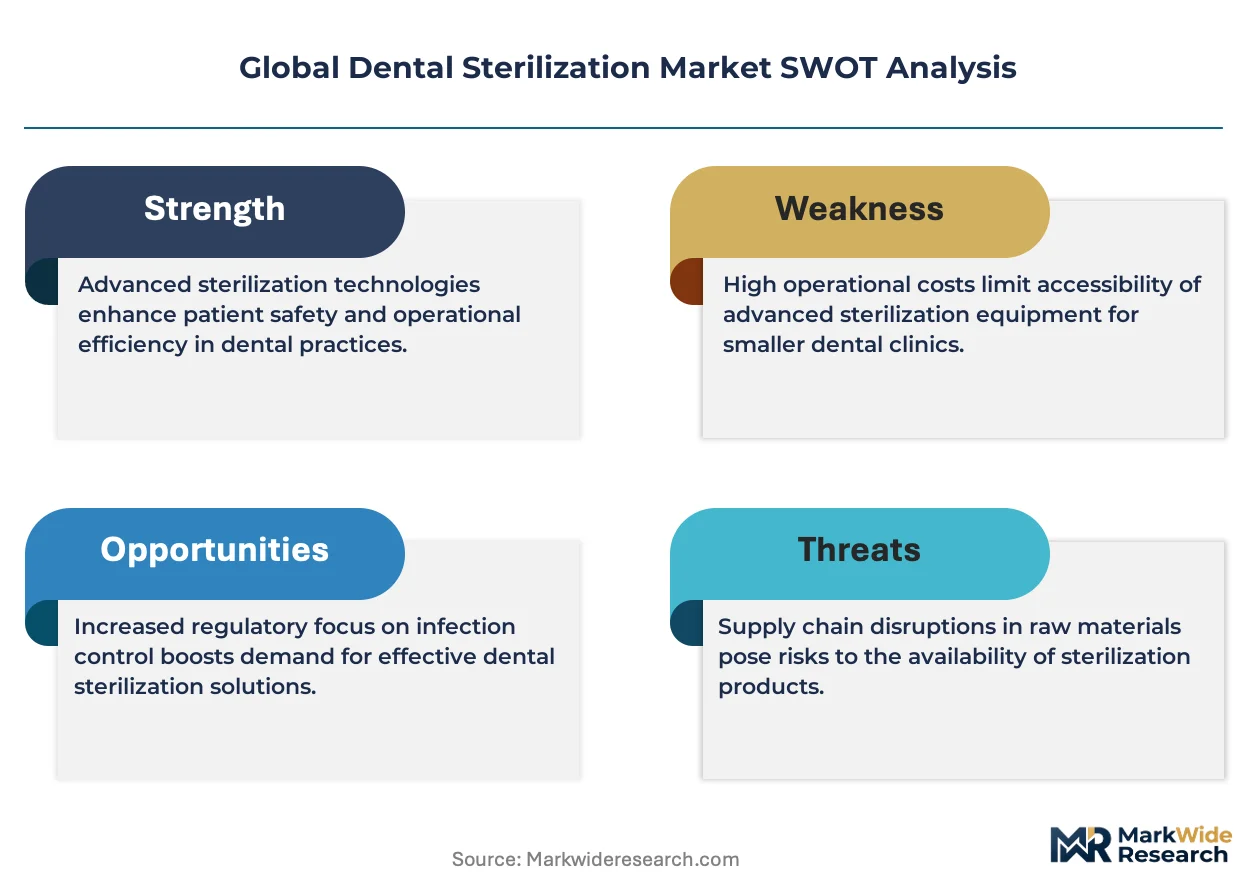
Subscription-based service contracts are displacing capital-heavy equipment purchases as dental clinics seek predictable operating expenditures and bundled compliance documentation. Steam autoclave manufacturers now capture recurring revenue through multi-year maintenance agreements that lock in instrument reprocessing workflows.
Growth Catalysts
- FDA 510(k) cybersecurity guidance:Networked sterilization equipment mandates drive replacement cycles for legacy autoclaves lacking connectivity infrastructure. Dental group practices accelerate procurement to meet documentation requirements.
- Heat-sensitive polymer proliferation:Guided surgery instruments incorporating electronic sensors require plasma sterilization protocols incompatible with traditional steam cycles. Oral surgery centers expand low-temperature reprocessing capacity.
- Centralized laboratory reprocessing:Germany's dental laboratories capture margin expansion through regional sterilization hubs serving multiple private practices. Economies of scale reduce per-instrument processing costs below in-clinic alternatives.
Market Restraints
- Stainless steel input volatility:Autoclave chamber fabrication depends on medical-grade 316L stainless steel pricing, which fluctuates with nickel commodity markets. Chinese foundry concentration amplifies supply risk.
- EU MDR technical documentation burdens:Reusable surgical instrument reclassification demands extensive clinical evidence for sterilization validation. Small equipment manufacturers face compliance cost barriers.
- Glutaraldehyde effluent restrictions:EPA discharge regulations for chemical sterilizer wastewater push clinics toward capital-intensive closed-loop autoclave systems. Liquid chemical sterilization contracts in high-regulation jurisdictions.
Strategic Opportunities
- India's dental infrastructure expansion:Government health scheme coverage extension creates demand for affordable sterilization equipment in tier-2 and tier-3 cities. CDSCO streamlined medical device registration accelerates market entry.
- AI-enabled cycle optimization:Machine learning integration with autoclave load sensors reduces energy consumption and extends chamber lifespan. Cloud-connected units transmit performance data for predictive maintenance scheduling.
- Mobile sterilization units:Rural health delivery programs in Brazil require portable steam sterilization for field dental camps. ANVISA emergency use pathways facilitate rapid deployment authorization.
Industry Challenges
- Biomedical technician scarcity:Specialized calibration and biological indicator testing expertise concentrates in urban hospital systems. Private dental practices struggle to retain qualified maintenance personnel.
- Legacy equipment interoperability:Networked sterilization management systems face integration friction with decade-old autoclave hardware lacking digital output ports. Partial fleet upgrades create workflow fragmentation.
- ISO 17665 validation timelines:Steam sterilization protocol documentation for new instrument geometries requires extended laboratory testing. Product launch schedules stretch to accommodate third-party verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dental Sterilization Market |
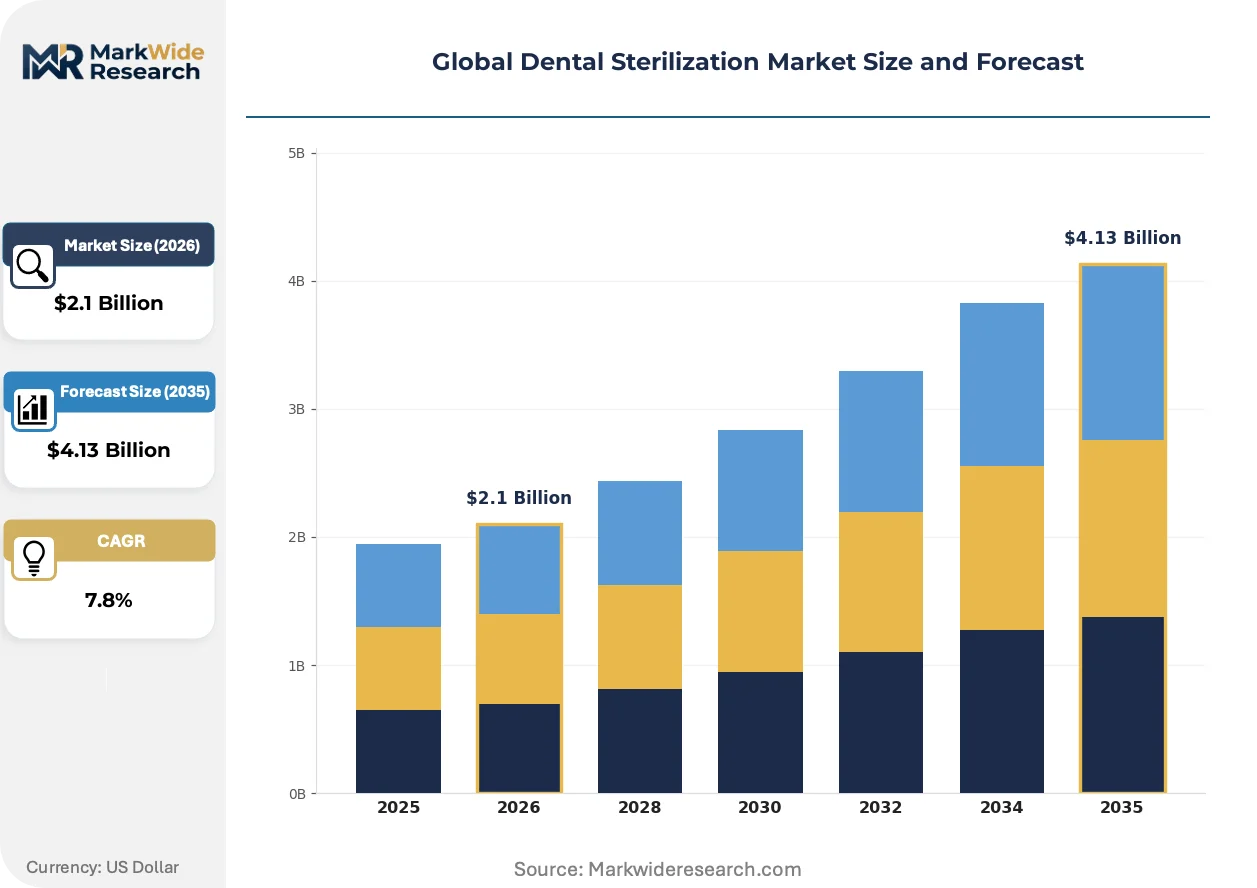
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autoclaves, Chemical Sterilizers, Dry Heat Sterilizers, Ultrasonic Cleaners, Radiation Sterilizers Application: Dental Clinics, Orthodontic Centers, Oral Surgery, Prosthodontics, Endodontics End User: Private Practices, Dental Laboratories, Community Health Centers, Academic Institutions, Mobile Clinics Technology: Steam Sterilization, Chemical Vapor Sterilization, Ethylene Oxide Sterilization, Ozone Sterilization, Plasma Sterilization |
| Companies Covered | Getinge, Tuttnauer, STERIS, Midmark, SciCan, Dentsply Sirona, Hu-Friedy, Planmeca, Matachana, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dental Sterilization Market Shifts & Advancements
Low-temperature sterilization modalities are capturing share from conventional steam protocols as instrument complexity outpaces thermal tolerance. Plasma and vaporized hydrogen peroxide systems address compatibility gaps for polymer-intensive dental technologies.
Plasma sterilization technology is modularizing around hydrogen peroxide vapor chambers sized for outpatient clinic footprints. Oral surgery centers in the United States adopt these units to process heat-sensitive navigation arrays and 3D-printed surgical guides. Equipment footprint compression enables reprocessing capacity expansion within existing utility rooms.
EU MDR Annex I general safety and performance requirements are forcing sterilization equipment manufacturers to redesign technical documentation architectures. Biological indicator validation protocols now demand traceable supply chain records for Geobacillus stearothermophilus spore sourcing. German and French notified bodies apply heightened scrutiny to reusable instrument reprocessing claims.
After-sales service unbundling is separating preventive maintenance from capital equipment transactions. Dental group purchasing organizations negotiate standalone calibration contracts with third-party biomedical service firms. This pattern concentrates in the United States where multi-site practice networks seek vendor-agnostic technical support.
Global Dental Sterilization Market Segmentation
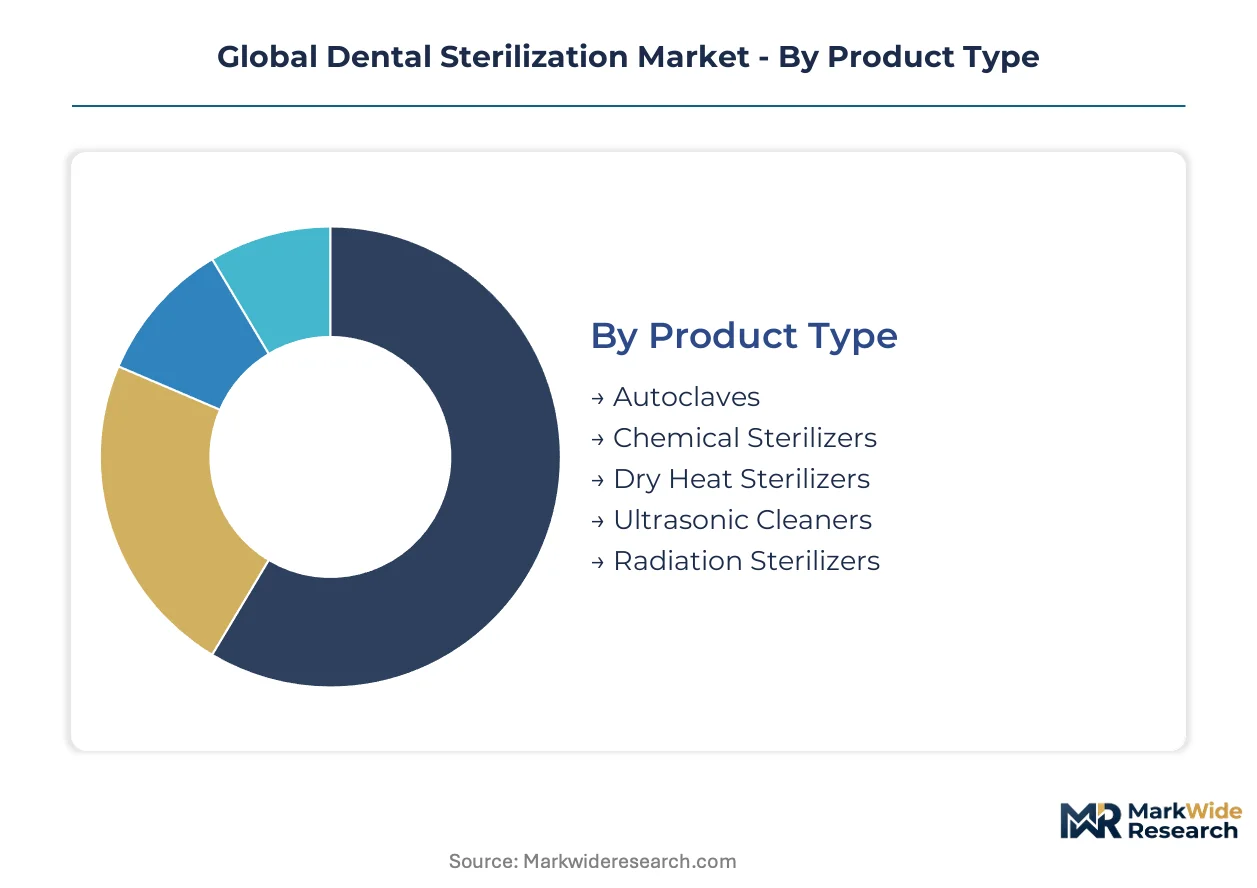
Dental sterilization procurement splits sharply between high-volume steam autoclave installations and premium low-temperature systems serving specialized surgical workflows. Understanding these segment boundaries reveals where equipment margins concentrate and where replacement cycles accelerate.
Product Type:
Volume concentration favors standardized chamber designs, while premium pricing attaches to specialized modalities addressing instrument compatibility constraints.
- Autoclaves:Saturated steam chambers operating at 121–134°C dominate installed base metrics across private dental practices in the United States and Germany. Chamber reliability and consumable availability drive replacement decisions toward established suppliers with dense service networks.
- Chemical Sterilizers:Liquid immersion systems using glutaraldehyde or ortho-phthalaldehyde retain niche positioning for heat-sensitive fiber-optic endoscopes in oral surgery suites. EPA effluent discharge regulations in California and New York constrain new installations.
- Dry Heat Sterilizers:Convection ovens at 160–190°C serve small-volume practices with corrosion-sensitive carbon steel instruments.
- Ultrasonic Cleaners:Cavitation-based pre-sterilization debris removal units precede autoclave cycles in high-throughput German dental laboratories.
- Radiation Sterilizers:Gamma and electron beam systems remain confined to industrial-scale dental implant packaging operations.
Mature deployment sits with Autoclaves. Newer deployment is concentrated in Ultrasonic Cleaners as pre-sterilization protocols tighten.
Application:
Procedure complexity determines sterilization protocol stringency, with invasive interventions demanding validated biological indicator documentation.
- Dental Clinics:General practice settings in China's tier-1 cities deploy compact tabletop autoclaves for handpiece and bur reprocessing. Volume procurement concentrates through dental supply distributors serving multi-site practice networks.
- Oral Surgery:Bone-implant contact procedures mandate hospital-grade sterilization validation with implant drill protocol documentation. United States ambulatory surgery centers drive demand for plasma-compatible low-temperature systems.
- Orthodontic Centers:Removable appliance sterilization favors smaller-capacity units with rapid cycle turnaround.
- Prosthodontics:Crown and bridge fabrication requires instrument sets with cement residue removal before sterilization.
- Endodontics:Nickel-titanium file reprocessing demands precise thermal profiles to preserve metallurgical properties.
Revenue concentration clusters around Oral Surgery. Fastest expansion is occurring in Dental Clinics as China's private healthcare infrastructure scales.
End User:
Capital availability and regulatory exposure create distinct procurement patterns across ownership structures.
- Private Practices:Solo and small-group clinics in France and Italy prioritize equipment footprint minimization over throughput capacity. Subscription-based maintenance contracts displace outright purchase financing.
- Dental Laboratories:Centralized reprocessing hubs in Germany's Baden-Württemberg region achieve per-instrument cost economies below in-clinic alternatives through batch optimization.
- Community Health Centers:Federally qualified health centers in the United States access sterilization equipment through group purchasing organization contracts.
- Academic Institutions:Dental schools require training-compatible units with transparent chamber observation and cycle interruption capability.
- Mobile Clinics:Field dental camps in Brazil's rural health programs deploy portable steam sterilization with generator-compatible power requirements.
Procurement standardization dominates Private Practices. Margin expansion is concentrating in Dental Laboratories through regional hub consolidation.
Technology:
Thermal tolerance thresholds of contemporary instruments are forcing modality diversification beyond traditional steam protocols.
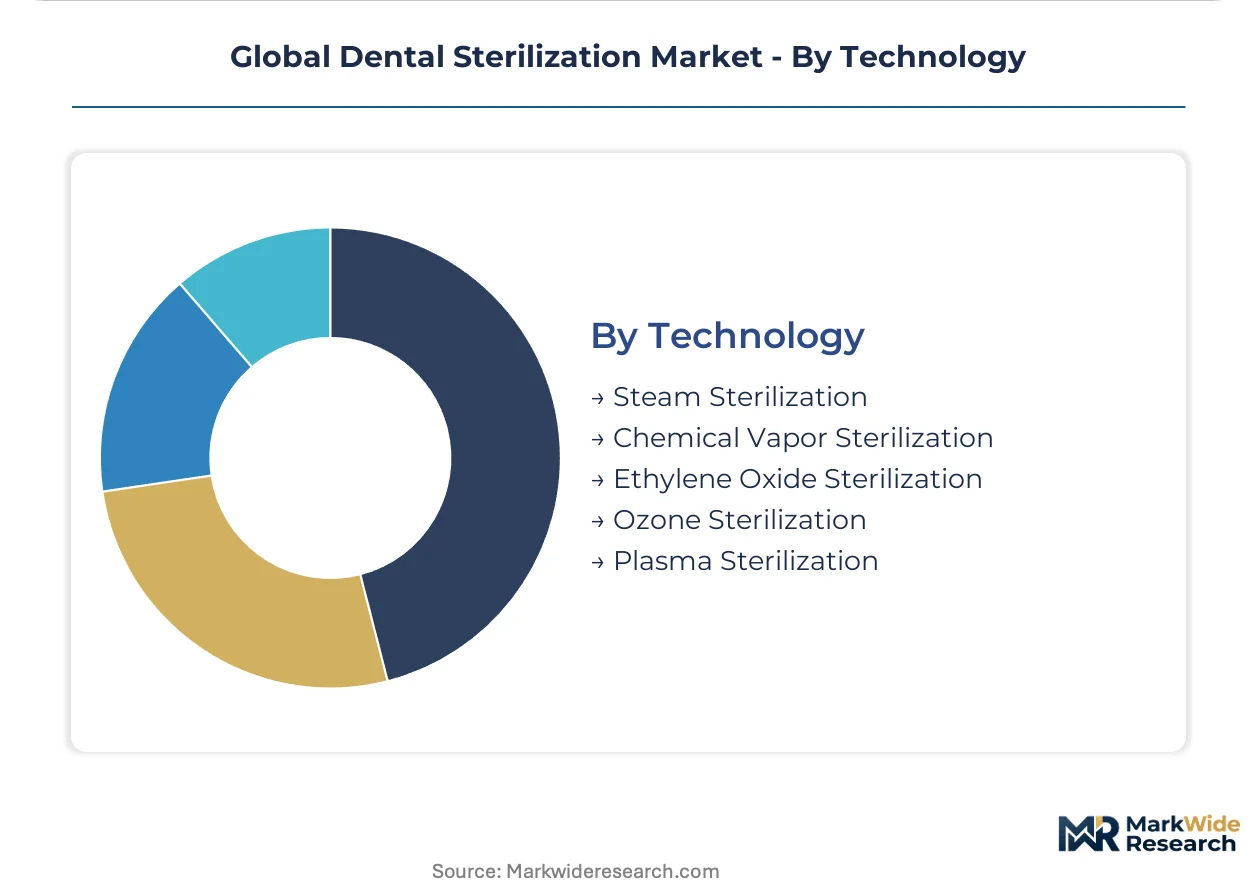
- Steam Sterilization:Pressurized saturated vapor at 121°C for 15 minutes or 134°C for 3 minutes remains the reference standard validated against Geobacillus stearothermophilus biological indicators. Compatibility with metallic handpieces sustains dominance across United States and German installed bases.
- Plasma Sterilization:Hydrogen peroxide vapor plasma cycles at 45–50°C accommodate polymer-embedded electronics in guided surgery navigation arrays. United States oral surgery centers adopt these systems despite higher per-cycle consumable costs.
- Chemical Vapor Sterilization:Formaldehyde-alcohol mixtures at 132°C serve instrument sets with combined metallic and elastomeric components.
- Ethylene Oxide Sterilization:Low-temperature gas diffusion remains limited to industrial-scale dental material sterilization due to aeration time requirements.
- Ozone Sterilization:Aqueous ozone systems gain traction in environmentally regulated European jurisdictions seeking effluent reduction.
Validation maturity concentrates in Steam Sterilization. Steepest expansion trajectory belongs to Plasma Sterilization as instrument electronics proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabrication clusters in Germany and the United States, while consumption growth concentrates in China's expanding private dental infrastructure and India's tier-2 city networks. Regulatory divergence between FDA 510(k) pathways and EU MDR compliance timelines shapes regional procurement patterns.
United States
Ambulatory surgery centers in Texas and Florida drive demand for plasma-compatible sterilization systems as guided oral surgery expands. FDA cybersecurity guidance for networked medical devices accelerates replacement cycles for legacy autoclave installations. The Dallas-Fort Worth metroplex hosts concentrated dental group practice networks negotiating multi-site service contracts.
Germany
Baden-Württemberg's dental laboratories operate regional sterilization hubs achieving per-instrument cost economies below in-clinic processing. EU MDR technical documentation requirements for reusable surgical instruments elevate compliance costs and consolidate procurement toward validated system suppliers. Stuttgart's precision manufacturing corridor supplies medical-grade 316L stainless steel chambers to domestic autoclave fabricators.
China
Tier-1 cities Beijing and Shanghai deploy compact tabletop autoclaves across expanding private dental clinic networks. NMPA streamlined medical device registration accelerates market entry for domestic sterilization equipment manufacturers. The Yangtze River Delta concentration of dental instrument foundries creates integrated supply chains for autoclave chamber production.
India
Government health scheme coverage extension generates demand for affordable sterilization equipment in tier-2 and tier-3 cities including Pune and Jaipur. CDSCO regulatory harmonization with international standards reduces import clearance timelines for European and American equipment suppliers. Maharashtra's dental college network trains biomedical technicians for regional maintenance capacity.
Brazil
Rural health delivery programs in Minas Gerais and Bahia deploy portable steam sterilization units for field dental camps. ANVISA emergency use pathways facilitate rapid deployment authorization for mobile sterilization equipment. São Paulo's private dental clinic concentration drives subscription-based maintenance contract adoption.
Global Dental Sterilization Market Competitive Landscape
Capital-heavy chamber fabricators compete with asset-light service integrators across divergent margin structures. The vendor base concentrates around three tiers: multinational sterilization system suppliers with dense service networks, regional equipment specialists capturing mid-market dental laboratories, and emerging Asian manufacturers competing on acquisition cost. Consolidation pressures favor players bundling preventive maintenance with capital equipment transactions. Technology licensing agreements and backward integration into biological indicator supply represent dominant competitive vectors.
Among multinational system suppliers, Getinge exemplifies the premium-tier archetype through hospital-grade sterilization platforms adapted for high-volume oral surgery centers. STERIS occupies a position within the installed-base monetization tier, leveraging dense autoclave fleets to secure multi-year service revenue streams. Tuttnauer represents mid-market channel specialists competing through aggressive positioning in dental laboratories across Germany and North America. These three anchors illustrate divergent strategic postures: premium validation, recurring revenue capture, and regional volume penetration.
| Leading Market Players |
|---|
| Getinge |
| Tuttnauer |
| STERIS |
| Midmark |
| SciCan |
| Dentsply Sirona |
| Hu-Friedy |
| Planmeca |
| Matachana |
| Others |
Supply & Pricing Matrix
Backward integration into medical-grade 316L stainless steel sourcing anchors both supply security and pricing power for autoclave fabricators in Germany and the United States, while outsourced chamber production in China's Yangtze River Delta creates cost-down pressure on economy-tier equipment. This divergence between captive metallurgical supply and contract manufacturing shapes tiered pricing stratification across premium validation-grade systems and commoditized tabletop units.
Pricing Analysis
Margin tightening in economy-tier autoclaves traces to Chinese foundry overcapacity and aggressive domestic manufacturer pricing in tier-2 city markets. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated hospital-grade systems from CE-marked laboratory equipment and basic NMPA-registered tabletop units. Dental group purchasing organizations in the United States exert acute price sensitivity through consolidated multi-site procurement, while oral surgery centers absorb premium positioning for plasma-compatible low-temperature systems.
Supply Chain Analysis
Domestic-content mandates under India's Production Linked Incentive scheme for medical devices are reshaping sourcing patterns, pushing European suppliers toward joint ventures with Maharashtra-based fabricators. Medical-grade 316L stainless steel draws from German and Chinese metallurgical clusters, while hydrogen peroxide plasma consumables hinge on specialized chemical supply from Belgium and the United States. Single-source vulnerability concentrates in biological indicator spore supply chains anchored to proprietary Geobacillus stearothermophilus strains. Distribution runs through dental supply distributors serving multi-site practice networks, with service contract bundling displacing pure equipment transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around validated system suppliers as EU MDR technical documentation burdens force sub-scale equipment manufacturers toward exit. Compliance cost escalation favors players with dense service networks and captive biological indicator supply.
For Market Incumbents: To counter emerging Asian manufacturers competing on acquisition cost in India's tier-2 cities, STERIS and Getinge should deepen backward integration into biological indicator production and expand calibration service density through third-party biomedical technician certification programs. Channel control through exclusive distributor agreements in Baden-Württemberg's laboratory hub secures recurring revenue against price erosion. For New Entrants and Emerging Players: A mid-market price-point gap between Getinge's premium plasma systems and economy Chinese autoclaves creates white-space opportunity for modular hydrogen peroxide vapor units sized for outpatient clinic footprints. Brazil's rural health delivery programs and India's government health scheme extension represent the most penetrable geographies. ANVISA emergency use pathways and CDSCO streamlined registration offer rapid deployment authorization without full validation burden. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by multinational sterilization system suppliers seeking regional service network density. Long-term viability over the next decade favors targets with validated ISO 17665 documentation architectures and installed bases convertible to subscription maintenance contracts. Watch FDA cybersecurity guidance enforcement timelines as replacement cycle inflection indicator for legacy autoclave fleets.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Indicator Backward Integration | Captive Geobacillus stearothermophilus supply secures validation protocol control against third-party dependency. |
| AI-Enabled Cycle Optimization | Machine learning integration with autoclave load sensors reduces energy consumption and extends chamber lifespan. |
| Regional Laboratory Hub Consolidation | Centralized reprocessing in Germany's Baden-Württemberg achieves per-instrument cost economies below in-clinic alternatives. |
| Mobile Sterilization Unit Deployment | Portable steam systems with generator-compatible power requirements address Brazil's rural field dental camp demand. |
| Subscription Service Contract Unbundling | Standalone calibration contracts with third-party biomedical firms concentrate in United States multi-site practice networks. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR technical documentation, and ISO 17665 validation protocols, complemented by interviews with biomedical engineers, dental laboratory operations managers, GPO contracts managers, and sterilization equipment procurement leads at oral surgery centers. Secondary validation drew from hospital procurement databases, customs trade records for medical-grade stainless steel, and dental supply distributor transaction data. Bottom-up equipment unit economics triangulated against top-down market sizing across technology and end-user segments.
Installed base projections and replacement cycle velocity outputs anchored the analytical framework across the analysis window, with segmentation modeled by sterilization modality, instrument compatibility tier, and regional regulatory cluster. CAGRs derived from historical procurement pattern analysis and forward-looking compliance-driven replacement assumptions. Forecast inputs incorporated FDA cybersecurity guidance implementation timelines and EU MDR Annex I general safety requirement enforcement trajectories.
Underlying measurement precision varies by segment; steam autoclave installed base metrics carry tighter precision than emerging plasma sterilization adoption curves. Forecasts reflect documented assumptions about regulatory enforcement intensity and commodity stainless steel pricing stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Medical Bags Market
Medical Supplies
Dissolvable Stitches Market
Medical Supplies
Custom Procedure Packs (CPT) Market
Medical Supplies
Tattoo Needles Market
Medical Supplies
Ostomy Drainage Bags Market
Medical Supplies
Asia-Pacific Human Fibrin Glue Market
Medical Supplies
Fibrin Sealants Market
Medical Supplies
Arterial Blood Collection Market
Medical Supplies
Demulcent Eye Drops Market
Medical Supplies
Global Lancet and Pen Needles Market
Medical Supplies
Latex Medical Disposables Market
Medical Supplies
Bile Collection Bags Market
Medical Supplies
Latin America Hypodermic Syringes and Needles Market
Medical Supplies
Veterinary Syringes Market
Medical Supplies
Global Syringes and Needles Market
Medical Supplies
Surgical and Examination Gloves Market